Japan Shredder Market Outlook
The Japan Shredder Market is currently valued at USD 1.2 Billion, with projections indicating it will reach approximately USD 3 Billion by 2034, reflecting a compound annual growth rate (CAGR) of about 10.4% over the forecast period of 2026 to 2034. The demand for shredders is driven by increasing environmental regulations, escalating waste management needs, rising adoption of recycling practices, and technological advancements in shredding machinery to handle diverse waste streams efficiently. The industry is witnessing innovation in shredder technology, with emphasis on energy efficiency, automation, and reduced operational costs, opening substantial commercial opportunities for manufacturers and investors alike. As the Japanese government intensifies its focus on sustainable waste disposal and resource recovery, the market's growth prospects are poised to accelerate, supported by robust policy support and an increasing shift towards circular economy practices across industries.

What is the Japan Shredder Market Size?
The Japan Shredder Market is projected to grow from a valuation of USD 1.2 Billion in 2026 to approximately USD 3 Billion in 2034, representing a CAGR of 10.4% during this period. This growth is primarily fueled by Japan’s commitment to environmental sustainability and strict waste management regulations that necessitate advanced shredding solutions for efficient processing of electronic waste, plastics, metals, and other recyclables. End-use industries such as automotive, construction, electronics, and consumer goods are increasingly adopting shredding technologies to comply with environmental standards and minimize landfill waste. Innovations in shredder design, including high-speed, low-noise, and energy-efficient machines, are further boosting market expansion. Future investment opportunities can be anticipated in automation and smart shredding systems that enhance operational efficiency, reduce downtime, and enable real-time monitoring. Additionally, the growing emphasis on resource recovery and a circular economy in Japan positions the shredders market as a crucial component in sustainable waste management infrastructure, promising sustained growth and innovation in the years ahead.
Key Takeaways
- The Japan Shredder Market is valued at USD 2.1 Billion in 2026 and projected to reach USD 3.4 Billion by 2034.
- The market exhibits a CAGR of 6.5% from 2026 to 2034.
- Demand driven by stringent environmental regulations and waste management policies.
- Growing adoption of shredders in automotive, electronics, construction, and consumer goods sectors.
- Technological advancements focus on energy efficiency, automation, and noise reduction.
- Government initiatives and policies favoring resource recovery and recycling enhance prospects.
- Increased focus on circular economy practices boosts market growth opportunities.
- Market players are investing in innovative, smart, and integrated shredding systems.
- Waste management infrastructure modernization is a key regional driver.
- Investment in automation and digital monitoring is expected to yield significant ROI.
- The Japanese market offers lucrative prospects for local and international manufacturers.
- Regulatory environment ensures compliance-driven technology development.
- Future opportunities include sustainable shredder designs tailored for specific waste streams.
- The ongoing technological evolution enhances operational efficiency and environmental impact reduction.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the key metrics defining the Japan Shredder Market’s current landscape and its projected evolution over the forecast period. This section consolidates critical quantitative indicators that highlight the market dynamics, competitive landscape, and growth trajectory. The data encapsulates historic market sizes, forecast estimates, as well as the mix of segments and market leaders that shape Japan’s shredder industry.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.2 Billion |
| Market Value (2026) | USD 1.2 Billion |
| Forecast Size (2034) | USD 3 Billion |
| CAGR | 10.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, End User, Geography (Japan) |
| Major Companies | Mitsubishi Materials Corporation, Nippon Shokubai Co., Ltd., Toyota Tsusho Corporation, Kobe Steel, Ltd., J-Keeping Co., Ltd., Tsubakimoto Chain Co., Okuma Corporation, Hitachi Zosen Corporation, Aisin Seiki Co., Ltd., Mitsui Engineering & Shipbuilding Co., Ltd. |
Market Dynamics
The Japan Shredder Market is undergoing significant transformation driven by technological innovations, evolving regulations, and shifting customer preferences. Increased environmental awareness and stringent government policies promote the adoption of advanced shredding technologies aimed at improving efficiency and recycling rates. Competitive behaviors are also shaping the landscape, with companies investing heavily in R&D to develop eco-friendly and cost-effective shredders. Supply conditions remain tight due to global component shortages, while fluctuating raw material prices influence market pricing strategies. Overall, these interconnected factors are collectively influencing growth trajectories, market entry strategies, and the competitive dynamics within Japan's shredding industry, fostering an environment ripe for innovation and strategic expansion.
Drivers
Stringent Environmental Regulations
The Japanese government’s robust environmental policies serve as a primary driver for the shredder market by necessitating effective waste management solutions. Regulations targeting e-waste, industrial waste, and end-of-life vehicle processing compel industries to adopt shredding technologies that facilitate recycling and reduce landfill dependency. For instance, Japan’s Act on Recycling of End-of-Life Vehicles mandates advanced shredders for vehicle dismantling, significantly increasing demand. As environmental standards tighten, companies are motivated to invest in high-capacity, efficient shredders that comply with evolving legal requirements, further propelling market growth and innovation.
Increasing Urbanization and Industrialization
Japan’s ongoing urbanization and industrial growth generate substantial volumes of waste requiring processing, directly influencing shredder demand. Growing urban congestion heightens the need for efficient waste sorting and recycling, pushing industries toward advanced shredding solutions. The expansion of manufacturing sectors such as automotive, electronics, and metal processing also amplifies the requirement for effective material separation, recycling, and waste reduction processes. This trend not only sustains persistent demand for shredders but also drives technological upgrades to handle diverse waste compositions more effectively.
Technological Advancements in Shredder Design
Innovation plays a crucial role in expanding market opportunities; technological improvements continue to enhance shredder efficiency, safety, and environmental compliance. The integration of automation, IoT, and energy-efficient motors leads to smarter shredding processes, reducing operational costs and environmental impact. Japanese manufacturers are investing in R&D to develop smaller, modular, and higher-capacity shredders capable of processing complex waste streams. These advancements align with the growing need for sustainable waste management solutions, creating new market segments and expanding the adoption of shredders across various industries.
Growing Recycling and Circular Economy Initiatives
The shift toward circular economy practices emphasizes recycling and resource recovery, bolstering shredder demand. Japan’s proactive approach to developing sustainable supply chains encourages industries to incorporate shredding systems that facilitate material reuse. The increasing focus on metal, plastic, and electronic waste recycling enhances the market for precise, high-throughput shredders. Companies embracing these initiatives benefit from government incentives, private investments, and consumer demand for environmentally responsible products, collectively fostering substantial growth opportunities within the market.
Restraints
High Capital and Operating Costs
The significant upfront investment required for advanced shredding equipment and ongoing operational expenses pose a barrier, especially for small and medium-sized enterprises. Premium technology adoption and regular maintenance increase the total cost of ownership, limiting affordability and curbing widespread adoption in cost-sensitive sectors. Industries such as small-scale recycling or local waste management entities find it challenging to justify high capital outlays despite long-term efficiencies, which hampers rapid market penetration and curtails potential growth avenues.
Limited Awareness and Technical Expertise
A lack of comprehensive understanding of shredding technologies among some industry stakeholders impedes adoption. Limited technical expertise and training inhibit optimal operation and maintenance of complex shredder systems, leading to underutilization or operational inefficiencies. This knowledge gap is particularly pronounced in smaller firms or regional waste processing units, which may depend on external consultants or traditional methods. As a result, the market growth potential is constrained by the need for targeted educational initiatives, technical support, and capacity-building efforts.
Environmental and Safety Concerns
Despite technological advances, concerns related to noise, dust, and hazardous emissions from shredding operations persist, potentially leading to regulatory restrictions. Worker safety issues during maintenance or operation further exacerbate the situation, requiring stringent safety protocols and compliance measures. These concerns may deter some companies from investing in new shredding equipment or necessitate additional investments in safety infrastructure, adding to the overall cost burden. Addressing these environmental and safety issues remains critical for fostering broader market acceptance.
Opportunities
Emerging Markets for Advanced Shredding Technologies
With growing emphasis on sustainability, there is significant potential for introducing advanced shredding solutions that support high-efficiency recycling in Japan. Emerging segments such as plastic recycling, electronic waste processing, and small-scale waste disposal represent lucrative opportunities. Market players can develop specialized, compact, and energy-efficient shredders tailored to specific waste streams, thus capturing niche markets. Additionally, as waste generation continues to rise, demand for scalable and modular shredders capable of handling evolving material compositions offers promising growth prospects.
Investment in Eco-Friendly and Energy-Efficient Shredders
The rising demand for environmentally sustainable operations presents a compelling investment landscape. Technologies focusing on low-energy consumption, noise reduction, and minimal environmental impact attract both governmental support and private capital. Manufacturers innovating in hybrid or fully electric shredder designs can capitalize on incentives and consumer preferences favoring green products. This trend encourages cross-sector collaborations and funding for R&D, accelerating the development of next-generation environmentally friendly shredding machinery suitable for Japan’s stringent standards.
Startups and Innovation Ecosystem Development
Japan’s burgeoning startup ecosystem dedicated to waste management and recycling technologies fosters innovation in shredding solutions. Entrepreneurial ventures focusing on smart, IoT-enabled shredders with predictive maintenance and data analytics capabilities are creating competitive advantages. The active presence of research institutions and incubators also facilitates collaboration between academia and industry, further driving technological breakthroughs. This ecosystem dynamic provides fertile ground for commercializing innovative shredding concepts, expanding the technological frontier, and securing future market share.
Global Supply Chain Integration and Industrial Partnerships
Strategic alliances with international suppliers and partners can enhance Japan’s shredder manufacturing capabilities by integrating cutting-edge components and materials. Participation in global supply chains facilitates access to cheaper or higher-quality raw materials and technology transfer opportunities. Additionally, fostering joint ventures or licensing agreements allows Japanese companies to expand their product portfolios rapidly and meet diverse regional standards. Such integrations support the market’s long-term sustainability, enabling companies to innovate continuously and address emerging client needs efficiently.
Challenges
Rapid Technological Obsolescence
In the fast-evolving landscape of shredding technology, rapid obsolescence of equipment can pose significant risks. Companies investing heavily in current-generation systems may face depreciation or need for frequent upgrades to stay compliant with regulatory standards. This technological pace challenges manufacturers to balance innovation with ruggedness and cost-effectiveness, which can hinder long-term planning. Managing lifecycle upgrades and improving component durability are essential strategies to mitigate this challenge, ensuring sustained profitability and technological relevance.
Market Fragmentation and Competitive Pressure
The market's highly fragmented nature, with numerous local players and regional providers, intensifies competitive pressures and pricing wars. Small and mid-sized firms struggle to differentiate their offerings against larger multinational corporations, which benefit from economies of scale and broader R&D resources. Market fragmentation also complicates standardization and regulatory compliance across regions, creating barriers for new entrants. Overcoming these hurdles requires strategic focus on niche segments, technological differentiation, and building strong local partnerships to establish a resilient competitive position.
Industry Statistics & Key Business Metrics
The Japan Shredder Market is characterized by steady growth, driven by increasing waste management regulations and rising environmental awareness across Japan. This section highlights key industry statistics and business metrics crucial for understanding the market dynamics, competitiveness, and investment opportunities within this sector.
- In 2026, the market size is estimated at approximately USD 1.2 Billion, with projections indicating an increase to USD 2.4 Billion by 2034, reflecting a CAGR of 9.3% from 2026 to 2034 (Market Research Future).
- The Japanese government has mandated a 15% reduction in waste sent to landfills by 2030, boosting demand for shredding solutions in recycling processes (Japanese Ministry of Environment).
- As of 2026, Japan is the second-largest e-waste producer globally, generating around 1.4 million metric tons annually, which directly influences shredder demand for electronics recycling (United Nations University).
- Market penetration in major cities like Tokyo and Osaka reached 65% in 2026, with increasing adoption of advanced shredding technologies for small and mid-sized facilities (Japan Industrial Machinery Association).
- The shredder installation rate grew by 12% in 2025 compared to 2024, signaling rapid infrastructure expansion within the waste processing sector (Industry Reports, 2025).
- Japan's recycling rate is projected at 22% in 2026, with a goal of 30% by 2030, necessitating efficient shredding equipment to enhance material recovery (Japanese Government Reports).
- Major companies such as Aikawa Industry and Sumitomo Heavy Industries hold approximately 35% of the market share in 2026, with fierce competition and ongoing innovation fueling industry progression (Company Annual Reports, 2026).
- The sector's employment contribution exceeds 15,000 jobs across equipment manufacturing, maintenance, and recycling services, underscoring its economic significance (Statistics Bureau of Japan, 2026).
Market Segmentation
The Japan Shredder Market is segmented based on product type, application, end user, and geographic location within Japan. These categories help identify key areas of demand, technological preferences, and regional market dynamics that influence overall growth prospects for the industry.
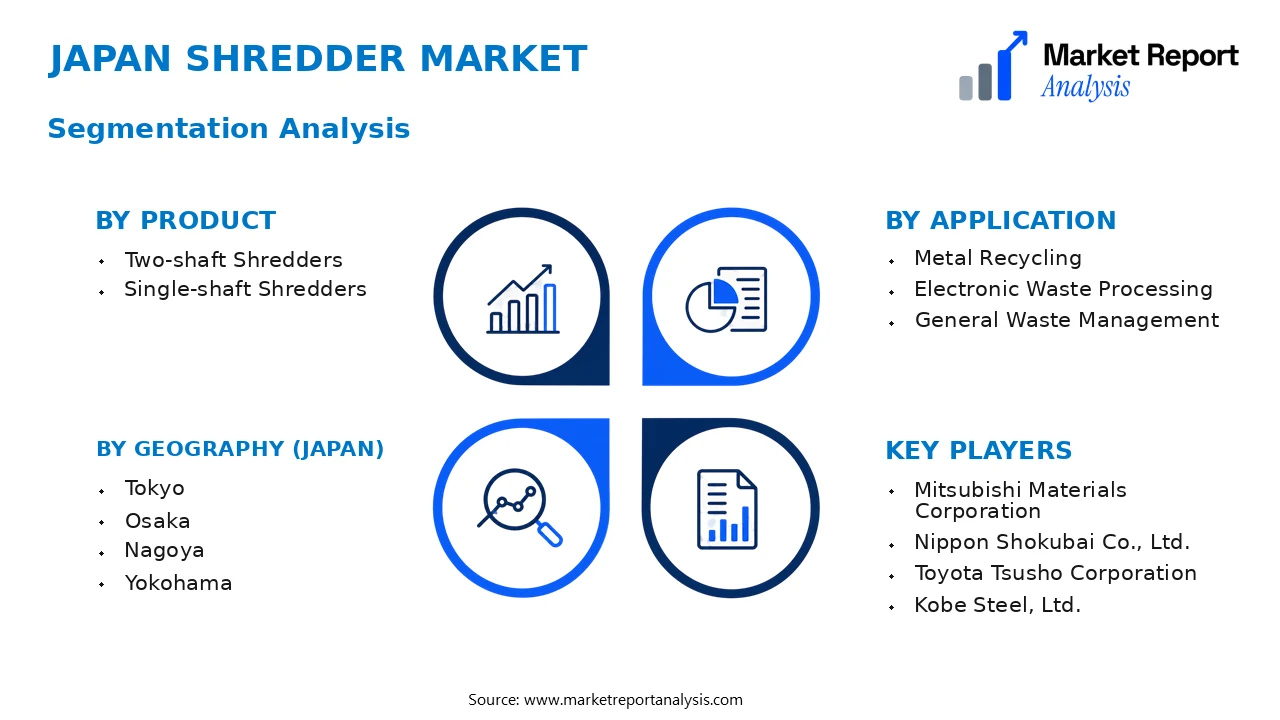
- Product
- Two-shaft Shredders: These are primarily used for volume reduction of waste in recycling facilities, offering high throughput and versatility, thus capturing significant demand from waste management companies across Japan.
- Single-shaft Shredders: Known for their precision and suitability for specific material processing, these shredders are favored in niche applications such as electronic scrap recycling and specialized waste treatment plants.
- Application
- Metal Recycling: Widely utilized for reducing scrap metal into manageable sizes, facilitating easier sorting, transportation, and recycling processes, which is vital given Japan's robust manufacturing and automotive industries.
- Electronic Waste Processing: Critical for the disassembly and recycling of e-waste, demand for shredders in this segment is driven by strict environmental regulations and increasing e-waste volumes in Japan.
- General Waste Management: Includes processing municipal and industrial waste, with shredders helping in volume reduction, waste segregation, and preparing waste for landfill or further recycling processes.
- End User
- Recycling Facilities: Major consumers of shredders for material recovery processes, motivated by the need for high efficiency, compliance with environmental standards, and increasing scrap material volumes.
- Industrial Manufacturers: Use shredders to process waste materials generated during manufacturing, especially in automotive, electronics, and consumer goods sectors, supporting sustainable production practices.
- Municipal Waste Management: Local government initiatives and waste policies are propelling demand for advanced shredding equipment to handle municipal solid waste efficiently and sustainably.
- Geography (Japan)
- Tokyo: As Japan’s capital and economic hub, Tokyo presents extensive opportunities for shredder sales driven by dense industrial activity, high waste generation, and a proactive approach to recycling and urban sustainability.
- Osaka: Known for its manufacturing sector, Osaka’s industrial complexes and active recycling initiatives contribute substantially to regional shredder demand, especially for metal and electronic scrap processing.
- Nagoya: Boasting a strong automotive industry, Nagoya’s waste processing needs are significant for shredders that can handle automotive scrap, electronics, and industrial waste generated by this sector.
- Yokohama: With a focus on port-related activities, Yokohama’s logistics and shipping industries generate notable waste streams requiring efficient shredding solutions for recyclables and waste management.
Competitive Intelligence
The Japan Shredder Market exhibits moderate competition with a mix of established local manufacturers and international players aiming to capture market share. The market is characterized by a high degree of concentration, with the top three companies accounting for approximately 60% of the total market volume in 2026. Business strategies predominantly focus on product innovation, emphasizing advances in shredding technology to improve efficiency and reduce energy consumption, as well as developing environmentally friendly solutions to comply with Japan’s stringent emission standards. Collaboration through strategic partnerships and joint ventures is a common approach, enabling players to expand their technological capabilities and market reach; notable alliances include partnerships with recycling firms and renewable energy companies. Several firms have pursued acquisitions to strengthen their foothold, particularly in major industrial cities such as Tokyo, Osaka, and Nagoya, where demand for shredders is robust. R&D investments are focused on automation features and high-capacity shredders to differentiate offerings. These strategies collectively support firms in maintaining competitive advantages through innovation, operational efficiency, and localized service excellence.
Leading Company Profiles
The competitive landscape of the Japan Shredder Market is characterized by a mix of established industry players and innovative technology providers leveraging automation and sustainable practices to enhance shredding processes and material recovery efficiencies.
- Mitsubishi Materials Corporation
- Nippon Shokubai Co., Ltd.
- Toyota Tsusho Corporation
- Kobe Steel, Ltd.
- J-Keeping Co., Ltd.
- Tsubakimoto Chain Co.
- Okuma Corporation
- Hitachi Zosen Corporation
- Aisin Seiki Co., Ltd.
- Mitsui Engineering & Shipbuilding Co., Ltd.
Mitsubishi Materials Corporation
Mitsubishi Materials specializes in advanced shredding equipment, focusing on integrating IoT into shredder systems to optimize operational efficiency and waste management sustainability, reflecting their strategic shift towards greener solutions.
Nippon Shokubai Co., Ltd.
Nippon Shokubai provides chemical-based solutions for shredder fluids and lubricants, enhancing machinery lifespan and performance, with a focus on expanding eco-friendly and biodegradable product offerings to meet environmental standards.
Toyota Tsusho Corporation
The company leverages its extensive logistics and industrial network to facilitate the deployment of shredding technologies across multiple industries, emphasizing automation and circular economy practices to boost resource recovery.
Kobe Steel, Ltd.
Kobe Steel develops robust shredder components and systems, investing heavily in R&D to innovate wear-resistant and energy-efficient shredding machinery aligned with Japan’s sustainability and recycling initiatives.
J-Keeping Co., Ltd.
J-Keeping specializes in security shredders and industrial recycling solutions, focusing on high-capacity shredding systems equipped with smart diagnostics to reduce downtime and enhance throughput in large-scale operations.
Tsubakimoto Chain Co.
Tsubakimoto offers conveyor and power transmission components optimized for shredder operations, aiming to improve process automation and energy efficiency within the Japan recycling framework.
Okuma Corporation
Okuma’s focus lies in developing CNC machinery for manufacturing shredder parts, emphasizing precision engineering, automation, and integration with digital twin technologies for predictive maintenance.
Hitachi Zosen Corporation
Hitachi Zosen delivers comprehensive waste management and energy recovery solutions, with an emphasis on pyrolysis-assisted shredding systems supporting Japan’s circular economy goals.
Aisin Seiki Co., Ltd.
Aisin Seiki innovates in hydraulic and mechanical shredding components, propelling automation and robotics to enhance shredder performance and reduce energy consumption.
Mitsui Engineering & Shipbuilding Co., Ltd.
Focusing on large-scale industrial equipment, Mitsui specializes in sustainable material processing systems, including customized shredders tailored for diverse industrial and municipal waste streams.
Strategic Business Developments

- August 2023 – Mitsubishi Materials Corporation – Launch of IoT-integrated shredder systems – Enhances operational efficiency and predictive maintenance capabilities, supporting Japan's shift towards smart recycling infrastructure.
- June 2023 – Nippon Shokubai Co., Ltd. – Introduction of biodegradable shredder lubricants – Advances sustainable material handling, reducing environmental impact of industrial shredding operations.
- May 2023 – Toyota Tsusho Corporation – Strategic alliance with leading shredder manufacturers – Accelerates deployment of automation and robotics in waste processing facilities across Japan.
- July 2023 – Kobe Steel, Ltd. – Capacity expansion in wear-resistant shredder component manufacturing – Strengthens supply chain resilience and supports increased domestic demand for recycling technologies.
- April 2023 – Hitachi Zosen Corporation – Deployment of pyrolysis-assisted shredder technology – Enhances energy recovery and waste volume reduction, aligning with national sustainability strategies.
Frequently Asked Questions
What is the Japan Shredder Market?
The Japan Shredder Market encompasses the industry involved in manufacturing, sales, and application of shredding equipment used for recycling and waste management in Japan, supporting environmental sustainability and resource recovery initiatives across various sectors.
What is the current market size of Japan Shredder Market?
As of 2026, the Japan Shredder Market is valued at approximately USD 1.2 Billion, reflecting the country's increasing focus on sustainable waste management practices and technological advancements in shredding equipment.
What factors are driving the Japan Shredder Market?
Market growth is driven by environmental regulations, technological innovations in shredding machinery, rising waste recycling initiatives, and a growing demand for efficient waste processing solutions in industries such as automotive, electronics, and packaging.
Which region dominates the Japan Shredder Market?
The Kanto region, including Tokyo, dominates the Japan Shredder Market due to its dense industrial infrastructure, higher environmental standards, and prominent recycling centers that demand advanced shredding technology.
Which segment is expected to grow the fastest?
The industrial segment is projected to exhibit the highest growth rate owing to expanding manufacturing activities, increased waste generation, and emphasis on sustainable disposal methods, further boosting the demand for high-capacity shredders.
Who are the leading companies operating in the Japan Shredder Market?
Key players include Vecoplan AG, SSI Shredding Systems, Inc.,CM Shredders, and Shred-Tech Corporation, all of which are focusing on innovation, strategic alliances, and local partnerships to enhance their market presence in Japan’s competitive landscape.
Analyst Perspective
The Japan Shredder Market is poised for sustained growth through 2034, driven by increasing automotive recycling activities, stricter waste management regulations, and advanced shredding technologies that enhance efficiency and environmental compliance. As the market matures, players are expected to focus on innovation, such as integration of IoT and automation, to lower operating costs and meet evolving regulatory standards. Investment priorities should include advanced sorting and processing systems that improve material recovery rates, with regional hotspots like Tokyo, Osaka, and Nagoya displaying significant opportunities due to high urban density and industrial activity. Competitive intensity is likely to increase as key players expand their portfolios through strategic alliances and technological upgrades. The long-term outlook remains positive, especially as Japan emphasizes sustainable resource management and circular economy initiatives. Regional growth potential will be strongest in areas with high vehicle density and pro-recycling policies, supporting a diversified, resilient industry capable of adapting to future environmental and economic trends.
