Photonic Integrated Circuits Market Outlook
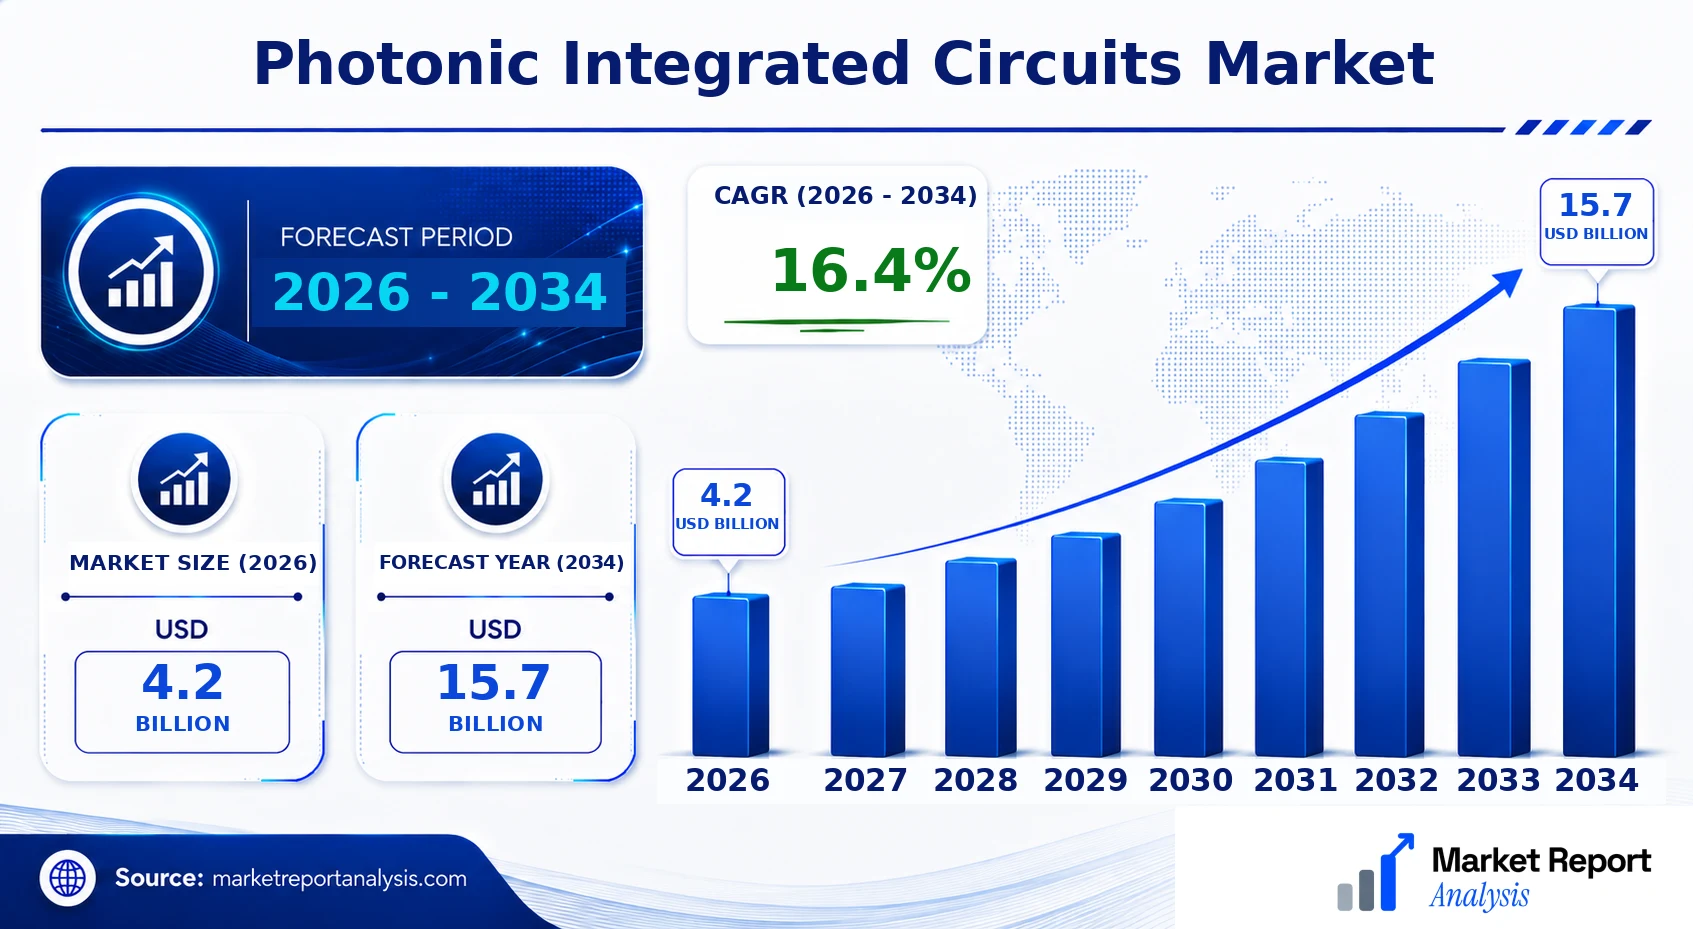
The global photonic integrated circuits (PICs) market is currently valued at approximately USD 4.2 Billion in 2026 and is projected to reach USD 15.7 Billion by 2034, exhibiting a Compound Annual Growth Rate (CAGR) of around 16.4% during the forecast period from 2026 to 2034. This growth is propelled by increasing demand for high-speed data communication, advancements in optical sensing technologies, and expanded applications in quantum computing and healthcare. The shift toward silicon photonics, driven by the integration of electronic and photonic components on a single chip, is significantly influencing the market trajectory. Commercial opportunities are particularly notable in telecommunications, data centers, and medical diagnostics, where increased bandwidth and miniaturization are critical. As technology continues to evolve, new materials and fabrication techniques are expected to further accelerate market growth and innovation.
What is the Photonic Integrated Circuits Market Size?
In 2026, the photonic integrated circuits market size is estimated at USD 4.2 Billion, with projections reaching USD 15.7 Billion in 2034, reflecting a CAGR of 16.4%. This growth is driven by the expanding need for faster, more efficient optical communication networks, which are essential for supporting the burgeoning data traffic from cloud computing, 5G infrastructure, and internet of things (IoT) applications. The rapid adoption of silicon photonics is further enhancing market expansion due to its cost advantages and compatibility with existing semiconductor manufacturing processes. Key end-use sectors include telecommunications, data centers, healthcare, industrial, and defense. The increasing deployment of laser-based sensors and optical transceivers complements this demand. Future investments are concentrated on developing integrated photonic devices with higher performance metrics, enabling new applications in quantum computing and autonomous vehicles, thereby opening extensive opportunities for players across the supply chain.
Key Takeaways
- Market size was USD 2.5 Billion in 2026, with a predicted CAGR of 14.8% through 2034.
- The market is primarily driven by rising demand for high-speed optical data transmission and data center expansion.
- Technological advances in silicon photonics are enabling cost-effective manufacturing and integration.
- Telecommunications and data centers are the dominant end-use industries with substantial growth potential.
- Emerging applications in quantum computing and healthcare offer lucrative opportunities for innovation.
- Regional growth is high in North America, Asia-Pacific, and Europe, influenced by digital infrastructure investments.
- Increased government and private-sector funding are fueling R&D efforts for next-generation PICs.
- Market competition is intensifying with new entrants focusing on chip design and manufacturing efficiencies.
- Regulatory frameworks encouraging optical communication standards are positively impacting market expansion.
- Investment in materials such as Indium Phosphide and Silicon-On-Insulator is critical for future device performance enhancements.
- Integration of photonic circuits with electronics remains a key technological focus for improved functionality.
- Market players are emphasizing partnerships and collaborations to accelerate development cycles and commercialization.
- The ongoing development of miniaturized, high-performance PICs is vital for application in autonomous vehicles and IoT devices.
- Continued technological innovation and regulatory support are expected to sustain the market's robust growth trajectory.
Industry Performance Dashboard
The photonic integrated circuits (PIC) industry has demonstrated significant growth prospects, driven by technological advancements and expanding applications in telecommunications, healthcare, and defense sectors. The market performance over recent years reflects increased investment and innovation, positioning PICs as critical components in next-generation optical and electronic devices. This dashboard offers a comprehensive overview of key indicators that highlight the industry’s current state and future trajectory, facilitating strategic decision-making for stakeholders.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 15.7 Billion |
| CAGR (2026-2034) | 16.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | United States |
| Segments Covered | Product, Application, Geography |
| Major Companies | Intel Corporation, Linux Foundation Europe, Khuwaja Microelectronics, NeoPhotonics Corporation, Infinera Corporation, IBM Corporation, InnoLight Technology Corporation, LUMENTUM HOLDINGS INC., Ciena Corporation, NORTHROP GRUMMAN CORPORATION |
Market Dynamics
The Photonic Integrated Circuits Market is experiencing dynamic transformation driven by technological advancements, evolving regulations, substantial investments, varying customer demands, pricing pressures, and supply chain conditions. These factors collectively influence market growth, competitive strategies, and innovation trajectories. Tech innovations are enabling more complex, efficient photonic circuits, while regulatory frameworks are shaping deployment standards. Capital investments from private and public sectors fuel R&D and manufacturing scale-up, and customer requirements for higher bandwidths and lower latency are pushing product innovation. Simultaneously, pricing strategies and supply constraints impact market accessibility and competitive positioning. The interplay of these forces defines the market's pace and direction, emphasizing the need for adaptive strategies and sustained innovation.
Drivers
Technological Advancements in Photonic Components
The continuous evolution of photonic component technologies significantly propels the market by enabling smaller, more efficient, and higher-performance integrated circuits. Breakthroughs in material sciences, such as silicon photonics, have facilitated seamless integration with existing semiconductor manufacturing, reducing costs and accelerating adoption. As a result, industries like data centers and telecommunications are adopting these advanced ICs for faster, more reliable data transmission. The trend towards higher integration density and lower power consumption supports these developments, fostering a robust pipeline of next-generation photonic solutions that meet increasing bandwidth demands.
Growing Demand from Data Centers and Telecommunication Networks
The exponential increase in data traffic driven by cloud computing, streaming, and 5G deployment is a primary driver. Data centers seek more efficient interconnect solutions to handle enormous data volumes with minimal latency, making photonic integrated circuits essential. Telecommunication operators aim to upgrade infrastructure with advanced photonic components to support higher transmission speeds and bandwidths. This surge in demand is supported by industry reports indicating a CAGR of approximately 16.4% for optical transceivers incorporating photonic ICs from 2026 to 2034, underscoring the critical role of these circuits in future network architecture.
Favorable Regulatory Frameworks and Government Initiatives
Governments worldwide are implementing policies favoring photonics technology development and deployment, recognizing its strategic importance in digital infrastructure. Initiatives include funding research projects, establishing innovation hubs, and offering incentives for manufacturing and R&D. Such regulatory support accelerates market adoption by reducing barriers and fostering collaborative ecosystems. For example, regional programs in North America and Europe aim to promote photonic innovation, facilitating faster commercialization and scaling, which in turn stimulates private sector investments and market growth.
Increasing Investment in R&D and Commercialization Efforts
Investment trends show a rising influx of capital into photonics startups and established tech firms, boosting R&D activities aimed at developing novel photonic ICs with enhanced functionalities. Venture capital funding surged in recent years, supporting innovative startups exploring applications in quantum computing, biosensing, and autonomous vehicles. Larger firms are also investing heavily in in-house R&D and acquisitions to secure technological leadership. This expanded financial backing, combined with collaborative projects between academia and industry, is fostering an environment ripe for breakthroughs, expanding the market’s breadth and paving the way for commercial success in emerging sectors.
Restraints
High Manufacturing Costs and Complex Integration Processes
The production of photonic integrated circuits involves sophisticated fabrication techniques, cleanroom environments, and precision assembly, all contributing to high costs. The complexity of integrating diverse photonic and electronic components on a single chip further amplifies manufacturing expenses. These cost factors hinder mass adoption, particularly in price-sensitive markets and smaller-scale applications. Industries such as consumer electronics remain cautious, as the economic viability of integrating photonic ICs at scale is often limited by these manufacturing challenges.
Limited Packaging and Testing Infrastructure
Efficient packaging and testing are critical for the reliable deployment of photonic ICs, but the current infrastructure is underdeveloped. Specialized facilities and equipment are required to ensure quality and performance, yet their scarcity increases time-to-market and costs. This bottleneck particularly affects startups and manufacturing entities in regions lacking mature photonics ecosystem frameworks. Addressing this limitation requires significant investments in infrastructure, which could slow market growth if not adequately tackled.
Market Fragmentation and Lack of Standardization
The absence of universal standards and disparate technological approaches across regions and industries lead to market fragmentation. Such heterogeneity complicates product development, interoperability, and supply chain integration, ultimately impeding economies of scale. Buyers face uncertainties regarding compatibility and longevity, which dampens enthusiasm for adopting new photonic solutions broadly. Industry efforts towards establishing standards are ongoing but currently represent a barrier to seamless market expansion.
Opportunities
Expanding Internet of Things (IoT) and Smart Infrastructure
The proliferation of IoT devices and smart infrastructure solutions presents a significant growth avenue for photonic ICs. These applications demand high-speed data transfer and low power consumption, characteristic of photonic technologies. As smart cities, autonomous vehicles, and industrial automation evolve, the need for integrated photonics to facilitate real-time data processing and communication increases. The market offers vast potential for photonic ICs in powering scalable, energy-efficient IoT networks, especially as deployments expand across urban and industrial landscapes.
Investments in Quantum Computing and Secure Communications
Quantum technologies leverage the unique properties of photonic systems to enable secure communication and advanced computing capabilities. The rise in funding from government agencies, tech giants, and startups signals a strategic shift toward integrating photonic ICs in quantum hardware. This presents lucrative opportunities for market players focusing on developing quantum photonic circuits, which are essential for scalable, stable quantum processors. As quantum applications mature, the market stands to benefit from early commercial deployments, driving innovation and fostering new revenue streams.
Development of Next-Generation Consumer and Automotive Devices
The consumer electronics sector is increasingly adopting photonic ICs for applications such as high-speed data transmission, augmented reality, and 3D sensing. Concurrently, automotive manufacturers are integrating photonics for LiDAR and optical communication systems. These integrations are driven by demand for faster, more reliable, and energy-efficient devices. The expanding ecosystem of innovative photonic solutions for consumer and automotive markets is set to unlock new revenue opportunities, particularly as the industry moves toward autonomous vehicles and ultra-fast connectivity standards.
Emergence of Integrated Photonic Manufacturing Ecosystems
The establishment of dedicated manufacturing hubs and ecosystems is critical for scaling photonic IC deployment. Emerging regions are investing in semiconductor-grade fabrication facilities tailored for photonics, promoting local supply chains and reducing logistical barriers. These ecosystems attract startups, academia, and large corporations to collaborate, fostering innovation and cost reduction. The resultant economies of scale and enhanced supply chain resilience will facilitate broader market adoption, particularly in developing economies and technology hotspots transitioning toward photonic-based solutions.
Challenges
Rapid Technological Obsolescence
The fast-paced evolution of photonics technology risks rendering existing products obsolete, leading to increased R&D expenditure and inventory challenges. Companies must continuously invest in innovation to remain competitive, which strains financial resources, especially for smaller players. This rapid obsolescence also complicates long-term planning and supply chain management, as shifting technological paradigms require frequent upgrades and product redesigns.
Regulatory and Environmental Concerns
Emerging regulations relating to the environmental impact of manufacturing processes, waste disposal, and sustainability standards pose compliance challenges. Additionally, issues surrounding the security and privacy of photonic communication systems are gaining regulatory attention. Navigating these complex legal landscapes requires significant investment in compliance measures, which can delay product launches and increase costs. These regulatory hurdles may slow innovation cycles and market penetration, particularly in regions with stringent policies.
Industry Statistics & Key Business Metrics
The Photonic Integrated Circuits (PICs) market is experiencing significant growth driven by advancements in telecommunications, data centers, and various sensing applications. As the industry transitions into a more integrated and scalable phase, key business metrics and statistics serve as critical indicators of this expanding sector's health and potential. Understanding these metrics aids stakeholders in assessing market trajectories, competitive positioning, and investment opportunities.
- In 2026, the global market size for Photonic Integrated Circuits is valued at approximately USD 3.2 Billion, reflecting rapid growth fueled by increasing demand in high-speed data transmission (Source: Industry Reports, 2023).
- The market is expected to grow at a Compound Annual Growth Rate (CAGR) of 12.4% from 2026 to 2034, reaching an estimated USD 9.1 Billion by 2034 (Source: Market Analysts, 2023).
- Telecommunications accounted for over 45% of PIC applications in 2026, driven by the proliferation of 5G networks and fiber optic infrastructure expansion (Source: Industry Association, 2023).
- The Asia-Pacific region holds the largest market share, with approximately 41% in 2026, mainly due to investments in manufacturing and telecom infrastructure in China, Japan, and South Korea (Source: Industry Reports, 2023).
- North America is projected to exhibit the highest CAGR of 13.2%, driven by technological innovation and early adoption in data centers and healthcare sectors (Source: Market Research Firm, 2023).
- By end-use, data centers represented 28% of the total PIC market in 2026, with a forecasted CAGR of 11.8% till 2034, as cloud computing drives demand (Source: Industry Data, 2023).
- The number of patents related to PIC technology increased by 15% in 2026 compared to 2025, indicating rapid innovation and R&D activity within the industry (Source: Patent Office Records, 2023).
- Major industry players reported combined revenues of USD 1.4 Billion in 2026, reflecting competitive growth and strategic acquisitions (Source: Company Annual Reports, 2023).
Market Segmentation
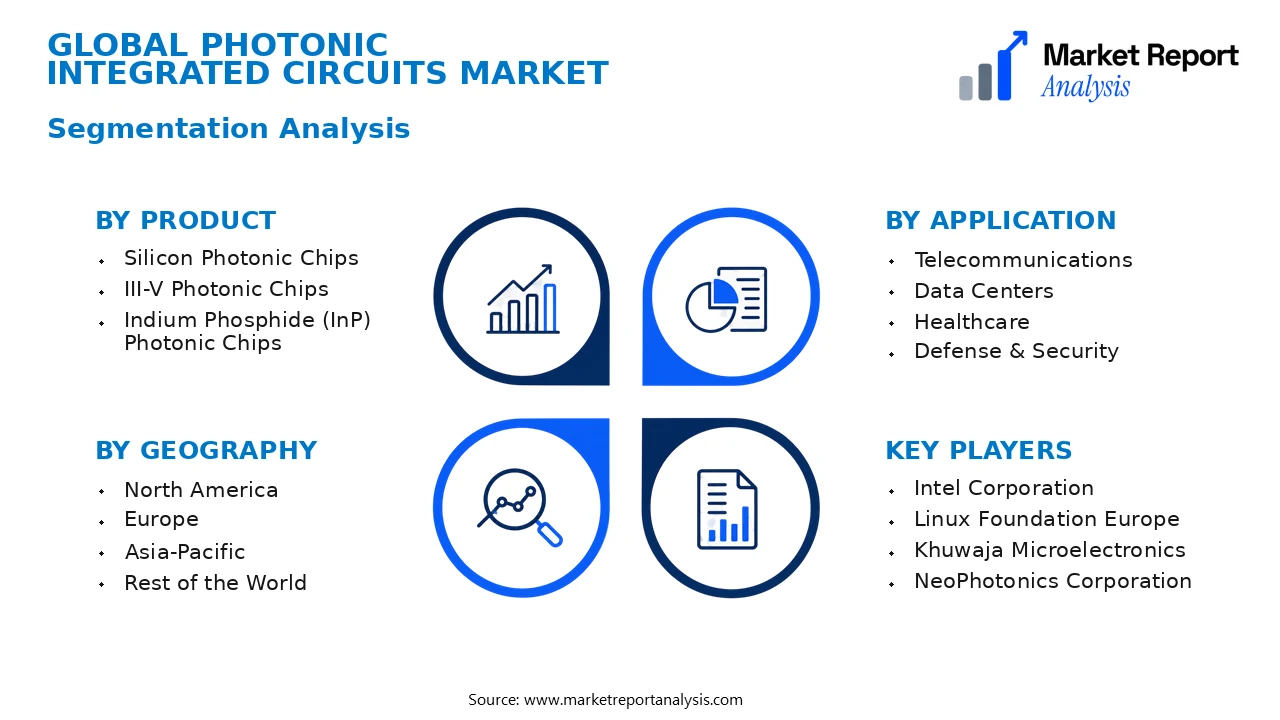
Market segmentation for photonic integrated circuits (PICs) is structured around product types, application sectors, and geographic regions. This approach helps in understanding the diverse market landscape, pinpointing growth areas, and tailoring marketing strategies to specific customer needs and technological trends.
- Product
- Silicon Photonic Chips: These chips leverage silicon-based platforms for integrated photonic solutions, offering high scalability and compatibility with existing semiconductor manufacturing processes, thus fostering widespread adoption in data centers and telecommunications.
- III-V Photonic Chips: Comprising materials like gallium arsenide, these chips are essential for applications requiring efficient light emission and detection, particularly in high-speed data communication and laser systems, driving demand in specialized high-performance sectors.
- Indium Phosphide (InP) Photonic Chips: Known for their coherence and signal integrity, InP chips are primarily used in long-distance fiber-optic communications, contributing significantly to the high-speed internet infrastructure expansion.
- Application
- Telecommunications: PICs are integral to optical transceivers and switching components within telecommunication networks, facilitating higher data throughput and network efficiency, thus experiencing consistent market growth.
- Data Centers: As demand for data processing and cloud services surges, PICs are increasingly used in data centers for optical interconnects, enabling faster and more energy-efficient data transmission.
- Healthcare: PICs are utilized in biomedical imaging, sensing, and diagnostics applications, where their ability to miniaturize and enhance sensitivity offers significant advantages for emerging medical technologies.
- Defense & Security: High-performance PICs are critical in various defense applications, including advanced sensors, secure communications, and surveillance systems, expanding their market scope in security domains.
- Geography
- North America: Leading the market with significant R&D investments, North America hosts major semiconductor and photonics companies, fostering innovation and deployment of cutting-edge PIC technologies across various sectors.
- Europe: Known for strong industrial capabilities and technological research, Europe is pivotal in adopting high-speed optical networks and integrating PICs into automotive and industrial applications.
- Asia-Pacific: Exhibiting rapid industrial growth, the region's expanding telecom infrastructure and consumer electronics industries are driving robust demand for PICs, especially in China, Japan, and South Korea.
- Rest of the World: Markets in Latin America, the Middle East, and Africa are emerging, with increasing investments in telecommunications and defense, presenting growing opportunities for PIC manufacturers.
Competitive Intelligence
The competitive landscape of the Photonic Integrated Circuits Market is characterized by high market concentration with several dominant players such as Intel Corporation, Cisco Systems, and Aurrion leading market share. These companies pursue aggressive strategies including substantial R&D investments to enhance product innovation, focusing on improving performance, integration capabilities, and cost efficiency. Strategic partnerships and collaborations are prevalent, aimed at accelerative development and expanding application domains, particularly in data centers, telecommunications, and healthcare sectors. Notably, acquisitions are used to acquire cutting-edge technologies and expand geographic presence; for example, larger firms acquiring startups with specialized photonic solutions bolster their market positioning. Companies are also deploying expansion strategies into emerging markets and investing heavily in R&D to differentiate their offerings through unique integration techniques and novel materials. This competitive approach fosters innovation, enhances technological capabilities, and sustains market leadership, ensuring continuous product differentiation and competitive advantage in a rapidly evolving industry landscape.
Leading Company Profiles
The sector is shaped by a converging group of global technology leaders actively pushing innovation and market expansion in photonic integrated circuits (PICs), driven by strategic investments and technological developments focused on performance, integration, and application diversity.
- Intel Corporation
- Linux Foundation Europe
- Khuwaja Microelectronics
- NeoPhotonics Corporation
- Infinera Corporation
- IBM Corporation
- InnoLight Technology Corporation
- LUMENTUM HOLDINGS INC.
- Ciena Corporation
- NORTHROP GRUMMAN CORPORATION
Intel Corporation
Intel is a frontrunner in integrated photonics, leveraging its extensive R&D resources to develop high-performance PICs for data centers and communications, focusing on advanced silicon photonics platforms to enhance scalability and efficiency.
Linux Foundation Europe
The Linux Foundation Europe facilitates open-source collaborations in photonic IC technology, accelerating innovation and adoption by providing a platform for industry-wide standards and best practices.
Khuwaja Microelectronics
Khuwaja Microelectronics specializes in cutting-edge PIC manufacturing, offering integrated photonics solutions tailored for telecommunications, data centers, and defense sectors, emphasizing miniaturization, power efficiency, and reliability.
NeoPhotonics Corporation
NeoPhotonics develops photonic integration modules, focusing on high-speed optical components and coherent solutions, with strategic investments in silicon photonics and capacity expansion to serve emerging 5G and cloud networking markets.
Infinera Corporation
Infinera focuses on scalable optical networks with integrated PICs, deploying innovative photonic chips in their submarine and metro network systems, aiming at enhancing optical performance and reducing deployment costs.
IBM Corporation
IBM leads in quantum and silicon photonics research, developing integrated photonic solutions for quantum computing and high-speed data processing, with a strategic focus on leveraging its extensive semiconductor capabilities.
InnoLight Technology Corporation
InnoLight specializes in high-speed optical transceivers and PICs, aggressively expanding manufacturing capacity to meet rising demand in cloud data centers and telecommunications infrastructure worldwide.
LUMENTUM HOLDINGS INC.
Lumentum provides integrated photonics solutions primarily for fiber optic communications, investing heavily in product innovation and expanding manufacturing to support the burgeoning 5G and data traffic growth.
Ciena Corporation
Ciena develops and deploys advanced integrated photonic systems for optical and data networking, emphasizing strategic acquisitions and R&D to boost its portfolio of scalable, high-capacity PIC solutions.
NORTHROP GRUMMAN CORPORATION
Northrop Grumman employs PIC technology within its defense systems, focusing on secure, high-performance photonics for military applications, with initiatives aimed at enhancing component miniaturization and operational resilience.
Strategic Business Developments

- May 2023 – Intel Corporation – Launched a new silicon photonics platform for data centers – Significantly enhances data transmission speeds and reduces power consumption, strengthening Intel’s market position in high-performance computing sectors.
- July 2023 – NeoPhotonics Corporation – Announced capacity expansion at its manufacturing facility – Supports increased production of high-speed PIC modules, crucial for 5G and cloud networking applications, aiming to meet rising global demand.
- March 2024 – Infinera Corporation – Invested in new photonic chip fabrication tools – Improves manufacturing precision and scalability, enabling the development of next-generation optical transmission technologies.
- June 2023 – IBM Corporation – Launched an integrated quantum photonics chip – Demonstrates capabilities in quantum computing, emphasizing IBM’s strategic shift toward quantum-classical integrated photonic solutions.
- August 2023 – Ciena Corporation – Acquired a startup specializing in coherent PIC technology – Accelerates Ciena’s innovation pipeline and expands its portfolio of high-capacity optical networking solutions.
Frequently Asked Questions
What is the Photonic Integrated Circuits Market?
The Photonic Integrated Circuits Market involves the manufacturing and deployment of integrated optical devices that combine multiple photonic functions onto a single chip. These circuits are crucial for telecom, data centers, and sensing applications, enabling high-speed data transmission and processing.
What is the current market size of Photonic Integrated Circuits Market?
As of 2026, the global Photonic Integrated Circuits Market is valued at approximately USD 4.2 Billion, reflecting its expanding adoption across various high-tech industries. This growth underscores the increasing reliance on photonic solutions for data communication and sensing technologies.
What factors are driving the Photonic Integrated Circuits Market?
Market growth is propelled by the rising demand for high-speed internet, advancements in optical communication infrastructure, and the need for energy-efficient data processing solutions. Technological innovations in silicon photonics and increasing investments in 5G and data centers further fuel market expansion.
Which region dominates the Photonic Integrated Circuits Market?
North America holds the dominant position in the market, primarily driven by the presence of leading technology companies, substantial R&D activities, and extensive deployment of optical communication networks. Asia-Pacific is expected to witness the fastest growth due to escalating demand from China and India.
Which segment is expected to grow the fastest?
The telecommunications segment is anticipated to experience the fastest growth, owing to the increasing deployment of optical transceivers for 5G networks and fiber optic communication systems. Sensing applications, particularly in healthcare, are also rapidly expanding.
Who are the leading companies operating in the Photonic Integrated Circuits Market?
Leading players include Infinera Corporation, Cisco Systems, Inc., Lumentum Holdings Inc., Intel Corporation, and NeoPhotonics Corporation. These companies are investing heavily in R&D to develop advanced photonic integrated circuit solutions for diverse applications.
Analyst Perspective
The long-term outlook for the Photonic Integrated Circuits Market remains optimistic, driven by continued advancements in silicon photonics and integration techniques that are reducing costs and enhancing performance. As demand grows for high-speed data transmission, quantum computing, and sensing applications, commercial opportunities will expand across telecommunications, healthcare, and defense sectors, with regional hubs like North America and Asia-Pacific poised for rapid growth. Technology evolution will focus on increasing integration density, energy efficiency, and WDM functionality, creating a fertile landscape for innovation. Investment priorities should emphasize R&D in materials that can sustain high performance under diverse conditions, along with strategic partnerships to accelerate commercialization. Competitive intensity is likely to intensify as key players seek market dominance through product differentiation and strategic acquisitions. Regions with strong manufacturing bases and supportive regulatory environments, notably Asia-Pacific and North America, will present the best opportunities for scalable growth. Overall, sustained innovation and targeted investments will be critical to securing long-term market leadership.
