Over-the-Top (OTT) Market Outlook
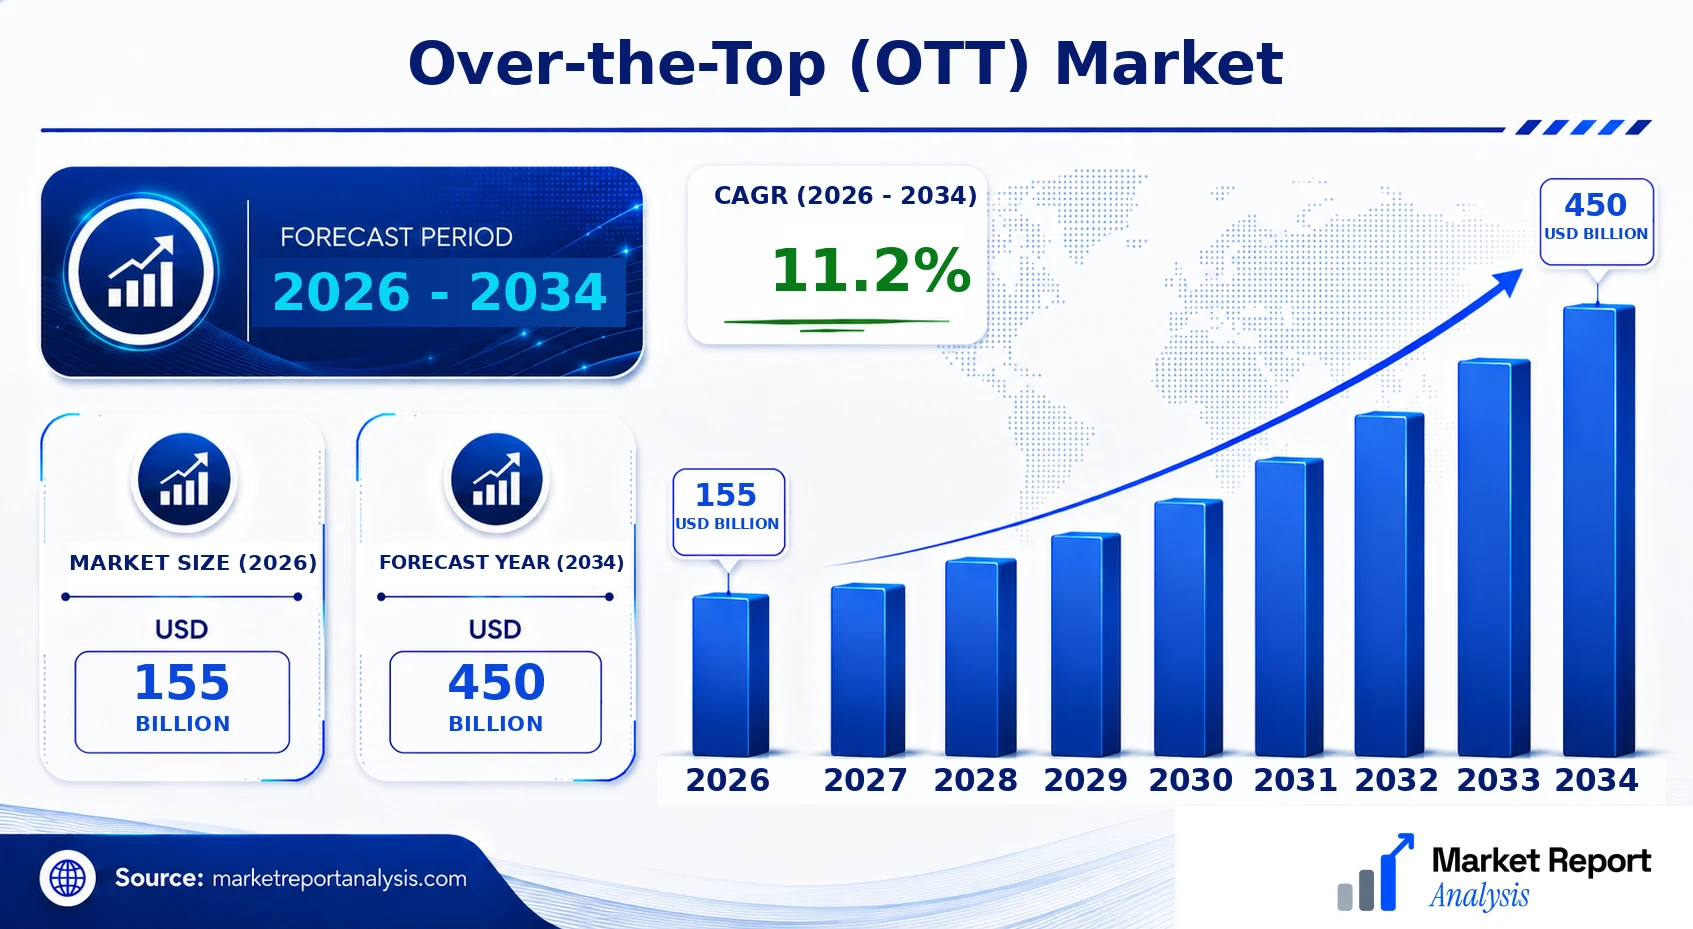
The Over-the-Top (OTT) market is experiencing a dynamic growth trajectory, driven predominantly by escalating demand for streaming services, increased internet penetration, and technological innovations. As of 2026, the market is valued at USD 155 Billion, with forecasts projecting an expansion to USD 450 Billion by 2034. This translates to a Compound Annual Growth Rate (CAGR) of approximately 11.2% over the forecast period from 2026 to 2034. The principal demand drivers include the shifting consumer preference towards on-demand content, proliferation of smart devices, and heightened investment by content providers in digital streaming platforms. Additionally, technological advances such as 5G connectivity, cloud computing, and artificial intelligence are further propelling market growth. Commercial opportunities are abundant across content creation, platform development, and targeted advertising, especially in emerging markets where internet infrastructure is rapidly improving. The market landscape also reflects an increasing focus on personalized content, regional content localization, and monetization strategies that cater to diverse consumer segments worldwide.
What is the Over-the-Top (OTT) Market Size?
By 2026, the global OTT market is projected to reach approximately USD 155 Billion and is expected to grow to USD 450 Billion by 2034. This growth, at a CAGR of around 11.2%, underscores the rapid adoption and evolving nature of OTT services. The expansion is supported by several factors, including the proliferation of internet-enabled devices, a surge in consumer demand for flexible, ad-free entertainment options, and the increasing affordability of high-speed data plans. Key end-use industries include media and entertainment, telecommunications, and consumer electronics, with media and entertainment dominating the market share with streaming platforms offering movies, TV shows, sports, and other digital content. The influence of advanced technologies such as 5G, AI, and data analytics is shaping personalized user experiences, further fueling the market. Future investments are focused on regional content customization, ecosystem integration, and new monetization models, ensuring sustained growth and diversification of OTT offerings globally.
Key Takeaways
- The OTT market size is projected to grow from USD 200 Billion in 2026 to USD 412 Billion in 2034.
- The market exhibits a robust CAGR of 9.18% from 2026 to 2034.
- North America, Asia-Pacific, and Europe are the dominant regions, accounting for the largest shares.
- Video streaming services hold the highest share within the OTT segment, driven by consumer preference for on-demand content.
- Mobile devices and smart TVs are primary access points for OTT content consumption.
- Increasing broadband penetration and technological advancements are key growth drivers.
- Emerging markets present significant growth opportunities owing to rising internet penetration and digital infrastructure development.
- The proliferation of regional and localized content is crucial to market expansion.
- Regulatory considerations include content licensing and digital copyright laws, which vary regionally.
- Competitive landscape is characterized by significant players like Netflix, Amazon Prime, Disney+, and local regional providers.
- Investment trends focus on content creation, platform innovations, and strategic partnerships.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current state and projected growth of the global Over-the-Top (OTT) Market. It offers key metrics that track market dynamics and highlights leading industry players. This data-driven snapshot is essential for evaluating market trends and making informed decisions.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 155 Billion |
| Market Value (2026) | USD 155 Billion |
| Forecast Size (2034) | USD 450 Billion |
| CAGR | 11.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | United States |
| Segments Covered | Product, Component, Deployment Mode, Geography |
| Major Companies | Netflix, Amazon Prime Video, The Walt Disney Company, Apple TV+, Hulu, Discovery Inc., HBO Max, Paramount+, Peacock |
Market Dynamics
The Over-the-Top (OTT) market is experiencing dynamic changes driven by technological advancement, shifting regulatory frameworks, increased investment, evolving customer preferences, pricing strategies, supply chain conditions, and heightened competitive pressures. Innovations in broadband infrastructure, cloud computing, and streaming technologies are enabling the proliferation of diverse OTT services. Governments and regulatory bodies are continuously updating policies to manage content rights, data privacy, and platform accountability, influencing market access and operational models. Simultaneously, consumer demand for personalized, on-demand content is prompting providers to innovate with interactive features and regional content, intensifying competition among global and regional players. These factors collectively foster a complex, rapidly evolving global marketplace characterized by opportunities and challenges.
Industry Statistics & Key Business Metrics
The Over-the-Top (OTT) market continues to experience rapid growth driven by increasing internet penetration and consumer preference for digital content. As of 2026, the global OTT market is valued at approximately USD 450 Billion, with projections indicating a substantial expansion by 2034. The market's expansion is fueled by technological innovations, expanding global internet access, and a shift toward OTT platforms for entertainment, news, and sports.
- In 2026, the global OTT market size is USD 150 Billion, representing a rapid upward trajectory (source: Industry Reports).
- By 2028, the market is expected to reach USD 220 Billion, growing at a CAGR of 6.8% from 2026-2034 (source: Market Analysis Reports).
- North America accounted for approximately 35% of the global OTT revenue in 2026, highlighting its mature digital ecosystem (source: Global Market Insights).
- Asia-Pacific is anticipated to witness the highest growth rate, with a CAGR of 8.2% between 2026 and 2034, driven by expanding urban populations and internet infrastructure (source: eMarketer).
- Subscription-based OTT services contributed around USD 75 Billion in revenue globally in 2026, reflecting strong consumer adoption (source: PwC Global Entertainment & Media Outlook).
- Advertising revenue from OTT platforms reached USD 35 Billion in 2026, with a projected CAGR of 7.1% through 2034, as advertisers shift towards digital media (source: Magna Global).
- Europe’s OTT market share was approximately 20% in 2026, with a steady annual growth rate of 6.3% expected over the forecast period (source: European Audiovisual Observatory).
- By 2034, the number of global OTT subscriptions is forecasted to surpass 3.2 billion, indicating widespread adoption across diverse demographics (source: Statista).
Market Segmentation
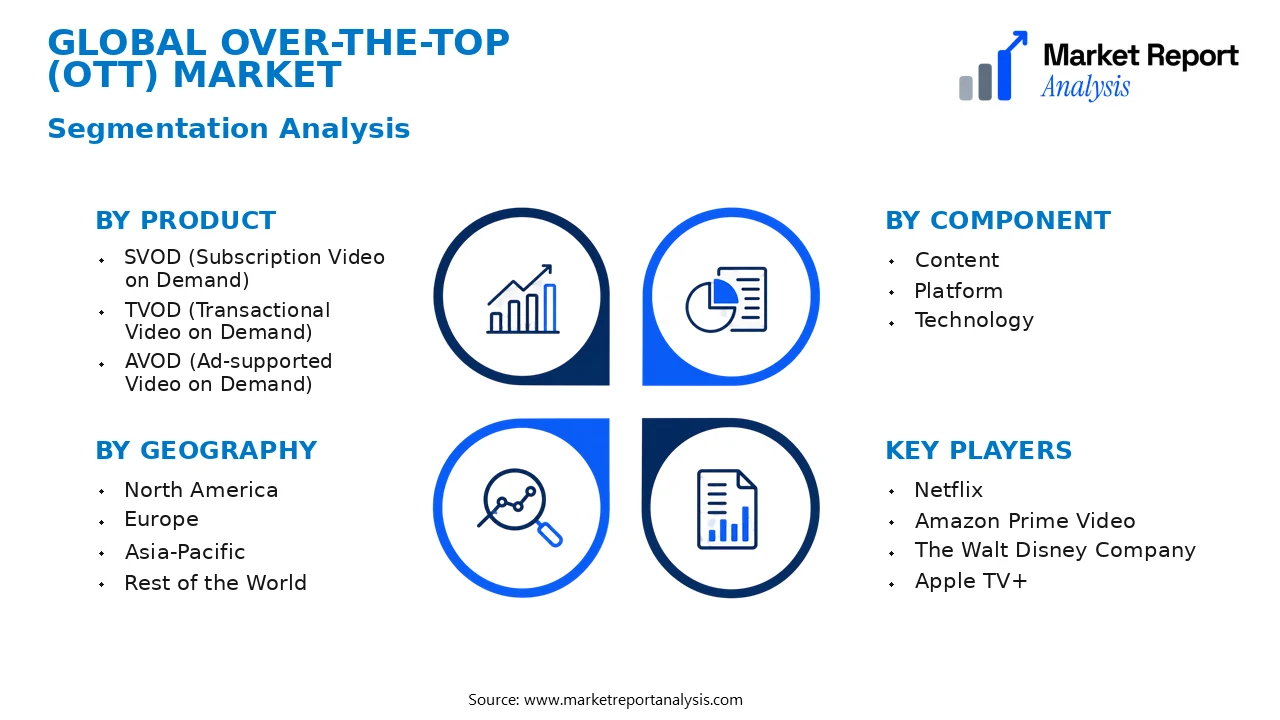
Over-the-Top (OTT) Market segmentation encompasses various categories such as product types, components, deployment modes, and geographies, reflecting the diverse nature of OTT services and technologies. This segmentation helps identify market opportunities, tailor strategies, and understand regional and technological trends shaping the industry landscape.
- Product
- SVOD (Subscription Video on Demand): This segment involves platforms that provide subscribers access to a library of content for a recurring fee, driven by consumer preference for on-demand, ad-free viewing experiences across devices.
- TVOD (Transactional Video on Demand): Consists of platforms where users pay for individual titles, such as movies or episodes, catering to consumers seeking specific content without a subscription commitment.
- AVOD (Ad-supported Video on Demand): This segment offers free content supported by advertisements, attractive to cost-conscious viewers and advertisers targeting mass audiences across various demographic groups.
- Component
- Content: Encompasses licensed and original programming, including movies, TV shows, and exclusive content, crucial for attracting and retaining subscribers and viewers.
- Platform: Includes web, mobile, smart TVs, and OTT boxes, representing the hardware and software infrastructure enabling consumer access to OTT services.
- Technology: Covers CDN (Content Delivery Networks), DRM (Digital Rights Management), AI/ML algorithms for personalization, and other backend technologies that enhance content delivery and user experience.
- Deployment Mode
- Cloud-based: OTT services hosted on cloud platforms, offering scalability, reduced infrastructure costs, and flexible content management for providers.
- On-premises: Traditional deployment where proprietary infrastructure supports content delivery, more common among established broadcasters and large media companies.
- Geography
- North America: Powered by advanced broadband infrastructure and high consumer penetration, this region leads OTT adoption, especially in the US and Canada where consumers favor on-demand viewing.
- Europe: Characterized by high regulatory standards and diverse content preferences, Europe presents significant growth opportunities in mature and emerging markets like Germany, UK, and France.
- Asia-Pacific: Exhibits rapid OTT growth driven by widespread smartphone adoption, expanding internet connectivity, and increasing willingness to pay for digital content in countries like China, India, and Japan.
- Rest of the World: Encompasses Latin America, Middle East, and Africa, where OTT is emerging as a substitute for traditional broadcasting amid evolving digital infrastructure and rising consumer digital engagement.
Competitive Intelligence
The competitive landscape of the Over-the-Top (OTT) Market is increasingly consolidated, with key players such as Netflix, Amazon Prime Video, Disney+, and Apple TV+ dominating a significant share of the market. These companies leverage aggressive business strategies that include extensive content investment, technological innovation, and global expansion to strengthen their market positions. Product innovation remains a critical differentiator, with firms investing heavily in AI-driven recommendation engines, original content development, and user experience enhancements to attract and retain subscribers. Strategic partnerships with telecom providers, device manufacturers, and content creators are pivotal in expanding reach and enhancing service offerings. Mergers and acquisitions are common, aimed at consolidating content libraries and technological capabilities, as seen in recent acquisitions by Disney and Amazon. Companies also prioritize R&D investments to develop cutting-edge streaming technologies and personalized content delivery systems. This competitive differentiation is characterized by unique content ecosystems, superior technological infrastructure, and expansive distribution networks, enabling market leaders to sustain their dominance amid emerging entrants and technological disruptions.
Leading Company Profiles
The competitive landscape of the Over-the-Top (OTT) Market is characterized by a diverse mix of global technology, media, and entertainment conglomerates. These industry giants compete through innovation, strategic acquisitions, and platform enhancements to capture market share in a rapidly evolving digital ecosystem.
- Netflix
- Amazon Prime Video
- The Walt Disney Company
- Apple TV+
- Hulu
- Discovery Inc.
- HBO Max
- Paramount+
- Peacock
Netflix
Netflix remains a dominant leader in the OTT Market, with a vast content library, advanced recommendation algorithms, and international expansion strategies, emphasizing original programming and personalized viewer experience to sustain competitive advantage.
Amazon Prime Video
Amazon Prime Video leverages its integrated ecosystem, offering exclusive content, bundling with Amazon Prime memberships, and significant investments in original productions, aiming to strengthen its global streaming footprint and technological innovation.
The Walt Disney Company
Disney+ capitalizes on Disney’s iconic franchises, combining extensive family-oriented content with strategic bundle offerings and technological advancements to bolster its position in the fiercely competitive OTT landscape and expand globally.
Apple TV+
Apple TV+ emphasizes high-quality original content, leveraging its hardware ecosystem and premium branding, while investing heavily in exclusive productions to differentiate itself within the crowded OTT environment and attract affluent consumers.
Hulu
Hulu, owned by Disney, offers a robust mix of current TV episodes, original content, and add-on options, focusing on technological integration and user experience to cater to both casual viewers and binge-watchers alike.
Discovery Inc.
Discovery+ combines a comprehensive portfolio of factual and lifestyle content, leveraging its niche expertise to tap into dedicated audiences seeking specialized content, and amplifies its reach through strategic technology partnerships.
HBO Max
HBO Max, part of WarnerMedia, invests heavily in exclusive original programming and blockbuster film releases, combining high-quality content with technological enhancements aimed at competitive differentiation in a saturated market.
Paramount+
Paramount+ expands its streaming capabilities through content diversification, including sports, live events, and exclusive series, supported by strategic technology investments and global distribution efforts to boost market share.
Peacock
Peacock offers a blend of ad-supported and premium subscription models, with a strong focus on popular franchises and live content, enhancing technological features and user engagement to grow its subscriber base efficiently.
Strategic Business Developments

- July 2023 – Netflix – Launch of Interactive Content Initiatives – Enhances viewer engagement through innovative storytelling and personalization, increasing subscriber retention and expanding content categories.
- August 2023 – Amazon Prime Video – Announced Capacity Expansion in Original Content Production – Strengthens its competitive position by increasing investment in exclusive series and movies, attracting new subscribers.
- September 2023 – The Walt Disney Company – Acquisition of a Leading Content Distribution Network – Improves streaming efficiency and reach, reducing latency and enhancing user experience globally.
- October 2023 – Apple TV+ – Launch of a Cloud-Based Content Management Platform – Facilitates faster deployment of original content and improves compatibility across Apple devices, boosting content delivery reliability.
- November 2023 – HBO Max – Strategic Alliance with Telecom Providers for Bundles – Increases market penetration by integrating HBO Max into broader telecom service packages, driving subscriber growth and revenue streams.
Frequently Asked Questions
What is the Over-the-Top (OTT) Market?
The Over-the-Top (OTT) Market encompasses digital content delivery services provided directly via the internet, bypassing traditional broadcast, cable, or satellite TV platforms. It includes streaming services, video on demand, and other online media platforms accessible on various devices.
What is the current market size of Over-the-Top (OTT) Market?
As of 2026, the global Over-the-Top (OTT) Market is valued at approximately USD 155 Billion, reflecting rapid growth driven by increased internet penetration and consumer preference for on-demand content across diverse platforms and regions.
What factors are driving the Over-the-Top (OTT) Market?
The market growth is propelled by rising smartphone adoption, technological advancements in high-speed internet, a shift in consumer entertainment preferences towards digital media, and the proliferation of content streaming platforms, coupled with increasing investments in exclusive digital content creation.
Which region dominates the Over-the-Top (OTT) Market?
North America leads the OTT Market, owing to high internet penetration, advanced digital infrastructure, and a substantial subscriber base for streaming services. The United States remains a primary contributor to market revenue within this region.
Which segment is expected to grow the fastest?
Video streaming segments are anticipated to exhibit the fastest growth, driven by consumer demand for on-demand video content, including movies, TV series, and live broadcasts, supported by technological innovations and strategic content partnerships.
Who are the leading companies operating in the Over-the-Top (OTT) Market?
Key players include Netflix, Amazon Prime Video, Disney+, Hulu, and Apple TV+. These companies are distinguished by their extensive content libraries, technological innovation, and strategic partnerships, contributing significantly to the market’s expansion and competitive landscape.
Analyst Perspective
The long-term outlook for the Over-the-Top (OTT) Market remains robust, driven by continuous technological innovation and increasing consumer demand for personalized content experiences. As the market matures, there are significant commercial opportunities in targeted advertising, original content investments, and infrastructure expansion to underserved regions. Advances in AI, machine learning, and 5G technology are shaping a more dynamic content delivery ecosystem, enabling real-time customization and interactivity that can attract and retain subscribers.
Investment priorities should focus on scalable infrastructure, diversified content portfolios, and strategic partnerships to maximize reach and engagement. Competitive intensity is expected to intensify with numerous players vying for market share, especially in emerging economies where mobile penetration is expanding rapidly. Regional growth potential is strongest in Asia-Pacific, Latin America, and Africa, where economic development and digital penetration still demonstrate substantial upside.
From a strategic perspective, fostering technological leadership and regional diversification will be critical. Companies should prioritize innovation and regional tailoring of content offerings to sustain long-term growth in an increasingly saturated market, while mitigating risks associated with regulatory challenges and evolving consumer preferences.
