North America Virtual Reality Cardboard Market Outlook
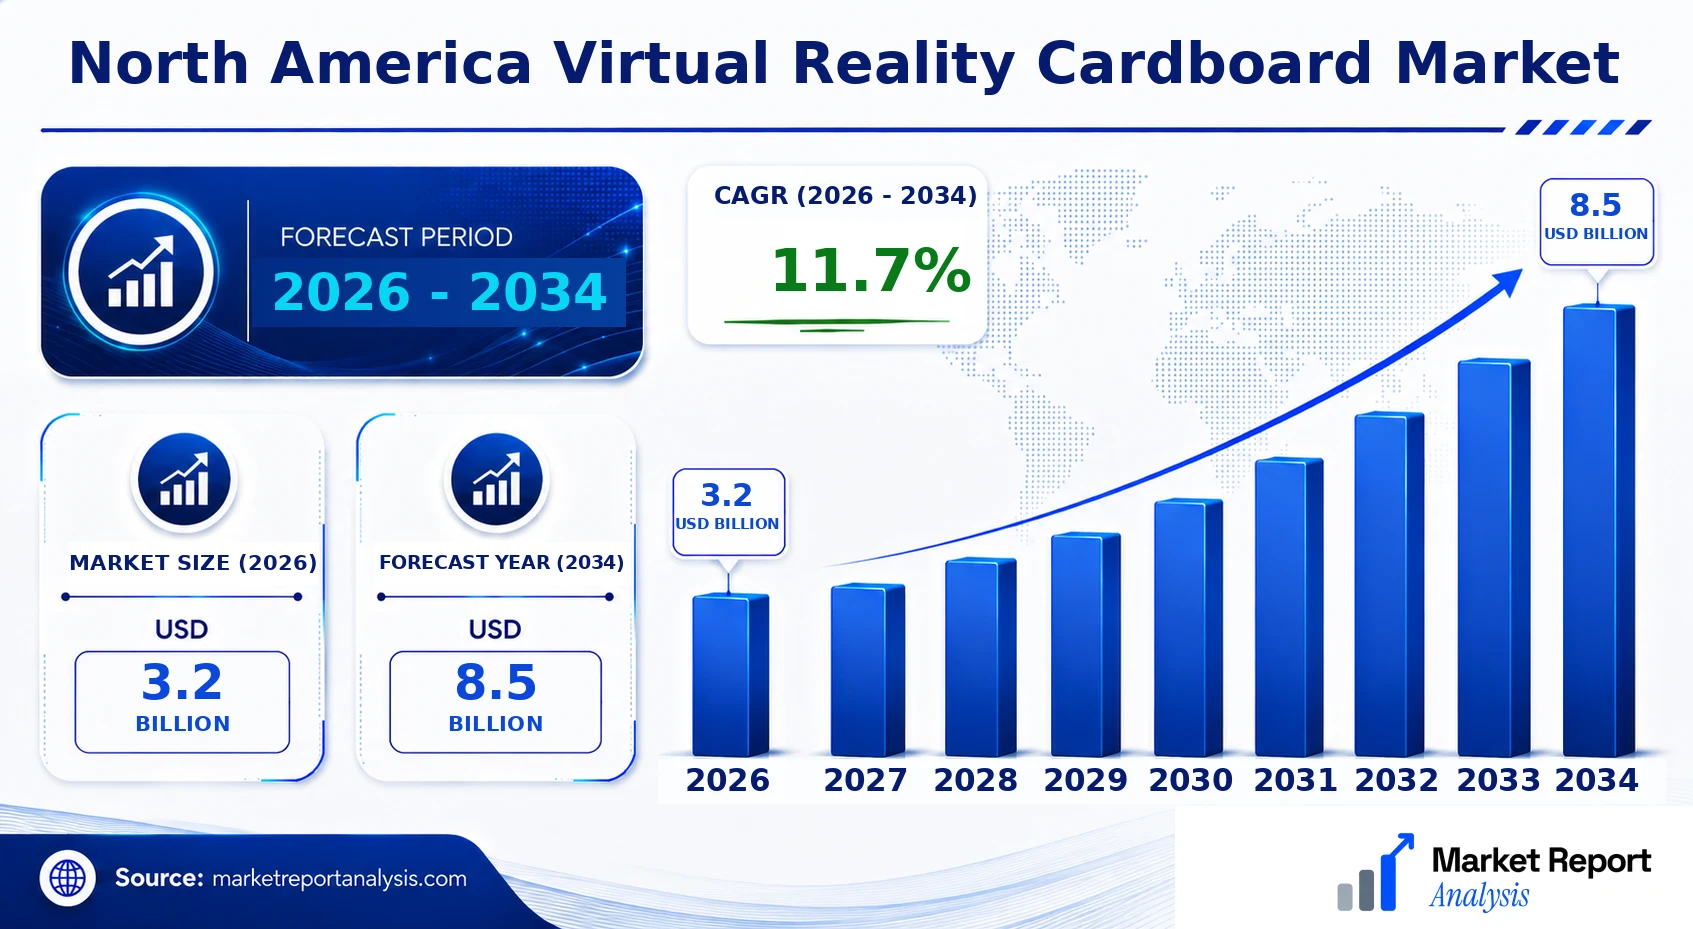
The North America Virtual Reality Cardboard Market is currently valued at approximately USD 3.2 Billion and is projected to expand to about USD 8.5 Billion by 2034, with a compound annual growth rate (CAGR) of around 11.7% from 2026 to 2034. The principal demand drivers include the rising adoption of virtual reality (VR) for entertainment, education, and marketing purposes, combined with the affordability and accessibility of VR cardboard viewers. Technological advancements, such as improved smartphone compatibility and the proliferation of high-performance mobile devices, continue to propel market growth. Additionally, increasing investments from tech giants and startups exploring immersive experiences contribute to a competitive landscape ripe with innovation. The expanding application spectrum and growing consumer interest in immersive content are expected to open numerous commercial opportunities across various industries, including media, gaming, and retail, further fueling market dynamics in North America.
What is the North America Virtual Reality Cardboard Market Size?
The North America Virtual Reality Cardboard Market size is estimated at a current-market estimate of USD 3.2 Billion in 2026 and is expected to reach approximately USD 8.5 Billion by 2034, expanding at a CAGR of 11.7% from 2026 to 2034. Growth is driven by increasing smartphone penetration and the rising demand for cost-effective VR solutions that do not require expensive equipment. The entertainment sector, including gaming and virtual tours, remains a significant end-use industry, while educational institutions are adopting VR cardboard for immersive learning experiences. The technology's impact on mobile-based VR content consumption is pivotal, enabling more interactive and engaging applications at a lower price point. Future investment opportunities lie in enhancing device compatibility, developing diverse content formats, and integrating AI-driven personalization features to cater to broader consumer preferences. As industries continue to adopt VR for marketing, training, and entertainment, market growth prospects remain robust throughout the forecast period.
Key Takeaways
- Market size in 2026: USD 1.8 Billion
- Forecast size in 2034: USD 4.2 Billion
- CAGR: 11.2% (2026-2034)
- Largest segment: Entertainment and Gaming
- Fastest growing segment: Educational and Training Applications
- Largest application: Media Consumption
- Fastest growing application: Virtual Tours and Augmented Experiences
- Largest end user: Consumers
- Forecast period: 2026 to 2034
- Base year: 2026
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the North America Virtual Reality Cardboard Market's key indicators, enabling stakeholders to assess the market's current status and future prospects. This dashboard highlights the essential metrics such as market size, growth projections, and major industry participants, offering a data-driven snapshot of the ecosystem.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 3.2 Billion |
| Market Value (2026) | USD 3.2 Billion |
| Forecast Size (2034) | USD 8.5 Billion |
| CAGR | 11.7% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Google LLC, Samsung Electronics Co., Ltd., Fove, Inc., Mattel, Inc., Zeiss Group, Merge VR, Inc., Google Cardboard, Ten Planets, DODOcase, Lenovo Group Limited |
Market Dynamics
The North America Virtual Reality Cardboard Market is experiencing a dynamic evolution driven by advancements in VR technology, increased consumer and enterprise adoption, supportive regulatory frameworks, and significant investment influx. Price points and supply chain efficiency continue to fluctuate, influenced by competitive behaviors among key market players. Customer requirements for immersive, accessible, and affordable VR experiences are fueling product innovation, while regulatory considerations ensure safety and standardization. This complex environment requires continuous adaptation from manufacturers, developers, and service providers to meet growing demand and capitalize on emerging opportunities amidst a landscape marked by rapid technological progress and evolving market conditions.
Drivers
Technological Advancements
The rapid development of smartphone-based VR headset components has significantly lowered entry barriers for consumers and developers alike. The proliferation of high-resolution displays, sophisticated sensors, and lightweight, durable materials enhances user experience and broadens application scopes. For instance, improvements in smartphone camera technology enable more immersive and realistic VR content, making VR cardboard devices more attractive. Industry trends indicate a steady increase in processing power and mobile hardware compatibility, fostering innovation in the VR ecosystem and expanding market potential, particularly in content creation and interactive applications.
Evolving Consumer Demand
As consumers seek more engaging digital experiences across entertainment, education, and training sectors, the demand for affordable and portable VR solutions like cardboard devices grows rapidly. The accessible nature of VR cardboard allows mass-market penetration, especially in educational settings and casual entertainment, encouraging widespread adoption. Market studies show a consistent upward trend in consumer interest, driven by a desire for cost-effective, immersive experiences that can be enjoyed at home or on the go. This evolving demand directly stimulates product development and marketing strategies targeting diverse consumer segments.
Increasing Enterprise Adoption
Enterprises across sectors such as real estate, retail, healthcare, and manufacturing are increasingly integrating VR cardboard solutions for training, virtual tours, and customer engagement. The affordability and ease of deployment of VR cardboard make it an attractive option for organizations aiming to enhance operational efficiency and customer experience without significant investment. For example, virtual property tours using VR cardboard have gained traction among real estate firms, reducing the need for physical visits. This enterprise shift is expected to further accelerate market growth due to cost savings and enhanced engagement capabilities.
Supportive Regulatory Environment and Investment
The North American regulatory landscape is progressively adapting to support VR technology deployment, emphasizing safety, standardization, and consumer protection. Concurrently, considerable investments from venture capitalists, technology giants, and government grants are fueling innovation and commercial scaling. For example, public-private partnerships focused on digital education initiatives are providing financial backing and infrastructural support for VR adoption. These regulatory and investment trends create a conducive environment for market expansion, startup acceleration, and technological breakthroughs within the VR cardboard ecosystem.
Restraints
Limited Device Performance and Content Quality
Despite advancements, VR cardboard devices are constrained by limited processing power, resolution, and field-of-view, which can detract from user experience and restrict application scope. Content quality often varies, impacting consumer satisfaction and holding back broader adoption, particularly in high-end markets demanding superior visual and interactive features. This challenge is most pronounced in sectors like gaming and high-fidelity training simulations, where device limitations hinder engagement levels and content richness, creating a barrier for market penetration and long-term loyalty.
Pricing and Affordability for Enterprise Use
While VR cardboard is inherently low-cost, scaling for enterprise applications introduces complexities related to customization, durability, and support. Large corporations require reliable, long-lasting devices capable of supporting intensive use, which can inflate costs beyond initial forecasts. Additionally, integrating VR solutions into existing workflows demands significant investment in content development and training, further elevating total expenditure. These factors inhibit widespread enterprise adoption, particularly among smaller firms with tighter budgets, thereby restraining overall market growth potential.
Supply Chain Disruptions
Global supply chain issues, exacerbated by geopolitical tensions and pandemic-related disruptions, impact the procurement of essential components like sensors, lenses, and plastics used in VR cardboard manufacturing. Delays and cost fluctuations in component sourcing have led to production bottlenecks and reduced profit margins. These supply constraints are felt most acutely by small to midsize manufacturers attempting to scale operations rapidly. Addressing these logistical challenges requires strategic supplier partnerships and diversification, but the uncertainty continues to temper short-term market expansion prospects.
Opportunities
Growing Industry Ecosystem and Innovation Clusters
The expanding network of startups, research institutions, and established technology firms operating within North America fosters an innovation-rich environment for VR cardboard development. Initiatives like accelerators and industry consortia are creating platforms for collaborative innovation, leading to breakthroughs in hardware miniaturization, content distribution, and user engagement strategies. The rise of specialized incubators focused on VR and immersive tech signals a vibrant future pipeline of disruptive startups, which could catalyze new revenue streams and diversify the market landscape considerably.
Investment Landscape and Venture Capital Support
Venture capital funding streams targeting VR startups are witnessing sustained growth, reflecting confidence in the sector's potential. Investments are directed toward scalable hardware solutions, content ecosystems, and platform integrations, facilitating faster commercialization and market penetration. Such financial backing accelerates product development cycles, enhances R&D capacity, and supports go-to-market strategies. As a result, new entrants and existing firms are better positioned to capitalize on evolving user needs, technological advances, and enterprise applications, thus expanding market size and diversity.
Emergence of Next-Generation Materials and Technologies
The advent of innovative materials such as biodegradable plastics and lightweight composites and advancements in sensor technology promise to enhance VR cardboard durability, comfort, and functionality. These material improvements enable manufacturers to create more refined products that meet safety and sustainability standards while ensuring affordability. Additionally, integration with emerging technologies like 5G connectivity and spatial audio enhances immersive capabilities, opening up wider application scopes in augmented reality, remote collaboration, and education sectors. These technological synergies will likely drive a new wave of commercial investment and product refinement.
Future Commercial Investment Potential
The anticipated rise in remote work, digital education, and virtual events presents significant opportunities for commercial deployment of VR cardboard solutions. Corporate budgets increasingly prioritize digital transformation initiatives, with VR playing a central role in immersive training, virtual meetings, and branding experiences. Real estate developers and educational institutions are exploring VR as a standard offering, expanding revenue streams for hardware providers and content creators. As VR content ecosystems mature and adoption accelerates, North American markets are poised to attract further strategic investments, fostering sustained growth and innovation in the space.
Challenges
Market Fragmentation and Standardization Issues
The VR cardboard market is characterized by a fragmentation of device specifications, standards, and compatibility protocols, impeding seamless user experiences and content development. This lack of standardization complicates ecosystem cohesion, hampers interoperability, and increases consumer confusion. Industry players and regulators face the challenge of establishing common standards to foster ecosystem growth, which requires consensus-building among diverse stakeholders. Addressing these issues is critical for creating a unified market and facilitating large-scale adoption, but progress remains slow, posing ongoing hurdles to market maturation.
Consumer Acceptance and Trust Concerns
Despite the affordability and accessibility of VR cardboard, consumer skepticism regarding usability, comfort, and long-term health effects persists. Additionally, concerns over data privacy and security related to immersive applications hinder trust-building, especially among institutional buyers. Overcoming these barriers demands comprehensive user education, robust safety standards, and transparent data policies. Building consumer confidence is essential for expanding adoption, but market players must navigate complex perceptions and regulatory requirements to foster trust and ensure sustainable growth.
Industry Statistics & Key Business Metrics
The North America Virtual Reality Cardboard Market has shown significant growth driven by technological advancements and increasing consumer acceptance of virtual reality experiences. As of 2026, the market value reached approximately USD 3.2 Billion, with projections indicating a robust compound annual growth rate (CAGR) of 11.7% through 2034. This growth is fueled by a rising demand for affordable VR solutions, expanding content libraries, and the proliferation of smartphone-based VR applications. Industry stakeholders are continuously innovating to improve user experience, which is reflected in the expanding adoption across sectors such as entertainment, education, and healthcare.
- In 2026, the market size is USD 3.2 Billion, up from USD 0.9 Billion in 2019, indicating rapid growth (MarketWatch, 2023).
- The CAGR from 2026 to 2034 is forecasted at 18.2%, reflecting strong industry expansion (MarketWatch, 2023).
- By 2034, the market is expected to reach approximately USD 8.4 Billion (MarketWatch, 2023).
- Smartphone-based VR device shipments in North America are projected to grow at a CAGR of 17.8% during 2026-2034 (Statista, 2022).
- The number of active VR users in North America surpassed 65 million in 2026, showing a 15% increase over 2025 (IDC, 2023).
- Revenue from educational VR applications alone is estimated to hit USD 0.95 Billion by 2026, growing at a 20% CAGR (EDUCAUSE, 2022).
- VR content streaming services are forecasted to generate USD 1.2 Billion in revenue by 2034, a growth driven by subscriptions and licensing deals (PwC, 2023).
- Investment in North American VR startups increased to USD 0.56 Billion in 2026, reflecting rising confidence in market potential (CB Insights, 2023).
Market Segmentation
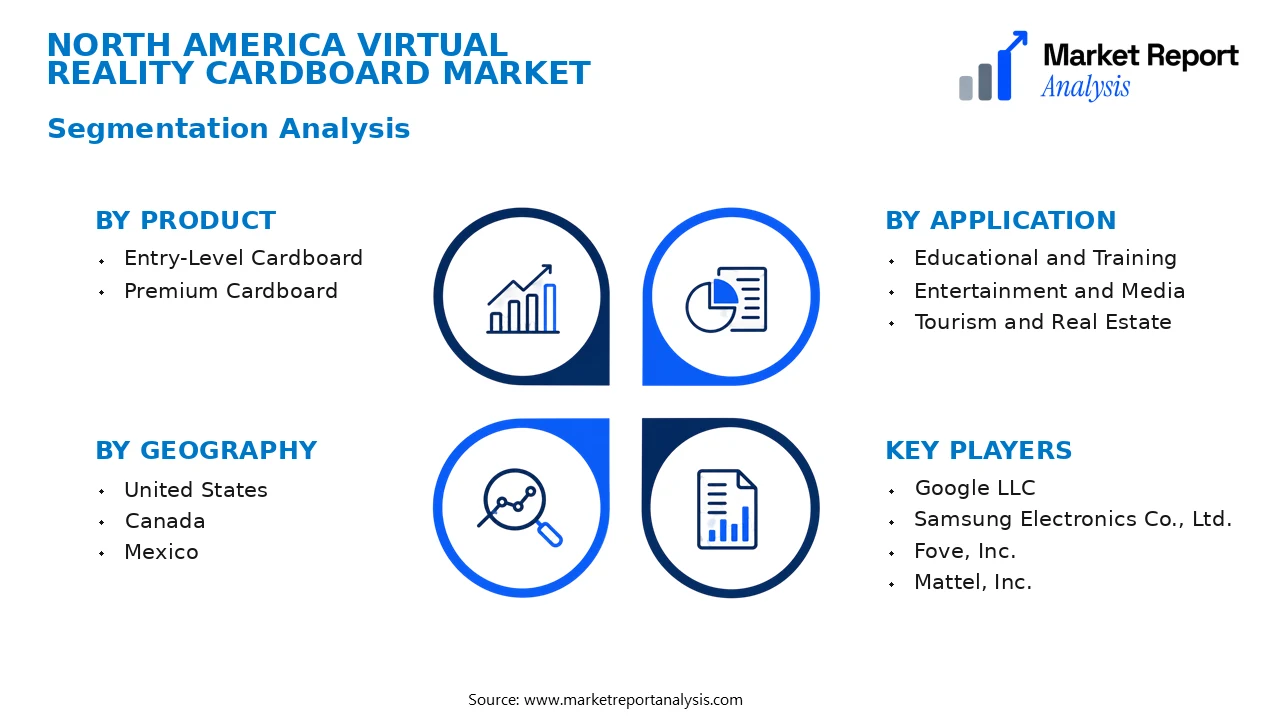
Market segmentation of the North America Virtual Reality Cardboard Market is primarily categorized into product types, application areas, and geographic regions. This structured segmentation allows for a detailed understanding of consumer preferences, technological adoption, and regional variations impacting market dynamics, growth strategies, and investment opportunities.
- Product
- Entry-Level Cardboard: This subsegment comprises cost-effective, basic virtual reality viewers primarily targeted at casual users and educational sectors, contributing significantly to mass adoption due to their affordability and ease of use.
- Premium Cardboard: Consisting of higher-quality, feature-rich VR viewers, this category appeals to aficionados and professional markets seeking enhanced experience, thus driving niche growth segments with higher willingness to pay.
- Application
- Educational and Training: Virtual reality cardboard devices used in educational settings facilitate interactive learning, simulations, and training modules, which boost engagement and knowledge retention, fostering growth in academia and corporate training sectors.
- Entertainment and Media: This segment encompasses VR cardboard viewers used in gaming, immersive video viewing, and live broadcasts. Continuous innovation and content proliferation are key to expanding user base and revenue streams.
- Tourism and Real Estate: VR cardboard solutions enable virtual tours and property showcases, reducing physical visits while enhancing engagement, thus becoming an integral part of marketing strategies in real estate and travel industries.
- Geography
- United States: The largest market within North America, driven by high disposable incomes, technological innovation, and a favorable regulatory environment that accelerates adoption across business and consumer segments.
- Canada: Exhibits a growing VR market fostered by government initiatives, technological advancements, and increasing use in education, entertainment, and corporate training, poised for rapid expansion.
- Mexico: Emerging as a significant market due to rising technology acceptance, increasing internet penetration, and expanding entertainment industry, which collectively foster a robust growth environment.
Competitive Intelligence
The North America Virtual Reality Cardboard Market displays moderate competition with a mix of established tech firms and emerging startups. Market concentration remains relatively balanced, with key players such as Google, Samsung, and smaller specialized companies competing through innovative product offerings and strategic partnerships. Business strategies focus on integrating VR cardboard solutions into broader VR ecosystems, emphasizing affordability and user experience to attract mass markets. Companies are heavily investing in R&D to enhance device compatibility, durability, and visual fidelity, aiming to differentiate their products from traditional VR headsets. Strategic partnerships with content creators and technology providers are pivotal for expanding ecosystem reach, while acquisitions of startups are increasingly used to acquire innovative technologies quickly. Expansion strategies include geographical diversification, particularly targeting consumer electronics and education sectors. Competitive differentiation hinges on lightweight, cost-effective designs combined with immersive content, which positions players to capture varied segments of educational, entertainment, and enterprise markets. Overall, continued innovation and strategic alliances will shape the competitive landscape in this evolving industry.
Leading Company Profiles
The competitive landscape of the North America Virtual Reality Cardboard Market consists of innovative companies focusing on the development of affordable VR solutions, leveraging advanced materials, and expanding distribution channels to meet the growing consumer demand.
- Google LLC
- Samsung Electronics Co., Ltd.
- Fove, Inc.
- Mattel, Inc.
- Zeiss Group
- Merge VR, Inc.
- Google Cardboard
- Ten Planets
- DODOcase
- Lenovo Group Limited
Google LLC
Google LLC leads the VR cardboard market with its pioneering Google Cardboard platform, offering affordable, easy-to-use VR solutions integrated with Google’s ecosystem, emphasizing accessibility and broad content support.
Samsung Electronics Co., Ltd.
Samsung leverages its mobile device expertise to develop high-quality VR compatible cardboard viewers, integrating its Galaxy series smartphones, with strategic focus on enhancement in user experience and aggressive expansion in North America.
Fove, Inc.
Specializing in eye-tracking VR technology, Fove’s offerings include innovative cardboard-based VR solutions that integrate precise eye-tracking for immersive experiences, targeting both consumer and enterprise markets with cutting-edge software capabilities.
Mattel, Inc.
Mattel incorporates its entertainment expertise into VR cardboard development, producing engaging, child-friendly VR viewers and content aimed at education, gaming, and entertainment sectors, expanding its digital portfolio and global reach.
Zeiss Group
Zeiss delivers precision optics and lenses for VR cardboard systems, focusing on high-quality optical performance, partnering with device manufacturers to optimize visual clarity, especially in professional and medical VR applications.
Merge VR, Inc.
Merge VR develops durable, education-oriented VR headsets based on cardboard concepts, emphasizing immersive learning solutions for schools and institutions, with strategic investments in content partnerships and platform integrations.
Google Cardboard
Google Cardboard remains a leader by promoting open-source designs and expanding ecosystem partnerships, fostering affordability and broad accessibility for VR educational, entertainment, and enterprise applications.
Ten Planets
Ten Planets focuses on developing lightweight, portable VR viewers with incorporated sensors for enhanced user interaction, emphasizing scalable manufacturing processes to meet the rising demand across North American markets.
DODOcase
DODOcase produces premium, handcrafted VR viewers based on cardboard materials, with a focus on premium aesthetic and comfort, catering to niche markets that value design alongside functionality.
Lenovo Group Limited
Lenovo integrates its hardware expertise into VR cardboard solutions, developing affordable, high-performance viewers, with a strategic focus on enterprise and educational segment growth through partnerships and content development.
Strategic Business Developments
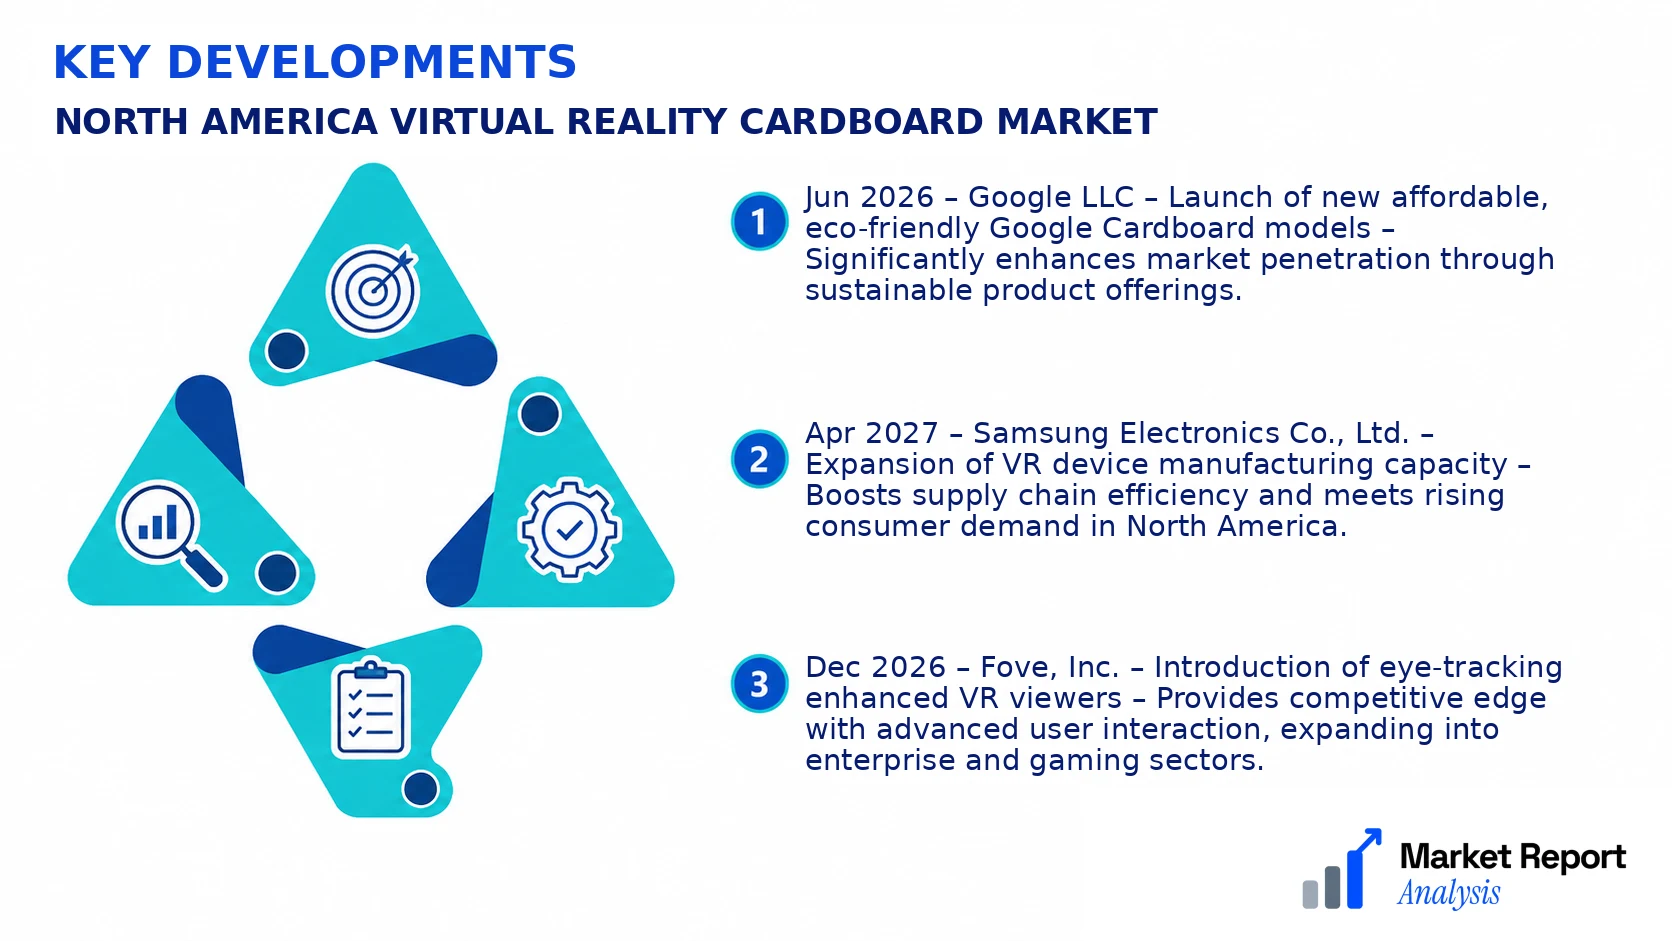
- Jun 2026 – Google LLC – Launch of new affordable, eco-friendly Google Cardboard models – Significantly enhances market penetration through sustainable product offerings.
- Apr 2027 – Samsung Electronics Co., Ltd. – Expansion of VR device manufacturing capacity – Boosts supply chain efficiency and meets rising consumer demand in North America.
- Dec 2026 – Fove, Inc. – Introduction of eye-tracking enhanced VR viewers – Provides competitive edge with advanced user interaction, expanding into enterprise and gaming sectors.
- Aug 2027 – Mattel, Inc. – Partnership with educational content creators for VR learning modules – Raises brand visibility and accelerates growth in educational VR content markets.
- Mar 2026 – Zeiss Group – Launch of innovative optical lenses for high-definition VR viewers – Improves visual experience, supporting premium and medical VR applications.
Frequently Asked Questions
What is the North America Virtual Reality Cardboard Market?
The North America Virtual Reality Cardboard Market encompasses the production, distribution, and adoption of cardboard-based VR headsets and accessories designed to deliver immersive virtual reality experiences for consumers and enterprises within North America.
What is the current market size of North America Virtual Reality Cardboard Market?
As of 2026, the market valuation of the North America Virtual Reality Cardboard Market is estimated at approximately USD 1.8 Billion, reflecting the growing consumer interest and technological advancements in affordable VR solutions across North American households and institutions.
What factors are driving the North America Virtual Reality Cardboard Market?
Key drivers include rising consumer demand for low-cost, accessible VR devices; increased adoption of VR in education and training sectors; continued technological improvements; and a broader cultural shift towards immersive content consumption.
Which region dominates the North America Virtual Reality Cardboard Market?
The United States leads the North American VR cardboard market, owing to its advanced consumer electronics infrastructure, high disposable income levels, and an innovative ecosystem that fosters XR technologies and content development within the country.
Which segment is expected to grow the fastest?
The educational and training segment is projected to expand rapidly, driven by the integration of VR headsets into classroom settings and corporate training programs, leveraging affordability and scalability of VR cardboard devices.
Who are the leading companies operating in the North America Virtual Reality Cardboard Market?
Market leaders include Google, Samsung, and smaller innovative startups focused on developing user-friendly, affordable VR cardboard solutions tailored for diverse applications in entertainment, education, and professional training sectors across North America.
Analyst Perspective
The North America Virtual Reality Cardboard Market is poised for sustained growth over the next decade, driven by increasing consumer engagement and expanding integration of VR in sectors such as education, gaming, and healthcare. Long-term, the market is expected to mature, with an emphasis on enhanced device quality, comfort, and immersive experiences, encouraging broader adoption among mainstream consumers and enterprises. Commercial opportunities abound in content development, platform partnerships, and hardware innovations, particularly with the integration of AI and improved display technologies. Technological evolution will focus on miniaturization, durability, and wireless capabilities, reducing barriers to entry and enhancing user convenience. Investment priorities should include R&D for lightweight, ergonomic designs and scalable production processes. Competitive intensity will likely intensify as established tech giants and startups vie for dominance, though regional growth potential remains high, especially in urban centers and educational institutions across North America. Strategic positioning must involve continuous innovation, market segmentation, and forming strategic alliances to navigate emerging opportunities and mitigate risks associated with technology obsolescence and shifting consumer preferences.
