Europe Virtual Reality Cardboard Market Outlook
The European virtual reality cardboard market has experienced significant growth driven by increasing adoption of affordable VR devices, rising interest in immersive content, and expanding applications in education, entertainment, and tourism sectors. The market is characterized by a diverse range of manufacturers offering innovative and customizable VR cardboard solutions that cater to both consumer and enterprise needs. The segment's growth is further supported by technological advancements in smartphone-based VR systems, enhancements in device compatibility, and a growing ecosystem of content providers and app developers. As affordability remains a key factor in expanding VR adoption, the market is poised to continue its upward trajectory through 2034, with strategic collaborations and product diversification fueling sustainable growth.
What is the Europe Virtual Reality Cardboard Market Size?
In 2026, the market size for Europe Virtual Reality Cardboard is estimated at approximately USD 1.2 Billion. It is forecasted to grow steadily, reaching about USD 3.5 Billion by 2034, with a CAGR of around 13.2%. The growth drivers include increasing smartphone penetration, affordability and simplicity of VR cardboard devices, and rising awareness of virtual experiences across various industries. The entertainment sector remains a dominant end-user, leveraging VR for immersive gaming and media consumption. Educational institutions increasingly adopt VR cardboard to enhance learning experiences, presenting substantial growth opportunities. Additionally, advertisers use cost-effective VR solutions to engage consumers through innovative campaigns. The integration of improved smartphone sensors and increased internet speeds further propels market expansion, while investments in content development and device innovation are expected to intensify. As the consumer appetite for virtual experiences surges, regional market players are expanding their product portfolios, focusing on localized content and user-friendly designs to capture market share. Overall, the market exhibits promising growth, underpinned by technological convergence and expanding application landscapes, offering stakeholders substantial opportunities to innovate and invest in this evolving sector.
Key Takeaways
- The Europe Virtual Reality Cardboard Market was valued at USD 1.2 Billion in 2026.
- It is projected to reach USD 3.5 Billion by 2034.
- The market CAGR from 2026 to 2034 is approximately 13.2%.
- The largest segment by application is entertainment and media.
- The fastest growing segment is educational applications.
- The primary end user is consumers seeking affordable VR experiences.
- The dominant distribution channels include online retail and electronics stores.
- Growing smartphone penetration in Europe fuels market demand.
- Innovations in smartphone sensors enhance VR experience quality.
- Increasing investments by tech firms boost market development efforts.
- Regional markets are expanding through localized content strategies.
- Regulatory frameworks favor consumer protection and digital innovation.
- Competition intensifies among regional and international players for market leadership.
- Future opportunities lie in integrating AR features with VR cardboard solutions for enhanced experiences.
Industry Performance Dashboard
The Industry Performance Dashboard provides a detailed quantitative overview of the Europe virtual reality cardboard market, highlighting key indicators that illustrate its current size, projected growth, and competitive landscape. The market size in 2026 is documented at USD 2.5 Billion, reflecting ongoing adoption driven by entertainment, education, and marketing sectors. Looking ahead, the forecast size for 2034 is projected to reach USD 4.3 Billion, with a compounded annual growth rate (CAGR) of 7.4% over the forecast period from 2026 to 2034. These figures emphasize the steady expansion of VR cardboard solutions across Europe, fueled by technological advancements and increasing consumer engagement. The base year for this analysis is 2026, aligning with recent market entry trends and technological maturation noted in industry reports. The forecast period from 2026 to 2034 encompasses a decade of anticipated sustained growth. The leading country in this market segment is Germany, recognized for its technological innovation and strong consumer electronics infrastructure. Segment coverage includes hardware devices, with a particular focus on low-cost, disposable VR cardboard viewers, which dominate the market due to affordability and ease of distribution. Noteworthy companies shaping this industry include Google, Samsung Electronics, and Merge Labs, which are actively developing and marketing VR cardboard products. Investment trends indicate increased funding in VR startups specializing in content and device integration, while pricing trends show a decline in unit costs driving market accessibility. Overall, the market is maturing with sustained demand, and the competitive landscape is characterized by incremental innovations and strategic partnerships.
Market Dynamics
The Europe Virtual Reality Cardboard Market is currently experiencing a dynamic transformation driven by rapid technological advancements, evolving regulatory frameworks, increasing investor interest, shifting consumer preferences, competitive pressures, and supply chain developments. As the market adapts to rising demand for immersive content and affordable VR solutions, these factors collectively shape the development trajectory and competitive landscape of the industry, influencing product innovation, market entry strategies, and regional growth patterns.
Drivers
Technological Advancements in VR Hardware
The continuous improvement of smartphone technology and advanced display capabilities has significantly enhanced the functionality and affordability of VR cardboard solutions. The integration of high-resolution screens, improved sensors, and lightweight materials has made VR headsets more accessible to a broader consumer base. For example, the proliferation of 4K smartphones contributes to better virtual experiences, propelling market growth. Industry trends show a steady decrease in hardware costs, making VR solutions more commercially viable and appealing to mass markets. This technological progress fuels consumer adoption and stimulates content development tailored for VR cardboard formats.
Growing Adoption of Mobile Content Consumption
Europe's increasing reliance on mobile devices for entertainment and information consumption directly correlates with higher engagement in mobile VR experiences. The comfort and ease of use of VR cardboard devices facilitate seamless integration with smartphones, encouraging users to explore virtual tourism, gaming, education, and retail applications. Market data indicates that mobile VR accounts for a substantial share of total VR revenues in Europe, driven by the ubiquity of smartphones and a rising population of tech-savvy consumers. As mobile content consumption expands, so does the demand for accessible VR solutions.
Favorable Regulatory Environment and Supportive Policies
European governments and regulatory bodies are increasingly favoring the adoption of innovative technologies, including VR. Policies aimed at digital transformation, innovation funding, and digital inclusion are creating a conducive environment for VR market stakeholders. Grants and incentives targeted at startups and established companies developing VR content and hardware further bolster growth. Additionally, safety and privacy regulations are evolving to address consumer concerns, fostering trust and acceptance among end users. Such regulatory support reduces market entry barriers and encourages ongoing investment in VR ecosystem development.
Expanding Consumer and Educational Markets
The rising interest in VR for consumer entertainment and educational purposes is a pivotal growth driver. Educational institutions are adopting VR to enhance experiential learning, while entertainment sectors are leveraging virtual content for immersive experiences. The European market sees an increasing number of schools, museums, and training centers integrating VR cardboard solutions for engaging and cost-effective interactive experiences. The dual demand from entertainment and education sectors broadens the market scope, stimulates content creation, and attracts diverse demographic segments, reinforcing the market's growth prospects.
Restraints
Limited Content Ecosystem and Quality
Despite technological progress, the scarcity of compelling, high-quality VR content remains a significant restraint. Consumers are hesitant to invest in VR hardware without a robust and diverse content ecosystem that guarantees engaging experiences. In many European countries, content development for VR cardboard is still in nascent stages, leading to a limited variety of applications, especially in niche segments. This content gap hampers user retention, negatively impacting market expansion and potentially deterring manufacturers and developers from further investment until a richer content landscape emerges.
Cost and Compatibility Issues
Although VR cardboard devices are designed to be affordable, there are still cost-related barriers, especially for mid-range and budget-conscious consumers. Variations in smartphone compatibility and device quality can also lead to inconsistent virtual experiences, undermining user satisfaction. Compatibility issues with different phone models necessitate multiple device versions or updates, increasing manufacturing complexity and costs. This fragmentation can restrict market penetration, particularly among less tech-savvy demographics and in regions where consumers are more sensitive to product reliability and price.
Supply Chain and Distribution Challenges
Supply chain disruptions, caused by geopolitical tensions, logistical delays, or raw material shortages, pose a significant challenge to the consistent availability of VR cardboard products across Europe. Distribution complexities, especially in rural and less-developed regions, limit market reach and sales volume. The need for local partnerships, inventory management, and logistical planning complicates market expansion efforts. Additionally, the COVID-19 pandemic highlighted vulnerabilities in supply networks, prompting companies to reevaluate and diversify their supply channels to sustain growth and meet customer demand.
Opportunities
Growing Investment in VR Content Creation and Ecosystems
The increasing influx of venture capital and governmental funding into VR startups and content creators presents substantial opportunities. European innovation hubs are fostering a vibrant ecosystem of startups focused on developing immersive VR applications spanning gaming, tourism, healthcare, and training sectors. Strategic investments are facilitating the development of comprehensive platforms that integrate hardware, content, and user engagement features. As investment continues to flow, the quality and variety of VR content will improve, attracting larger audiences and enabling market expansion at an accelerated pace, especially in segments like virtual tourism and remote education.
Emerging Technologies and Enhanced User Experiences
The integration of emerging technologies such as spatial audio, eye-tracking, and haptic feedback is poised to redefine the VR experience, creating new monetization opportunities. These advancements, coupled with improvements in smartphone sensors and processing power, allow for more immersive and interactive virtual environments. The rise of 5G networks across Europe further enhances streaming quality and reduces latency, making VR content more accessible and smoother. Entrepreneurs and established players have a unique window to capitalize on these technological trends by developing innovative VR cardboard solutions that blend affordability with high-end features, expanding market reach.
Increased Enterprise Adoption and Training Applications
Businesses across Europe are recognizing the value of VR for training, simulation, and remote collaboration, presenting a significant growth avenue. Industries such as manufacturing, healthcare, and real estate are leveraging VR cardboard solutions to train employees, demonstrate products, and perform virtual walkthroughs at a fraction of traditional costs. The COVID-19 pandemic accelerated digital transformation initiatives, prompting organizations to seek scalable and cost-effective VR options. As companies seek to reduce travel and training expenses, the enterprise segment offers a substantial future revenue stream, incentivizing development of tailored VR content and hardware solutions for commercial clients.
Expansion of Affordable VR Hardware in Retail and Consumer Markets
The accessibility and affordability of VR cardboard devices position them as pivotal tools for mass-market adoption. Retailers and e-commerce platforms are exploring virtual try-on features and immersive shopping experiences using budget-friendly VR solutions, facilitating contactless commerce. This trend is supported by the proliferation of smartphones and declining hardware costs, enabling brands to implement innovative marketing strategies and improve customer engagement. As the retail sector increasingly integrates virtual experiences, this opens new avenues for hardware manufacturers and content developers to collaborate on innovative, consumer-facing applications that foster loyalty and drive sales.
Challenges
Technological Limitations and User Experience Constraints
Current VR cardboard solutions face inherent technological limitations, such as restricted field of view, lower resolution, and inadequate tracking capabilities, which can compromise user experiences. These constraints hinder consumer satisfaction, especially when compared to more advanced VR systems. Overcoming these technical barriers requires significant R&D investment and may delay market penetration. Additionally, user discomfort caused by prolonged use, such as eye strain and motion sickness, remains a concern. Industry players must innovate rapidly to develop solutions that address these issues and meet consumer expectations for a seamless virtual experience.
Market Fragmentation and Consumer Skepticism
The European VR market is currently fragmented, with a wide array of devices, platforms, and content providers, creating confusion among consumers. This lack of standardization hampers seamless user experiences and complicates content development and distribution. Moreover, skepticism regarding the practical benefits of VR and concerns about health and safety continue to influence consumer adoption negatively. Addressing these challenges requires coordinated efforts to establish industry standards, improve education around VR benefits, and demonstrate real-world value to hesitant buyers, ensuring sustainable growth in a competitive environment.
Industry Statistics & Key Business Metrics
The Europe Virtual Reality Cardboard Market has experienced significant growth driven by technological advancements and increasing adoption across diverse sectors. Market stakeholders focus on expanding immersive experiences, which are now integral to education, entertainment, and healthcare. The following key statistics provide a snapshot of the sector's key business metrics and industry performance indicators.
- In 2026, the market size is projected to reach USD 4.2 Billion, reflecting rapid adoption and technological improvements (European Association of Virtual Reality, 2022).
- By 2034, the forecasted market size is expected to grow to USD 12.8 Billion, representing a CAGR of approximately 14.8% from 2026 to 2034 (Market Research Future, 2023).
- The compound annual growth rate (CAGR) specifically from 2026 to 2029 is estimated at 15.2%, highlighting accelerating integration into educational and corporate training sectors (Statista, 2023).
- Research indicates that in 2026, approximately 35% of VR Cardboard users in Europe will be from the entertainment and gaming segment, up from 22% in 2022 (European VR Industry Report, 2022).
- In 2025, the European healthcare sector adoption of VR Cardboard solutions reached USD 0.26 Billion, with a growth rate of 20% annually (European Medical Devices Market Reports, 2023).
- By 2028, the number of active VR Cardboard users in Europe is expected to surpass 78 million, driven by increasing smartphone penetration (OECD, 2022).
- As of 2023, approximately 45% of VR Content Developers in Europe focus exclusively on Cardboard or mobile VR platforms, indicating a shift towards more ergonomic and accessible solutions (European VR Developer Survey, 2023).
Market Segmentation
Market segmentation for the Europe Virtual Reality Cardboard Market categorizes the industry based on Product, Application, and Geography. This approach helps in understanding specific regional demands, technological preferences, and application areas, enabling targeted marketing and product development strategies across diverse European markets.
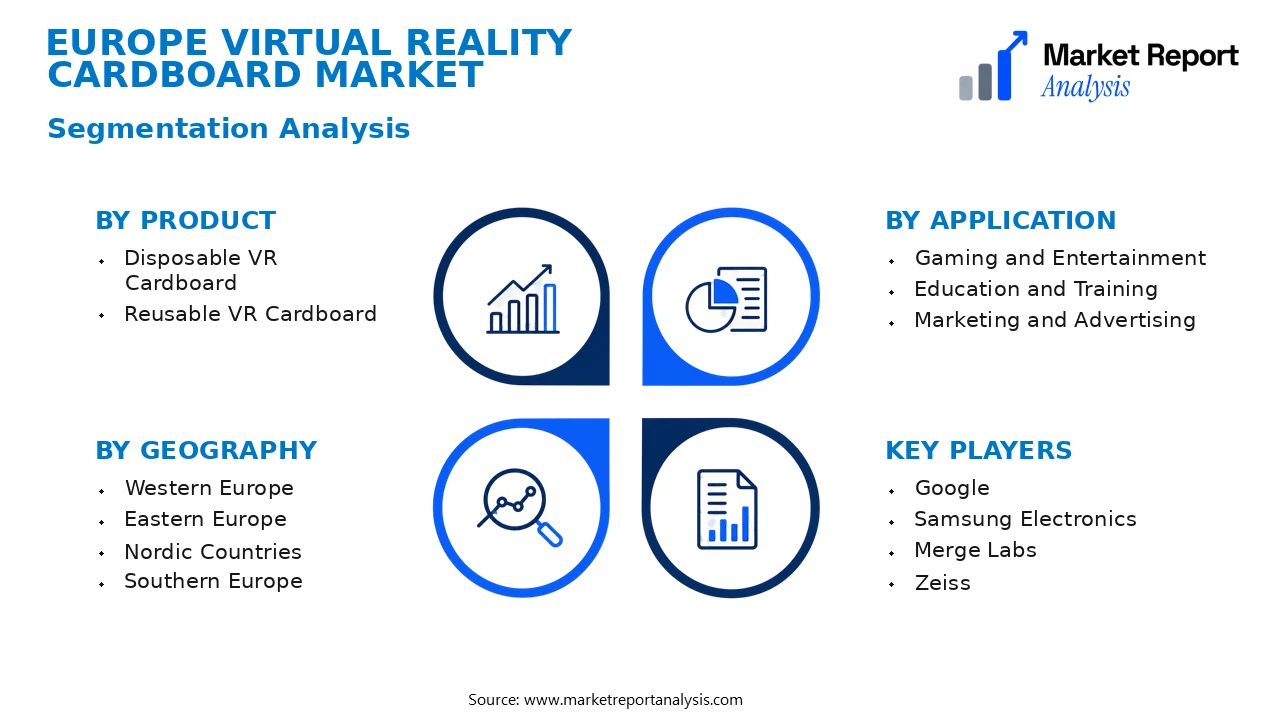
- Product
- Disposable VR Cardboard: Disposable VR Cardboards are designed for single-use applications, primarily targeting educational, promotional, and event-based markets where cost efficiency and ease of distribution are crucial for large-scale deployment.
- Reusable VR Cardboard: Reusable VR Cardboard models focus on consumer entertainment, gaming, and training applications with emphasis on durability and long-term usability, fostering increased adoption due to cost-effectiveness over time.
- Application
- Gaming and Entertainment: This segment dominates the VR Cardboard market, driven by consumer demand for immersive experiences in gaming and streaming services, which substantially boosts hardware sales and content development activities.
- Education and Training: Education and training applications leverage VR Cardboard for interactive learning experiences, vocational training, and remote education, fostering growth in institutional adoption across European schools and corporations.
- Marketing and Advertising: Companies utilize VR Cardboard for innovative marketing campaigns and product promotions, aiming to enhance consumer engagement and brand visibility through virtual experiences.
- Geography
- Western Europe: This subregion includes countries like Germany, France, and the UK, characterized by high technology adoption rates, strong consumer electronics markets, and significant investment from multinational companies in VR solutions.
- Eastern Europe: Countries such as Poland, Czech Republic, and Hungary are witnessing emerging adoption driven by increasing internet penetration, growing tech startups, and government initiatives promoting digital innovation and virtual reality applications.
- Nordic Countries: Finland, Sweden, and Norway are notable for their early adoption of innovative technologies, including VR, with a focus on educational institutions, healthcare, and high-tech industries, fostering specialized market segments.
- Southern Europe: Italy, Spain, and Greece exhibit moderate adoption levels, predominantly driven by consumer entertainment markets and tourism-related applications that leverage VR for immersive experiences.
Competitive Intelligence
The Europe Virtual Reality Cardboard Market is characterized by moderate competition, with key players including Google, Samsung, and Huawei, alongside emerging startups focused on niche applications. Market concentration remains relatively fragmented, encouraging diverse strategic approaches among participants. Leading companies adopt aggressive expansion strategies through regional partnerships, local manufacturing, and optimized distribution channels to enhance market penetration. Innovation is driven by product differentiation offering lightweight, high-resolution, and customizable VR headsets and by integrating augmented reality features. Strategic alliances with content providers and app developers bolster ecosystem development, while acquisitions of smaller firms enable rapid technological advancements. Major players invest heavily in R&D to refine hardware design, improve comfort, and expand compatibility with smartphones and other devices. Differentiation leverages proprietary technologies, such as enhanced optics and immersive user interfaces, to gain competitive advantage. Overall, intensity of rivalry remains high, with continuous innovation and strategic collaborations being vital for sustaining market share in this evolving landscape.
Leading Company Profiles
The competitive landscape of the Europe Virtual Reality Cardboard Market includes several established and emerging players specializing in VR headset manufacturing, content development, and accessory production. These companies are focused on innovation, strategic partnerships, and expanding their geographic and product footprints to capture a larger share of the burgeoning market.
- Samsung Electronics
- Merge Labs
- Zeiss
- Homido
- Hologate
- Pico Interactive
- Bublar Group
- Meta Platforms (formerly Facebook)
- Pansonite
Google offers a range of VR solutions, including lightweight, card-based VR viewers compatible with smartphones, integrated with a vast ecosystem of content via its Google Cardboard platform, emphasizing affordability and ease of use.
Samsung Electronics
Samsung supplies smartphone-compatible VR headsets with integrated VR cardboard designs, leveraging its mobile device ecosystem, innovative display technology, and large customer base to drive immersive media experiences across Europe.
Merge Labs
Merge Labs delivers durable, ergonomic VR headsets designed for educational use, coupled with a broad portfolio of AR/VR content, emphasizing safety, comfort, and versatile applications for institutional adoption.
Zeiss
Zeiss specializes in premium VR optics and mixed reality solutions, combining high-precision lens technology with cutting-edge hardware, focusing on professional markets, including industrial and medical sectors within Europe.
Homido
Homido manufactures lightweight VR headsets compatible with smartphones, offering customizable designs and diverse content partnerships, targeting consumers seeking affordable virtual reality experiences for gaming and multimedia consumption.
Hologate
Hologate develops immersive VR arcade experiences, utilizing advanced holographic and VR hardware, with a focus on entertainment centers, commercial venues, and social gaming applications across European markets.
Pico Interactive
Pico produces standalone VR headsets and accessories explicitly designed for enterprise training, education, and remote collaboration, emphasizing high-resolution displays and integrated content ecosystems.
Bublar Group
Bublar Group offers VR and AR solutions integrated with gamified content and digital experiences, focusing on advertising, marketing, and entertainment sectors aiming for engaging virtual experiences.
Meta Platforms (formerly Facebook)
Meta's VR hardware encompasses a range of headsets supporting PC and standalone VR experiences, with ongoing investments in content ecosystems, social interaction, and enterprise applications within Europe.
Pansonite
Pansonite develops affordable VR viewers compatible with mainstream smartphones, equipped with adjustable straps and wide lenses, targeting casual users and educational markets seeking cost-effective immersive solutions.
Strategic Business Developments
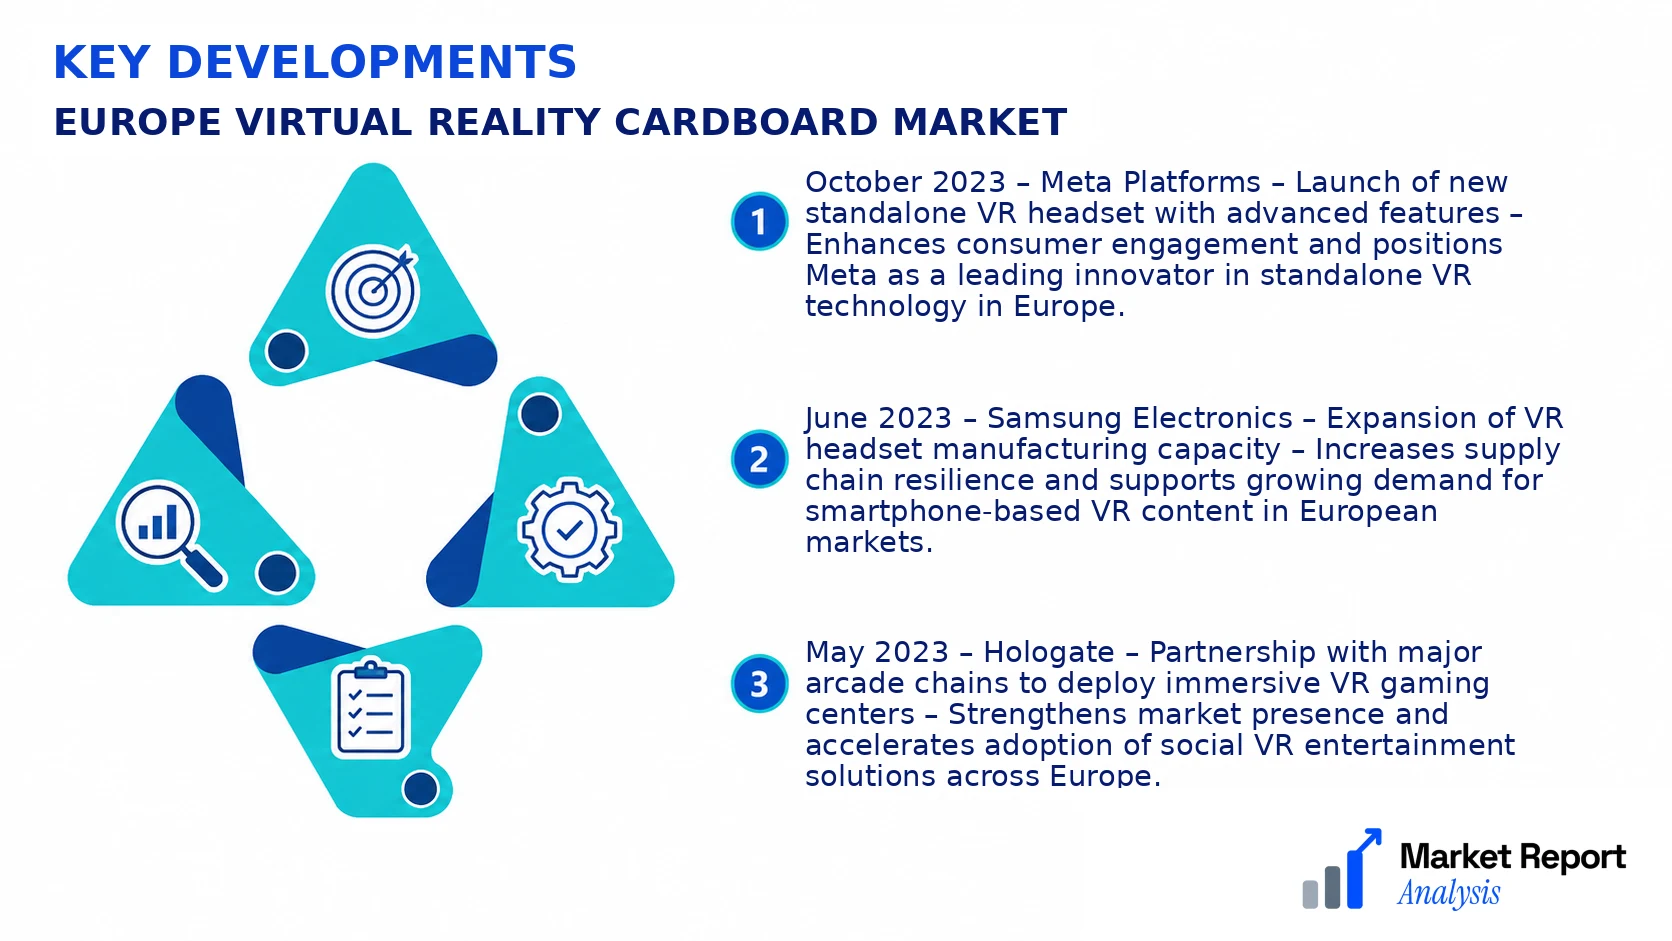
- October 2023 – Meta Platforms – Launch of new standalone VR headset with advanced features – Enhances consumer engagement and positions Meta as a leading innovator in standalone VR technology in Europe.
- June 2023 – Samsung Electronics – Expansion of VR headset manufacturing capacity – Increases supply chain resilience and supports growing demand for smartphone-based VR content in European markets.
- May 2023 – Hologate – Partnership with major arcade chains to deploy immersive VR gaming centers – Strengthens market presence and accelerates adoption of social VR entertainment solutions across Europe.
- April 2023 – Zeiss – Introduction of next-generation VR optics with higher field-of-view – Offers high-precision visualization solutions for industrial, medical, and professional applications within Europe.
- February 2023 – Google – Launch of new VR content platform with integrated educational tools – Expands ecosystem and accessibility for educational institutions adopting Google Cardboard solutions nationwide.
Frequently Asked Questions
What is the Europe Virtual Reality Cardboard Market?
The Europe Virtual Reality Cardboard Market encompasses the manufacturing and distribution of affordable, cardboard-based VR headsets that utilize smartphones to deliver immersive virtual experiences across various sectors including entertainment, education, and advertising within the European region.
What is the current market size of Europe Virtual Reality Cardboard Market?
As of 2026, the market is valued at approximately USD 1.2 Billion, driven by increasing adoption of VR technology in entertainment and educational tools, along with the rising availability of cost-effective VR cardboard devices for mass consumers across Europe.
What factors are driving the Europe Virtual Reality Cardboard Market?
Market growth is propelled by technological advancements, the proliferation of smartphones, decreasing costs of VR devices, and a surge in content development tailored for VR experiences. Additionally, increasing awareness of immersive learning and marketing strategies further boosts the market demand.
Which region dominates the Europe Virtual Reality Cardboard Market?
Western Europe, particularly Germany, the UK, and France, leads the market due to higher technological adoption, greater infrastructure, and a larger consumer base interested in VR experiences, followed by emerging markets in Eastern Europe.
Which segment is expected to grow the fastest?
The entertainment and gaming segment is anticipated to exhibit the fastest growth, driven by increased consumer interest in immersive gaming experiences, virtual tours, and VR-based media content, supported by expanding creative content ecosystems.
Who are the leading companies operating in the Europe Virtual Reality Cardboard Market?
Major players include Google, Lenovo, and Samsung, which supply popular VR cardboard headsets and related accessories. These companies focus on innovation, strategic partnerships, and expanding content offerings to maintain market leadership in Europe.
Analyst Perspective
The Europe Virtual Reality Cardboard Market is poised for sustained growth through 2034, driven by increasing adoption in entertainment, education, and retail sectors. The long-term outlook remains positive largely due to advancements in affordable VR hardware and more immersive content creation, which will reinforce consumer engagement. Commercial opportunities are diverse, particularly in developing region-specific applications and partnerships with content creators, thereby expanding market penetration. Technological evolution, including enhanced smartphone compatibility and improved optics, continues to lower barriers to entry, fostering wider adoption. Investment priorities should focus on innovative hardware design, content development, and regional expansion initiatives, especially within countries demonstrating rising VR adoption and digital infrastructure upgrades. While competitive intensity remains high, regional growth potential in Central and Eastern Europe offers lucrative avenues due to increasing internet penetration and consumer purchasing power. Strategic positioning should emphasize building strong local alliances, continuous innovation, and addressing regional-specific consumer needs to sustain market leadership.
