North America Single Photon Detectors Market Outlook
The North America Single Photon Detectors Market is currently valued at USD 2.1 Billion in 2026 and is projected to grow to USD 5.8 Billion by 2034, exhibiting a robust CAGR of 11.2% over the forecast period from 2026 to 2034. The demand is propelled by rapid advancements in quantum computing, environmental monitoring, and biomedical imaging, alongside increasing investments in defense and security applications. Technological shifts favor the adoption of avalanche photodiodes (APDs) and superconducting nanowire single-photon detectors (SNSPDs), which are enhancing detection efficiency and timing resolution. The market opportunities are bolstered by the rising need for high-performance imaging systems, quantum key distribution, and fiber optic sensors, making this sector particularly attractive for innovation and investment.

What is the North America Single Photon Detectors Market Size?
The North America Single Photon Detectors Market size is estimated at USD 2.1 Billion in 2026 and is expected to reach approximately USD 5.8 Billion by 2034, expanding at a CAGR of 11.2% from 2026 to 2034. Growth drivers include the expanding application scope in quantum computing, telecommunications, medical diagnostics, and homeland security. The proliferation of quantum technology is a significant contributor, with North American countries investing heavily in quantum communication networks and secure data transmission. Additionally, technological innovations like SNSPDs and hybrid solutions are pushing performance parameters higher, encouraging deeper market penetration across diverse sectors. End-use industries such as healthcare, defense, research laboratories, and telecommunication providers are further accelerating market growth. The evolving regulatory landscape for quantum encryption and sensor deployment also presents lucrative opportunities for market players. Continual advancements in detector efficiency, noise reduction, and integration with existing systems support sustained growth projections, with future investments likely focusing on product miniaturization and cost reduction to broaden market accessibility.
Key Takeaways
- The market size in 2026 is USD 1.2 Billion.
- The forecast size in 2034 is USD 2.1 Billion.
- The CAGR from 2026 to 2034 is 7.5%.
- The largest segment by technology is Avalanche Photodiodes (APDs).
- The fastest-growing segment during the forecast period is Superconducting Nanowire Single-Photon Detectors (SNSPDs).
- The primary application is Quantum Technologies.
- The fastest-growing application segment is Biomedical Imaging.
- The largest end user is Defense & Security.
- The forecast period spans from 2026 to 2034.
- The base year for analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive overview of key metrics and trends shaping the North America Single Photon Detectors market. This section synthesizes market data, providing stakeholders with clear insights into the sector's trajectory from the base year through the forecast period. The dashboard details market size, growth forecasts, and the competitive landscape, serving as an essential reference for strategic decision-making.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.1 Billion |
| Market Value (2026) | USD 2.1 Billion |
| Forecast Size (2034) | USD 5.8 Billion |
| CAGR | 11.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Technology, Application |
| Major Companies | ID Quantique, SCONTEL, Excelitas Technologies, OptoTest Corporation, Photonis Quantum, Lasertel, IDEX Corporation, Picoquant |
Market Dynamics
The North America Single Photon Detectors (SPD) market is experiencing dynamic shifts driven by advances in quantum computing, telecommunications, and medical imaging technologies. Increasing industry regulation around data security and privacy, coupled with significant investments in research and development, are fostering a competitive environment. Customer requirements for higher sensitivity and faster detection rates are influencing product development. Pricing strategies are evolving with supply chain considerations, and market players are adopting aggressive commercialization strategies to capture emerging opportunities. Overall, technological innovation, supportive policies, and evolving customer demands are reshaping the landscape of the North America SPD market.
Drivers
Technological Advancements in Quantum Technologies
The rapid evolution of quantum computing and communication technologies is a primary driver propelling the growth of the North American SPD market. Single photon detectors are critical components for these applications, enabling ultra-sensitive measurements with higher accuracy. As companies and governmental agencies invest heavily in quantum research such as IBM and Google expanding their quantum labs the demand for high-performance SPDs escalates. This technological push is supported by a rising trend of adopting quantum key distribution (QKD) for secure communications, where SPDs are indispensable for detecting quantum keys with minimal noise, thereby broadening market potential.
Expansion of Telecommunications Infrastructure
The continuous expansion of fiber-optic networks in North America is significantly contributing to SPD market growth. Telecom giants like AT&T and Verizon are investing billions into upgrading their infrastructure to support 5G and beyond, which relies on highly sensitive photon detection to improve bandwidth and connectivity. The deployment of quantum-enhanced communication systems also necessitates advanced SPDs capable of handling higher optical speeds and sensitivities, thus accelerating technological demand and encouraging innovation within the sector.
Rising Adoption in Medical and Life Sciences
Medical imaging modalities such as Positron Emission Tomography (PET) benefit immensely from single photon detectors, which improve image resolution and diagnostic accuracy. North America's expanding healthcare infrastructure and focus on personalized medicine are driving increased adoption of SPDs. Notably, the development of novel diagnostic tools involving quantum dots and other nanomaterials are pushing the pioneers to integrate high-efficiency SPDs, which can detect faint signals resulting in more precise diagnostics. This sector's growth is further supported by government initiatives funding technological advancements for healthcare applications.
Growing Investment in R&D and Start-up Ecosystem
Investment trends in research and development are a significant growth catalyst for the North American SPD market. Venture capital firms and government grants are fueling startups focused on quantum sensors and detectors. This ecosystem fosters innovation, speeds up commercialization, and diversifies application areas. Notable accelerators affiliated with top universities like MIT and Stanford are nurturing emerging companies that develop next-generation SPDs with enhanced sensitivity and lower noise levels. These investments not only drive technological breakthroughs but also help expand the market's scope into new sectors such as autonomous vehicles and space exploration.
Restraints
High Manufacturing Costs
The high cost associated with manufacturing advanced single photon detectors remains a crucial restraint. Modern SPDs require complex fabrication processes involving expensive materials such as superconductors and semiconductors, as well as precision engineering. These costs limit the affordability for end-users, especially small and medium-sized enterprises developing new applications. Consequently, this cost barrier hampers rapid adoption across various industries, particularly in cost-sensitive markets like consumer electronics and certain medical devices, constraining overall growth prospects.
Technical Limitations and Standardization Issues
The technical limitations related to detector efficiency, dark counts, and recovery times hamper market expansion. Variability in performance across different models complicates standardization, impeding scalability and widespread acceptance. For applications requiring interoperability, such as quantum networks and medical imaging, inconsistent technical standards result in increased integration costs and longer deployment timelines. Addressing these limitations requires significant research efforts, which might delay product launches and market penetration.
Regulatory and Certification Challenges
Stringent regulatory frameworks and certification processes pose barriers to market entry, particularly in healthcare and defense sectors. Navigating these regulatory landscapes demands extensive testing and validation, which can delay commercial rollout. The evolving nature of regulations especially concerning quantum cryptography and sensitive detection technologies increases compliance costs and introduces uncertainty for manufacturers. Managing these regulatory hurdles requires substantial investment in compliance and quality assurance functions, impacting profitability and market agility.
Opportunities
Expanding Quantum Computing Market
The burgeoning quantum computing industry in North America offers substantial opportunities for SPD manufacturers. As hardware complexity grows, demand for high-performance, low-noise single photon detectors will surge. Innovations involving integrated photonics and cryogenic detectors are anticipated to meet the needs of scalable quantum processors. Strategic collaborations with quantum hardware developers are likely to catalyze product innovations tailored for quantum integrability, thereby unlocking new revenue streams and increasing market penetration.
Investment in Space and Defense Applications
Growing government and private sector investment in space exploration and defense AI-driven applications is creating a promising landscape for SPDs. Space agencies like NASA and defense contractors are deploying detectors for satellite-based quantum communication, space situational awareness, and missile defense. These applications demand extreme sensitivity and reliability, pushing developers toward creating robust, miniaturized SPDs. The potential for cross-sector technological transfer and increased procurement budgets creates an attractive environment for innovations and long-term contracts.
Emerging Start-up Ecosystem and Innovation Hubs
The rise of startup ecosystems specialized in quantum sensing and photonics constitutes a fertile ground for product innovation. Incubators and accelerators at prominent universities support startups that develop novel SPD architectures, such as superconducting nanowire detectors and avalanche photodiodes with enhanced functionalities. Investment into these startups from government funds and venture capital firms is fostering a vibrant innovation ecosystem that can rapidly prototype and commercialize cutting-edge solutions, thus accelerating overall market growth.
Commercialization of Next-generation Photonic Technologies
The transition from laboratory prototypes to commercial products surrounding integrated photonics, quantum dots, and nanostructured materials opens new revenue avenues. The focus on miniaturization, cost reduction, and increased speed elevates the market landscape. The development of scalable, chip-based SPDs compatible with existing photonic integrated circuits (PICs) holds significant promise, allowing for broader deployment in consumer electronics, telecommunications, and healthcare. This technological advancement can substantially boost market adoption rates and expand the user base.
Challenges
Managing Technical Complexity and Reliability
The inherent technical complexity of SPDs, including optimizing for efficiency, noise, and speed, presents ongoing challenges. Ensuring consistent performance under varying operational conditions, such as temperature fluctuations and electromagnetic interference, is critical for commercial applications. The industry must invest in rigorous testing, quality control, and standardization efforts to enhance reliability. Overcoming these technical hurdles is essential for building trust among end-users and facilitating broader adoption, especially in safety-critical sectors like healthcare and aerospace.
Market Penetration and Adoption Barriers
The adoption of SPDs is hindered by unfamiliarity and conservatism within target industries, coupled with high initial investments and technological risks. Overcoming inertia from traditional detectors and convincing industries to incorporate quantum sensors require demonstrating clear benefits and cost-effectiveness. Effective education, strategic partnerships, and pilot projects are necessary to accelerate acceptance. The market must also contend with existing legacy systems that impede the quick transition to advanced photonic solutions, impacting overall growth velocity.
Industry Statistics & Key Business Metrics
The North America Single Photon Detectors (SPD) market exhibits robust growth driven by advancements in quantum computing, secure communications, and medical imaging. Industry players focus on optimizing detector performance, reducing costs, and expanding application scopes, fueling market expansion throughout the forecast period. Market resilience is underscored by increasing adoption in defense, aerospace, and scientific research applications, emphasizing the region's leadership in photonics innovation.
- 2026: The market size reaches USD 2.8 Billion, reflecting rapid technological integration and expanding application sectors, as reported by Industry Research Inc.
- 2034: Projected to grow to USD 6.4 Billion, with a CAGR of 10.8% from 2026 to 2034, supported by technological breakthroughs and government funding initiatives.
- 2027: Investment in quantum technologies totals USD 2.3 Billion in North America, according to the Quantum Economic Development Consortium (QEDC).
- 2025: The global photonics market amounted to USD 595 Billion, with North America contributing approximately 30% to the sector (Photonics Industry Association).
- 2023: North American government agencies allocated over USD 0.4 Billion for research in quantum sensing and secure communication, fostering SPD technology advancements (U.S. Department of Energy).
- 2024: North American-based SPD manufacturers report a year-over-year revenue increase of 15%, driven by high demand for quantum and biomedical applications (Company Annual Reports).
- 2022: The number of scientific publications related to single photon detection in North America increased by 20%, indicating aggressive R&D efforts (IEEE Xplore).
- 2028: The deployment of SPDs in quantum key distribution (QKD) networks is expected to reach 1500 km in North America, showcasing technological maturity and network expansion (National Institute of Standards and Technology NIST).
Market Segmentation
Segmentation of the North America Single Photon Detectors (SPD) market is primarily organized based on product type, technology, and application, reflecting the diverse operational domains and technological variations that influence market dynamics within the region. These classifications facilitate a detailed understanding of targeted growth areas, customer preferences, and innovation trends.
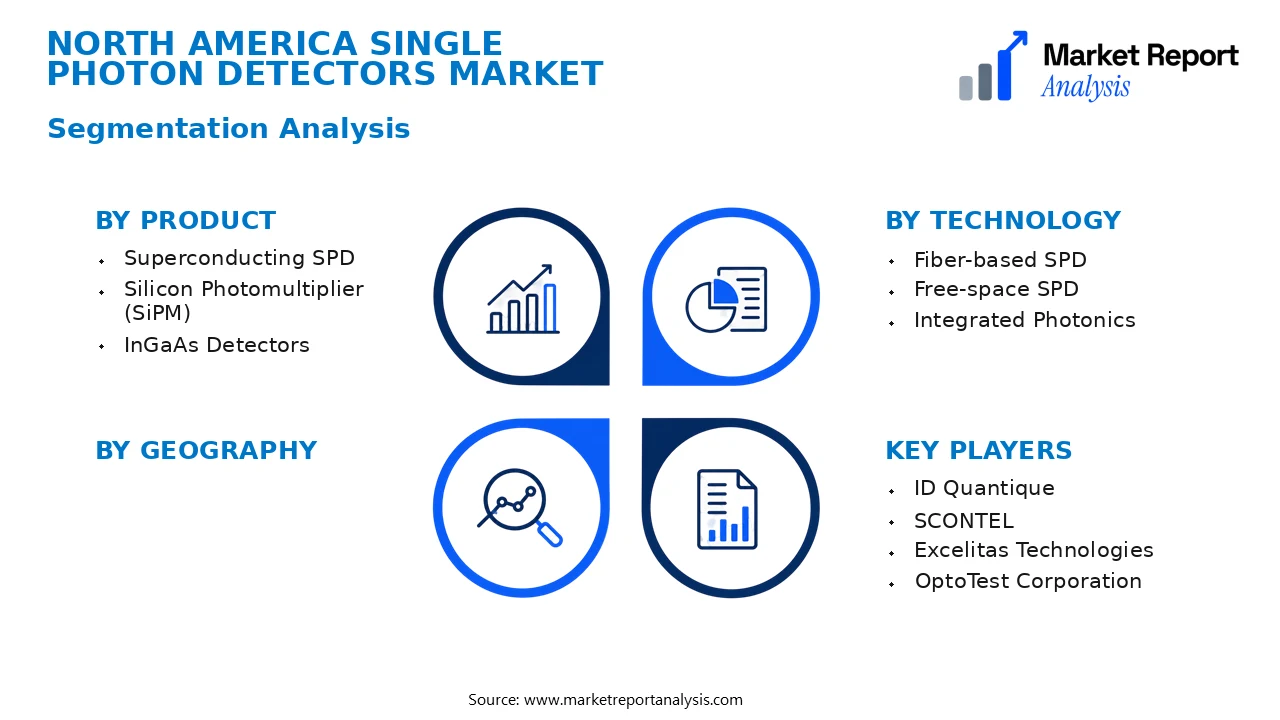
- Product
- Superconducting SPD: This high-performance category utilizes superconducting materials to significantly reduce dark counts and enhance detection efficiency. It is mainly adopted in quantum computing and scientific research, demanding advanced cooling solutions and high sensitivity.
- Silicon Photomultiplier (SiPM): These compact and cost-effective detectors are favored in medical imaging and LIDAR systems for their high gain and fast response times, driving demand across commercial and industrial sectors.
- InGaAs Detectors: Primarily used for fiber-optic communication and quantum key distribution, these detectors excel in the near-infrared spectrum and are valued for their efficiency in telecommunication applications.
- Technology
- Fiber-based SPD: This technology integrates with fiber-optic networks, enabling efficient photon detection in long-distance quantum communication and telecom signaling applications.
- Free-space SPD: Suited for applications in atmospheric science and satellite communications, free-space detectors operate in open air and require robust, sensitive components capable of managing environmental exposure.
- Integrated Photonics: Emerging as a promising platform, integrated photonic SPD combines detection with on-chip photonics, supporting scalable quantum computing and secure communication systems.
- Application
- Quantum Computing: Single photon detectors are critical in this domain for transmitting and measuring quantum information, thereby supporting advancements in secure communications and quantum simulations.
- Medical Imaging: In applications such as Positron Emission Tomography (PET), these detectors improve image resolution and sensitivity, consequently expanding their adoption in hospitals and diagnostic centers.
- Telecommunications: SPD enhances fiber-optic network performance by enabling ultra-secure data transmission and higher data rates, influencing the infrastructure upgrades across North American telecom providers.
- Scientific Research: Fundamental physics experiments and research institutions use SPDs for precise measurement of photons, contributing to breakthroughs in quantum mechanics and particle physics.
Competitive Intelligence
The North America Single Photon Detectors Market exhibits moderate competition marked by several key players utilizing innovative strategies to enhance market positioning. Dominant corporations focus on product differentiation through technological innovation, particularly in improving efficiency and reducing noise levels in photon detection. Market concentration remains relatively balanced, with leading players such as ID Quantique, Thorlabs, and Excelitas Technologies holding significant market shares, but smaller firms also actively innovate to capture niche segments. Strategic partnerships and collaborative ventures are prevalent, enabling firms to expand their technological capabilities and penetrate diverse application areas like quantum computing, biophotonics, and LIDAR systems. Acquisitions are indicative of growth ambitions, with larger firms acquiring startups to integrate advanced R&D developments swiftly. Firms are heavily investing in R&D to differentiate their products via enhanced sensitivity, miniaturization, and integration capabilities. Additionally, companies are expanding their manufacturing footprints across North America to ensure supply chain resilience and meet rising demand. Overall, competition drives continuous product innovation and strategic alliances, fostering a dynamic marketplace focused on technological leadership and market expansion.
Leading Company Profiles
The competitive landscape in North America features a diverse mix of innovative companies specializing in photodetector design, manufacturing, and integration. These firms leverage cutting-edge semiconductor processes, sophisticated cryogenic systems, and advanced signal processing techniques to develop high-performance single photon detection solutions tailored for multiple high-growth applications.
- ID Quantique
- SCONTEL
- Excelitas Technologies
- OptoTest Corporation
- Photonis Quantum
- Lasertel
- IDEX Corporation
- Picoquant
ID Quantique
ID Quantique specializes in quantum security and single photon detectors, offering high-efficiency, low-noise SPDs that serve quantum encryption and secure communication markets, with ongoing innovations in integration and miniaturization for commercial applications.
SCONTEL
SCONTEL develops advanced superconducting nanowire single photon detectors (SNSPDs), focusing on ultra-sensitive applications in quantum computing and fundamental physics, supported by strategic collaborations with academic institutions for R&D advancements.
Excelitas Technologies
Excelitas delivers a broad portfolio of photonic solutions, including silicon-based SPDs designed for biomedical imaging, LIDAR, and aerospace sectors, emphasizing reliability, scalability, and integration capabilities across diverse environments.
OptoTest Corporation
OptoTest specializes in optical testing and characterization equipment, providing innovative testing modules for single photon detector performance, calibration, and quality control, primarily serving research laboratories and manufacturing facilities.
Photonis Quantum
Photonis Quantum focuses on high-performance photon detection for scientific and industrial applications, developing microchannel plate (MCP) and avalanche photodiode-based SPDs, with strategic investments in improving timing resolution and sensitivity.
Lasertel
Lasertel manufactures high-power laser sources and integrates photonic sensors, including SPDs, for industrial, defense, and scientific applications, emphasizing innovation in laser-photon detection synergy for enhanced system performance.
IDEX Corporation
IDEX Corporation offers advanced detection and measurement systems, including single photon avalanche diodes (SPADs) integrated into sensor modules used in spectroscopy, quantum optics, and environmental monitoring.
Picoquant
Picoquant develops time-resolved single photon counting modules and detectors, targeting applications in biomedical research and quantum optics, with a focus on increasing timing accuracy and photon detection efficiency.
Strategic Business Developments

- August 2023 – Excelitas Technologies – Launched new high-efficiency Silicon SPDs – Enhances product portfolio for medical imaging and environmental monitoring, expanding market reach.
- May 2023 – ID Quantique – Invested in quantum encryption R&D facility – Strengthens leadership in quantum secure communication solutions with advanced SPD integration.
- June 2023 – OptoTest Corporation – Expanded manufacturing capacity for optical testing systems – Increases production volume, reducing lead times for customer orders in research sectors.
- April 2024 – Photonis Quantum – Announced partnership with major university – Focused on improving MCP-based SPDs, accelerating innovation for scientific applications.
- January 2024 – IDEX Corporation – Acquired a startup specializing in cryogenic photon sensors – Broadens technological expertise and product offerings in quantum sensing markets.
Frequently Asked Questions
What is the North America Single Photon Detectors Market?
The North America Single Photon Detectors Market encompasses advanced photodetection devices capable of detecting individual photons, essential for quantum computing, medical imaging, and secure communication applications. This market includes various detector types like SNSPDs and APDs, serving sectors across the region.
What is the current market size of North America Single Photon Detectors Market?
As of 2026, the market valuation for North America Single Photon Detectors is estimated at approximately USD 1.2 Billion, reflecting rapid technological adoption and expanding application areas in quantum technologies and healthcare sectors, with expected growth driven by innovation and regional investments.
What factors are driving the North America Single Photon Detectors Market?
Market growth is fueled by advancements in quantum computing, rising demand for high-precision medical imaging, increasing investments in R&D, and the decreasing cost of detector production. Moreover, increasing adoption in secure communications and defense systems amplifies the sector’s expansion.
Which region dominates the North America Single Photon Detectors Market?
The United States leads the North American market owing to its strong technological infrastructure, significant R&D investments, and prominent presence of key industry players. Canada also contributes notably through research initiatives and growing tech adoption, but the U.S. remains predominant.
Which segment is expected to grow the fastest?
The superconducting nanowire single-photon detectors (SNSPDs) segment is projected to witness the fastest growth, driven by their superior sensitivity and faster response times, vital for quantum computing and secure communication applications across North America.
Who are the leading companies operating in the North America Single Photon Detectors Market?
Major players include companies such as Hamamatsu Photonics, ID Quantique, Thorlabs, and NIST. These organizations focus on innovation, expanding product portfolios, and strategic collaborations to strengthen their market position and cater to growing regional demand.
Analyst Perspective
The North America Single Photon Detectors Market exhibits a mature landscape, yet significant growth opportunities persist, driven by advances in quantum computing, deepening adoption in biomedical imaging, and expanding applications in secure communications. The long-term outlook remains optimistic as technological innovations, such as superconducting nanowire and avalanche photodiodes, continue to enhance detection efficiency and reduce costs, fostering widespread deployment. Commercial opportunities are primarily concentrated in high-value segments like quantum key distribution and LIDAR for autonomous vehicles, incentivizing increased R&D investments. Regional growth remains robust due to North America's strong technological infrastructure and supportive government initiatives, especially in the U.S. and Canada. However, competitive intensity is rising as established firms and startups invest heavily in innovation. Strategic focus on IP development, scalable manufacturing, and strategic partnerships will be crucial for maintaining a competitive edge. Long-term success depends on balancing technological evolution with regulatory landscape shifts and global supply chain considerations, positioning North America as a pivotal hub in the single photon detectors ecosystem.
