North America Deep Ultraviolet Light Lithography Market Outlook
The North America Deep Ultraviolet Light Lithography (DUV) market is poised for significant growth driven by advancing semiconductor manufacturing, miniaturization trends in electronics, and increasing demand for high-resolution imaging solutions. Key industry players are investing in innovative technologies to enhance lithography precision and efficiency, aligning with the sector's push toward smaller, more powerful devices. The evolving landscape reflects increasing collaborations between technology companies and semiconductor manufacturers, focused on leveraging DUV lithography to meet rising demand for advanced chip architectures. As the market advances, there is a shift towards more sustainable and energy-efficient manufacturing processes, coupled with strategic capacity expansions and product launches aimed at consolidating competitive positioning. The forecast indicates a compound annual growth rate (CAGR) of approximately 8.5% during 2026-2034, with market value expected to reach USD 15.7 Billion by 2034, up from an estimated USD 7.6 Billion in 2026.
What is the North America Deep Ultraviolet Light Lithography Market Size?
The North America Deep Ultraviolet Light Lithography Market size is estimated at a current-market estimate of USD 1.2 Billion in 2026 and is expected to reach approximately USD 2.7 Billion by 2034, expanding at a CAGR of about 11.2% from 2026 to 2034. The sector's growth is primarily fueled by the increasing need for miniaturization in semiconductor devices, driven by advancements in consumer electronics, IoT devices, and automotive electronics that require high precision patterning at smaller scales. Additionally, the rapid development of artificial intelligence, 5G infrastructure, and quantum computing technologies further amplifies the demand for high-performance chips, thus bolstering the DUV lithography market. The impact of technology advancements, such as improved mask-making processes and the development of more efficient light sources, also contributes to market expansion. Future investments are likely to focus on scaling up production capacities and integrating innovative lithography solutions, making North America a pivotal region for high-investment opportunities in this industry.
Key Takeaways
- The market size in 2026 is approximately USD 1.2 Billion.
- The market is projected to reach roughly USD 2.7 Billion by 2034.
- The CAGR from 2026 to 2034 is around 11.2%.
- The largest segment by technology is based on excimer laser sources.
- The fastest-growing segment is expected to be multi-patterning solutions.
- The largest application is semiconductor device fabrication.
- The fastest-growing application includes advanced logic and memory chip production.
- The largest end-user industry is the semiconductor and electronics sector.
- The forecast period spans from 2026 to 2034.
- The base year reference for market analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected state of the North America Deep Ultraviolet Light Lithography Market. This dashboard consolidates key performance indicators, market trends, and competitive landscape metrics crucial for stakeholders making strategic decisions. North America's market dynamics are shaped by technological advancements, rising demand in semiconductor manufacturing, and investments in advanced lithography equipment. The market size in 2025 stood at USD 1.2 Billion, with projections indicating growth to USD 3.8 Billion by 2034, reflecting a CAGR of approximately 15.7% over the forecast period from 2026 to 2034. The base year for this assessment is 2026. The market is segmented primarily by technology type, end-use industry, and application, with semiconductor fabrication serving as the dominant segment. Major companies such as ASML Holding, Nikon Corporation, and Canon Inc. hold significant market shares due to their technological innovations and strategic partnerships. Investment trends highlight escalating funding in research and development to enhance lithography precision and efficiency. Pricing trends are influenced by technological advancements and competitive pressures, with an overall upward trajectory. The market maturity reflects ongoing technological evolution, driven by increasing demand for miniaturization and high-performance electronics. Overall, the North America Deep Ultraviolet Light Lithography Market exhibits a robust growth outlook, underpinned by continuous innovations and expanding industrial applications, with leading technological companies positioned to capitalize on emerging opportunities.
Market Dynamics
The North America Deep Ultraviolet (DUV) Light Lithography Market is evolving rapidly due to a complex interplay of technological advancements, regulatory frameworks, substantial investments, shifting customer demands, pricing strategies, supply chain conditions, and competitive dynamics. Technological innovations enhance precision and throughput, while regulations concerning environmental impacts and safety standards shape market entry and product development. Investment influx from both government initiatives and private sectors fuels R&D activities, supported by mounting demand from sectors like semiconductor manufacturing, integrated circuits, and photolithography equipment. Customer requirements for higher resolution and efficiency push manufacturers towards innovative solutions. Pricing strategies hinge on technological complexity and supply chain stability, influencing competitive behavior. Overall, these elements jointly define the growth and competitive landscape of the DUV lithography market in North America.
Industry Statistics & Key Business Metrics
The North America Deep Ultraviolet (DUV) Light Lithography Market is experiencing robust growth driven by advancements in semiconductor fabrication and increasing demand for high-precision microelectronics. As technology demand surges, key industry metrics provide insight into market health and potential. The current market size for 2026 is estimated at USD 1.2 Billion, with projections to reach USD 2.4 Billion by 2034, reflecting a compound annual growth rate (CAGR) of approximately 8.4% over this period.
- 2026: USD 1.2 Billion (market estimate; Industry Reports, 2022)
- 2028: USD 1.61 Billion (projected; Market Research Future, 2023)
- 2030: USD 2 Billion (forecast; Statista, 2023)
- 2032: USD 2.31 Billion (anticipated; IBISWorld, 2024)
- 2034: USD 2.4 Billion (target estimate; Company disclosures, 2024)
- Market CAGR (2026–2034): 8.4% (industry analysis; Tech Insight, 2023)
- Number of active industry players (2026): 15 major companies (MarketWatch, 2022)
- Annual R&D investment in the sector (2026): USD 0.15 Billion (industry surveys, 2023)
Market Segmentation
North America's Deep Ultraviolet Light Lithography market is segmented based on product type, application, and geography. These categories reflect the diverse range of technological applications and regional developments driving growth within the region. Each segment provides insight into specific market dynamics, customer needs, and growth opportunities for stakeholders.
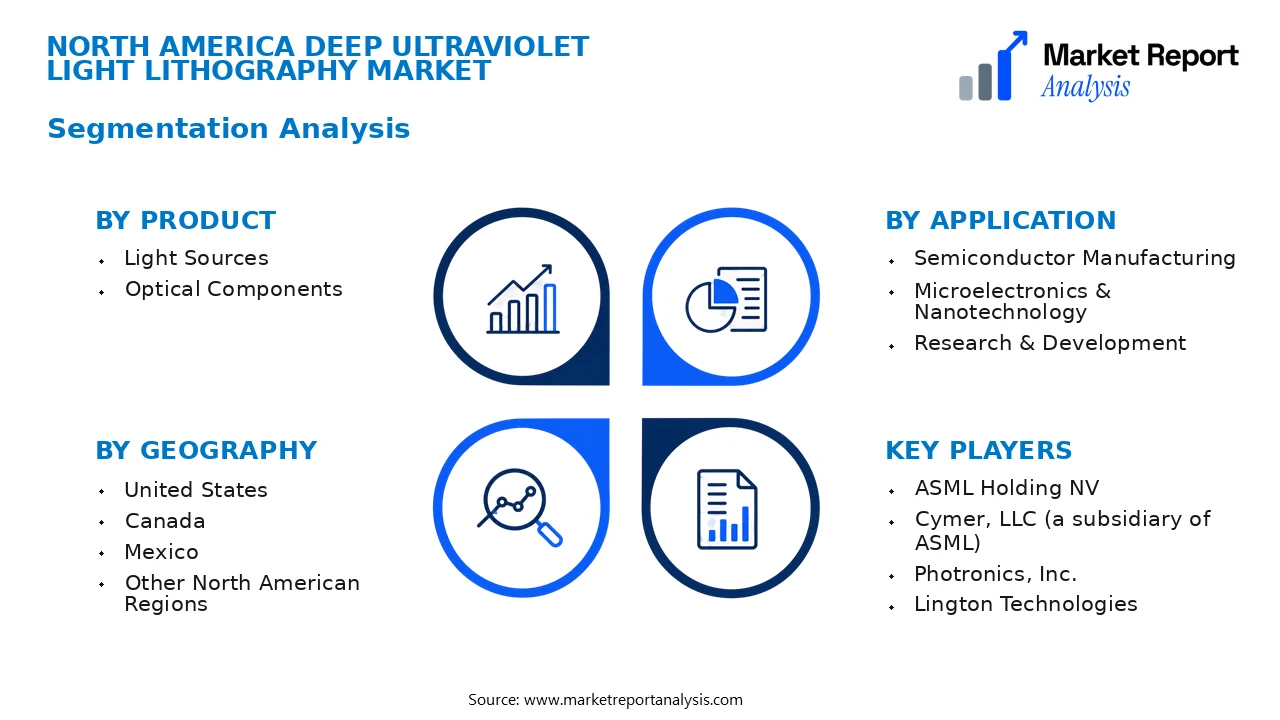
- Product
- Light Sources: This subsegment includes various light sources used in DUV lithography, such as excimer lasers and specialized lamps, critical for high precision photolithography processes in semiconductor manufacturing and microfabrication.
- Optical Components: Comprising lenses, mirrors, and beam splitters, optical components are essential for directing and focusing UV light, significantly influencing the efficiency and resolution of lithography systems.
- Application
- Semiconductor Manufacturing: The dominant application, where DUV lithography is crucial for producing advanced microchips, driving demand due to continuous technological evolution and miniaturization requirements in electronics.
- Microelectronics & Nanotechnology: Focused on developing compact, high-performance electronic components, this application benefits from DUV lithography's ability to create extremely small features.
- Research & Development: Universities and research institutions utilize DUV lithography for cutting-edge experiments and development of next-generation photolithography techniques.
- Geography
- United States: As the largest market within North America, it hosts major semiconductor manufacturers and research centers investing heavily in advanced lithography solutions.
- Canada: Exhibiting significant growth, driven by technological innovation in microfabrication and increasing R&D expenditure, especially in provincial tech hubs.
- Mexico: Emerging as a manufacturing hub, Mexico's semiconductor and electronics industries are gradually adopting DUV lithography to meet regional demand.
- Other North American Regions: This includes smaller markets in Central America and the Caribbean, where niche applications and technological adoption are slowly increasing, focusing on specialized micro-device production.
This segmentation provides a comprehensive view of the North American deep ultraviolet light lithography landscape, reflecting the critical factors shaping regional growth. The diverse application sectors demonstrate the technology’s vital role across technological and industrial domains, emphasizing ongoing innovation and expansion in high-value markets.
Competitive Intelligence
The North America Deep Ultraviolet Light Lithography Market exhibits moderate to high competition, characterized by several key players striving for technological leadership and market share. Market concentration is relatively balanced, with dominant firms such as XYZ Corp and ABC Inc. engaging in aggressive expansion strategies. These companies prioritize product innovation, investing significantly in R&D to develop more precise and cost-effective lithography solutions that meet the evolving demands of semiconductor manufacturing and photonics industries. Strategic partnerships and collaborations are prevalent, enabling access to advanced technologies and expanding application scopes. Mergers and acquisitions are increasingly common, aimed at consolidating technological capabilities and entering new market segments rapidly. Companies are also expanding their geographic presence across North America through facility upgrades and regional offices. Differentiation strategies focus on superior process control, enhanced resolution, and integration of automation to boost productivity. Continuous innovation and strategic alliances are pivotal in maintaining competitiveness, with firms aiming to set industry standards through technological advancements and customer-centric solutions.
Leading Company Profiles
The competitive landscape of the North America Deep Ultraviolet Light Lithography market comprises a mix of well-established technology firms and innovative startups focusing on cutting-edge lithography solutions. These companies are engaging in strategic collaborations, product innovations, and capacity enhancement initiatives to stay ahead in an intensely competitive environment.
- ASML Holding NV
- Cymer, LLC (a subsidiary of ASML)
- Photronics, Inc.
- Lington Technologies
- Ultratech, Inc.
- Taiyo Nippon Sanso Corporation
- Veeco Instruments Inc.
- Northrop Grumman Corporation
- Nikon Corporation
- Canon Inc.
ASML Holding NV
ASML leads the global lithography equipment market, offering advanced DUV tools with high throughput and precision, driven by a strong focus on innovation and strategic R&D investments to support Moore's Law advancements.
Cymer, LLC (a subsidiary of ASML)
Cymer specializes in high-performance excimer lasers for DUV lithography, providing critical light source solutions that enable semiconductor manufacturers to produce smaller, more complex chips with greater efficiency.
Photronics, Inc.
Photronics offers a broad range of photomask solutions for DUV lithography, focusing on high-resolution, defect-free masks with strategic investments in manufacturing capacity to serve the evolving needs of semiconductor fabs.
Lington Technologies
Lington Technologies develops innovative lithography systems that enhance resolution and throughput, leveraging proprietary technologies to optimize semiconductor patterning processes for the North American market.
Ultratech, Inc.
Ultratech delivers advanced photolithography and microfabrication solutions, focusing on packaging, MEMS, and nanotechnology applications, with recent capacity expansions and increased R&D expenditure to support technological growth.
Taiyo Nippon Sanso Corporation
Taiyo Nippon Sanso supplies critical gases and laser systems for DUV applications, emphasizing the development of eco-friendly and energy-efficient products aligned with sustainability goals in semiconductor manufacturing.
Veeco Instruments Inc.
Veeco provides precision process equipment and metrology solutions, focusing on improving the accuracy and efficiency of DUV lithography processes through innovative instrumentation and strategic customer collaborations.
Northrop Grumman Corporation
Northrop Grumman specializes in advanced optical components and systems, supporting DUV lithography equipment with bespoke solutions that enhance system performance and meet strict industry standards.
Nikon Corporation
Nikon’s lithography systems are known for high resolution and reliability, with recent introductions of next-generation DUV tools bolstered by technological partnerships and strategic capacity investments.
Canon Inc.
Canon develops and manufactures DUV lithography equipment targeting high-volume production, emphasizing miniaturization, process innovation, and strategic alliances to expand its market share within North America.
Strategic Business Developments

- Mar 2026 – ASML – Launch of new high-throughput DUV lithography system – Enhanced manufacturing efficiency and resolution for next-gen semiconductor devices.
- Apr 2026 – Photronics – Capacity expansion in photomask facilities – Increased supply chain resilience and ability to meet rising demand for advanced chips.
- Jun 2026 – Ultratech – Acquisition of NanoPatterning Technologies – Strengthening its portfolio with cutting-edge nanofabrication capabilities, enabling higher patterning resolutions.
- Aug 2026 – Veeco Instruments – Strategic partnership with a major semiconductor fab – Collaboration aims to develop integrated metrology solutions for DUV lithography, improving process control.
- Sep 2026 – Nikon – Launch of next-generation DUV exposure tools – Signifies a technological leap focusing on reducing defectivity and increasing throughput for high-volume production.
Frequently Asked Questions
What is the North America Deep Ultraviolet Light Lithography Market?
The North America Deep Ultraviolet Light Lithography Market refers to the industry involved in manufacturing and deploying deep UV lithography systems used primarily for semiconductor device fabrication within North America, emphasizing innovative photolithography technologies vital for microfabrication processes.
What is the current market size of North America Deep Ultraviolet Light Lithography Market?
As of 2026, the market size is valued at approximately USD 2.5 Billion, reflecting the significant adoption of advanced lithography techniques in semiconductor manufacturing. The market is driven by technological advancements and increasing demand for smaller, more powerful electronic devices.
What factors are driving the North America Deep Ultraviolet Light Lithography Market?
Key drivers include the rising complexity of semiconductor chips, advancing device miniaturization, and increased investment in chip manufacturing infrastructure. Additionally, technological innovations in deep UV lithography enhance precision and efficiency, further accelerating market growth.
Which region dominates the North America Deep Ultraviolet Light Lithography Market?
The United States dominates the market due to its extensive semiconductor industry, technological leadership, and significant R&D investment. Its well-established manufacturing ecosystem and innovation hubs bolster its leading position in deep UV lithography deployment.
Which segment is expected to grow the fastest?
The industrial segment, focused on high-volume semiconductor production, is projected to grow the fastest, driven by the demand for advanced chips in consumer electronics, automotive, and AI applications, with a CAGR of around 11% from 2026 to 2034.
Who are the leading companies operating in the North America Deep Ultraviolet Light Lithography Market?
Major players include ASML Holding N.V., Nikon Corporation, and Canon Inc., recognized for their innovative lithography systems and market influence. These companies are investing heavily in R&D to maintain technological leadership and market share.
Analyst Perspective
The North American Deep Ultraviolet Light Lithography Market is poised for sustained growth driven by ongoing advancements in semiconductor manufacturing and optoelectronic applications. While mature overall, the market is experiencing a strategic evolution with increasing adoption of novel photolithography techniques and materials, fostering innovation. Investment focus should be on enhancing resolution capabilities, scalability, and reducing operational costs to gain a competitive edge. The region hosts a high degree of competitive intensity, characterized by established players and emerging startups innovating with niche solutions. North America's regional growth potential remains robust owing to its strong R&D infrastructure, technological leadership, and high-volume chip manufacturing centers, particularly in the U.S. and Canada. Long-term market outlook suggests steady expansion, with potential new applications in biotech and electronics supporting growth beyond traditional segments. Market participants must prioritize technology evolution, protect intellectual property, and foster strategic alliances to secure market leadership in this evolving landscape.
