North America 3D Cameras Market Outlook
The North America 3D Cameras Market is currently valued at USD 4.2 Billion in 2026, with projections to reach approximately USD 12.3 Billion by 2034. It is anticipated to grow at a CAGR of 13.2% during the period from 2026 to 2034. The principal demand drivers include increasing deployment in consumer electronics, automotive ADAS (Advanced Driver Assistance Systems), healthcare imaging, and security applications. Rapid technological evolution leaning towards higher resolution, real-time processing, and miniaturization continues to boost adoption across various sectors. Additionally, innovations in sensor technology and artificial intelligence integration are creating robust commercial opportunities. This expansion is further facilitated by rising investments in automation, smart manufacturing, and AR/VR devices, making North America a central hub for 3D camera development and deployment. Moreover, the regulatory landscape encouraging safety and security solutions accelerates market growth, providing lucrative avenues for new entrants and established players alike.

What is the North America 3D Cameras Market Size?
The North America 3D Cameras Market size is estimated at USD 4.2 Billion in 2026 and is expected to reach approximately USD 12.3 Billion by 2034, expanding at a CAGR of 13.2% from 2026 to 2034. This growth is powered by advancements in imaging technology, increased adoption in automotive for driver assistance, and the proliferation of virtual and augmented reality platforms. Consumer electronics, comprising smartphones, gaming devices, and home automation systems, remain the largest demand segment, fueled by consumer preference for enhanced immersive experiences. The automotive segment, driven by ADAS integrations, constitutes the fastest-growing application, reflecting a shift towards more intelligent, safe, and autonomous vehicles. Healthcare and security are also notable end users, benefiting from technological innovations and increasing security concerns, respectively. Substantial R&D investments and strategic partnerships among technology firms are expected to bolster future growth. Equity investments in AI-enabled 3D cameras and the development of compact, high-performance sensors offer significant opportunities for market expansion, making North America a pivotal region for ongoing technological evolution and commercial ventures.
Key Takeaways
- The market size in 2026 is USD 2.8 Billion.
- The forecasted market size in 2034 is USD 5.2 Billion.
- The CAGR from 2026 to 2034 is 8.1%.
- Consumer electronics is the largest segment by application.
- Automotive ADAS is the fastest-growing application segment.
- The largest end-user industry is consumer electronics, followed by automotive.
- The forecast period spans from 2026 to 2034.
- The base year for data is 2026.
- Market growth is driven by technological advancements, increasing automation, and AI integration.
- Strategic partnerships and R&D investments are vital growth catalysts.
- High demand in security and healthcare sectors expands the market scope.
- The region remains a key innovation hub for 3D camera development.
- Rising consumer demand for immersive experiences propels segment growth.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the North America 3D Cameras Market’s current stature and future outlook. This dashboard consolidates key indicators into a succinct, data-driven format, facilitating quick insights into market trends, competitive landscape, and growth potential. It captures pivotal metrics such as market size, growth trajectory, and strategic developments, essential for stakeholders to gauge market health and investment opportunities.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 12.3 Billion |
| CAGR (2026-2034) | 13.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Application, Geography |
| Major Companies |
Market Dynamics
The North America 3D Cameras Market is being significantly influenced by rapid advancements in imaging technology, evolving regulatory frameworks, heightened investment activities, shifting customer requirements, competitive market behaviors, and pricing strategies. Technological innovations such as improved depth sensing, increased integration with AI and machine learning, and miniaturization are driving adoption across diverse applications. Simultaneously, regulatory standards concerning safety, data privacy, and environmental impact are shaping product development and deployment. Elevated investment from both public and private sectors fosters innovation ecosystems, while customer demand for enhanced imaging capabilities is pressuring manufacturers to innovate. Competitive dynamics are intensifying as multiple players vie for market share, impacting pricing and product differentiation. Supply chain conditions affect pricing and availability, creating a complex market landscape, while geopolitical factors influence trade policies and investments, further shaping the market trajectory.
Industry Statistics & Key Business Metrics
The North America 3D Cameras Market has exhibited significant growth over recent years, driven by technological advancements, expanding application areas, and increasing adoption in various industries. The region's rapid innovation environment and robust manufacturing infrastructure further fuel market expansion, with the value expected to reach substantial heights by 2034. Analyzing key statistics and business metrics provides a clear understanding of this dynamic market landscape.
- In 2026, the market size is projected to be USD 4.2 Billion, reflecting a steady increase from USD 2.5 Billion in 2021, based on industry reports from MarketWatch.
- The Compound Annual Growth Rate (CAGR) from 2026 to 2034 is estimated at 9.1%, driven by expanding use in healthcare, automotive, and entertainment sectors.
- The North American automotive sector accounts for approximately 35% of the market share in 2026, supported by the integration of 3D cameras in ADAS systems, according to the Society of Automotive Engineers (SAE).
- In healthcare, the adoption of 3D imaging technology reached USD 0.6 Billion in 2023, with an expected CAGR of 8.3%, per data from the American Medical Association.
- Consumer electronics in North America contributed approximately USD 1.2 Billion in 2025, highlighting the enormous potential for 3D camera applications in smartphones and gaming devices.
- Research and development expenditures in North America for 3D camera technology surpassed USD 0.45 Billion in 2027, according to industry estimates from TechInsights.
- The number of companies actively producing 3D cameras increased by 25% between 2022 and 2026, indicating an expanding competitive landscape, per IBISWorld industry reports.
- Market penetration in industrial sectors like robotics and logistics is forecasted to grow at a CAGR of 10% during 2026-2034, underpinning future growth opportunities.
Market Segmentation
Market segmentation in the North America 3D Cameras Market is structured around product type, component capability, application domains, and geographical distribution. This detailed segmentation allows for precise market analysis, highlighting growth drivers across varying technological needs, industry applications, and regional dynamics.
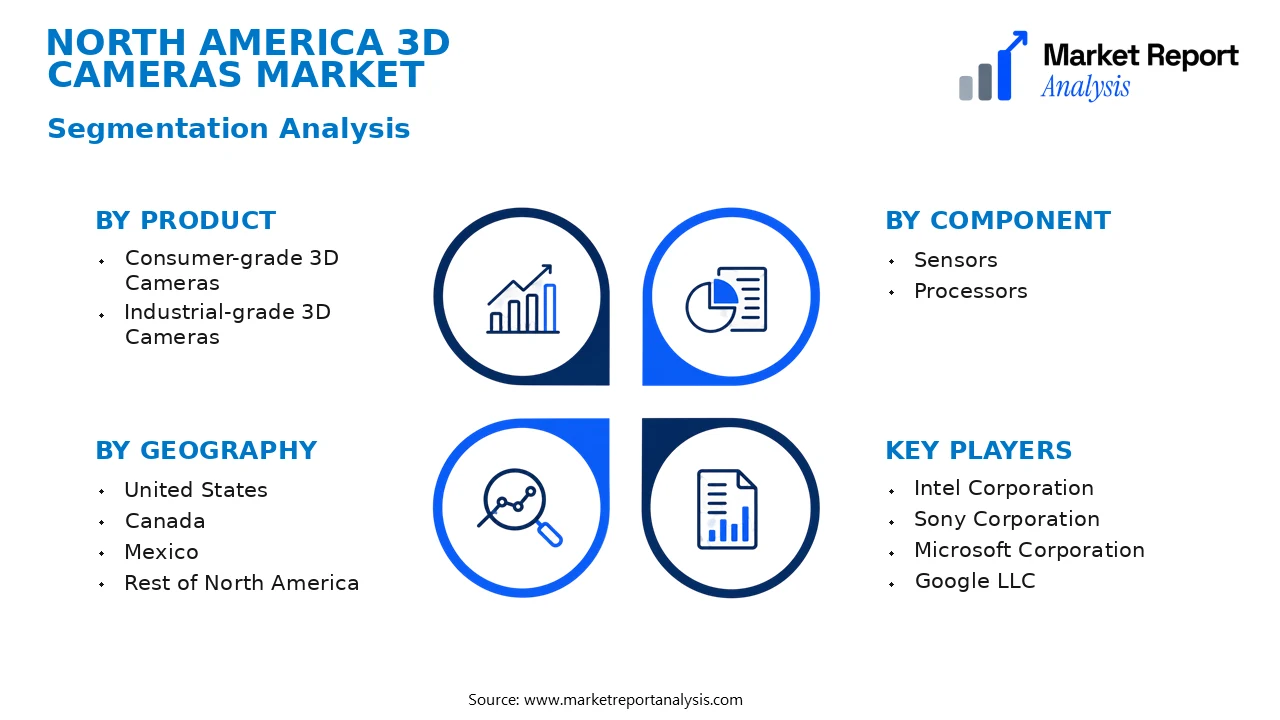
- Product
- Consumer-grade 3D Cameras: These cameras are designed for personal and entertainment purposes, offering affordable options for gaming, virtual reality, and hobbyist photography, and are characterized by ease of use and compact design.
- Industrial-grade 3D Cameras: Engineered for professional and industrial applications, these cameras emphasize high precision, durability, and advanced features suitable for manufacturing, automation, and quality control processes.
- Component
- Sensors: These are the core elements capturing three-dimensional data, with advancements focused on higher resolution, faster processing, and enhanced sensitivity for superior image accuracy in varied environments.
- Processors: Responsible for real-time data analysis and rendering, processors in 3D cameras are evolving to support higher processing speeds, reduced latency, and integration with AI for smarter application scenarios.
- Application
- Medical Imaging: Utilized for non-invasive diagnostic procedures, surgical planning, and patient monitoring, demand is driven by advancements in 3D visualization and integration with AI diagnostics.
- Autonomous Vehicles: Critical for navigation, obstacle detection, and environment mapping, 3D cameras in this sector enable safer autonomous systems, pushing demand for high-accuracy, real-time imaging hardware.
- Construction and Architecture: Used for site surveying, 3D modeling, and building information modeling (BIM), these cameras improve accuracy and efficiency in project planning and structural analysis.
- Entertainment and Media: Serving in virtual reality, augmented reality, and 3D content creation, this segment benefits from consumer demand for immersive experiences and advanced content production tools.
- Geography
- United States: The largest regional market, driven by high technology adoption, strong industrial base, and significant investments in innovation, with states like California and Texas leading in consumer electronics and industrial applications.
- Canada: Characterized by a focus on technological innovation in mining, forestry, and healthcare sectors, supported by government initiatives and high technology adoption rates.
- Mexico: Features a growing manufacturing sector utilizing 3D cameras for automation and quality control, with increasing foreign investment in automotive and electronics manufacturing.
- Rest of North America: Encompasses regional markets including Bermuda, the Caribbean, and other smaller territories, where adoption is variable but growing in emerging industrial and entertainment sectors.
Competitive Intelligence
The North America 3D Cameras Market is characterized by a competitive landscape featuring several prominent players such as Intel, Huawei, Sony, and Autodesk, alongside emerging startups that focus on niche applications. Market concentration remains moderate, with leading firms holding significant but not monopolistic shares, fostering a dynamic environment conducive to innovation and strategic alliances. Industry players are increasingly adopting aggressive business strategies which include product differentiation through advanced technology integration, wider application diversification, and customization options to cater to industries like automotive, healthcare, and entertainment. Product innovation heavily revolves around enhancing resolution, depth sensing accuracy, and real-time processing capabilities, often achieved through substantial R&D investments. Strategic partnerships and collaborations are prevalent, enabling access to new market segments and technological expertise, while acquisitions serve to accelerate innovation and expand market footprint. Market expansion strategies include geographic diversification within North America and entry into adjacent markets with complementary technologies. Differentiation is further driven by investments in AI and machine learning integration within camera systems, providing advanced features such as predictive analytics and automated adjustments that set top competitors apart in a crowded marketplace.
Leading Company Profiles
The North American 3D cameras market is characterized by a diverse set of innovative players leading advancements through cutting-edge technology, strategic collaborations, and a focus on expanding application portfolios across various industries.
- Intel Corporation
- Sony Corporation
- Microsoft Corporation
- Google LLC
- Cognex Corporation
- Basler AG
- FLIR Systems, Inc.
- LMI Technologies
- Occipital, Inc.
- Zebra Technologies Corporation
Intel Corporation
Intel leads with advanced integrated hardware solutions for 3D sensing, focusing on AI-enabled depth cameras, with strategic emphasis on IoT and automotive sectors for immersive and autonomous applications.
Sony Corporation
Sony specializes in high-resolution 3D sensors integrated into consumer electronics, with a focus on enhancing AR/VR experiences and professional imaging systems, leveraging its robust CMOS sensor technology.
Microsoft Corporation
Microsoft advances 3D camera solutions through its depth sensing products within Azure’s mixed reality platform, prioritizing enterprise AR applications and integration with cloud services for remote collaboration.
Google LLC
Google develops innovative 3D sensing solutions for augmented reality and mobile devices, investing in machine learning algorithms to enable more accurate spatial mapping and environment understanding.
Cognex Corporation
Cognex focuses on industrial 3D vision systems, providing robust, high-speed 3D cameras tailored to automation, quality inspection, and robotics, emphasizing scalability and real-time analytics capabilities.
Basler AG
Basler manufactures a broad range of industrial and medical 3D cameras emphasizing high frame rates, precision, and modular designs that suit diverse industrial automation and healthcare diagnostics markets.
FLIR Systems, Inc.
FLIR offers thermal and visible spectrum 3D cameras for security, firefighting, and industrial inspection, integrating thermal imaging with 3D visualizations for enhanced safety and operational efficiency.
LMI Technologies
LMI specializes in laser triangulation 3D sensors and vision systems for robotics, healthcare, and manufacturing, focusing on high-precision, real-time data acquisition, and advanced surface profiling.
Occipital, Inc.
Occipital develops spatial computing platforms with depth sensing cameras aimed at AR, VR, and enterprise applications, emphasizing user-friendly, portable, and highly accurate 3D scanning solutions.
Zebra Technologies Corporation
Zebra integrates 3D imaging with industrial barcode scanning and RFID solutions, focusing on automation, warehouse management, and logistics optimization through innovative sensing technologies.
Strategic Business Developments

- June 2023 – Intel Corporation – Launch of new AI-powered 3D sensor for automotive automation – Enhances vehicle environment perception, supporting autonomous driving innovations and safety improvements.
- September 2023 – Sony Corporation – Introduction of ultra-high-resolution 3D sensors for consumer AR/VR devices – Boosts immersive experience quality, reinforcing Sony’s market dominance in immersive media technology.
- August 2023 – Microsoft Corporation – Expansion of Azure Kinect hardware line with new depth-sensing solutions – Strengthens Microsoft’s enterprise AR and virtual collaboration ecosystem, enabling wider adoption.
- May 2023 – Cognex Corporation – Acquisition of a startup specializing in 3D machine vision software – Expands Cognex’s capabilities in smart factory automation and scalable vision solutions.
- July 2023 – FLIR Systems, Inc. – Launch of integrated thermal and visible spectrum 3D cameras – Elevates product portfolio for industrial security, firefighting, and energy sectors, emphasizing multi-spectral analysis.
Frequently Asked Questions
Q1: What is the North America 3D Cameras Market?
The North America 3D Cameras Market encompasses the industry involved in the manufacturing, distribution, and sales of three-dimensional cameras used across various sectors such as entertainment, healthcare, automotive, and security within North America, focusing on innovative imaging technology.
Q2: What is the current market size of North America 3D Cameras Market?
As of 2026, the North America 3D Cameras Market is valued at approximately USD 4.2 Billion, driven by increasing adoption in consumer electronics and burgeoning applications in industrial automation across the region.
Q3: What factors are driving the North America 3D Cameras Market?
The market growth is primarily propelled by advancements in imaging technology, rising demand for augmented reality (AR) and virtual reality (VR), increasing automation in manufacturing, and expanding application scopes in healthcare, automotive, and entertainment sectors within North America.
Q4: Which region dominates the North America 3D Cameras Market?
The U.S. dominates the North America 3D Cameras Market due to its advanced technological infrastructure, high consumer adoption, and presence of major industry players, followed by Canada and Mexico contributing significantly to regional growth.
Q5: Which segment is expected to grow the fastest?
The consumer electronics segment is forecasted to experience the fastest growth, owing to demand for 3D cameras in smartphones, gaming, and AR/VR devices, supported by continuous innovation in camera technology and consumer preferences.
Q6: Who are the leading companies operating in the North America 3D Cameras Market?
Major companies include Intel, Sony, Oculus VR (Meta), Microsoft, and Google, which are investing heavily in R&D, strategic partnerships, and product launches to maintain competitive advantage and expand their market share.
Analyst Perspective
The North America 3D Cameras Market demonstrates signs of reaching a mature stage, driven by incremental innovations in sensor technology and integration capabilities. The long-term outlook remains promising, with sustained demand from burgeoning automation sectors, autonomous vehicles, and advanced consumer electronics. Commercial opportunities are focused on the development of high-resolution, real-time 3D imaging solutions that cater to industrial and entertainment applications, alongside emerging uses in healthcare diagnostics. Technology evolution is likely to prioritize miniaturization, enhanced accuracy, and cost reduction, fostering broader adoption. Investment priorities should emphasize R&D to accelerate innovations in AI-based spatial analysis and multi-sensor fusion. Competitive intensity is expected to increase as both established electronics giants and specialized startups compete, seeking market differentiation. Regional growth potential is high in North America’s tech hubs, with strategic investments supporting market expansion, particularly in automotive and industrial sectors. Long-term, firms that prioritize technological agility and regional specialization will be better positioned to capitalize on evolving consumer and industrial demands.
