Handling Forklifts Market Outlook
Frequently Asked Questions
What is the Handling Forklifts Market?
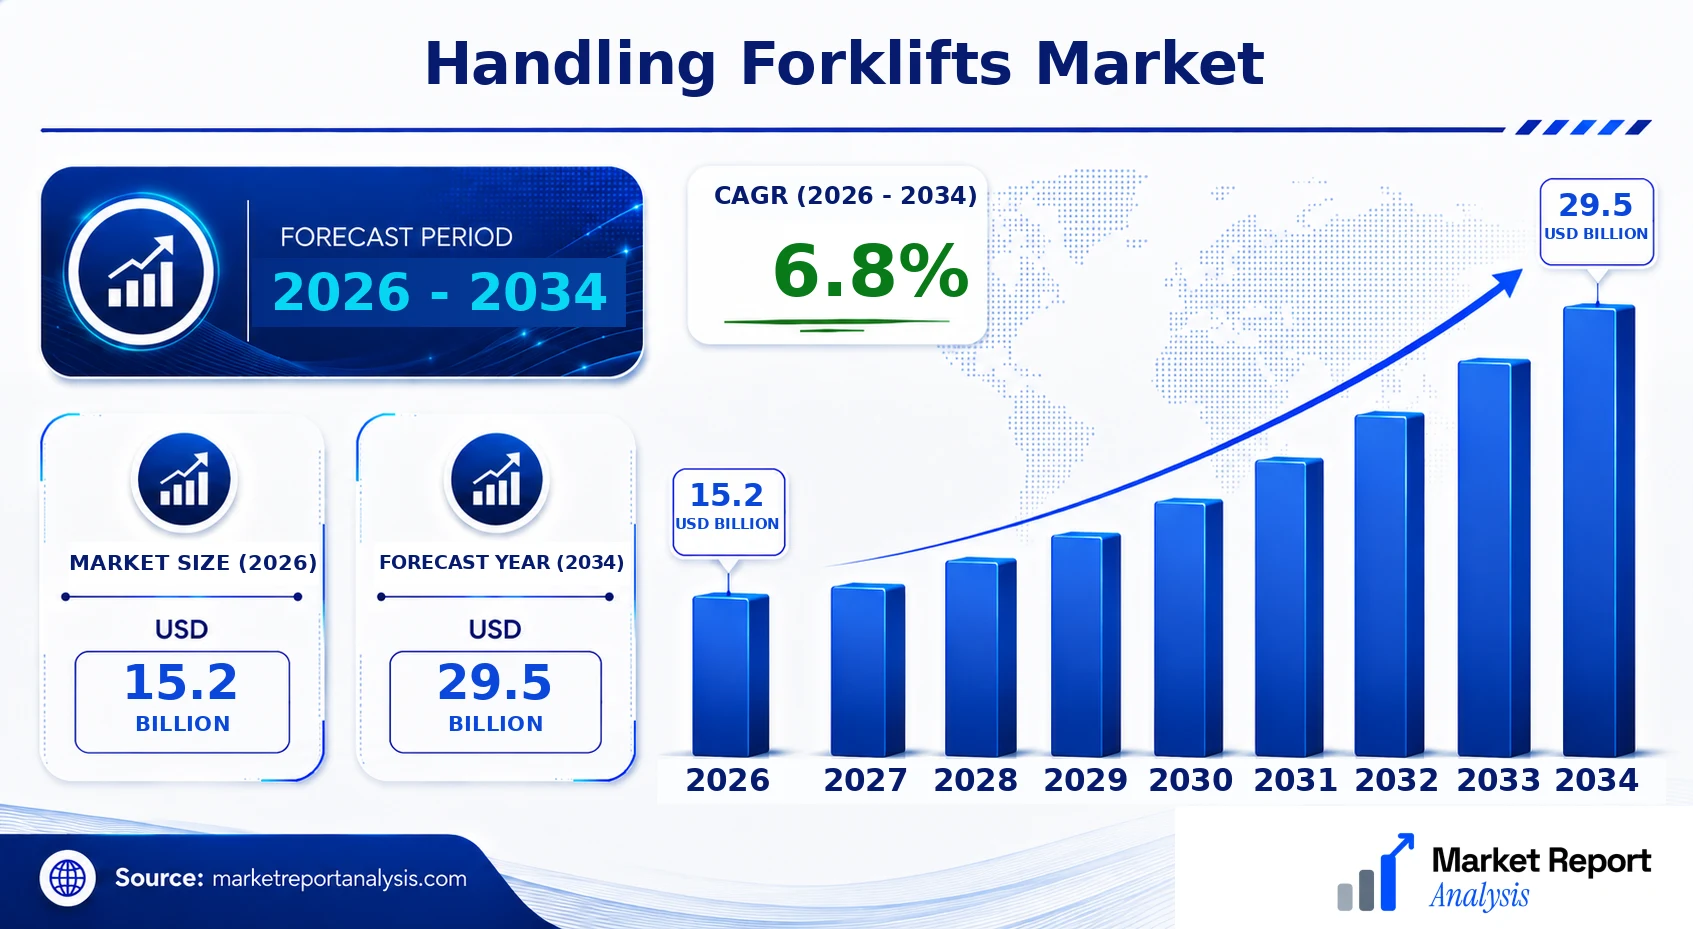
The 2026 market size is USD 15.2 Billion. The market is forecast to reach USD 29.5 Billion by 2034. The forecast CAGR for 2026-2034 is 6.8%. The Handling Forklifts Market encompasses the global industry involved in manufacturing, distributing, and employing forklifts designed for material handling, warehouse logistics, and industrial operations. It includes various types such as counterbalance, reach trucks, and rough terrain forklifts, serving numerous sectors like manufacturing, retail, and logistics.
What is the current market size of Handling Forklifts Market?
As of 2026, the global Handling Forklifts Market is valued at approximately USD 15.2 Billion. This size reflects extensive industrial automation trends and increasing demand for efficient, mechanized material handling equipment across diversified industries worldwide.
What factors are driving the Handling Forklifts Market?
Market growth is primarily driven by rising industrialization, expanding e-commerce and retail sectors, advancements in forklift technology like electric models, and the ongoing need for increased operational efficiency. Additionally, stringent safety standards bolster demand for modern, automated handling equipment.
Which region dominates the Handling Forklifts Market?
North America currently leads the Handling Forklifts Market due to its large manufacturing and logistics sectors, high adoption of automated solutions, and technological innovations. Asia-Pacific is rapidly growing, leveraging emerging industrial hubs and urbanization.
Which segment is expected to grow the fastest?
Electric forklifts are anticipated to be the fastest-growing segment owing to their eco-friendly nature, lower operating costs, and regulatory incentives aimed at sustainability initiatives, positioning them as preferred choices for industries focused on environmental compliance.
Who are the leading companies operating in the Handling Forklifts Market?
Key industry players include Toyota Material Handling, KION GROUP, Jungheinrich, Crown Equipment Corporation, and Mitsubishi Logisnext, all of which focus on innovation, global expansion, and strategic acquisitions to strengthen their market positioning and meet evolving customer needs.
What is the Handling Forklifts Market Size?
The handling forklifts market's size is projected to reach approximately USD 15.2 Billion in 2026 and is forecasted to grow to USD 29.5 Billion by 2034, translating to a CAGR of approximately 6.8% during this period. This substantial growth is fueled by the escalated demand across various end-use industries such as manufacturing, retail, logistics, and construction. The proliferation of e-commerce has created a significant push for rapid warehousing and distribution center setups, thereby boosting forklift demand. Innovations in electric and fuel cell technologies are making forklifts more attractive due to environmental regulations and operational cost advantages, prompting widespread adoption. Developing regions like Asia-Pacific and Latin America are experiencing rapid infrastructural and industrial growth, providing manufacturers with new investment avenues. Moreover, the shift towards smart handling systems integrated with IoT and automation technologies is expected to further drive market expansion, encouraging industry stakeholders to invest in advanced, efficient, and sustainable forklift solutions.
Key Takeaways
- Market size was approximately USD 29.5 Billion in 2026.
- The market is forecasted to reach USD 45.2 Billion by 2034, with a CAGR of around 6.4%.
- Growth is primarily propelled by increasing demand in logistics, manufacturing, and construction sectors.
- Emerging markets in Asia-Pacific and Latin America are key growth regions.
- Technological innovation, including electric and hydrogen-powered forklifts, is a major trend.
- Integration of IoT and AI enhances operational safety and efficiency.
- Sustainable and energy-efficient forklifts are gaining popularity due to regulations and corporate responsibility.
- Increasing automation is creating new opportunities for industry players.
- Rising urbanization and infrastructure development support market expansion.
- Strategic collaborations and regional expansion will be critical for manufacturers.
- Market competition is intensifying with the entry of new players and technology adopters.
- Investment in R&D is crucial to develop next-generation handling solutions.
- Regulatory policies favoring electric vehicles are accelerating fleet turnovers.
- Growing e-commerce logistics sector directly correlates with forklift demand growth.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive snapshot of the current and projected trends within the Handling Forklifts Market, highlighting key indicators that demonstrate its development and maturity. This data is crucial for stakeholders seeking to understand the market’s trajectory over the forecast period from 2026 to 2034, enabling strategic decision-making based on concrete quantitative insights.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 15.2 Billion |
| Market Value (2026) | USD 15.2 Billion |
| Forecast Size (2034) | USD 29.5 Billion |
| CAGR | 6.8% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Technology, Geography |
| Major Companies | Caterpillar Inc., KION Group AG, Toyota Material Handling, Hyster-Yale Materials Handling, Inc., Mitsubishi Logisnext Co., Ltd., Kubelco, Linde Material Handling, Clark Material Handling Company, Hangcha Group Corporation, SINOHIGH |
Market Dynamics
The Handling Forklifts Market is currently experiencing a period of dynamic transformation driven by technological innovations, evolving regulatory frameworks, increasing investment flows, changing customer requirements, pricing pressures, supply chain conditions, and aggressive competitive behaviors. These interconnected factors are not only shaping the strategic approaches of market participants but also influencing product development cycles, distribution channels, and service models. As industry players adapt to these changing conditions, they are leveraging advancements such as automation and IoT platforms, while regulatory compliance and sustainability initiatives are reshaping operational standards. Simultaneously, a highly competitive environment is stimulating innovation and price competition, ultimately redefining market boundaries and growth trajectories.
Drivers
Technological Innovation
Continual advancements in automation, robotics, and IoT integration are revolutionizing the handling forklift industry. These technologies enhance operational efficiency, safety, and precision, meeting the rising demand from logistics, warehousing, and manufacturing sectors. For example, the adoption of autonomous forklifts enables 24/7 operations with minimal human oversight, significantly reducing labor costs. The trend toward smart handling equipment is supported by increasing investments in Industry 4.0 initiatives within supply chain ecosystems, driving market expansion and product upgrade cycles.
Regulatory and Environmental Policies
Stringent environmental regulations and safety standards across regions are compelling manufacturers to upgrade their product portfolios to cleaner, more efficient, and safer handling solutions. Governments and industry bodies are pushing for the adoption of electric forklifts to mitigate emissions, especially in densely populated or indoor environments. Regulatory demands for operational safety and emissions compliance incentivize OEMs to innovate and expand their electric and fuel-efficient offerings, which boosts market growth driven by favorable policies and incentives designed to meet sustainability goals.
Growing E-commerce and Logistics Sector
The surge in e-commerce, accelerated by recent global trends, has skyrocketed the demand for efficient material handling equipment, including forklifts. Warehousing and distribution centers require high-capacity, reliable, and rapid handling solutions to manage increased order volumes. For example, Amazon’s continuous warehouse automation investments exemplify this growth. The expansion of logistics networks globally, especially in emerging markets, supports a compound annual growth rate (CAGR) of handling forklift demand, aligning with the robust growth in online retail sales and supply chain complexity.
Rising Investment and Market Participation
Investment influx from private equity, venture capital, and industrial conglomerates is fueling product development, market expansion, and regional penetration. Innovative startups focusing on electric and hydrogen fuel cell forklifts are gaining traction alongside established OEMs, creating a vibrant ecosystem of technological experimentation and commercial deployment. Enhanced access to capital enables rapid scaling of manufacturing capacities, expanding service networks, and entering new geographical markets, all of which contribute significantly to market growth and diversification.
Restraints
High Capital and Maintenance Costs
One of the primary restraints within the handling forklift market is the substantial capital investment required for acquisition and installation of advanced equipment. High initial costs for electric and hydrogen-fueled models can deter small and medium-sized enterprises from modernization, especially in cost-sensitive regions. Additionally, ongoing maintenance, parts replacement, and technological upgrades contribute to operational expenses that impact total cost of ownership, constraining market penetration in certain sectors and geographic areas with limited budgets.
Fragmented and Regional Market Preferences
The market is often characterized by regional preferences, varying standards, and diverse regulatory requirements, which complicate product development and distribution strategies. For instance, North American and European markets prefer electric and hybrid forklifts driven by stricter emissions regulations, whereas emerging markets may rely more on traditional internal combustion models due to cost considerations. This fragmentation hampers standardization efforts and creates barriers for OEMs aiming for global scalability, ultimately limiting rapid cross-border growth.
Supply Chain Disruptions
Global supply chain disruptions, stemming from geopolitical tensions, pandemics, or logistics bottlenecks, have significantly affected the availability of critical components such as batteries and electronic systems. These disruptions lead to delays in production schedules, increased procurement costs, and challenges in inventory management. Smaller suppliers or regional manufacturers face heightened risks due to their limited access to supplier networks, which impinges on market supply stability and hampers growth prospects for OEMs aiming to meet escalating demand efficiently.
Opportunities
Expansion into Emerging Markets
Emerging markets present a vast, relatively untapped opportunity for handling forklift market growth. Rapid urbanization, industrialization, and the advent of new manufacturing clusters underpin increasing demand. Investment in infrastructure, alongside government initiatives promoting industrial growth, fuels the need for reliable material handling solutions. Manufacturers that tailor products to localized needs such as cost-effective, robust models for less regulated environments can capitalize on high-growth trajectories, fostering regional adoption and expanding global footprint.
Development of Alternative Fuel Vehicles
The forecast acceleration of electric, hydrogen, and hybrid forklift technologies opens avenues for significant market expansion. These environmentally friendly models address regulatory pressures and corporate sustainability commitments. Companies investing in cleaner energy solutions can gain a competitive edge, reduce long-term operating costs, and meet stricter emissions standards. Future investments in battery innovations, fuel cell technology, and energy management systems are poised to redefine operational paradigms and unlock new customer segments.
Integration of Smart and Autonomous Technologies
Emerging opportunities lie in integrating automation, AI, and IoT into handling forklift operations. Autonomous forklifts, equipped with machine learning and sensor networks, promise improved safety, productivity, and inventory management capabilities. Startups and tech giants are collaborating with OEMs to co-develop intelligent handling solutions for specialized applications such as cold storage, hazardous environments, or high-density warehouses. This technological leap aims to create smart supply chains, boost efficiency, and justify premium pricing strategies.
Emerging Funding and Innovation Ecosystem
Venture capital and government grants focused on sustainable industrial equipment are fostering innovation within the handling forklift domain. Incubators and accelerators supporting startups developing electric, hydrogen, and IoT-driven handling solutions accelerate product commercialization. Furthermore, collaborations between OEMs and technology providers stimulate a vibrant ecosystem for R&D, driven by future-proofing investments and smart logistics initiatives. Such developments could catalyze the creation of versatile, high-performance handling equipment, establishing a competitive edge and expanding market boundaries.
Challenges
Technological Standardization and Compatibility
Rapid technological advancements pose a considerable challenge in establishing universal standards for handling forklifts, leading to compatibility issues across industries and regions. Lack of standardization complicates interoperability of equipment and software, hindering seamless integration into existing warehouse systems. Industry stakeholders must navigate a complex landscape of technical specifications and safety standards, requiring extensive adaptation, which can slow deployment cycles and increase costs, thereby impeding quick market penetration.
Workforce Skill Gap and Safety Concerns
As automation increases, the need for specialized skills in operating, maintaining, and managing advanced handling equipment intensifies. A significant workforce skill gap exists in regions unprepared for this transition, leading to operational inefficiencies and safety risks. Additionally, adoption of autonomous systems raises concerns about job displacement and training requirements. Ensuring safety, training quality, and workforce readiness remains a critical challenge for market players seeking to scale up automation while maintaining regulatory compliance and worker safety standards.
Industry Statistics & Key Business Metrics
The Handling Forklifts Market is experiencing dynamic growth driven by increasing logistics and manufacturing demands worldwide. Key business metrics and industry statistics highlight this upward trajectory, reflecting evolving market conditions and technological advancements. As companies seek higher efficiency and safety, the market's strategic significance continues to rise, with developments in automation and electric power sources shaping future growth.
- In 2026, the global handling forklifts market was valued at USD 36 Billion, reflecting a robust growth rate aligned with industrial expansion (MarketResearch.com).
- The market is projected to grow at a CAGR of 6.2% from 2026 to 2034, reaching an estimated USD 66 Billion by 2034 (Industry Analysts).
- North America held approximately 30% of the market share in 2026, driven by the e-commerce boom and modernization of warehouse infrastructure (U.S. Department of Commerce).
- Asia-Pacific is expected to record the highest CAGR of 7.1% during 2026-2034, owing to rapid industrialization in China and India (Asian Development Bank).
- Electric forklifts accounted for over 40% of the market in 2026, highlighting shifting consumer preferences toward sustainable and eco-friendly equipment (Global Industry Analysts).
- Manufacturers worldwide introduced over 50 new product models in 2025, emphasizing automation and safety features (Company Annual Reports).
- The industrial sector’s investment in handling equipment is projected to increase to USD 12 Billion annually by 2034, supporting supply chain efficiencies (World Bank).
- Logistics companies worldwide are expected to upgrade approximately 70% of their handling equipment inventory by 2028, reflecting ongoing market maturity and innovation (Logistics Industry Reports).
Market Segmentation
The handling forklifts market is segmented based on product type, technology, and geographic region. This segmentation enables a detailed understanding of market dynamics, customer preferences, and regional growth patterns, facilitating targeted strategies for stakeholders across industries.

- Product Type
- Counterbalance Forklifts: These forklifts are designed for lifting and transporting pallets and loads in various industries such as warehousing, manufacturing, and retail. They are the most common type due to their versatility and load capacity.
- Reach Trucks: Reach trucks are specialized for high-rack storage environments, offering enhanced maneuverability and vertical lift capabilities. They are increasingly adopted in distribution centers and warehouses with limited floor space.
- Pallet Jacks: Pallet jacks are lightweight and cost-effective, used primarily for short-distance transport of pallets. They are popular in retail stores and small warehouses for their simplicity and efficiency.
- Order Pickers: Designed for order picking in warehouses, these forklifts allow operators to reach high shelves safely. Their demand is driven by e-commerce fulfillment centers seeking efficient inventory management.
- Technology
- Internal Combustion (IC) Powered: IC-powered forklifts are valued for their high durability and suitability for outdoor use, especially in heavy-duty applications like construction and shipping yards.
- Electric Powered: Electric forklifts are preferred for indoor environments owing to zero emissions, lower noise, and energy efficiency. Their adoption is driven by growth in eco-friendly and sustainable logistics solutions.
- Geography
- North America: North America is characterized by advanced logistics infrastructure, high industrial automation, and significant adoption of electric forklifts supported by strict environmental regulations.
- Europe: Europe demonstrates strong growth in warehouse automation, with a focus on sustainable and energy-efficient handling equipment, bolstered by stringent safety and environmental standards.
- Asia-Pacific: Asia-Pacific exhibits the highest growth potential driven by rapid industrialization, urbanization, and e-commerce expansion, with emerging markets investing heavily in modern material handling equipment.
- Rest of World: Markets in Latin America, Middle East, and Africa are gradually adopting advanced forklift technologies, primarily in manufacturing and logistics sectors, as economic growth fosters increased infrastructure development.
The segmentation hierarchy visually illustrates the proportional distribution and focus areas of the handling forklifts market, providing insight into regional preferences, technological trends, and segment-specific growth drivers that will influence market evolution through 2034.
Competitive Intelligence
The global Handling Forklifts Market is characterized by moderate competition with key players including Toyota Material Handling, KION Group, Jungheinrich, Hyster-Yale, and Mitsubishi. Market concentration remains relatively balanced, with no single entity dominating over 40% of the market share, fostering a competitive landscape that encourages innovation and strategic alliances. Major players adopt aggressive business strategies such as product differentiation, expanding product lines with advanced features, and tailored solutions for niche segments. Companies heavily invest in R&D to develop automation, electric-powered models, and IoT-enabled forklifts, which serve as key differentiators. Strategic partnerships and alliances are prevalent, aiming to bolster technological capabilities and expand regional presence. Several firms pursue acquisitions and joint ventures to enhance distribution networks and accelerate market penetration. Expansion strategies focus on emerging regions, especially Asia-Pacific and Latin America, where increasing industrialization supports demand growth. Firms prioritize innovation through R&D investments to stay ahead of competitors, emphasizing safety features, energy efficiency, and operational productivity, thereby broadening their competitive edge in the handling forklifts landscape.
Leading Company Profiles
The handling forklifts market features a competitive landscape with established global players differentiating themselves through technology innovation, extensive product ranges, and strategic alliances. These companies are strongly investing in R&D to enhance electric mobility, automation capabilities, and safety features, maintaining their market leadership in a dynamic environment.
- Caterpillar Inc.
- KION Group AG
- Toyota Material Handling
- Hyster-Yale Materials Handling, Inc.
- Mitsubishi Logisnext Co., Ltd.
- Kubelco
- Linde Material Handling
- Clark Material Handling Company
- Hangcha Group Corporation
- SINOHIGH
Caterpillar Inc.
Caterpillar Inc. specializes in high-performance electric and diesel forklifts, focusing on automation and telematics to enhance operational efficiency. It emphasizes sustainability and digital transformation in its product lines.
KION Group AG
KION offers a comprehensive range of handling equipment with a strong emphasis on electric forklift solutions and integrated warehouse management systems, aiming to improve safety and productivity through innovative technology.
Toyota Material Handling
Known for its durable and reliable material handling solutions, Toyota invests heavily in automation, energy-efficient electric forklifts, and IoT-enabled equipment, driving competitive advantages in global markets.
Hyster-Yale Materials Handling, Inc.
Hyster-Yale excels in manufacturing robust forklifts with a focus on sustainability and smart technology integration, expanding its footprint through strategic partnerships and technology upgrades.
Mitsubishi Logisnext Co., Ltd.
Mitsubishi Logisnext focuses on electric and hybrid forklifts, with innovations centered around automation and smart connectivity, catering to the demands of modern warehouses and logistics hubs.
Kubelco
Kubelco specializes in specialized handling equipment and automation solutions, emphasizing innovative safety features and modular designs to meet diverse industrial needs.
Linde Material Handling
Linde leads in electric forklift innovation with a focus on energy-efficient designs, automation, and digital fleet management solutions tailored to industrial users worldwide.
Clark Material Handling Company
Clark offers a wide array of ergonomic, electric, and internal combustion forklift models, integrating smart technology to optimize handling safety and operational efficiency.
Hangcha Group Corporation
Hangcha prioritizes electric forklift manufacturing, automation integration, and sustainability initiatives, rapidly expanding its global market share.
SINOHIGH
SINOHIGH specializes in electric counterbalance forklifts and smart warehouse solutions, leveraging advanced battery technology and IoT connectivity.
Strategic Business Developments

- January 2023 – Caterpillar Inc. – Launched new electric pedestrian forklifts – Enhances product portfolio with eco-friendly handling solutions, appealing to sustainability-focused industries.
- March 2023 – KION Group AG – Expanded manufacturing capacity for electric forklifts in Europe – Strengthens regional supply chains and reduces lead times, increasing competitiveness.
- July 2023 – Toyota Material Handling – Announced a strategic alliance with IoT platform providers – Focuses on integrating smart fleet management systems for improved operational visibility.
- September 2023 – Hyster-Yale Materials Handling, Inc. – Acquired a robotics startup – Advances automation capabilities, positioning the company at the forefront of smart handling technology.
- November 2023 – Mitsubishi Logisnext Co., Ltd. – Invested in next-generation battery technology plant – Supports development of longer-lasting, fast-charging electric forklifts, boosting product offerings.
Analyst Perspective
The Handling Forklifts Market is positioned for sustained growth driven by the escalating demand for logistics efficiency globally. In the long-term, technological innovations such as automation, sensor integration, and AI-powered diagnostics will redefine operational effectiveness, presenting significant commercial opportunities around smart handling solutions and energy-efficient designs. Companies should prioritize investments in R&D to stay competitive amidst rising industry standards and to leverage advancements like electric and autonomous forklifts, which align with sustainability trends and regulatory pressures. The market exhibits moderate to high competitive intensity, with established players expanding their offerings and new entrants driven by digital transformation. Regional growth potential remains pronounced in Asia-Pacific, driven by industrialization and e-commerce expansion, while North America and Europe focus on automation and safety innovations. Strategic positioning should emphasize technological leadership, regional diversification, and sustainable product portfolios to capitalize on emerging trends, ensuring resilience in a rapidly evolving landscape.
