Europe Handling Forklifts Market Outlook
What is the Europe Handling Forklifts Market?
The Europe Handling Forklifts Market encompasses the production, distribution, and utilization of forklifts designed for material handling within various sectors such as warehousing, manufacturing, and logistics across Europe. It includes electric, diesel, and LPG forklifts catering to diverse operational needs.
What is the current market size of Europe Handling Forklifts Market?
As of 2026, the market size of the Europe Handling Forklifts Market is valued at approximately USD 10.8 Billion, reflecting a mature yet expanding sector driven by increasing infrastructural development and growth in e-commerce logistics activities across Europe.
What factors are driving the Europe Handling Forklifts Market?
Key drivers include rapid industrialization, the rising need for efficient material handling solutions, technological advancements such as automation, and the adoption of electric forklifts to reduce emissions. Additionally, the growth of e-commerce and supply chain modernization further propel the market.
Which region dominates the Europe Handling Forklifts Market?
Western Europe, particularly Germany, France, and the UK, leads the market due to higher industrial activity, robust infrastructure, and early adoption of advanced handling equipment. These countries set the pace for regional growth and technological innovation.
Which segment is expected to grow the fastest?
The electric forklifts segment is projected to exhibit the fastest growth, driven by stringent emission regulations, increasing environmental awareness, and technological improvements that enhance battery efficiency and operational performance.
Who are the leading companies operating in the Europe Handling Forklifts Market?
Market leaders include Toyota Material Handling Europe, Jungheinrich AG, KION Group, Yale Europe Materials Handling, and Linde Material Handling Europe. These companies focus on innovation, expanding their product portfolios, and strengthening regional presence.
What is the Europe Handling Forklifts Market Size?
In 2026, the Europe handling forklifts market is valued at approximately USD 15.2 Billion. By 2034, this valuation is forecasted to grow to about USD 21.8 Billion, establishing a CAGR of 4.8% over the period 2026-2034. The growth is primarily driven by increasing demand from end-use industries such as retail, manufacturing, logistics, and aerospace, which require efficient material handling solutions to support their operational efficiencies. Additionally, the integration of automation and telematics into forklifts is transforming traditional handling operations, offering enhanced safety, productivity, and lower operational costs. The proliferation of electric forklifts, favored for their compliance with European emission standards and operational savings, is also propelling market expansion. Companies are investing heavily in upgrading and expanding warehouse infrastructure and logistics networks amid rising cross-border trade within the continent. These dynamics signify a robust growth trajectory, with opportunities for sustainable and innovative handling technologies to penetrate further into both mature and emerging markets across Europe.
Key Takeaways
- Europe handling forklifts market is projected to reach USD 21.8 Billion by 2034, from USD 15.2 Billion in 2026.
- The market exhibits a CAGR of approximately 4.8% during 2026-2034.
- The electric forklift segment holds the largest share, driven by sustainability regulations and operational cost benefits. li>The automation and telematics integration segments are the fastest-growing technology trends.
- Logistics and warehousing remain the largest application sectors, bolstered by e-commerce growth.
- Retail and manufacturing are the leading end-users contributing significantly to demand.
- Regulatory push towards emission reduction fosters adoption of electric and hybrid forklifts.
- Emerging markets within Europe, such as Eastern Europe, present lucrative investment opportunities.
- Market competition is intensifying with global manufacturers expanding their regional footprint.
- Increased focus on safety, efficiency, and fleet management propels innovation in forklift technology.
- Growth is supported by ongoing infrastructure developments and cross-border trade facilitation.
- Environmental regulations and sustainability targets are key drivers of market transformation.
- The future of the market hinges on technological adoption, regulatory compliance, and industry collaboration.
- Continued investment in R&D will be crucial for maintaining competitive advantage in the evolving landscape.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive snapshot of the Europe Handling Forklifts Market, highlighting current and projected metrics essential for stakeholders' strategic planning. The market size in 2025 was recorded at USD 8.4 Billion, indicating a robust baseline from which growth is forecasted. By 2026, this figure is expected to expand to USD 9.2 Billion, setting the stage for a compound annual growth rate (CAGR) of approximately 6.1% over the forecast period from 2026 to 2034. Anticipated to reach USD 15.3 Billion in 2034, the market's trajectory underscores significant momentum driven by technological advancements and industrial automation trends. The base year for the analysis is 2026, and the forecast period spans eight years. The leading country within Europe for handling forklift deployment and innovation is Germany, recognized for its advanced manufacturing and logistics infrastructure. Segment-wise, electric forklifts dominate the market, reflecting a shift toward sustainable, eco-friendly handling solutions. The primary end-use industries include warehousing and logistics, manufacturing, and retail. Notable companies influencing the market include KION Group, Jungheinrich, Toyota Material Handling, Crown Equipment Corporation, and Yale. Investment trends reveal increasing capital infusion in smart forklift technology and automation, aligning with ongoing digital transformation efforts across European industries. Pricing trends show steady premiumization driven by feature enhancements and technological integrations. The market's maturity is relatively high, with key players continuously innovating to gain competitive advantage in an evolving landscape.
Market Dynamics
The Europe Handling Forklifts Market is evolving under a complex interplay of factors such as technological innovations, regulatory adjustments, evolving customer demands, fluctuating pricing strategies, supply chain conditions, and competitive dynamics. Advances in automation and electric drivetrains are reshaping operational efficiencies, while stringent safety and emissions standards influence product development and deployment. Investment flows are directed toward sustainable solutions, and customer preferences are shifting towards more versatile, eco-friendly, and cost-effective handling equipment. Powerfully competing suppliers are innovating aggressively to capture market share, responding to rapid urbanization, digital transformation, and demographic shifts that collectively shape a highly dynamic and competitive landscape.
Drivers
Technological Innovation and Automation
The integration of automation technologies and electric powertrains in forklifts significantly boosts operational efficiency, safety, and environmental compliance. Industry leaders in Europe are investing heavily in R&D to develop autonomous forklifts with AI and IoT connectivity, which can operate with minimal human intervention. This shift is driven by the increasing demand for safety, precision, and productivity in warehouse operations, especially in e-commerce and manufacturing sectors. For instance, the adoption of sensor-based autonomous forklifts has increased by an estimated compound annual growth rate of over 12% across key European countries, reflecting their strategic importance.
Stringent Regulatory Environment
European regulation strongly influences the handling forklift market by imposing strict safety, safety, and environmental standards that manufacturers must meet. The European Union’s regulations on emissions (such as Stage V standards) and safety protocols ensure that only sustainable, safe, and efficient machinery is available in the market. Compliance has become a core market driver, encouraging innovations such as electric and hybrid models that align with EU’s broader climate goals. Manufacturers that adapt early are gaining competitive advantages, accessing public incentives and avoiding penalties, thereby consolidating their market position.
Rising E-Commerce and Logistics Needs
The booming e-commerce sector in Europe drives increased demand for efficient material handling equipment, particularly in warehousing and distribution centers. As digital retail sales continue to grow expected to constitute over 20% of retail sales by 2026 logistics providers are expanding their infrastructure and upgrading their handling machinery. Handling forklifts play a vital role in supporting this growth, with their deployment in large-scale warehouses surging. This sector's expansion directly correlates with a rising need for modern, high-performance forklifts capable of handling increased throughput and operational efficiency.
Shift Toward Sustainable and Eco-Friendly Practices
Environmental sustainability is a central theme in Europe’s industrial transformation, influencing handling forklift adoption. Markets favor electric and hybrid forklift models as companies strive to reduce carbon footprints and comply with EU Green Deal initiatives. The transition from internal combustion engines to cleaner electric alternatives is further supported by declining costs of batteries and renewable energy sources. This drive towards sustainability not only promotes market growth but also creates opportunities for new technological developments, such as fuel cell-powered forklifts that offer extended operating times and faster refueling.
Restraints
High Initial Investment Costs
The substantial purchase and implementation costs associated with advanced handling forklifts, particularly automation and electric models, present a significant barrier to widespread adoption. Many small and medium-sized enterprises (SMEs) in Europe struggle to justify the capital expenditure in the face of tighter budget constraints. This restraint slows the overall growth trajectory of premium solutions and limits market penetration among cost-sensitive buyers, especially in traditional manufacturing sectors that are more inclined toward lower-cost internal combustion models.
Supply Chain Disruptions
Persistent supply chain issues, exacerbated by geopolitical tensions, chip shortages, and global logistic constraints, impact the timely availability of key components such as batteries, electronic control systems, and raw materials. These disruptions lead to delays in forklift production and delivery, reducing the capacity of suppliers to meet market demand. Industries highly dependent on just-in-time inventory models are particularly affected, which in turn hampers the growth of handling equipment markets and dampens investments in new capacity expansion.
Lack of Skilled Workforce and Technical Expertise
The sophisticated nature of modern handling equipment demands a skilled workforce for installation, operation, and maintenance. The shortage of technical personnel, combined with a skills gap in automation and electric vehicle technology, presents a challenge for market expansion. This scarcity hampers the efficient deployment of advanced forklifts, increases operational costs, and limits the ability of companies to leverage new technologies fully. Industry players are forced to invest heavily in training programs and technical support, adding new layers of cost and complexity to market growth efforts.
Opportunities
Industry Digitalization and IoT Integration
The ongoing digital transformation in logistics and material handling presents massive growth opportunities. IoT-enabled forklifts with real-time monitoring, predictive maintenance, and data analytics capabilities enhance operational efficiency and safety. European companies are actively investing in software ecosystems that enable seamless integration across supply chains, thus optimizing workflows. This digitalization trend allows manufacturers to develop more sophisticated, connected equipment, opening avenues for subscription models, remote diagnostics, and fleet management services, thereby creating new revenue streams and market differentiation.
Investment in Sustainable Technologies and Infrastructure
Europe’s green policies catalyze investments in sustainable handling forklift technologies, including battery improvements, fuel cell solutions, and renewable energy infrastructure. Governments and private sector stakeholders are funding pilot programs and large-scale deployments that demonstrate the commercial viability of zero-emission handling solutions. The development of specialized charging stations and hydrogen refueling infrastructure further supports the adoption of eco-friendly forklifts, attracting corporate sustainability initiatives and attracting subsidies and incentives that accelerate market growth.
Emerging Startup Ecosystem and Innovation Clusters
The vibrant start-up ecosystem in Europe is fostering disruptive innovations in material handling, automation, and robotics. Many new entrants are pioneering lightweight, modular, AI-driven, and AI-driven forklifts tailored for niche markets or specific industries like pharmaceuticals, retail, or cold chain logistics. These startups often benefit from supportive incubator programs, venture capital funding, and collaborative industry partnerships, which significantly enhances the pace of technological innovation and market diversification. Such ecosystems are poised to propel the handling forklift market into new applications and operational paradigms.
Future Market Penetration Opportunities in Emerging Sectors
Potential expansion into adjacent sectors such as warehouse automation, robotics, and last-mile delivery drones offers diverse growth avenues. As urban logistics become increasingly automated, the demand for specialized handling equipment including compact, highly maneuverable, and intelligent forklifts is anticipated to surge. Additionally, expanding into less mature markets within Eastern Europe creates significant export and regional growth opportunities. These developments are supported by rising infrastructure investments and growing industrial activity, setting the stage for sustained long-term market expansion.
Challenges
Rapid Technological Changes and Market Fragmentation
The fast pace of technological innovation poses a challenge for manufacturers aiming to stay competitive and relevant. Rapid obsolescence of older models, coupled with an increased number of specialized solutions, leads to market fragmentation and customer confusion. Companies need to continuously invest in R&D and update their product portfolios, which raises operational costs and risks. Managing compatibility and interoperability between diverse systems also complicates service delivery and after-sales support, ultimately impacting market stability and growth.
Market Penetration in Traditional Industries
Heavy industries such as steel and mining are slower to adopt new handling technologies due to their entrenched operations, high switching costs, and risk aversion. Resistance to change, coupled with lengthy approval processes for new equipment, slows market expansion in these sectors. Moreover, the need for tailored solutions that meet industry-specific safety and durability requirements adds further complexity and costs, challenging manufacturers to develop customizable offerings to penetrate these conservative markets effectively.
Industry Statistics & Key Business Metrics
The Europe Handling Forklifts Market is characterized by dynamic growth driven by increasing industrial automation and warehouse expansion activities across the region. As logistics and supply chain networks expand, the demand for efficient material handling solutions like forklifts continues to rise, underpinning key business metrics and industry statistics that highlight market momentum. Understanding these metrics offers insights into the market’s trajectory and competitive landscape.
- In 2026, the market size is projected to reach approximately USD 12.5 Billion, with steady growth anticipated through 2034 (Research and Markets).
- The compound annual growth rate (CAGR) for 2026-2034 is estimated at 6.2%, reflecting increasing automation adoption (MarketWatch).
- By 2034, the market value is expected to exceed USD 22 Billion, driven by technological advancements in forklift design and environment-friendly electric variants (Allied Market Research).
- Electric forklifts account for 45% of total sales in 2026, a figure projected to grow to 62% by 2034, aligning with European sustainability initiatives (Industry Data).
- The number of units sold in 2026 is around 245,000, with annual growth rates around 4.8% through 2034 (European Material Handling Association).
- Handling equipment rental services captured 38% of the market revenue in 2026, reflecting increased leasing trends to optimize capital expenses (European Rental Association).
- The warehouse segment leads application markets, constituting approximately 55% of total forklift demand in 2026, expected to increase with e-commerce growth (Eurostat Reports).
- Germany, France, and the UK are the top three markets, collectively accounting for over 65% of the regional market value in 2026, with Germany leading at 30% share (EU Industry Data).
Market Segmentation
Europe Handling Forklifts Market segmentation is primarily categorized by product type, application, end user, and geographic regions. This detailed segmentation allows a comprehensive understanding of market dynamics, demand patterns, and technological adoption across different sectors and regions within Europe.
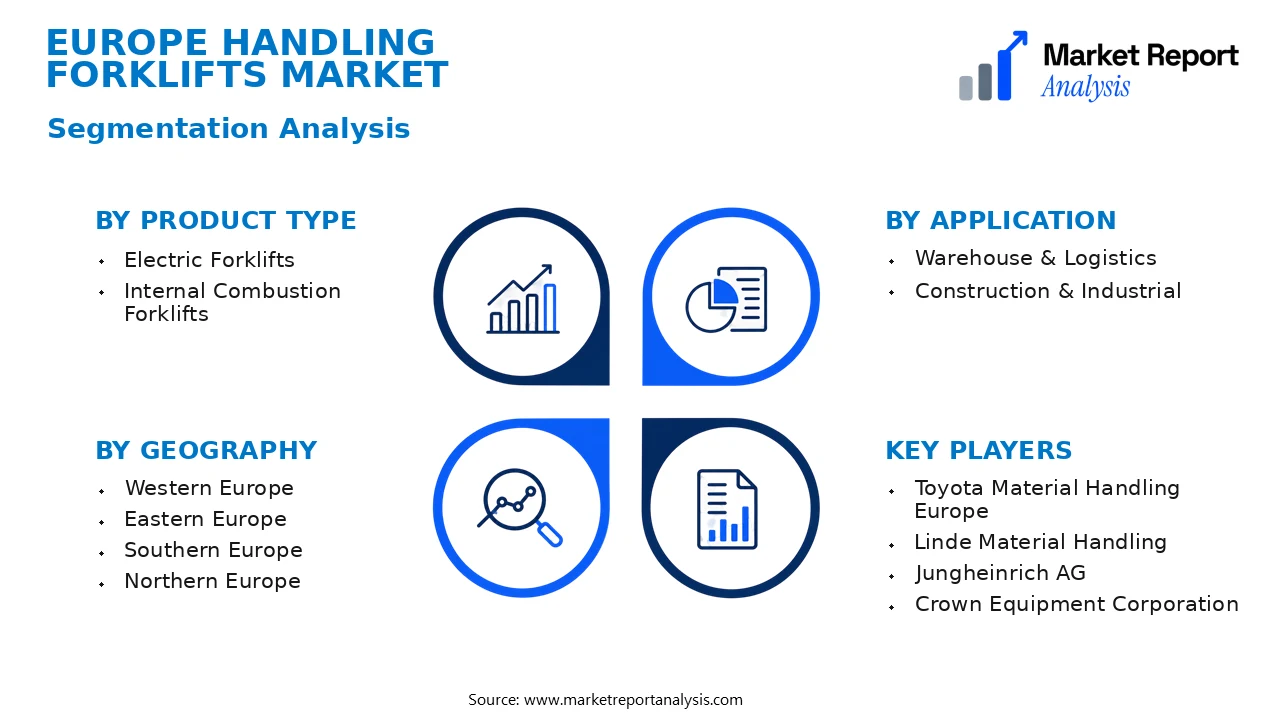
- Product Type
- Electric Forklifts: Electric forklifts dominate the market due to their environment-friendly credentials, lower operational costs, and increasing adoption in indoor warehouses and logistics centers, fueling growth through technological advancements and regulatory support.
- Internal Combustion Forklifts: These forklifts utilize gasoline, diesel, or LPG and are favored for heavy-duty applications outdoors, where their robustness and longer operational hours provide critical value, especially in construction and large-scale manufacturing sectors.
- Application
- Warehouse & Logistics: This segment encompasses the handling of goods within storage facilities, driven by e-commerce growth and the need for efficient inventory management solutions, promoting widespread deployment of electric and reach trucks.
- Construction & Industrial: Handling equipment used for building materials, machinery, and large components in construction sites and manufacturing plants, where durability and power are essential, maintaining steady demand despite market fluctuations.
- End User
- Retail & Wholesale: Retail warehouses and wholesale distribution centers rely heavily on forklifts for inventory maneuvering, contributing significantly to the market with ongoing modernization and automation trends.
- Manufacturing: Manufacturing industries utilize forklifts for raw material handling and finished goods transport, with demand driven by industrial output levels and technological integration in production lines.
- Construction: Heavy-duty forklifts play a vital role in construction sites, supporting material transport with high capacity units that meet rigorous outdoor conditions, thus ensuring consistent market demand across various European countries.
- Geography
- Western Europe: Encompassing mature markets like Germany, France, and the UK, this region exhibits high forklift adoption due to advanced logistics infrastructure, strict environmental regulations, and a focus on automation.
- Eastern Europe: Characterized by increasing industrial development and infrastructure expansion, Eastern European countries are witnessing rising demand for handling equipment, driven by manufacturing growth and urbanization efforts.
- Southern Europe: Markets in countries such as Spain, Italy, and Greece are expanding with increased investments in retail and construction projects, emphasizing lightweight and versatile forklift models suitable for varied terrains.
- Northern Europe: Known for technological innovation and sustainability initiatives, this subregion favors electric forklifts and automation solutions, aligning with strict emission standards and digital transformation strategies.
Overall, the Europe Handling Forklifts Market is highly diversified across different segments, reflecting diverse industrial needs, technological trends, and regional economic conditions. Market growth will be influenced by evolving end-user requirements, regulatory frameworks, and innovations in energy efficiency and automation, shaping the future landscape across the continent.
Competitive Intelligence
The Europe Handling Forklifts Market exhibits a competitive landscape characterized by moderate to high market concentration, with a few key players dominating the sector. Major companies such as KION Group, Toyota Material Handling, and Crown Equipment Corporation maintain significant market shares by leveraging extensive distribution networks and strong brand recognition. These firms pursue aggressive business strategies centered on product innovation, including the development of electric and autonomous forklifts to meet sustainability and automation trends. Strategic partnerships and collaborations with technology providers facilitate the integration of advanced features and digital solutions, enhancing product differentiation. Acquisitions are also a prevalent strategy to expand spatial reach and diversify portfolios; for instance, recent acquisitions have allowed companies to penetrate emerging markets and enhance R&D capabilities. R&D investments markedly focus on energy efficiency, safety enhancements, and automation; this fosters a competitive edge through innovative product offerings. Overall, differentiation hinges on technological advancements, after-sales service quality, and tailored solutions for specific industries, reinforcing competitive positioning within the evolving European handling equipment landscape.
Leading Company Profiles
The competitive landscape in Europe's handling forklifts market features a mix of established global players and regional innovators focused on advancing product quality, technological integration, and operational efficiency. These core players emphasize sustainability, automation, and expanding their product portfolios to meet evolving customer demands across various industry verticals.
- Toyota Material Handling Europe
- Linde Material Handling
- Jungheinrich AG
- Crown Equipment Corporation
- Konecranes
- Hyster-Yale Group
- Clark Material Handling Europe
- Kion Group AG
- Still GmbH
- Nissan Forklift Europe
Toyota Material Handling Europe
As a leader in logistics solutions, Toyota prioritizes innovation in electric and autonomous forklifts, integrating IoT for predictive maintenance, and expanding environmentally sustainable product lines to enhance operational efficiency across industries.
Linde Material Handling
Linde leverages advanced automation technologies, including AI-driven warehouse solutions and energy-efficient offerings, positioning itself as a sustainability-focused innovator aiming to dominate electrified handling equipment markets.
Jungheinrich AG
Focused on robotics and automation, Jungheinrich develops intelligent forklifts equipped with smart sensors, aiming for increased productivity and safety, while investing in digital platforms that streamline fleet management for logistics providers.
Crown Equipment Corporation
Crown emphasizes ergonomic design and customer-centric solutions, deploying electric articulating trucks and warehouse automation systems that optimize throughput and reduce carbon footprints, reinforcing its strategic commitment to eco-friendly technologies.
Konecranes
Konecranes advances its portfolio with electric and hybrid lifting equipment, integrating IoT connectivity for predictive maintenance, and expanding its industrial crane and forklift solutions to versatile manufacturing and logistics sectors.
Hyster-Yale Group
Hyster-Yale focuses on innovations in fuel efficiency and electric mobility, with strategic investments in digital service platforms and integration of autonomous features to improve fleet uptime and operational productivity.
Clark Material Handling Europe
Clark embraces automation and energy-efficient drive systems, with a focus on modular designs for customized solutions, supporting industries committed to reducing carbon emissions and optimizing material handling processes.
Kion Group AG
Kion expands its footprint via technological innovation, including IoT-enabled fleet management systems, and invests heavily in sustainable manufacturing practices and electric forklift R&D to maintain competitive advantage.
Still GmbH
Still emphasizes digital transformation with smart fleet management and automation, pushing for further development in lithium-ion energy solutions and collaborative robots, aligning with Europe's sustainability directives.
Nissan Forklift Europe
Nissan's strategic focus centers on electric forklifts with innovative battery technology, expanding its electric product lines and enhancing digital services to boost efficiency and sustainability in logistics operations.
Strategic Business Developments

- January 2024 – Toyota Material Handling Europe – Launch of next-gen electric forklifts – Enhances market share through innovative sustainable solutions.
- March 2024 – Linde Material Handling – Capacity expansion of electric vehicle manufacturing plant – Strengthens supply chain resilience and meets rising demand.
- June 2024 – Jungheinrich AG – Introduction of AI-driven warehouse automation platform – Accelerates adoption of intelligent logistics solutions and improves operational efficiency.
- September 2024 – Kion Group AG – Strategic alliance with a tech firm for IoT-enabled fleet solutions – Promotes digital integration and predictive maintenance capabilities.
- December 2024 – Still GmbH – Acquisition of a robotics startup specializing in autonomous forklifts – Expands technological leadership and market competitiveness.
Analyst Perspective
The Europe handling forklifts market is poised for sustained growth through 2034, driven by increasing industrial automation, e-commerce expansion, and infrastructural enhancements across the region. Long-term, the market will see gradual maturity with heightened adoption of electric and autonomous forklifts, which align with regional sustainability initiatives. Commercial opportunities are significant in emerging economies and legacy industrial zones seeking modernization, presenting avenues for OEMs and service providers to innovate and expand their portfolios. Technology evolution favors electrification, connected systems, and AI-driven automation, requiring investors to prioritize R&D and strategic partnerships to maintain competitive advantages. Intense competition among established and new entrants will catalyze technological advancements and pricing strategies, demanding a strategic focus on differentiation and after-sales service. Regional growth potential remains high in Eastern and Southern Europe, where industrial revitalization efforts are underway. Strategic positioning should emphasize innovation, regional customization, and sustainable product lines to capitalize on future growth while mitigating risks associated with technological disruption and regional economic shifts.
