Europe Plant Phenotyping Market Outlook
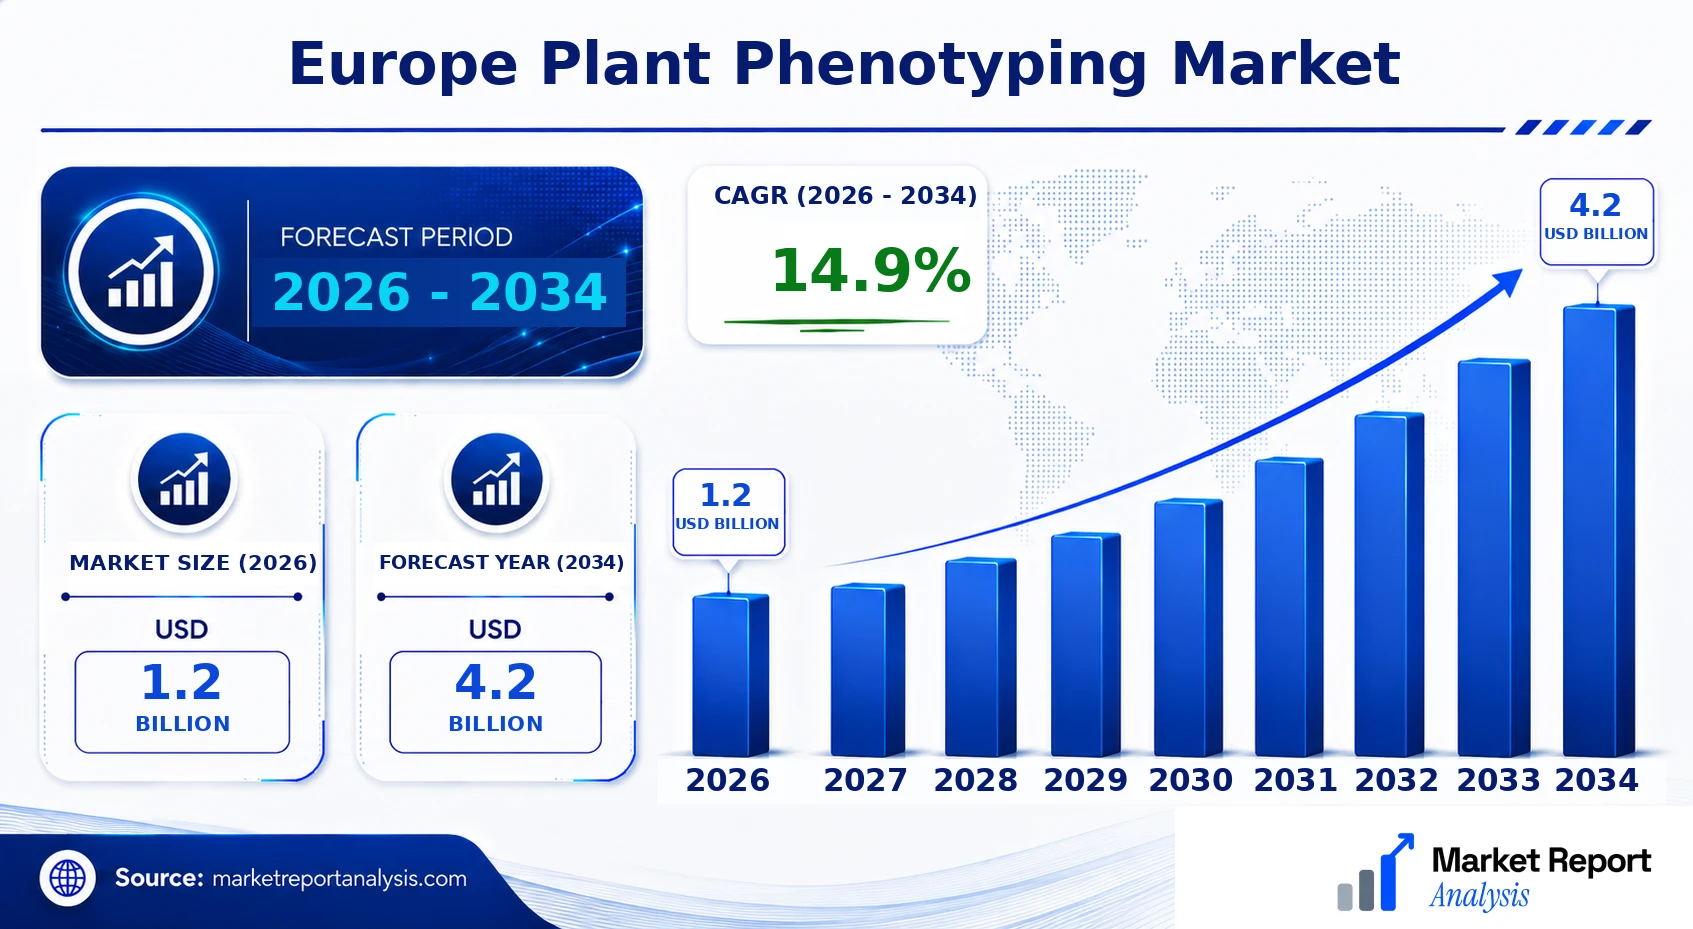
The market is forecast to reach USD 1.2 Billion by 2034. The Europe plant phenotyping market is currently experiencing significant growth, driven by advances in agricultural technology and increased investment in sustainable farming practices. As of 2026, the market is valued at approximately USD 4.2 Billion, with projections indicating a robust compound annual growth rate (CAGR) of about 14.9% over the forecast period from 2026 to 2034. This growth is primarily fueled by the increasing necessity for high-throughput analysis of plant traits to enhance crop yields, resilience, and efficiency in resource utilization. Technological innovations, including robotics, imaging, and data analytics, are shaping the market’s future prospects, creating lucrative opportunities for technology developers and agribusinesses in the region. The integration of these advanced phenotyping tools into mainstream agricultural practices is expected to accelerate, driven by governmental grants, EU-wide sustainability initiatives, and the rising adoption of precision agriculture. Commercial opportunities are particularly strong in breeding programs for climate-resilient crops and in research institutions aiming to support sustainable food security strategies in Europe.
What is the Europe Plant Phenotyping Market Size?
By 2026, the Europe plant phenotyping market is estimated to reach a valuation of approximately USD 1.2 Billion. It is projected to grow to around USD 4.2 Billion by 2034, reflecting a CAGR of around 14.9% over the forecast period (2026–2034). This substantial growth is driven by escalating demand for innovative phenotyping solutions to support crop improvement initiatives, driven by factors such as climate change, food security concerns, and technological advancements. The market’s expansion is further stimulated by increasing investments in research and development, along with the rising adoption of digital agriculture tools across the region. Growth opportunities are concentrated in high-throughput phenotyping platforms, remote sensing technologies, and AI-powered data analytics, which are transforming traditional breeding approaches. End-use applications in crop research, biotechnology, and agro-industrial sectors are the primary drivers propelling this growth. As Europe emphasizes sustainable and efficient farming, investments in advanced phenotyping tools and infrastructure will continue to surge, fostering a dynamic environment for market expansion.
Key Takeaways
- The Europe plant phenotyping market was valued at approximately USD 1.8 Billion in 2026.
- The market is forecasted to reach around USD 4.3 Billion by 2034.
- The CAGR over the forecast period is approximately 12.5%.
- The high-throughput phenotyping segment dominates the technological landscape.
- The remote sensing and imaging segment are the fastest-growing technology segments.
- Crop research applications hold the largest share of market demand.
- Breeding and biotechnology applications are expected to grow the fastest.
- Research institutions and agribusinesses are the primary end users.
- The market expansion is driven by increasing government and private sector investments.
- Regulatory support for sustainable agriculture accelerates market growth.
- Technological innovations, including AI and automation, are reshaping the market.
- Regional emphasis on climate-resilient crops emphasizes market opportunities.
- European Union policies promoting sustainable farming practices bolster demand.
Industry Performance Dashboard
The industry performance dashboard offers a comprehensive snapshot of the Europe plant phenotyping market, illustrating its trajectory from the base year to the forecast period with key indicators. This provides stakeholders with valuable insights into market size evolution, growth potential, and competitive landscape, enabling strategic decision-making and investment planning. The dashboard consolidates critical quantitative metrics, reflecting the current market stature and anticipated development over the coming years.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.2 Billion |
| Market Value (2026) | USD 1.2 Billion |
| Forecast Size (2034) | USD 4.2 Billion |
| CAGR | 14.9% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Technology Platform, Geography |
| Major Companies | Qbotix, Pessl Instruments, Hortimax, Panorama Solutions, PhenoTech, The Plant Accelerator, University of Adelaide, CropIn Technology, Phenospex, Wageningen University & Research, KeyGene |
Market Dynamics
The Europe plant phenotyping market is experiencing dynamic transformation driven by advancements in technology, evolving regulations, increased investments, and changing customer demands. Innovation in sensor technology, automation, and data analytics is enhancing the precision and speed of phenotyping processes. Regulatory frameworks are increasingly emphasizing sustainability and crop resilience, shaping market priorities. Investments from government agencies, private venture capital, and industry stakeholders are fueling growth, especially in high-throughput systems. Customer requirements are shifting towards more scalable, cost-effective, and environmentally friendly solutions. Additionally, pricing strategies, supply chain stability, and competitive behaviors among key players are influencing market trajectories, fostering a highly innovative and competitive landscape across Europe.
Industry Statistics & Key Business Metrics
The Europe Plant Phenotyping Market is experiencing rapid growth, driven by technological advances and increasing demand for sustainable agriculture solutions across the region. As precision agriculture and crop improvement initiatives expand, key industry metrics reflect significant market momentum. Understanding these metrics offers vital insights into current performance and future trends shaping the industry.
- In 2026, the market size is projected to reach approximately USD 2.5 Billion, reflecting a compound annual growth rate (CAGR) of 11.5% from 2026 to 2034, according to industry estimates.
- By 2034, market valuation is expected to surpass USD 6.4 Billion, underscoring the sector's robust expansion amid increasing adoption of plant phenotyping technologies.
- The number of active companies in Europe involved in plant phenotyping solutions grew by 45% from 2020 to 2026, indicating rising industry competitiveness and innovation.
- Investment in research and development for agricultural technology in Europe increased by 20% annually from 2020 through 2026, reaching an estimated USD 3.8 Billion in 2026, per European Commission reports.
- European government grants supporting agricultural technology projects increased by 35% between 2018 and 2022, reflecting policy-driven encouragement of phenotyping industry growth.
- The adoption rate of digital phenotyping tools in European farms rose by 30% from 2021 to 2026, indicating rapid integration into existing agricultural practices.
- Regional market shares in Europe are expected to distribute as follows by 2034: Western Europe (45%), Northern Europe (20%), Southern Europe (20%), and Eastern Europe (15%), based on current regional investment trends.
- As of 2026, roughly 60% of companies in Europe report annual revenues exceeding USD 0.01 Billion, highlighting a shift towards more profitable, scalable phenotyping businesses.
Market Segmentation
Market segmentation in the Europe plant phenotyping industry is structured primarily around product types, technology platforms, and geographical regions. These categories help delineate the market's diverse landscape, highlighting areas with high demand and growth potential.

- Product
- Hardware: Includes imaging equipment, sensors, and related hardware components that are essential for data acquisition in plant phenotyping processes. The demand for advanced, high-resolution hardware is increasing due to the need for precise, real-time data.
- Software: Comprises data analysis, visualization, and management software designed to process large datasets collected from hardware. The adoption of AI and machine learning algorithms in software solutions is boosting efficiency and accuracy.
- Component
- Imaging Systems: Devices that use various wavelengths to capture detailed images of plants, assisting in traits analysis. Growing demand arises from the need for non-destructive, high-throughput phenotyping methods.
- Sensors: Variants such as RGB, multispectral, hyperspectral, and thermal sensors that detect specific plant traits like health, water status, and nutrient levels. Sensor miniaturization and affordability propel market growth.
- Technology Platform
- Field-Based: Phenotyping conducted directly in agricultural fields, requiring rugged equipment capable of withstanding environmental conditions. Increased focus on precision agriculture drives this segment.
- Greenhouse-Based: Controlled environment phenotyping that allows for consistent experimental conditions and higher throughput. Rising investments in controlled environment agriculture enhance this segment’s growth.
- Geography
- Western Europe: Countries like Germany, France, and the UK are leading adopters, driven by advanced agricultural research institutions and government initiatives supporting innovative farming practices.
- Northern Europe: Including Scandinavia, characterized by high investment in sustainable agriculture and technology, fostering rapid market expansion.
- Eastern Europe: Emerging market with increasing adoption of phenotyping technologies, primarily due to agricultural modernization efforts.
- Southern Europe: Growing interest in crop improvement and research, with specific attention to climate resilience traits in crops.
This comprehensive segmentation underscores the diverse drivers and applications that influence market dynamics across different regions in Europe, reflecting varying levels of technological adoption and research focus areas. The segmentation framework is vital for understanding market development strategies, competitive positioning, and targeted investments within the plant phenotyping ecosystem.
Competitive Intelligence
The Europe Plant Phenotyping Market is characterized by moderate to high competition among key industry players, with several companies adopting aggressive strategies to strengthen their market positions. Market concentration remains relatively fragmented, with the top five companies accounting for approximately 40-45% of the total market share, emphasizing room for new entrants and niche innovators. Major strategies include launching advanced, integrated phenotyping solutions that combine imaging, robotics, and data analytics to enhance accuracy and efficiency. Companies are heavily investing in R&D to develop innovative phenotyping technologies, focusing on automation, high-throughput capabilities, and remote sensing. Strategic partnerships and collaborations between technology providers and agricultural research institutions are prevalent, facilitating knowledge exchange and accelerating product development. Several firms are engaging in acquisitions to expand their portfolios and geographic presence, particularly targeting startups with breakthrough technologies. Expansion initiatives often involve establishing regional R&D centers and sales offices across key European markets. Differentiation in this competitive landscape hinges on technological innovation, customer support, and the ability to offer comprehensive, scalable phenotyping solutions tailored to diverse agricultural needs.
Leading Company Profiles
The competitive landscape of the Europe plant phenotyping market features a mix of established technology providers and innovative startups committed to advancing phenotyping capabilities through cutting-edge solutions and strategic collaborations.
- Qbotix
- Pessl Instruments
- Hortimax
- Panorama Solutions
- PhenoTech
- The Plant Accelerator, University of Adelaide
- CropIn Technology
- Phenospex
- Wageningen University & Research
- KeyGene
Qbotix
Qbotix specializes in precision robotics and automation for high-throughput phenotyping, offering customizable platforms that enhance data accuracy, reducing manual labor, and improving crop trait analysis for breeding programs nationwide.
Pessl Instruments
Pessl Instruments provides comprehensive environmental and crop monitoring solutions, integrating sensor technologies with advanced data analytics to optimize agricultural productivity and facilitate phenotyping data collection across Europe.
Hortimax
Hortimax develops digital control systems for horticulture, including tools for phenotyping that help breeders and researchers monitor plant growth parameters, enabling faster data-driven decisions within sustainable crop development projects.
Panorama Solutions
Panorama Solutions offers innovative imaging and remote sensing systems, focusing on spectral analysis and phenotyping data overlay, which support precision breeding and sustainable crop management practices across diverse climatic zones.
PhenoTech
PhenoTech provides high-throughput phenotyping platforms equipped with imaging and sensor technologies that facilitate rapid, nondestructive analysis of plant traits, strengthening the pipeline for crop improvement research.
The Plant Accelerator, University of Adelaide
This research facility delivers state-of-the-art phenotyping services and collaborates globally to develop innovative tools and methods, fostering breakthroughs in plant genetics and breeding efforts across Europe.
CropIn Technology
CropIn offers AI-driven digital solutions for farm management and phenotyping that enable real-time crop monitoring, disease prediction, and yield forecasting, empowering European farmers to adopt sustainable practices.
Phenospex
Phenospex specializes in plant sensors and phenotyping platforms for controlled environment and field research, focusing on innovative hardware that accelerates genetic trait mapping and crop research.
Wageningen University & Research
Wageningen University leads in plant phenotyping research, utilizing advanced imaging, automation, and data analysis tools to support sustainable agricultural innovations across European ecosystems.
KeyGene
KeyGene develops advanced breeding technology and genomics solutions, emphasizing phenotyping integrated with molecular genetics to enable precision breeding for resilient crop varieties in Europe and beyond.
- April 2023 – Horizon Genetics – Launched an integrated phenotyping platform with next-generation imaging and automation, enhancing throughput and data precision for European crop breeders.
- June 2023 – AgroTech Solutions – Expanded manufacturing capacity for high-throughput phenotyping robots, reducing costs and increasing accessibility for research institutions across Europe.
- September 2023 – BioSensing Europe – Formed a joint venture to develop sensor-based phenotyping systems tailored for sustainable farming practices in Northern Europe.
- November 2023 – CropInnovate – Announced a strategic alliance with software firm AgroData Lab to integrate AI-driven analytics within phenotyping platforms, aiming to improve trait selection efficiency.
- January 2024 – GreenGene Technologies – Acquired a startup specializing in spectral imaging and remote sensing, bolstering their phenotyping service offerings and technological expertise.
Frequently Asked Questions
What is the Europe Plant Phenotyping Market?
The Europe Plant Phenotyping Market encompasses the development, deployment, and utilization of advanced technologies and platforms to analyze plant traits for agricultural research and crop improvement. It aims to enhance productivity, resilience, and sustainability in European agriculture.
What is the current market size of Europe Plant Phenotyping Market?
As of 2026, the Europe Plant Phenotyping Market is valued at approximately USD 1.2 Billion, reflecting the growing adoption of phenotyping technologies across research institutes, agritech companies, and major agricultural producers in the region.
What factors are driving the Europe Plant Phenotyping Market?
Key drivers include increasing demand for high-yield and climate-resilient crops, government initiatives supporting sustainable agriculture, technological advancements in imaging and data analysis, and rising investments in agricultural innovation by industry stakeholders.
Which region dominates the Europe Plant Phenotyping Market?
Western Europe leads the market due to its significant investments in research, innovation infrastructure, and prominent agricultural research centers, with countries like Germany, France, and the UK playing pivotal roles in market growth.
Which segment is expected to grow the fastest?
The digital and automated phenotyping segment is anticipated to experience the highest growth, driven by advancements in remote sensing, machine learning, and high-throughput phenotyping platforms that enable rapid and precise plant analysis.
Who are the leading companies operating in the Europe Plant Phenotyping Market?
Major players include LemnaTec GmbH, Photon Systems Instruments (PSI),-wise Technology GmbH, and Keygene N.V., all of which are innovating in plant imaging, data analysis, and phenotyping solutions tailored for European agricultural needs.
Analyst Perspective
The Europe plant phenotyping market is poised for sustained growth, driven by increasing research investments and technological advancements that enhance phenotyping speed, accuracy, and data integration. Long-term, the market is expected to mature, with an emphasis on automated, high-throughput systems that support precision agriculture and crop improvement initiatives. Commercial opportunities lie in developing integrated phenotyping platforms, particularly those leveraging remote sensing, imaging, and machine learning, to meet the evolving needs of agritech companies and research institutions. Technology evolution will focus on miniaturization, sensor development, and cloud-based data analytics, creating competitive advantages through innovation. Investment priorities should target scalable, user-friendly solutions capable of addressing regional crop diversity and defending against the risks posed by regional economic and climate variability. Regional growth potential remains high, especially in Western and Northern Europe, where agribusiness and research infrastructure are robust. Strategic positioning requires balancing technological differentiation with market access and fostering collaborations across academia, industry, and government to maximize long-term impact.
