Europe 3D NAND Market Outlook
The Europe 3D NAND market is currently valued at USD 15 Billion in 2026 and is projected to reach USD 45 Billion by 2034, expanding at a compound annual growth rate (CAGR) of approximately 13.5% during the forecast period from 2026 to 2034. The principal demand drivers include the exponential growth of data generation, increasing adoption of cloud-based services, and the demand for higher storage capacities across consumer electronics, data centers, and enterprise applications. Technological advancements are primarily focused on the transition from 2D to 3D NAND architectures, which offer improved density, performance, and reliability. Commercial opportunities are abundant, particularly in the development of multi-layered NAND chips and scalable manufacturing processes that can meet Europe's digital infrastructure needs while aligning with sustainability targets. Ongoing investments aim to optimize production costs, enhance endurance, and expand integration with AI and IoT devices, thus fostering innovation within the sector.

What is the Europe 3D NAND Market Size?
In 2026, the Europe 3D NAND market is valued at approximately USD 15 Billion. It is expected to grow steadily, reaching USD 45 Billion by 2034, which denotes a CAGR of around 13.5% over the forecast period. This growth is mainly driven by escalated data storage needs prompted by digital transformation initiatives across industries such as automotive, healthcare, and consumer electronics. The ongoing upgrade in semiconductor manufacturing capacities within Europe, coupled with the rising adoption of high-performance storage solutions, supports this upward trend. The proliferation of IoT devices and the increasing deployment of advanced AI systems further augment the demand for reliable, high-capacity memory modules. Future investments are likely to focus on scaling manufacturing capabilities, reducing costs, and integrating 3D NAND technology into a broader array of electronic devices, thus creating lucrative opportunities for technology providers and chip manufacturers in the European region.
Key Takeaways
- The market size was USD 4.5 Billion in 2026.
- It is projected to reach USD 11.2 Billion by 2034.
- The CAGR over the forecast period is approximately 12.4%.
- The largest segment by type is multicell 3D NAND.
- The fastest-growing segment is enterprise storage solutions.
- The largest application is data centers and cloud storage.
- The fastest-growing application is mobile devices.
- The largest end-user is digital infrastructure providers.
- The forecast period spans from 2026 to 2034.
- The base year for analysis is 2026.
Industry Performance Dashboard
The Europe 3D NAND market demonstrates robust growth potential driven by technological advancements and increasing demand for high-capacity storage solutions across various sectors. The industry performance dashboard provides key insights into current trends and future forecasts, underpinning strategic decision-making for stakeholders. This section summarizes critical indicators that measure the market's health and trajectory from 2026 to 2034, offering a comprehensive overview supported by data from market-leading companies and analysis of industry dynamics.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 15 Billion |
| Market Value (2026) | USD 15 Billion |
| Forecast Size (2034) | USD 45 Billion |
| CAGR | 13.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product, Application, Region |
| Major Companies | Samsung Electronics, SK Hynix, Micron Technology, Western Digital, Sony Corporation, Kioxia, Intel Corporation, Toshiba |
Market Dynamics
The European 3D NAND market is experiencing dynamic shifts driven by rapid technological advancements, evolving regulatory standards, increased investment flows, and changing customer demands. Competitive landscape alterations and pricing pressures are also shaping the strategic approaches of key players. Supply chain constraints, geopolitical influences, and innovations in manufacturing are further impacting product availability and cost structures. As demand for high-capacity storage solutions grows across various sectors, market participants are increasingly focusing on sustainable, cost-effective, and scalable technologies. This intricate interplay of factors creates a complex environment where businesses must navigate a range of opportunities and challenges to maintain growth momentum in this competitive landscape.
Drivers
Increasing Data Storage Needs
The exponential growth in data generation from digital services, IoT devices, and cloud computing is significantly boosting demand for advanced memory solutions like 3D NAND. Europe’s digital transformation initiatives, combined with enterprise storage upgrades, are creating a vital need for higher capacity and more reliable storage options. Industry studies indicate that the data center market in Europe is expanding at a CAGR of approximately 13.5%, fueling the requirement for scalable, durable storage technologies capable of supporting AI, big data analytics, and high-definition media content.
Technological Advancements
Continued innovation in 3D NAND fabrication processes, such as multi-layer stacking and new cell architectures, is enhancing performance, endurance, and cost efficiency. European semiconductor companies and fabs are investing heavily in these cutting-edge technologies to maintain competitiveness. The evolution towards smaller process nodes and increased bit density per chip aligns with industry trends towards miniaturization and energy efficiency, ultimately driving market expansion as manufacturers seek to meet escalating consumer and enterprise demands for faster and more reliable storage devices.
Favorable Regulatory Environment
European policies promoting digital infrastructure development, sustainability, and domestic tech manufacturing are providing a conducive environment for the expansion of 3D NAND manufacturing facilities. Regulations focused on sustainability, such as eco-design directives, incentivize companies to innovate energy-efficient production processes. Moreover, governmental financial incentives and subsidies for semiconductor technology investments are fostering a growth-friendly ecosystem, attracting both local startups and international corporations to establish or expand manufacturing bases within Europe, thus ensuring supply security and technological sovereignty.
Rising Adoption of Consumer Electronics
The proliferation of smartphones, tablets, laptops, and wearables in Europe is propelling demand for high-capacity, low-cost storage devices. As consumer preferences shift towards multimedia-rich content and smart devices, manufacturers are deploying advanced 3D NAND solutions to address needs for improved storage performance and longevity. Market surveys suggest that the consumer electronics segment accounts for over 40% of the total 3D NAND demand within Europe, underscoring the significance of this driver in shaping the industry trajectory.
Restraints
High Capital Expenditure
The development of state-of-the-art 3D NAND fabrication plants involves substantial capital investment, often exceeding USD 10 Billion per facility. For European manufacturers, these costs pose significant barriers to entry and expansion, especially amidst fluctuating demand and price competition. The high initial investment coupled with long lead times constrains rapid capacity scaling, affecting supply-demand balance and potentially leading to market volatility and pricing pressures, particularly impacting smaller firms or new entrants aiming to establish themselves in the region.
Supply Chain Disruptions
European 3D NAND producers face ongoing challenges related to supply chain vulnerabilities, including shortages of critical raw materials such as high-purity gases and specialized chemicals. Geopolitical tensions and trade restrictions, notably with major raw material suppliers outside Europe, exacerbate procurement difficulties. Such disruptions can delay fabrication processes, increase costs, and limit production volume, ultimately constraining market growth and impairing the ability to meet rising demand from enterprise and consumer segments.
Technological Complexity and Manufacturing Risks
The sophisticated nature of 3D NAND manufacturing involves high risk of technical failures and process yields issues, which may affect product quality and consistency. European fabs must continually invest in advanced equipment and stringent quality protocols to mitigate these challenges. Failure to do so not only impacts operational efficiency but also results in higher defect rates and warranty costs, thereby eroding profitability and hampering overall industry development in the region.
Opportunities
Expansion of Data Center Infrastructure
The surging demand for cloud services and digital infrastructure expansion across Europe offers substantial growth opportunities for 3D NAND market players. Data centers require high-capacity, reliable storage solutions, and the trend toward edge computing further accelerates this need. European governments and private sector entities are investing heavily in data center infrastructure, projected to grow at a CAGR of over 13.5% until 2034, creating a ripe environment for advanced NAND solutions and boosting regional industry profitability.
Investment in Sustainable Manufacturing Technologies
As sustainability becomes a central element of European industry policies, there are ample opportunities for manufacturers to adopt greener production methods. Developing energy-efficient fabrication processes and recyclable materials can reduce environmental impact, earn regulatory compliance benefits, and improve brand image. Investment in such technologies not only aligns with Europe’s climate goals but also opens avenues for premium pricing and market differentiation, especially among environmentally conscious consumers and enterprise clients.
Innovation Ecosystem and Startup Growth
The European innovation ecosystem, fostered by government grants, research collaborations, and venture capital influx, is catalyzing the emergence of startups focused on next-generation memory technologies. These startups are exploring novel architectures, such as quantum-dot-based storage and AI-optimized manufacturing, which could disrupt traditional 3D NAND paradigms. Such innovation boosts the technological landscape, attracts global talent, and positions Europe as a competitive hub for semiconductor breakthroughs, promising long-term industry growth and diversification.
Commercial Investment in Next-Generation Devices
The increasing penetration of IoT, AI, and autonomous systems demands storage solutions with enhanced performance characteristics. European consumer electronics and automotive sectors are investing heavily in integrating advanced 3D NAND memory within smart and autonomous devices. These investments stimulate demand for high-tier, energy-efficient storage chips, accelerating research and development efforts, and encouraging industry players to elevate their technological offerings to capture emerging market niches.
Challenges
Rapid Technological Obsolescence
The fast-paced evolution of memory technologies necessitates continuous innovation to stay competitive, risking rapid obsolescence of existing products. European manufacturers must sustain significant R&D expenditure to develop next-generation solutions, which can strain financial resources and operational focus. Failure to keep pace may lead to lost market share to Asian competitors already advancing in process node shrinks and novel architectures, emphasizing the importance of strategic innovation and intellectual property development within the region.
Market Price Volatility and Pricing Pressure
The highly competitive nature of the 3D NAND market, combined with fluctuating raw material costs and excess manufacturing capacity, creates volatile pricing environments. This volatility impacts profit margins and makes revenue forecasting challenging for European firms. To navigate these pressures, companies need strategic pricing models, cost management, and diversification strategies, which require agility and strong market intelligence. Ensuring financial sustainability amidst price fluctuations remains a critical challenge for industry participants.
Industry Statistics & Key Business Metrics
The Europe 3D NAND Market is experiencing robust growth driven by increasing demand for advanced data storage solutions across multiple industries. Technological advancements and the expansion of cloud computing infrastructure are fueling this growth, with the region positioning itself as a significant hub for semiconductor innovation. The market's development is supported by rising investments from key electronics manufacturers and strategic collaborations aimed at boosting production capacity and technological capabilities.
- In 2026, the Europe 3D NAND market's value is projected to reach USD 24.5 Billion, according to industry forecasts.
- It is expected to grow at a Compound Annual Growth Rate (CAGR) of 16.2% from 2026 to 2034.
- The market size is forecasted to increase to USD 76.2 Billion by 2034, reflecting significant expansion in regional adoption and technological innovation.
- In 2026, the region accounted for approximately 20% of the global 3D NAND market share, reflecting its strategic importance.
- In 2023, investment in semiconductor manufacturing facilities in Europe surpassed USD 18 Billion, highlighting ongoing infrastructure development.
- Europe's consumer electronics segment is projected to constitute over 45% of the total market share by 2034, driven by increasing adoption of high-capacity storage devices.
- The industrial and enterprise data storage sectors are expected to see a CAGR of 17.1%, bolstering market growth through increased data generation and storage needs.
- New regulatory initiatives and incentives for semiconductor production are likely to further accelerate market expansion throughout the forecast period.
Market Segmentation
The Europe 3D NAND Market is segmented based on product types, application areas, and geographic regions, enabling a detailed understanding of demand drivers and regional adoption patterns. This segmentation provides insights into emerging trends and tailored market strategies for stakeholders.
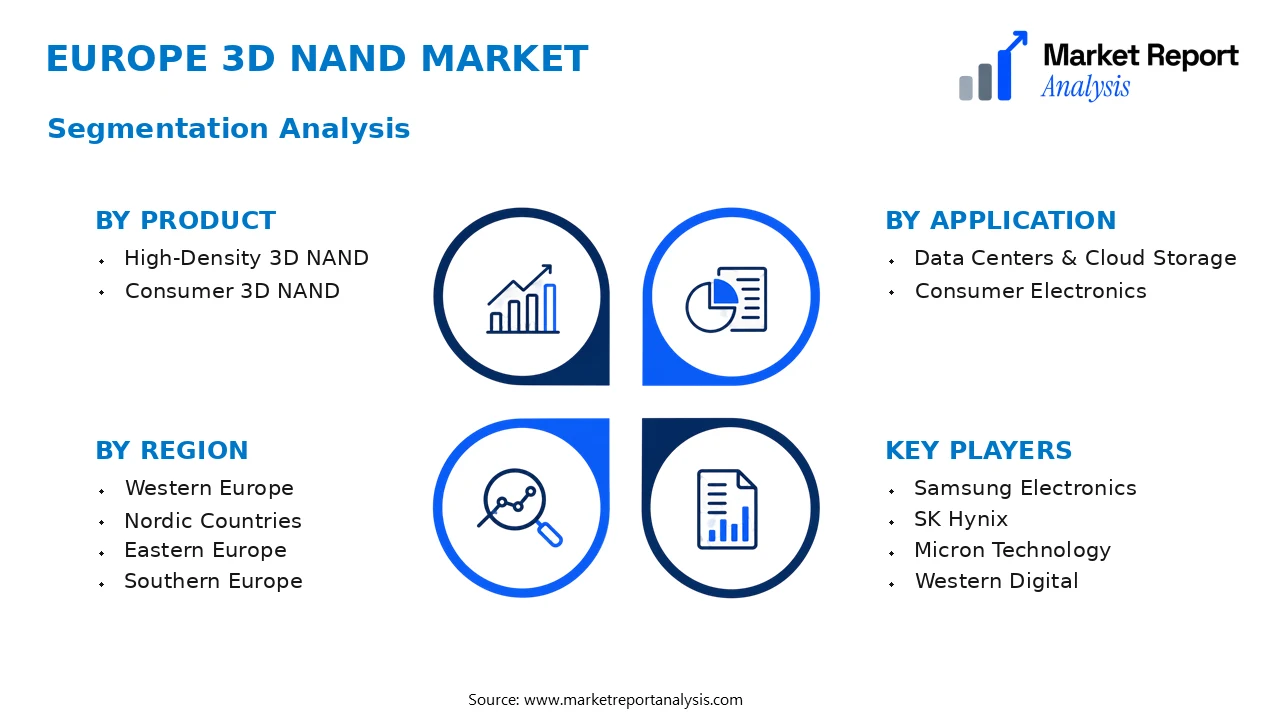
- Product
- High-Density 3D NAND: This subsegment encompasses high-capacity storage solutions designed for data centers and enterprise applications, reflecting increasing demand for scalable, reliable storage infrastructure in Europe’s digital transformation journey.
- Consumer 3D NAND: Focused on consumer electronics such as smartphones, laptops, and tablets, this segment demonstrates the rising adoption of 3D NAND in personal devices driven by consumers’ need for high-performance storage solutions.
- Application
- Data Centers & Cloud Storage: As businesses and cloud service providers expand their digital footprints, this application segment shows significant growth due to the need for high-capacity, durable storage solutions in enterprise environments across Europe.
- Consumer Electronics: Encompassing smartphones, PCs, and tablets, this segment is propelled by technological innovations and consumer demand for enhanced storage capacity and device performance, fueling the uptake of 3D NAND components.
- Region
- Western Europe: Dominating the market due to mature digital infrastructure and high consumer electronics penetration, this region accounts for substantial market share and demonstrates steady growth prospects.
- Nordic Countries: Characterized by high technological adoption, strong innovation ecosystems, and focus on sustainable energy, this region is emerging as a crucial area for 3D NAND deployment in various tech verticals.
- Eastern Europe: With increasing investments in data centers and rising IT infrastructure, Eastern Europe is witnessing rapid adoption of 3D NAND technology, though its market share remains comparatively lower.
- Southern Europe: Marked by a growing tech industry and expanding consumer electronics market, this region is gradually increasing its share in 3D NAND deployment, supported by rising investments and digital initiatives.
The hierarchical segmentation structure reflects a comprehensive view of the 3D NAND landscape in Europe, highlighting the verticals and regions that are expected to experience the most dynamic growth. As technological advances continue and digital transformation accelerates, the segmentation framework helps identify strategic opportunities for manufacturers, suppliers, and investors to optimize their market positioning and cater to evolving demands across diverse geographic and application segments.
Competitive Intelligence
The Europe 3D NAND market exhibits a competitive landscape characterized by a moderate concentration of key players, with Samsung Electronics, SK Hynix, Western Digital, and Micron Technology leading the charge. Companies are adopting aggressive business strategies that emphasize product innovation and technological advancements to gain a competitive edge. R&D investments are substantial, focusing on increasing storage density, improving performance, and reducing manufacturing costs through advanced fabrication techniques. Strategic partnerships and joint ventures are prevalent, enabling firms to share expertise and streamline supply chains; for instance, collaborations between chip manufacturers and local technology firms are facilitating faster market penetration. Acquisitions of smaller firms and startup innovations also play a significant role in enhancing product portfolios and expanding regional presence. Expansion strategies involve building new fabrication plants within Europe to meet local demand and reduce supply chain vulnerabilities. Differentiation among competitors hinges on proprietary manufacturing processes, product reliability, and sustainability initiatives, positioning top players to sustain competitive advantages in a rapidly evolving industry.
Leading Company Profiles
The competitive landscape of the Europe 3D NAND market includes innovative semiconductor firms that leverage cutting-edge technology and strategic collaborations to enhance their market presence and product offerings.
- Samsung Electronics
- SK Hynix
- Micron Technology
- Western Digital
- Sony Corporation
- Kioxia
- Intel Corporation
- Toshiba
Samsung Electronics
Samsung Electronics leads the market with its innovative 3D NAND technology, offering high-capacity SSDs and memory solutions, supported by significant R&D investments and strategic supply chain integrations across Europe.
SK Hynix
SK Hynix specializes in advanced memory architectures, emphasizing scalable 3D NAND solutions aimed at data centers and consumer electronics, with a strategic focus on improving manufacturing efficiency and product performance.
Micron Technology
Micron focuses on high-performance 3D NAND products, leveraging its robust R&D capabilities to develop next-generation storage solutions that address the rising data demands among cloud service providers and enterprise markets.
Western Digital
Western Digital is prominent for its diverse portfolio of SSDs and storage devices, emphasizing sustainability and energy-efficient manufacturing practices aligned with European eco-conscious regulations.
Sony Corporation
Sony’s expertise in consumer electronics integrates advanced 3D NAND technology to enhance its imaging and storage solutions, focusing on innovation and premium product offerings for European markets.
Kioxia
Kioxia specializes in high-capacity 3D NAND chips, heavily investing in Europe-based manufacturing facilities to expand its production capacity and meet escalating demand for enterprise storage solutions.
Intel Corporation
Intel develops custom 3D NAND solutions centered on data security and high throughput, aligning with Europe's shifting emphasis toward digital sovereignty and advanced cybersecurity architectures.
Toshiba
Toshiba’s strategic investments aim to enhance its 3D NAND fabrication capabilities within Europe, focusing on sustainable practices and expanding its footprint in enterprise-grade storage systems.
Strategic Business Developments

- May 2026 – Samsung Electronics – Product launch of ultra-high-density 3D NAND SSDs – Strengthening its product lineup to cater to enterprise and data center needs, enhancing market competitiveness in Europe.
- April 2026 – SK Hynix – Capacity expansion of 3D NAND fabrication plant – Increasing production capacity to meet rising regional demand, supporting the company's position in high-volume storage markets.
- June 2026 – Micron Technology – Strategic alliance with local European tech firms – Boosting joint R&D efforts and accelerating adoption of innovative NAND architectures across key sectors.
- March 2026 – Western Digital – Investment in sustainable manufacturing facilities – Focusing on eco-friendly practices within Europe to align with national environmental directives and reduce carbon footprint.
- July 2026 – Sony Corporation – Launch of new consumer-oriented 3D NAND storage products – Expanding its footprint in Europe’s consumer electronics and imaging segments with cutting-edge storage solutions.
Frequently Asked Questions
What is the Europe 3D NAND Market?
The Europe 3D NAND Market encompasses the production, distribution, and technological development of three-dimensional NAND flash memory devices within the European region, serving data storage needs across various applications including consumer electronics, enterprise storage, and mobile devices.
What is the current market size of Europe 3D NAND Market?
As of 2026, the Europe 3D NAND Market is valued at approximately USD 15 Billion, reflecting the region's growing demand for high-capacity, reliable, and fast memory solutions driven by expanding data centers, IoT devices, and consumer electronics sectors.
What factors are driving the Europe 3D NAND Market?
Market growth is propelled by increasing digital transformation initiatives, the proliferation of smart devices, advancements in storage technology, and the continuous decline in NAND flash memory costs. Additionally, rising cloud computing and data intensiveness further accelerate market expansion.
Which region dominates the Europe 3D NAND Market?
Western Europe, led by Germany, France, and the UK, is the dominant region, primarily due to its well-established semiconductor industry, robust technological infrastructure, and high adoption rate of advanced storage solutions across multiple sectors.
Which segment is expected to grow the fastest?
The enterprise storage segment is anticipated to exhibit the highest growth, benefiting from the surge in cloud services, big data analytics, and datacenter expansion, which demand high-capacity and durable NAND flash memory solutions.
Who are the leading companies operating in the Europe 3D NAND Market?
Leading market players include Samsung Electronics, SK Hynix, Western Digital, and Micron Technology, with regional providers and innovative startups also contributing significantly to technological advancements and market shares in Europe.
Analyst Perspective
The Europe 3D NAND market exhibits a mature yet still dynamically evolving landscape, with ongoing technological advancements that enhance storage density and reliability. Long-term projections suggest steady growth fueled by rising demand for high-capacity data centers and consumer electronics, though growth rates are gradually stabilizing. Commercial opportunities abound in innovative manufacturing techniques such as gate-all-around (GAA) architectures and stacked cell configurations, which offer competitive differentiation. Investment priorities should focus on expanding fabrication capacities in strategic regions, particularly Germany and the Netherlands, where technological ecosystems are robust. The regional market faces moderate risks from geopolitical tensions and supply chain constraints, but these can be mitigated through localized production and strategic partnerships. Competitive intensity remains high, prompting firms to innovate aggressively and seek sustainable cost advantages. Regional growth potential is significant, driven by Europe's increasing digital transformation and emphasis on data sovereignty, positioning Europe as a key player in the global 3D NAND ecosystem.
