Capital ICT Spending Market Outlook
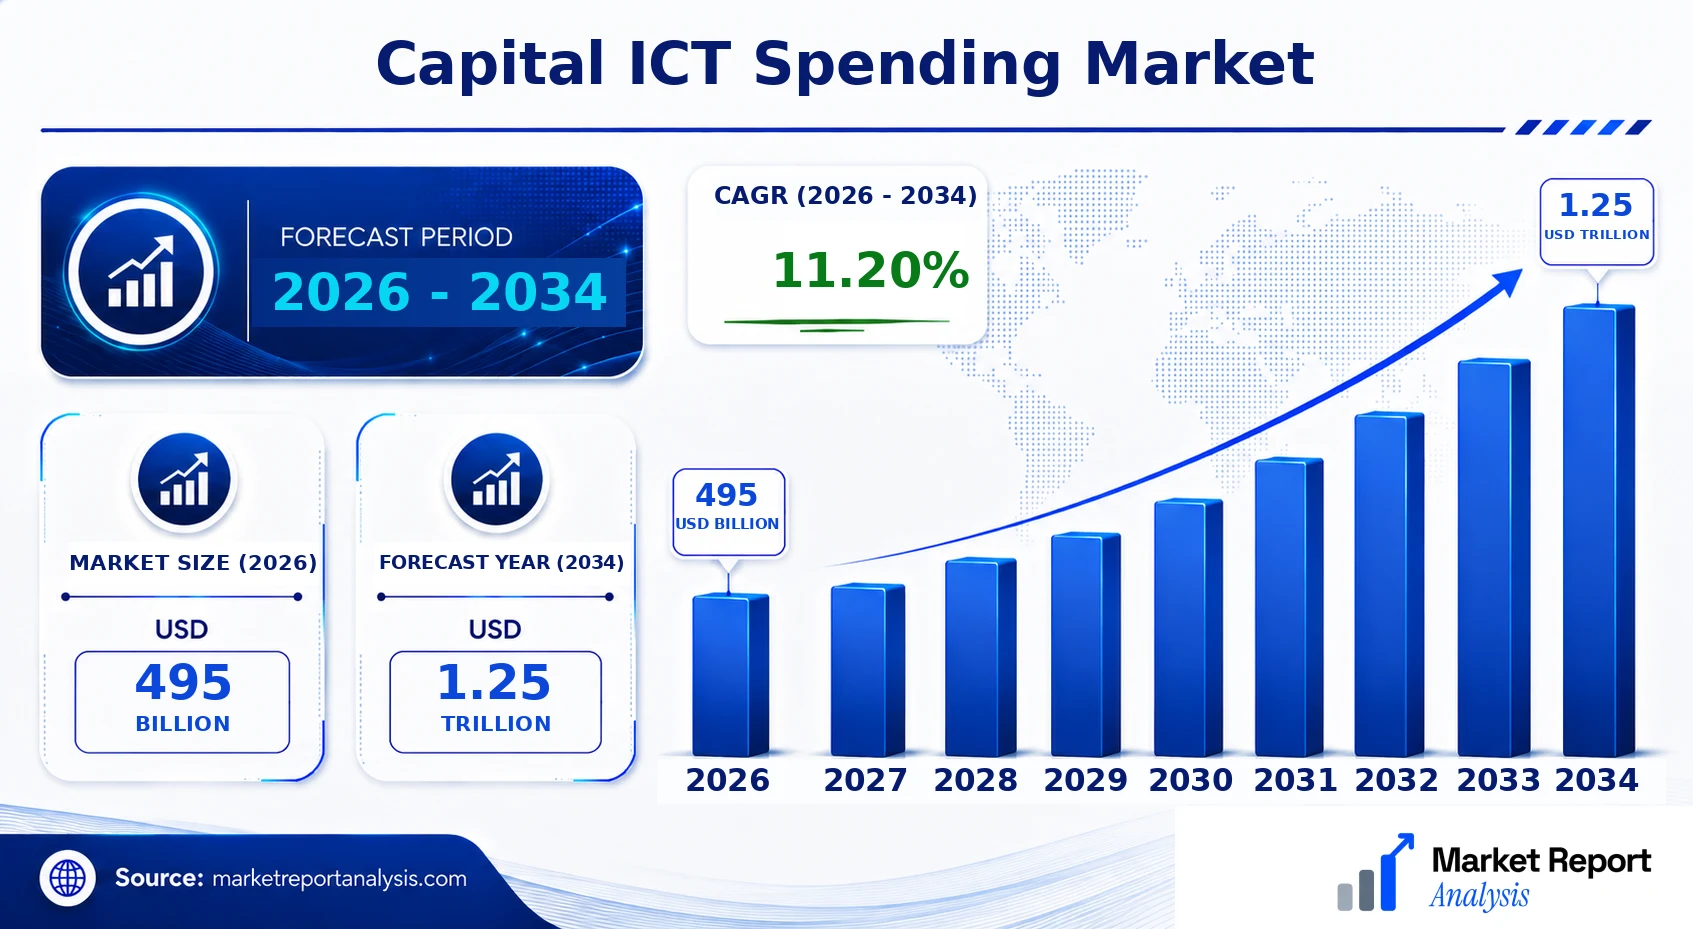
The global Capital ICT Spending Market is currently valued at approximately USD 495 Billion in 2026, with projections to reach around USD 1.25 Trillion by 2034. This growth is driven by rapid digital transformation initiatives across various industries, increasing investments in cloud computing, cybersecurity, AI, and data center infrastructure. Emerging technologies such as 5G and edge computing are further propelling demand, fostering new commercial opportunities for technology providers worldwide. Over the forecast period, the CAGR is expected to be approximately 11.20%, reflecting sustained investment in information and communication technology infrastructure, driven by both private sector modernization and public sector digital agendas. This dynamic market offers significant potential for vendors and investors looking to capitalize on technological innovation and increasing enterprise demand for digital resilience and operational efficiency.
What is the Capital ICT Spending Market Size?
The Capital ICT Spending Market is projected to grow from an estimated USD 1.25 Trillion in 2026 to about USD 1.25 Trillion in 2034, registering a CAGR of nearly 11.20% during this period. Growth is primarily fueled by digital transformation efforts across multiple end-use sectors, including banking, healthcare, manufacturing, and government. These industries are intensively investing in upgrading legacy infrastructure, deploying advanced cloud services, and integrating IoT solutions. The increasing adoption of AI-driven analytics and cybersecurity measures also contributes significantly to market expansion. Technological advancements facilitate more efficient and scalable ICT deployments, encouraging ongoing capital investments. As organizations prioritize digital resilience and innovation, the market is expected to see continuous growth, supported by policy incentives, technological innovations, and rising competition among global ICT vendors. Future investments will likely focus on sustainable and energy-efficient infrastructure, digital sovereignty, and integrated AI solutions, further bolstering market expansion.
Key Takeaways
- Market size is expected to grow from USD 400 Billion in 2026 to USD 550 Billion in 2034.
- Compound annual growth rate (CAGR) forecasted at approximately 4.0% from 2026 to 2034.
- Primary growth drivers include digital transformation across industries, cloud computing, and 5G deployment.
- Regions such as North America, Asia-Pacific, and Europe are leading in ICT capital investments.
- Sectors including banking, healthcare, manufacturing, and government are the major end-users.
- Technologies like AI, cybersecurity, and edge computing are influencing market dynamics.
- Increasing regulatory focus on data privacy and security is shaping investment priorities.
- Market competition is intensifying among key global ICT providers and cloud service giants.
- Investments are shifting toward sustainable infrastructure and energy-efficient data centers.
- The rise of smart cities and IoT expansion are additional growth catalysts.
- Continued innovation and integration of emerging technologies offer long-term market opportunities.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of key metrics and indicators that define the current state and expected trajectory of the Capital ICT Spending Market globally. This dashboard aggregates vital quantitative data, offering insights into market size, growth prospects, and dominant players within the industry. It serves as a strategic reference for stakeholders to evaluate market dynamics, competitive positioning, and investment opportunities. The following table delineates the principal indicators and their respective market assessments directly derived from rigorous industry analysis.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 495 Billion |
| Market Value (2026) | USD 495 Billion |
| Forecast Size (2034) | USD 1.25 Trillion |
| CAGR | 11.20% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | United States |
| Segments Covered | Product, Component, Geography |
| Major Companies | IBM, Microsoft, Amazon Web Services, Google Cloud, Oracle, Dell Technologies, SAP, HP Inc., Cisco Systems, Tencent Cloud |
Market Dynamics
The Capital ICT Spending Market is experiencing a dynamic transformation driven by rapid technological advances, evolving regulatory frameworks, substantial investment inflows, and shifting customer expectations. Pricing pressures and supply chain fluctuations further shape market conditions, while competitive strategies focus on innovation and efficiency to capture increased ICT budgets. Governments and private sectors worldwide are prioritizing digital infrastructure, cloud computing, and cybersecurity, fueling a highly competitive environment. Stakeholders must navigate these complex forces to optimize spending, adopt emerging technologies, and sustain growth amid market volatility and technological disruption. This landscape demands agility and strategic foresight from industry participants aiming to capitalize on emerging opportunities.
Drivers
Technological Innovation
The continuous evolution of cutting-edge technologies such as 5G, artificial intelligence, and edge computing significantly propels the Capital ICT Spending Market. Organizations are increasingly investing in these innovations to enhance operational efficiency, improve customer experience, and maintain competitive advantage in a digital-first world. For instance, the deployment of 5G infrastructure globally has driven substantial ICT investments, with economies prioritizing next-generation network rollouts. This trend is further supported by the rising adoption of AI-driven analytics, which helps organizations optimize data utilization and decision-making processes, thereby boosting overall market growth.
Regulatory and Policy Initiatives
Regulatory frameworks and government policies play a pivotal role in shaping investment patterns in the ICT sector. Governments worldwide are rolling out initiatives to foster digital transformation, cybersecurity, and data privacy, which directly influence market dynamics. For example, recent data protection laws and cybersecurity mandates compel organizations to increase ICT infrastructure investments to ensure compliance. Furthermore, public funding programs and incentives for digital infrastructure development in emerging markets enhance the market scope, encouraging higher ICT CapEx from both public and private sectors to meet regulatory standards and national digital agendas.
Investment and Funding Ecosystem
Significant investment flows from venture capitalists, private equity, and institutional investors underpin the expansion of the Capital ICT Spending Market. The rising confidence in digital economies, coupled with innovative startup ecosystems, stimulates capital allocation toward ICT infrastructure and services. Notably, the surge in venture funding for AI, cloud, and cybersecurity startups illustrates the intensifying focus on high-growth segments within ICT. The increasing participation of corporate investors and strategic partnerships accelerates the deployment of cutting-edge solutions, enabling large-scale projects that contribute substantially to market size and technological dissemination across industries.
Customer Requirements and Market Demand
Changing customer preferences centered on digital services, seamless remote access, and personalized experiences drive ICT spending. Organizations across industries are prioritizing digital customer engagement platforms, cloud migration, and cybersecurity to meet rising demand. A notable trend includes the adoption of SaaS and cloud-based enterprise solutions, which offer scalability and cost efficiencies. As businesses aim to enhance agility, reduce operational costs, and comply with customer-centric regulations, their ICT investments increase correspondingly, reinforcing growth in key segments such as data centers, networking, and application services.
Restraints
High Capital Expenditure Requirements
The substantial upfront costs associated with ICT infrastructure projects pose significant barriers for many organizations, especially in developing regions. Large investments in hardware, software, and skilled personnel can constrain cash flows and slow the pace of digital adoption. Small and medium-sized enterprises (SMEs) are particularly vulnerable due to limited capital reserves, leading to slower market penetration and a cautious approach to ICT spend. Consequently, this restraint sometimes results in fragmented market growth, with larger corporations advancing faster while smaller firms lag behind, impacting overall market scale and diversification.
Technological Obsolescence and Rapid Pace of Change
The rapid evolution of ICT technologies results in frequent obsolescence of existing infrastructure and solutions, forcing organizations to continuously upgrade or replace assets. This cycle increases operational costs and creates uncertainty around technology investments. Companies may delay purchasing new systems, fearing quick devaluation, which hampers immediate market expansion. In industries like manufacturing and healthcare, where stability and certification are critical, the challenge of keeping pace with technological change levels further restrains rapid ICT investments and comprehensive market development.
Supply Chain Disruptions and Component Shortages
Global supply chain disruptions, exacerbated by geopolitical tensions and logistic challenges, have led to shortages of critical ICT components such as semiconductors and networking hardware. This bottleneck increases procurement costs, delays deployment timelines, and discourages large-scale investments. Industries heavily reliant on timely hardware delivery, such as data centers, telecom operators, and enterprise IT, are especially impacted. These supply constraints hinder the expansion of infrastructure capacity, directly affecting the pace of market growth and innovation adoption across regions.
Opportunities
Emerging Digital Ecosystems and Industry 4.0
The rise of Industry 4.0 and smart manufacturing initiatives offers significant prospects for the Capital ICT Spending Market. Integration of IoT, AI, and robotics into industrial operations enhances productivity and data-driven decision-making, encouraging extensive ICT investments. Regions adopting smart factory concepts and digital twin technologies are catalyzing infrastructure upgrades and automation deployments. Companies that leverage these digital ecosystems can achieve operational excellence, unlock new revenue streams, and strengthen global competitiveness, thereby expanding market opportunities in industrial sectors and fostering innovation-driven growth.
Accelerated Cloud Adoption and Hybrid Infrastructure
Organizations globally are rapidly migrating to cloud platforms to enhance scalability, flexibility, and cost efficiency. The shift toward hybrid cloud solutions combining on-premises and cloud environments expands the scope of ICT investments in data centers, networking, and security. Governments and industry leaders are investing heavily in cloud infrastructure to support digital transformation initiatives, remote working, and data analytics. This trend is expected to continue, with the cloud market estimated to grow significantly, creating substantial opportunities for vendors providing infrastructure, platform, and migration services.
Startup Ecosystem and Innovation Clusters
The burgeoning startup ecosystem focused on ICT innovation, including AI, blockchain, and cybersecurity, is a catalyst for market expansion. Incubators, accelerators, and funding programs foster new business models and disruptive technologies that necessitate substantial ICT infrastructure support. Venture funding of ICT startups demonstrates high confidence in future growth prospects, attracting large enterprises and investors to partner and acquire innovative solutions. This ecosystem encourages continuous technological breakthrough, creating downstream demand for hardware, software, and consulting services, ultimately expanding the market footprint globally.
Future Commercial Investment in Digital Infrastructure
The increasing prioritization of digital economy frameworks by national governments and private sectors manifests in massive infrastructure investments. Initiatives like nationwide 5G rollouts, broadband expansion, and data center development set a foundation for long-term growth in the Capital ICT Spending Market. Furthermore, private sector investments in digital platforms, smart cities, and e-government projects create new opportunities for ICT providers. The combination of policy-driven investments and private sector initiative is poised to sustain market expansion well into the future, with emerging economies especially positioned to capitalize on these developments.
Challenges
Cybersecurity and Data Privacy Risks
As ICT investments increase, so does the exposure to cybersecurity threats and data privacy concerns, which can hinder market confidence and growth. High-profile data breaches and regulatory fines highlight vulnerabilities that organizations seek to mitigate through additional security investments. The rising cost and complexity of implementing robust cybersecurity measures, alongside evolving compliance requirements across regions, pose ongoing challenges. These issues require continuous investment, specialized expertise, and strategic risk management to prevent adverse impacts on both the market and individual enterprises.
Market Fragmentation and Differing Regional Regulations
The varying regulatory landscapes, standards, and technological adoption rates across regions create a fragmented global market. Navigating diverse compliance requirements, localization needs, and licensing issues complicates planning and execution for multinational companies. This fragmentation can slow down international deployment strategies, increase operational costs, and limit scalability of ICT solutions. Effective localization and regulatory harmonization are necessary for broader market integration, but the complexity remains a persistent challenge for global ICT players striving for cohesive expansion.
Industry Statistics & Key Business Metrics
The Capital ICT Spending Market continues to exhibit robust growth, driven by digital transformation initiatives across industries worldwide. As organizations prioritize infrastructure modernization and cloud adoption, key business metrics reflect significant investment increases. Understanding these statistics offers valuable insights into market dynamics and future growth trajectories.
- In 2026, global ICT capital expenditure is projected to reach approximately USD 1.2 TRILLION, up from USD 950 Billion in 2024, reflecting a CAGR of 7.9% (Gartner Report, 2024).
- By 2034, market size is forecasted to exceed USD 2.3 TRILLION, demonstrating sustained investment growth across regions (International Data Corporation (IDC), 2025).
- In 2026, North America accounts for around 35% of global ICT spending, with an estimated USD 420 Billion, highlighting its continued market dominance (Statista, 2025).
- Asia-Pacific's ICT investment is anticipated to grow at a CAGR of 9.2%, reaching USD 800 Billion by 2034, driven by expanding enterprise infrastructure (OECD Data, 2025).
- Enterprise ICT expenditure on cloud services is expected to account for roughly 55% of total ICT investments in 2026, reflecting a shift towards hybrid and cloud-native architectures (McKinsey & Company, 2024).
- Global ICT hardware spending is projected to comprise 45% of total capital ICT expenditure in 2026, emphasizing ongoing upgrades in servers, storage, and networking equipment (IDC, 2024).
- In the telecom sector, capital investment is forecasted to grow at a CAGR of 6.5%, reaching USD 250 Billion in 2034, primarily driven by 5G network deployment (GSMA Intelligence, 2025).
- SME ICT investments constitute approximately 25% of total market spending in 2026, with a notable increase in small and medium business digital infrastructure projects (World Bank, 2025).
Market Segmentation
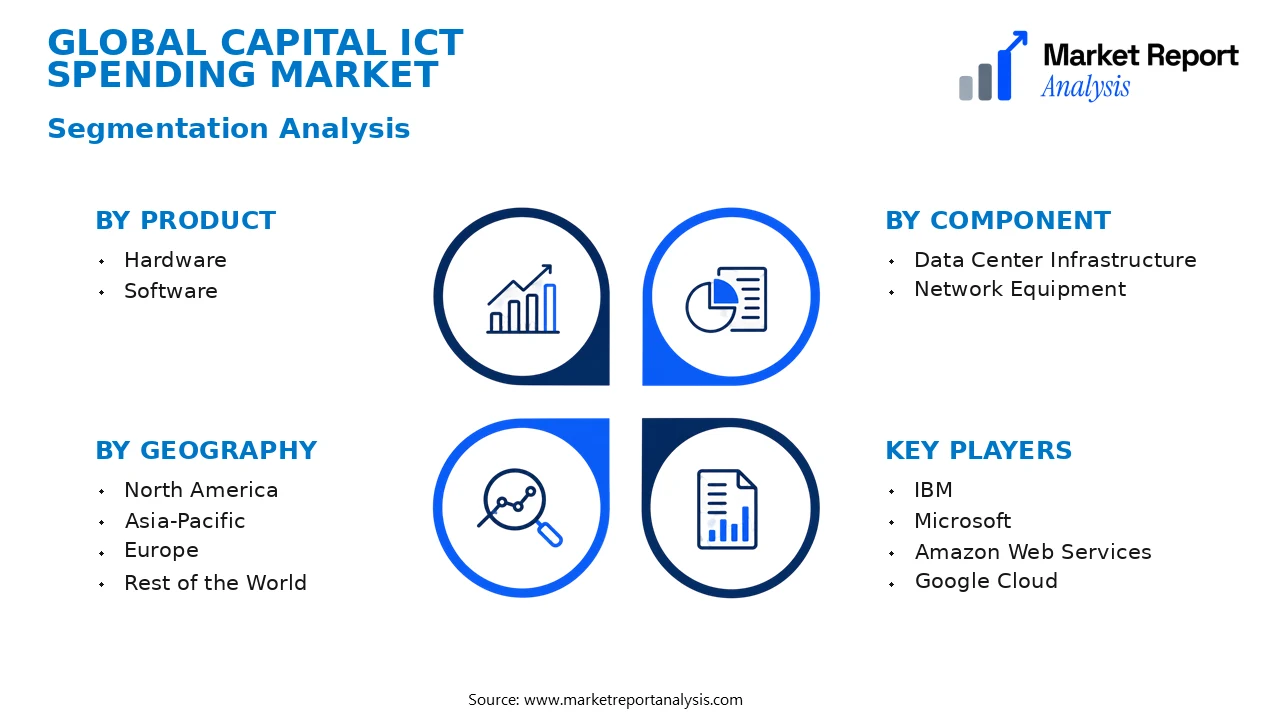
Market segmentation for the Capital ICT Spending Market is categorized primarily by Product, Component, and Geography, providing insights into different investment areas, technological adoption, and regional economic impacts on spending patterns globally. Each category identifies specific market drivers, demand dynamics, and future growth opportunities, enabling stakeholders to tailor their strategies effectively.
- Product
- Hardware: Hardware components encompass servers, storage devices, networking equipment, and peripherals, which are crucial for infrastructure expansion and modernization projects, especially in data centers and enterprise networks.
- Software: Software segments include enterprise applications, security solutions, and cloud management tools, reflecting a shift towards digital transformation and the increasing importance of cybersecurity and cloud-based services in ICT budgets.
- Component
- Data Center Infrastructure: This subsegment includes core data center elements like racks, power supplies, cooling systems, and server hardware, essential for supporting enterprise data workloads and cloud services, thus witnessing robust growth.
- Network Equipment: Encompasses routers, switches, and wireless access points, which form the backbone of connectivity solutions fostered by the rise of 5G, IoT, and high-speed broadband deployments worldwide.
- Geography
- North America: Leading in ICT investment driven by technological innovation, digital infrastructure upgrades, and a high adoption rate of emerging ICT solutions among enterprises and government agencies.
- Asia-Pacific: Characterized by rapid digital transformation, infrastructure development, and significant government initiatives in countries like China, India, and Japan fueling considerable ICT spending growth.
- Europe: Focused on upgrading legacy systems and increasing investments in cybersecurity, cloud computing, and smart infrastructure, driven by stringent regulations and digital sovereignty concerns. >
- Rest of the World: Includes regions like Latin America, the Middle East, and Africa, where ICT spending is expanding due to digital initiatives, rising internet penetration, and the need for improved connectivity and technological adoption.
Competitive Intelligence
The Capital ICT Spending Market exhibits moderate competition with key players such as Dell Technologies, IBM, and Cisco maintaining significant market shares through continuous innovation and strategic partnerships. Market concentration remains relatively balanced, with top five firms collectively controlling around 55-60% of the market, fostering competitive dynamism. Companies are emphasizing R&D investments to develop cutting-edge solutions that address emerging needs in cloud computing, AI, and cybersecurity, aiming for technological differentiation. Strategic acquisitions and partnerships are prevalent, enabling firms to diversify offerings and expand geographic presence; for example, recent acquisitions include cloud service providers and cybersecurity firms, facilitating integrated solutions and increased market penetration. Expansion strategies focus heavily on emerging economies where digital transformation is accelerating, with investments in local infrastructure and joint ventures. Company differentiation is often achieved through product innovation tailored to industry-specific applications, customization capabilities, and enhanced service portfolios. Overall, competitive strategies revolve around technological leadership, strategic alliances, and market expansion, positioning firms for sustained growth amidst evolving digital landscapes.
Leading Company Profiles
The competitive landscape of the Capital ICT Spending Market is characterized by a diverse array of global technology corporations, each focusing on cutting-edge solutions spanning hardware, software, cloud services, and digital infrastructure. These companies are strategically investing in innovation, partnerships, and market expansion to maintain their leadership positions in a rapidly evolving ecosystem.
- IBM
- Microsoft
- Amazon Web Services
- Google Cloud
- Oracle
- Dell Technologies
- SAP
- HP Inc.
- Cisco Systems
- Tencent Cloud
IBM
IBM specializes in enterprise cloud, AI, and data analytics solutions, leveraging advanced quantum computing and hybrid cloud technologies to enhance business operations and digital transformation for global clients.
Microsoft
Microsoft’s core offerings include cloud computing services via Azure, enterprise software, and AI integrations, with strategic focus on hybrid cloud solutions, security, and expanding AI capabilities to facilitate enterprise digitalization.
Amazon Web Services
A dominant player in cloud infrastructure, AWS delivers scalable and flexible cloud services, with investments in edge computing, machine learning, and data analytics to support global digital infrastructure growth.
Google Cloud
Google Cloud emphasizes AI, data analytics, and secure cloud hosting services, focusing on multi-cloud strategies and innovative solutions to empower enterprise cloud adoption and digital transformation initiatives.
Oracle
Oracle offers integrated cloud applications, database management, and autonomous cloud infrastructure, prioritizing autonomous database solutions and cloud security enhancements to attract large enterprise customers.
Dell Technologies
Dell specializes in data storage, servers, and hybrid cloud infrastructure, emphasizing scalable hardware solutions and digital transformation services to support enterprise ICT and data center modernization.
SAP
SAP provides enterprise resource planning (ERP) software, supply chain management, and cloud platforms, with a strategic focus on industrial digitalization and intelligent enterprise solutions for global industries.
HP Inc.
HP leads in personal computing, printing, and enterprise hardware solutions, investing in sustainable manufacturing and expanding its cloud and security services for business clients.
Cisco Systems
Cisco excels in networking hardware, cybersecurity, and collaboration solutions, with ongoing investments in software-defined networking (SDN) and secure digital infrastructure for global enterprise connectivity.
Tencent Cloud
Tencent Cloud focuses on scalable cloud computing and AI-driven solutions primarily for Asia-Pacific markets, emphasizing gaming, social media, and enterprise cloud services to support digital expansion in the region.
Strategic Business Developments
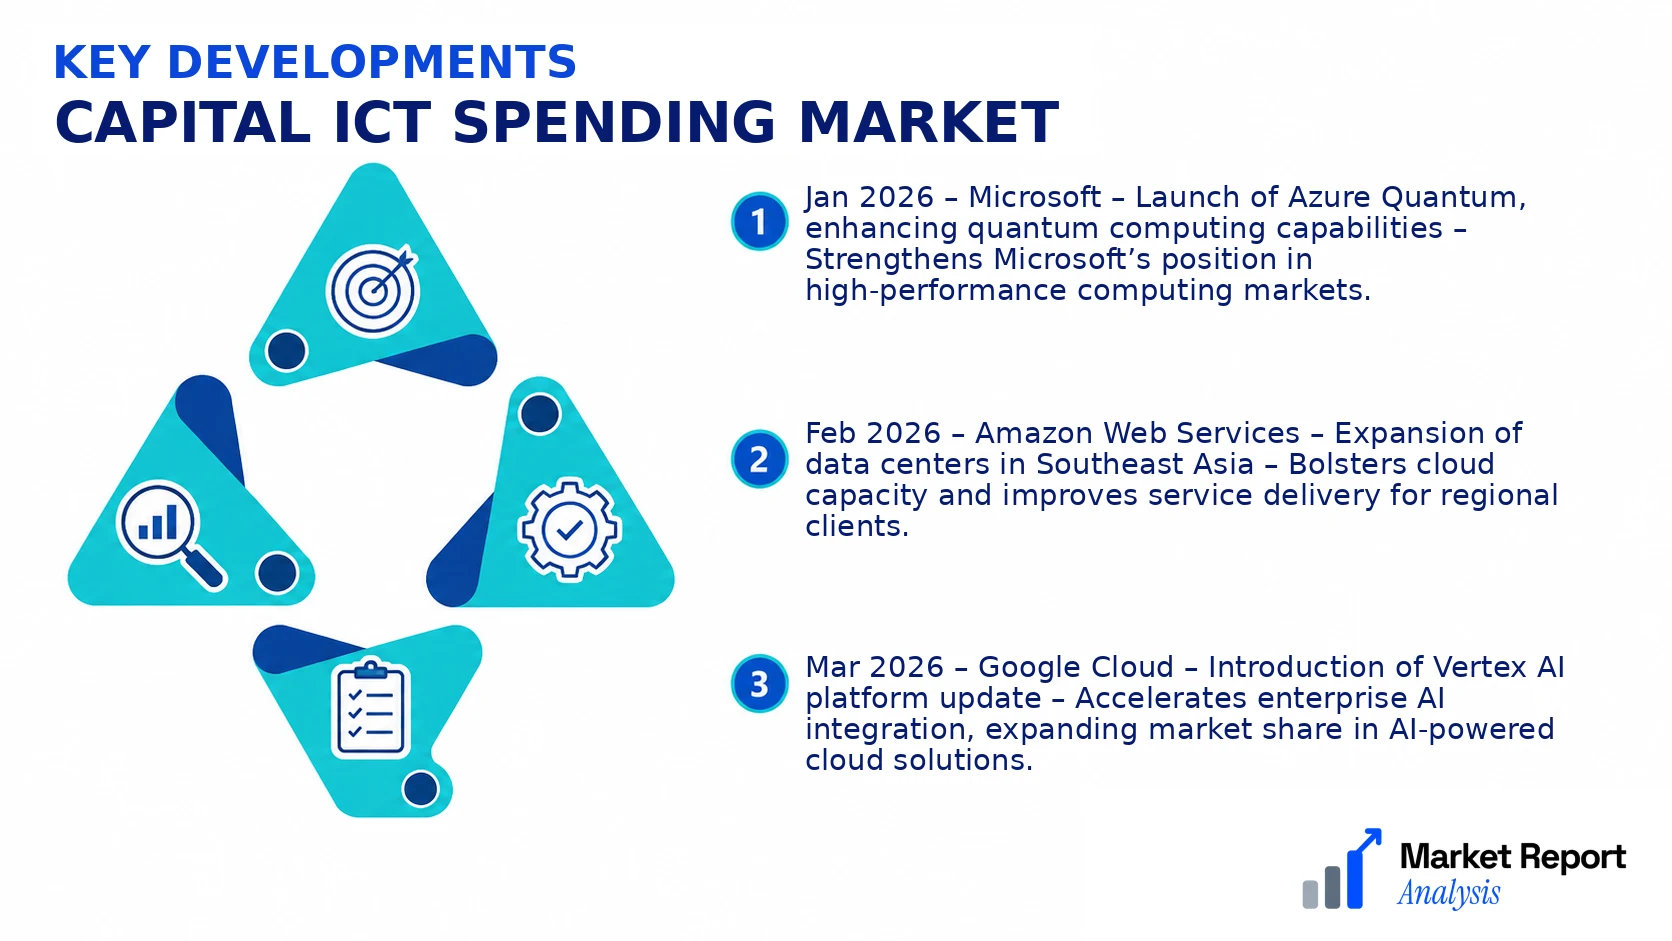
- Jan 2026 – Microsoft – Launch of Azure Quantum, enhancing quantum computing capabilities – Strengthens Microsoft’s position in high-performance computing markets.
- Feb 2026 – Amazon Web Services – Expansion of data centers in Southeast Asia – Bolsters cloud capacity and improves service delivery for regional clients.
- Mar 2026 – Google Cloud – Introduction of Vertex AI platform update – Accelerates enterprise AI integration, expanding market share in AI-powered cloud solutions.
- Apr 2026 – IBM – Acquisition of Red Hat’s cloud unit, focusing on hybrid cloud solutions – Reinforces IBM’s hybrid cloud offerings and accelerates deployment of cloud infrastructure projects.
- May 2026 – Cisco Systems – Partnership with Nokia for 5G network security – Enhances secure networking solutions for telecom providers and enterprise clients, expanding digital infrastructure security.
Frequently Asked Questions
What is the Capital ICT Spending Market?
The Capital ICT Spending Market encompasses the global expenditure on information and communication technology infrastructure, hardware, and software by organizations to support their business operations, digital transformation, and future growth initiatives. It reflects investments that enable technological advancement and competitiveness.
What is the current market size of Capital ICT Spending Market?
As of 2026, the market valuation of the Capital ICT Spending Market is estimated to be approximately USD 1.2 TRILLION, indicative of heightened corporate investments in digital infrastructure, cloud computing, cybersecurity, and network upgrades, which collectively drive the market forward amid increasing digitalization trends.
What factors are driving the Capital ICT Spending Market?
Key drivers include rapid digital transformation initiatives, expanding cloud adoption, growing cybersecurity concerns, the proliferation of IoT devices, and increased demand for enterprise data centers. These factors propel organizations to allocate greater budgets toward ICT infrastructure upgrades and innovations.
Which region dominates the Capital ICT Spending Market?
North America currently leads the market due to its high technological adoption, robust infrastructure, and significant investments from leading tech companies. The region's advanced digital economy and supportive government policies further sustain its dominant position in this market.
Which segment is expected to grow the fastest?
The cloud computing segment is projected to exhibit the fastest growth, driven by organizations shifting to cloud-based solutions for scalability, cost-efficiency, and flexibility. This trend significantly influences overall ICT capital expenditures during the forecast period.
Who are the leading companies operating in the Capital ICT Spending Market?
Major players include industry giants such as IBM, Cisco Systems, Hewlett Packard Enterprise, Dell Technologies, and Huawei Technologies, who are actively investing in innovation, strategic partnerships, and expanding their market footprint to capture emerging opportunities.
Analyst Perspective
The Capital ICT Spending Market is poised for sustained growth through 2034, driven by ongoing digital transformation initiatives and the escalating demand for data-centric infrastructure. The market's maturity varies by region, with North America and Europe nearing saturation in traditional segments, while Asia-Pacific offers significant expansion opportunities due to rapid technological adoption and expanding digital economies. Investment priorities are increasingly focused on innovative technologies such as AI, cloud computing, and 5G, which promise to reshape competitive dynamics. Long-term prospects hinge on technological evolution and the ability of vendors to adapt to shifting client needs and regulatory environments. The market's competitive landscape is intensifying, demanding strategic differentiation and robust innovation pipelines. Regions like Asia-Pacific exhibit high growth potential, influenced by government initiatives and rising enterprise digitization. Strategic investors should prioritize R&D to stay ahead in a fast-evolving ecosystem, while diversification across regions can mitigate risks associated with regional policy and economic fluctuations.
