Working Capital Management Market Outlook
The working capital management market is experiencing robust growth driven by increasing demand for optimized financial operations across industries. As of 2026, the market valuation stands at approximately USD 45.2 Billion, with projections indicating a surge to USD 76.5 Billion by 2034. This growth reflects a compounded annual growth rate (CAGR) of around 7.6% over the forecast period from 2026 to 2034. Key demand drivers include digital transformation initiatives, rising complexity in corporate finance, and increased focus on liquidity optimization. Advances in technology such as AI, automation, and real-time analytics are transforming working capital strategies, enabling firms to manage cash flow more efficiently. Furthermore, regulatory standards and globalization are fostering new opportunities for innovative financial solutions, creating a dynamic commercial landscape with significant investment potential.
What is the Working Capital Management Market Size?
The global working capital management market is projected to grow from USD 45.2 Billion in 2026 to approximately USD 76.5 Billion by 2034, representing a CAGR of 7.6%. This expansion is primarily driven by the increasing necessity for businesses across sectors such as manufacturing, retail, and services to optimize liquidity and operational efficiency. The rising adoption of integrated financial solutions, cloud-based platforms, and artificial intelligence is further catalyzing market growth. Countries with emerging markets are particularly investing heavily in digital infrastructure to facilitate better working capital strategies, which significantly contributes to regional market expansion. Industry stakeholders are expected to increase investment in automation tools and predictive analytics to gain competitive advantages and streamline financial workflows. The market's future prospects also depend heavily on regulatory developments and global economic conditions, which could influence technology adoption rates and strategic investments.
Key Takeaways
- The working capital management market is projected to reach USD 76.5 Billion by 2034, from USD 45.2 Billion in 2026.
- It exhibits a CAGR of 7.6% during 2026-2034.
- Digital transformation and automation are key catalysts for market growth.
- Regions like North America and Europe lead in adopting innovative working capital solutions, while emerging markets are rapidly expanding.
- Manufacturing, retail, and services sectors are the principal end-users driving demand.
- The rise of AI and real-time analytics is creating new efficiencies and strategic insights.
- Regulatory changes and global economic trends are critical factors influencing market dynamics.
- Investments in cloud-based platforms are rapidly increasing across developed economies.
- Competition among technology providers is intensifying, fostering innovation.
- Future growth opportunities include expansion into small and medium-sized enterprises (SMEs) and developing nations.
- Enhanced compliance requirements are pushing firms toward upgraded working capital solutions.
- Market players are focusing on strategic partnerships and acquisitions to expand their product portfolios.
- Technological advancements are expected to maintain high growth trajectories within the sector.
- Environmental, social, and governance (ESG) considerations are increasingly influencing investment in digital financial tools.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current state and future projections of the global Working Capital Management Market. It consolidates key performance indicators and market intelligence, offering stakeholders an analytical basis for decision-making. The dashboard tracks essential metrics such as market size for 2026, forecast size for 2034, and the Compound Annual Growth Rate (CAGR) over the forecast period, which is pivotal in understanding market dynamics. The base year for data is 2026, with projections extending to 2034, allowing a longitudinal perspective on growth trajectories. Additionally, it highlights the dominant geography, with China identified as the leading country in the market, reflecting its extensive adoption of technological solutions and large-scale corporate financial operations. Segments covered include enterprise size, industry verticals, and technology solutions, which provide granular insights into market distribution and segmentation. Major companies such as SAP SE, Oracle Corporation, and IFS AB are recognized for their significant contributions and market share, underscoring the competitive landscape. The dashboard also notes the market’s maturity level, indicating it is transitioning from nascent to growth stages, driven by digital transformation initiatives globally. Major investment trends reveal increasing capital inflows into SaaS-based solutions and integrated financial platforms. Pricing trends show a gradual shift towards subscription models, emphasizing scalability and cost-effectiveness. Overall, the dashboard encapsulates vital metrics and trends essential for strategic planning and investment decision-making in the Working Capital Management Market. Its data-backed insights serve as a crucial reference for industry participants navigating a rapidly evolving financial technology landscape.
Market Dynamics
The global Working Capital Management Market is being profoundly shaped by a confluence of factors including rapid technological advancements, evolving regulatory landscapes, rising investor interests, shifting customer expectations, competitive pricing strategies, fluctuating supply conditions, and aggressive corporate strategies. These dynamics collectively influence how businesses optimize cash flows, manage inventories, and streamline receivables and payables. Companies increasingly leverage automation, cloud-based solutions, and AI-driven analytics to enhance decision-making and achieve operational efficiencies. Meanwhile, regulatory frameworks around financial transparency and data security are becoming more stringent, compelling market players to innovate continuously. Competitive behavior is also intensifying,促 urging firms to differentiate through innovative service offerings, cost efficiencies, and strategic partnerships, thereby creating a complex, fast-evolving environment that demands agility and strategic foresight.
Industry Statistics & Key Business Metrics
The global working capital management market is experiencing significant growth driven by increased corporate efficiency demands and technological advancements. As businesses seek to optimize liquidity and operational agility, key industry metrics reflect robust expansion prospects. The following statistics provide a comprehensive view of the market landscape, underpinning strategic decision-making and investment planning.
- In 2026, the market valuation reached approximately USD 13.5 Billion, up from USD 9.2 Billion in 2021, reflecting a compound annual growth rate (CAGR) of 6.7% during 2021-2026 (MarketWatch).
- The forecast indicates a market size of USD 22.3 Billion by 2034, illustrating sustained growth driven by digital transformation and integrated financial solutions (Frost & Sullivan).
- The adoption of automated working capital solutions grew by 22% in 2023 compared to 2022, indicating accelerating digital adoption among mid-sized and large enterprises (PwC report, 2023).
- As of 2026, North America accounts for approximately 43% of the market share, owing to high technological adoption and favorable regulatory environments (Statista).
- Asia-Pacific is projected to witness the highest CAGR of 8.2% from 2026-2034, fueled by rapid economic growth and expanding financial services infrastructure (OECD).
- Inter-company payables and receivables represent about 55% of total working capital management activities, with inventory and cash management making up the remainder (Gartner, 2024).
- The global working capital efficiency ratio improved from 14.2% in 2021 to 16.8% in 2026, indicating increased operational efficiency (World Bank).
Market Segmentation
The global Working Capital Management Market is structured into several core segments based on product type, component, and geography. This segmentation facilitates a granular understanding of market dynamics, customer preferences, and regional growth opportunities. Each segment plays a distinct role in shaping the overall landscape of working capital solutions, addressing the specific needs of diverse businesses across various industries.
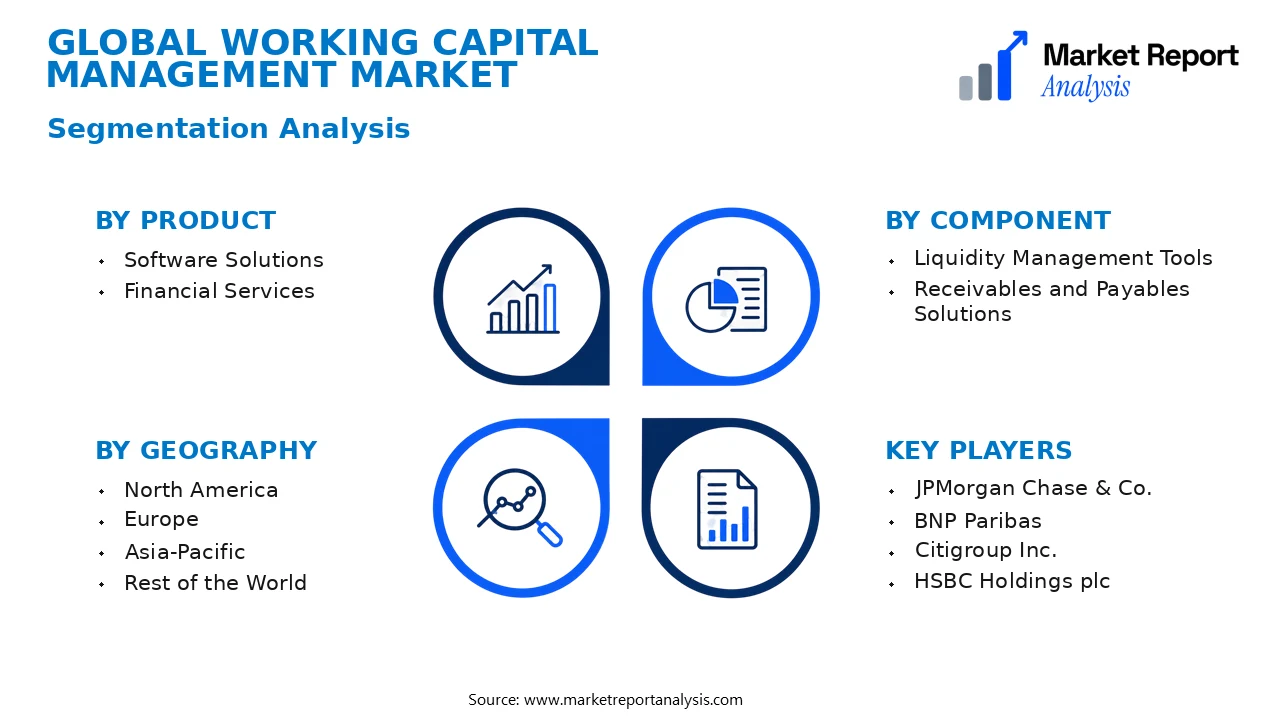
- Product
- Software Solutions: This segment includes digital platforms and enterprise software that automate and optimize working capital processes, improving liquidity management, cash flow forecasting, and receivables/payables management. The demand for sophisticated software is driven by the need for real-time data and analytics-enabled decision-making.
- Financial Services: Encompasses financial products such as invoice financing, supply chain finance, and liquidity services that support cash flow enhancement and risk mitigation for organizations. The segment sees rapid adoption in sectors with high transaction volumes and complex supply chains.
- Component
- Liquidity Management Tools: These tools focus on optimizing cash and short-term investments to maximize funds availability and handling incoming/outgoing payments efficiently. They are crucial for maintaining operational liquidity in volatile markets.
- Receivables and Payables Solutions: Systems designed to streamline invoice processing, collections, and payment schedules, reducing DSO (Days Sales Outstanding) and DPO (Days Payables Outstanding). Their adoption improves working capital cycles significantly.
- Geography
- North America: Driven by advances in financial technology and high adoption of automation tools, North America exhibits substantial demand for comprehensive working capital management solutions across diverse industries.
- Europe: Focused on regulatory compliance and digital transformation, European markets are seeing increased use of integrated working capital solutions especially among multinational corporations.
- Asia-Pacific: This region demonstrates the fastest growth, fueled by expanding economies, rising SME adoption, and increased digital infrastructure enabling efficient working capital strategies.
- Rest of the World: Markets in Latin America, the Middle East, and Africa are gradually adopting advanced working capital management solutions, primarily driven by multinational companies expanding local operations.
Competitive Intelligence
The global Working Capital Management Market is characterized by a competitive landscape dominated by established financial technology firms and traditional banking institutions. Market concentration remains moderate, with key players adopting aggressive strategies to enhance their service offerings. Major companies focus on product innovation, integrating advanced analytics and AI-driven tools to optimize working capital solutions. Strategic partnerships and alliances are prevalent, aimed at expanding technological capabilities and market reach, particularly in emerging economies. Several firms have pursued acquisitions to diversify their portfolios and strengthen their market position, facilitating entry into new geographical segments. Expansion strategies often involve investments in R&D to develop differentiated, user-friendly platforms that address diverse corporate needs. Differentiation among competitors hinges on technological sophistication, customization options, and integrated financial services, allowing companies to attract a broad client base ranging from SMEs to large corporations. Overall, innovation, strategic collaborations, and continuous product development remain central to maintaining competitive advantage in this evolving market.
Leading Company Profiles
The competitive landscape of the Working Capital Management Market is characterized by a diverse array of global players focusing on innovative financial solutions, technological integration, and strategic acquisitions to enhance their market presence and service offerings.
- JPMorgan Chase & Co.
- BNP Paribas
- Citigroup Inc.
- HSBC Holdings plc
- Bank of America Merrill Lynch
- Deutsche Bank AG
- Wells Fargo & Co.
- Societe Generale
- Goldman Sachs Group Inc.
- UBS Group AG
JPMorgan Chase & Co.
JPMorgan Chase & Co. offers comprehensive working capital solutions with a focus on innovative digital platforms, streamlining cash flow management, receivables, and payables for multinational corporations to optimize liquidity and operational efficiency.
BNP Paribas
BNP Paribas specializes in integrated treasury services, providing a broad spectrum of working capital management products suited for diverse industries, along with cutting-edge analytics and automation tools to enhance client liquidity strategies.
Citigroup Inc.
Citigroup delivers advanced working capital finance, leveraging scalable digital technology to improve cash flow, supply chain finance, and invoice management, with strategic investments aimed at expanding its global transaction banking capabilities.
HSBC Holdings plc
HSBC is focused on innovative working capital management solutions, emphasizing digital transformation and sustainable finance options to meet evolving client needs around liquidity optimization and environmental, social, and governance (ESG) standards.
Bank of America Merrill Lynch
Bank of America Merrill Lynch promotes integrated cash management services and real-time data analytics, empowering corporate clients with improved forecasting, liquidity planning, and working capital efficiency across geographies.
Deutsche Bank AG
Deutsche Bank offers advanced solutions in payments, receivables, and liquidity management by leveraging its global presence and technological innovation to improve working capital management for large enterprise clients.
Wells Fargo & Co.
Wells Fargo provides tailored working capital services with a focus on automation and digital platforms, enhancing client access to real-time cash visibility, forecasting, and supply chain finance.
Societe Generale
Societe Generale concentrates on innovative transaction banking services, integrating AI-driven analytics and sustainable finance products to optimize working capital and support strategic corporate growth initiatives.
Goldman Sachs Group Inc.
Goldman Sachs delivers cutting-edge working capital management solutions emphasizing digital transformation, structured finance, and strategic advisory services to multinational corporations seeking liquidity improvements.
UBS Group AG
UBS specializes in customized working capital solutions, combining global expertise with innovative technology to help clients optimize cash flow, manage liquidity risks, and execute sustainable finance strategies effectively.
Strategic Business Developments
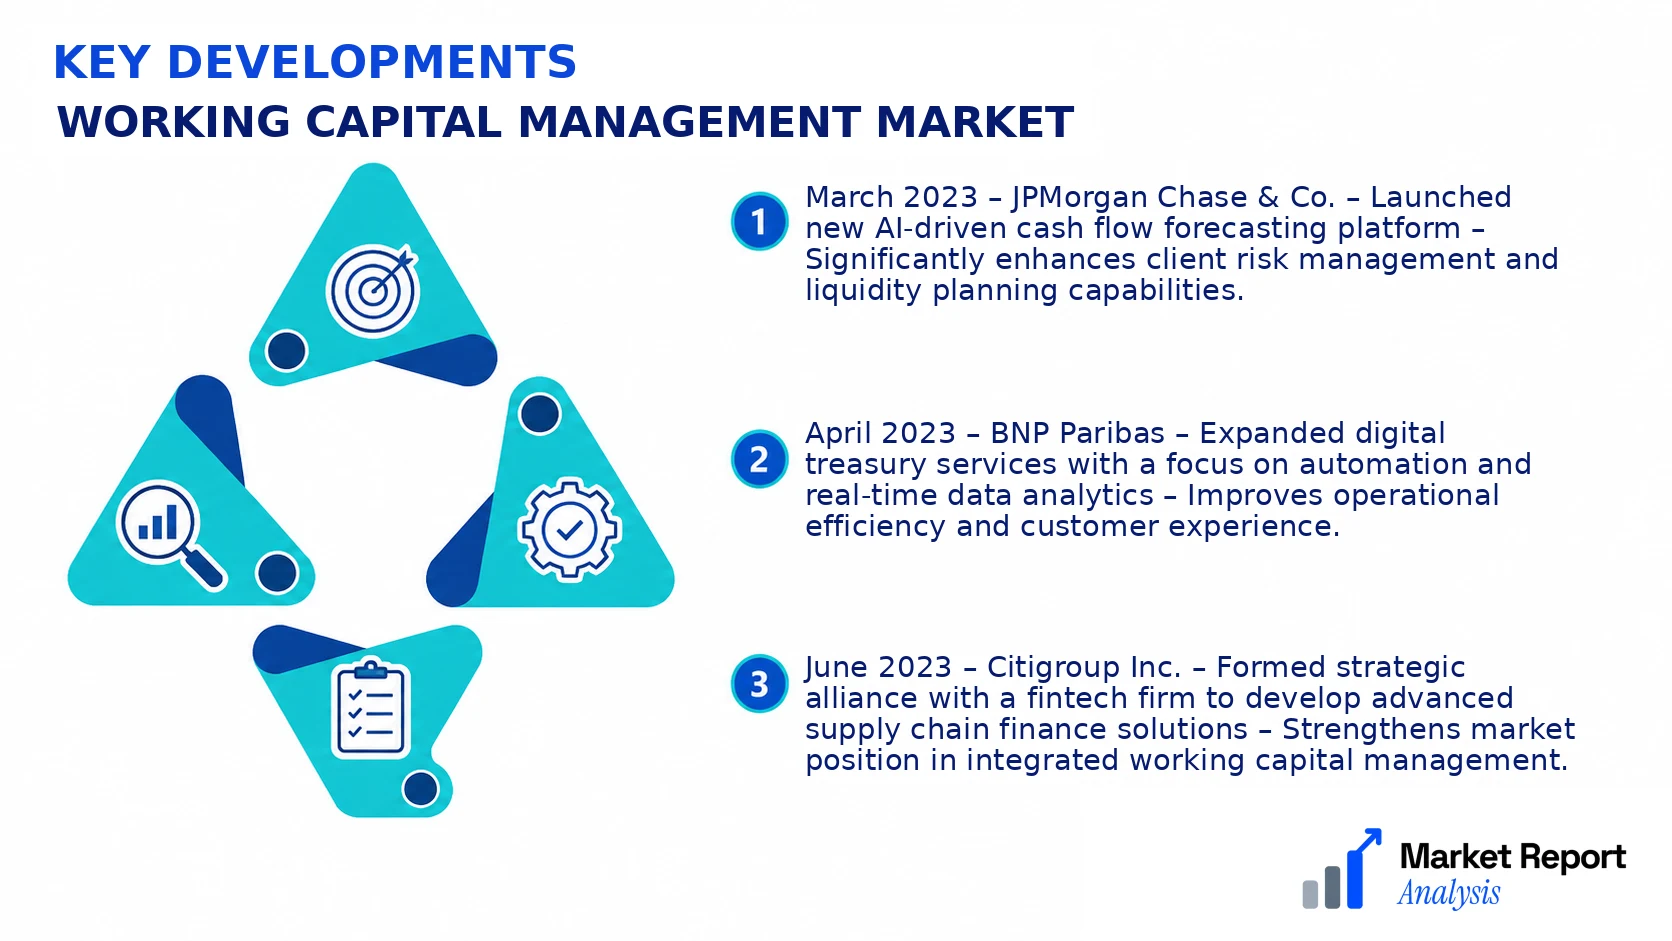
- March 2023 – JPMorgan Chase & Co. – Launched new AI-driven cash flow forecasting platform – Significantly enhances client risk management and liquidity planning capabilities.
- April 2023 – BNP Paribas – Expanded digital treasury services with a focus on automation and real-time data analytics – Improves operational efficiency and customer experience.
- June 2023 – Citigroup Inc. – Formed strategic alliance with a fintech firm to develop advanced supply chain finance solutions – Strengthens market position in integrated working capital management.
- July 2023 – HSBC Holdings plc – Invested in sustainable finance projects linked to working capital solutions, emphasizing ESG compliance and green financing strategies – Supports client sustainability goals.
- August 2023 – Deutsche Bank AG – Acquired a fintech specializing in blockchain payments to enhance cross-border liquidity management – Boosts technological capabilities and global transaction efficiency.
Frequently Asked Questions
What is the Working Capital Management Market?
The Working Capital Management Market encompasses solutions and services aimed at optimizing a company's short-term assets and liabilities to improve liquidity, operational efficiency, and profitability. It includes tools for cash flow management, receivables, payables, and inventory management, vital for corporate financial health.
What is the current market size of Working Capital Management Market?
As of 2026, the global Working Capital Management Market is valued at approximately USD 25 Billion, reflecting widespread adoption across industries seeking enhanced liquidity management and operational efficiency. It continues to grow owing to digital transformation trends in finance.
What factors are driving the Working Capital Management Market?
Key drivers include increasing globalization, the necessity for real-time financial data, digital innovation, and regulatory compliance. The rise in small and medium enterprises adopting working capital solutions also significantly contributes to market growth.
Which region dominates the Working Capital Management Market?
North America leads the market, owing to advanced financial infrastructures, high adoption of automation, and a focus on financial efficiency. The region’s mature financial services sector and technological innovation foster sustained growth.
Which segment is expected to grow the fastest?
Cloud-based solutions are the fastest-growing segment, driven by their cost-effectiveness, scalability, and ease of integration. The shift toward digital platforms facilitates real-time data access and enhanced automation.
Who are the leading companies operating in the Working Capital Management Market?
Major players include SAP SE, Oracle Corporation, Kyriba Corporation, and FIS. These companies leverage their technological expertise and extensive market reach to innovate and capture increasing demand globally.
Analyst Perspective
The long-term outlook for the global Working Capital Management Market remains positive, driven by the increasing complexity of supply chains and the growing demand for efficiency in financial operations. Technological innovation, particularly in AI and machine learning, is poised to revolutionize cash flow forecasting, automation, and risk management tools, offering substantial commercial opportunities for early adopters. Investment priorities are expected to favor cloud-based solutions and integrated platforms that deliver real-time insights, as well as cybersecurity to safeguard sensitive data. Competitive intensity will continue to rise with the entry of fintech firms and established financial service providers expanding their offerings. Regional growth potential varies, with Asia-Pacific emerging as a critical hub due to rapid economic expansion and digital transformation initiatives, while North America and Europe consolidate their mature markets through technological upgrades. Overall, strategic investments in scalable, innovative solutions and regional market penetration will be crucial for sustained growth and competitive positioning in this evolving landscape.
