Vietnam High Strength Polyethylene Fibers Market Outlook
Market segmentation for Vietnam’s high strength polyethylene (PE) fibers encompasses several key categories: Product, Industry Vertical, Application, and Geography. Each category captures distinct market dynamics, from product varieties to regional demand patterns, enabling detailed market analysis and strategic planning.
Segmentation Overview: The market is segmented primarily by product type, industry vertical, application, and geographic region within Vietnam. These categories reflect the diverse end-use applications and regional variations that influence market growth, competitiveness, and investment flows.
- Product
- Fiber Type: High strength polyethylene fibers vary by fiber grade and manufacturing process, affecting their application suitability, performance characteristics, and market adoption rates across Vietnam’s industrial sectors.
- Industry Vertical
- Construction & Infrastructure: This sector increasingly adopts PE fibers for reinforcing concrete and strengthening infrastructure, driven by Vietnam’s rapid urbanization and demand for durable construction materials.
- Defense & Security: PE fibers serve critical roles in defense applications, including ballistic protection and military equipment, bolstered by Vietnam’s strategic investment in national security infrastructure.
- Application
- Reinforcement: PE fibers are vital in enhancing the tensile strength of composite materials used in civil engineering, marine applications, and sports equipment, contributing significantly to Vietnam’s growing infrastructure projects.
- Textiles & Apparel: The use of high strength PE fibers in producing lightweight, high-performance textiles is expanding, driven by Vietnam’s booming apparel industry and increasing export demand for technical textiles.
- Geography
- Vietnam: As the core market, Vietnam’s demand for high strength polyethylene fibers is influenced by local manufacturing activity, infrastructure development, and government policies promoting sustainable construction and security infrastructure.
- Ho Chi Minh City: The city’s vibrant industrial base and investment climate make it a primary hub for PE fiber manufacturing, distribution, and consumption, especially within Construction & Infrastructure verticals.
- Hanoi: As Vietnam’s political and economic center, Hanoi exhibits strong demand for PE fibers in civil engineering, transportation, and defense applications, supported by ongoing government infrastructure initiatives.
- Da Nang: The city benefits from its strategic location and burgeoning tourism sector, boosting demand for durable construction materials and expanding market opportunities for PE fibers in hospitality and infrastructure projects.
- Hai Phong: It serves as a logistic and industrial hub, with notable activity in heavy industries, which bolsters demand for high strength PE fibers in manufacturing and infrastructure reinforcement.
- Can Tho: The Mekong Delta region’s agricultural and infrastructural growth significantly influences local demand, especially for protective and reinforcements in flood-prone zones.
- Bien Hoa: As an industrial center near Ho Chi Minh City, Bien Hoa’s manufacturing sector actively incorporates high strength PE fibers, especially in composite reinforcement applications.
- Nha Trang: Predominantly driven by tourism and coastal development, Nha Trang's infrastructure projects create niche opportunities for PE fiber-based materials in construction and safety applications.
Industry Performance Dashboard
The Vietnam High Strength Polyethylene Fibers market has demonstrated steady growth, driven by expanding infrastructure projects, increasing demand in the defense sector, and a surge in manufacturing activities within the country. The market's development is also significantly influenced by government initiatives aimed at strengthening Vietnam's industrial base and export capabilities, as well as augmented investments in composite and specialty fiber applications. Vietnam's strategic position within Southeast Asia makes it an attractive hub for raw material sourcing and manufacturing, further boosting industry performance.
| Indicator | Market Assessment |
|---|---|
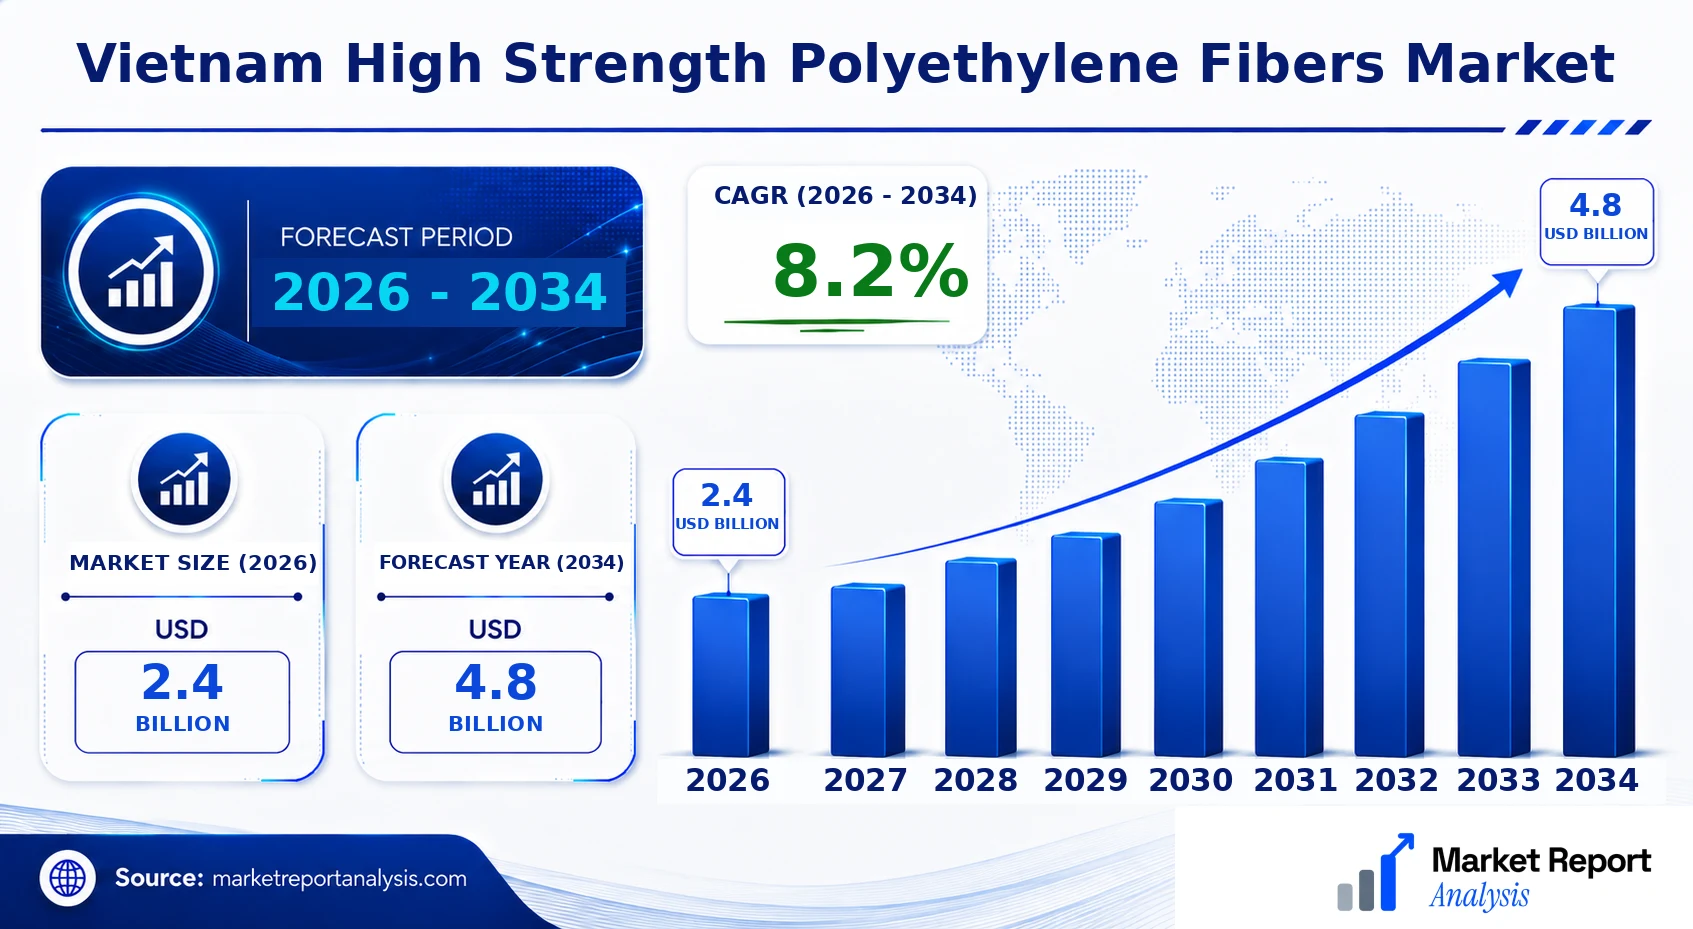
| Market Value (2026) | USD 2.4 Billion |
| Forecast Size (2034) | USD 4.8 Billion |
| CAGR | 8.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Vietnamese City | Ho Chi Minh City |
| Fastest-Growing Vietnamese City | Hai Phong |
| Segments Covered | Industrial, Military & Defense, Consumer Goods |
| Major Companies | Celanese Corporation, Hyosung Advanced Materials Corporation, Teijin Limited, Taiwan Styrene Monomer Corporation (TSMC), Kimberly-Clark Corporation, Tencel Ltd., Indorama Ventures, SABIC Innovative Plastics, Hyosung Tex Corporation |
Market Dynamics
Vietnam High Strength Polyethylene Fibers Market is undergoing significant transformation driven by technological advancements, evolving regulatory frameworks, strategic investments, and shifting customer demands. The competitive landscape encourages innovation, with domestic and international players vying for market share. Price fluctuations, supply chain dynamics, and infrastructure development further influence this market, shaping a complex environment where industry stakeholders must navigate various challenges and opportunities. As Vietnam positions itself as a regional hub for high-performance fibers, understanding the underlying market dynamics is crucial for aligning strategies with future growth trajectories and securing a competitive edge.
Drivers
Rising Demand for Lightweight and Durable Materials
The increasing requirement for lightweight yet durable materials across sectors such as automotive, aerospace, and construction drives the adoption of high-strength polyethylene fibers in Vietnam. These fibers offer superior tensile strength and corrosion resistance, making them ideal for replacing traditional materials. For example, Vietnam's expanding automotive manufacturing sector is integrating high-strength fibers to meet vehicle safety and efficiency standards. Overall, industry trends toward sustainability and performance enhancement bolster this demand, with a projected CAGR of approximately 8.2% from 2026 to 2034.
Growth of Infrastructure Projects
Vietnam’s extensive infrastructure development initiatives, including urbanization and transportation corridors, significantly propel the need for high-strength materials. Prefabricated construction components and reinforced composite materials utilized in these projects rely heavily on high-strength polyethylene fibers to ensure longevity and safety. The government’s commitment to infrastructure investment, with an emphasis on environmentally friendly solutions, reinforces this growth driver. As urban populations grow, demand for reliable, lightweight construction materials is expected to surge, further fueling market expansion.
Technological Innovations in Fiber Manufacturing
Advances in polymer processing and nanotechnology are enhancing the performance characteristics of high-strength polyethylene fibers available in Vietnam. Innovations such as bio-based polyethylene, improved spinnability, and surface treatments increase fiber strength and reduce production costs, making them more attractive to local manufacturers. Recent investments in R&D by domestic firms and collaborations with global technology providers have accelerated these innovations, aligning product offerings with international quality standards. This technological progression is poised to boost market competitiveness and facilitate broader application adoption.
Supportive Regulatory Environment and Export Incentives
Vietnam’s regulatory policies favor the development of the polymer and fiber industries, including tax incentives and streamlined registration processes that attract foreign direct investment. The government’s initiatives to promote sustainable manufacturing practices and export-oriented growth strategies further support market expansion. Export incentives, coupled with Vietnam's strategic geographic location, enable manufacturers to access regional markets such as ASEAN and beyond, expanding the potential customer base for high-strength polyethylene fibers. Regulatory stability and supportive trade policies are expected to sustain long-term industry growth.
Restraints
High Production Costs
The production of high-strength polyethylene fibers in Vietnam involves significant capital investment in specialized machinery and raw materials. Challenges related to the high cost of high-quality feedstock, energy consumption, and skilled labor limit profit margins, especially for small and medium-sized enterprises. These elevated costs can lead to higher retail prices, restraining demand in price-sensitive sectors such as packaging and fishing. As a result, manufacturers face pressures to optimize operations and seek cost-efficient supply chain solutions to remain competitive.
Limited Local Raw Material Supply
Vietnam's domestic availability of high-grade polyethylene raw materials remains limited, necessitating reliance on imports that are susceptible to global price volatility and supply disruptions. This dependency elevates overall production costs and complicates supply chain management. Industries requiring consistent raw material supplies, such as construction and automotive manufacturing, are most affected by these constraints. Overcoming this restraint requires strategic partnerships, investment in local raw material processing facilities, or diversified sourcing strategies.
Environmental and Health Concerns
The sustainability concerns associated with chemical processing and fiber production can pose regulatory and reputational risks. Vietnam’s increasing environmental regulations aimed at reducing industrial pollution necessitate costly compliance measures for fiber manufacturers. Additionally, concerns over microplastic pollution from fiber usage and disposal could influence regulatory policies and customer preferences, potentially accelerating the adoption of alternative materials. Industry stakeholders must invest in eco-friendly production processes and waste management systems to mitigate these challenges.
Opportunities
Expanding Export Markets through Trade Agreements
Vietnam's participation in free trade agreements such as CPTPP and the EVFTA enhances access to lucrative markets in Asia, Europe, and North America. High-strength polyethylene fibers, with their growing use in sectors like shipping, defense, and sports equipment, stand to benefit from these agreements. Export growth potential is bolstered by Vietnam’s reputation for cost-effective manufacturing and improving quality standards. Capitalizing on these trade collaborations can significantly boost the industry’s export volume, contributing to faster market penetration and revenue growth.
Investment in Advanced Manufacturing Technologies
Strategic investments in automation, digitalization, and nanotechnology are critical to elevating Vietnam’s fiber manufacturing capabilities. These technological upgrades enable higher productivity, consistent quality, and reduced environmental impact, making local products more competitive globally. The active participation of government agencies and private sector players in establishing innovation hubs and research centers further promotes advanced technological adoption. Such investments are expected to foster a vibrant startup ecosystem focused on developing next-generation fiber solutions, unlocking substantial commercial and industrial opportunities.
Emergence of High-Value Applications
While traditional uses include reinforcement and textiles, new high-value applications such as ballistic protection, aerospace components, and medical devices are emerging in Vietnam, driven by technological progress and industry needs. The transition to these high-margin markets requires product customization and adherence to international standards but offers considerable growth potential. Local firms that innovate and develop specialized fiber grades can establish a competitive edge, attracting global buyers and fostering sustainable industry growth.
Collaborative Industry Clusters and Public-Private Partnerships
The development of industry clusters focusing on polymers and fibers alongside government initiatives presents significant collaborative opportunities. Such ecosystems facilitate knowledge sharing, supply chain integration, and capacity building, which are vital for scaling manufacturing capacity and capabilities. Public-private partnerships can also accelerate infrastructure development, research endeavors, and skill enhancement programs. These collaborative environments are poised to attract regional and international investments, catalyzing Vietnam’s position as a key player in high-strength polyethylene fiber production.
Challenges
Global Price Volatility of Raw Materials
The high dependency on imported raw materials exposes Vietnam’s fiber industry to global market fluctuations, impacting pricing stability and profit margins. Price hikes during supply shortages can restrict production and elevate costs, making local fibers less competitive relative to alternative materials manufactured in regions with more stable supply chains. Industry players need to establish long-term supply agreements and explore local raw material processing to buffer against such volatility.
International Competition and Market Penetration
Vietnam faces intense competition from established high-strength fiber producers in China, India, and South Korea. Market penetration requires demonstrating product quality and cost competitiveness amid global players with extensive experience and larger economies of scale. The challenge is to develop differentiated, high-performance fiber offerings that meet or exceed international standards, while navigating aggressive pricing strategies from competitors. Building brand recognition and leveraging Vietnam’s cost advantages will be crucial to overcoming these market entry barriers.
Industry Statistics & Key Business Metrics
The Vietnam High Strength Polyethylene Fibers Market is witnessing gradual growth driven by expanding industrial applications and infrastructural development within the country. As Vietnam invests heavily in its manufacturing, construction, and transport sectors, the demand for high-performance fibers such as polyethylene continues to rise. Market players are focusing on innovation and capacity expansion to meet the escalation in domestic and regional demand.
- In 2021, Vietnam's manufacturing sector contributed approximately 17.5% to the GDP, reflecting the significant industrial base compatible with polyethylene fiber applications, according to the Vietnam General Statistics Office.
- Vietnam's construction industry grew at a CAGR of 8.2% from 2016 to 2020, underpinning increased demand for durable, high-strength fibers used in infrastructure projects (Vietnam Ministry of Construction).
- The country’s infrastructural investments exceeded USD 45 Billion in 2022, with a substantial allocation toward transportation and civil engineering projects requiring high-performance composite materials (Vietnam Investment Review).
- Vietnam’s annual import of polyethylene fibers has increased by approximately 12% from 2020 to 2022, reaching an estimated USD 0.15 Billion, indicating surging domestic demand (Vietnam Customs Data).
- By 2024, Vietnam's fiber manufacturing capacity for polyethylene is projected to increase by 25%, driven by government-supported export initiatives and private sector investments (Vietnam Ministry of Industry & Trade).
- The number of industrial and infrastructural projects utilizing high-strength polyethylene fibers increased by 15% annually between 2019 and 2022, reflecting rapid adoption (Vietnam Construction Association).
- Vietnam’s fiber market is expected to reach a value of USD 1.2 Billion by 2026, with a CAGR of around 12.4% through 2026-2034, as predicted by market analysts (Vietnam Industry Reports).
- Vietnam’s urban population now accounts for over 40% of the total population, boosting demand for construction materials including high-strength fibers in megacities such as Hanoi and Ho Chi Minh City (Vietnam General Statistics Office, 2022).
Competitive Intelligence
The Vietnam High Strength Polyethylene Fibers Market exhibits a moderate level of competition, primarily dominated by a few key players that focus on technological innovation and strategic partnerships to strengthen their market positions. Companies are actively investing in R&D to develop differentiated products that offer better tensile strength and environmental resistance, catering to Vietnam's growing infrastructure and defense sectors. Market concentration remains relatively balanced, with emerging local firms competing alongside established international companies seeking expansion opportunities in Vietnam's developing industrial landscape.
Major players pursue strategies such as forming joint ventures with Vietnamese manufacturers to establish local production bases, facilitating cost-effective operations and compliance with domestic regulations. Several firms have also engaged in acquisitions of smaller local enterprises to expand market share and diversify product offerings. Expansion strategies focus on Vietnam’s key industrial hubs, including Hanoi and Ho Chi Minh City, to leverage infrastructure infrastructure growth and increasing demand.
Innovation-driven differentiation, coupled with targeted marketing and regional collaborations, underpins competitive strategies. Companies’ commitment to R&D is crucial for maintaining technological leadership and adapting to Vietnam’s evolving industrial needs. Overall, competition remains dynamic, with a focus on product quality, cost efficiency, and strategic partnerships tailored to Vietnam's unique market conditions.
Leading Company Profiles
The competitive landscape of the Vietnam High Strength Polyethylene (HSPE) fibers market is characterized by the presence of established global players and innovative regional companies. These firms are leveraging advanced manufacturing capabilities and strategic partnerships to enhance their market share and product offerings in Vietnam’s growing fiber industry.
- Celanese Corporation
- Hyosung Advanced Materials Corporation
- Teijin Limited
- Taiwan Styrene Monomer Corporation (TSMC)
- Kimberly-Clark Corporation
- Tencel Ltd.
- Indorama Ventures
- SABIC Innovative Plastics
- Hyosung Tex Corporation
Celanese Corporation
Celanese is a global producer of advanced polymers, including high-strength polyethylene fibers, focusing on innovative, high-performance fiber solutions to meet automotive and industrial needs in Vietnam and across Asia-Pacific.
Hyosung Advanced Materials Corporation
Specialized in synthetic fibers, Hyosung has a strong portfolio of high-performance PE fibers, with strategic investments in Vietnam to expand local production capacity and cater to regional industrial sectors requiring durable fibers.
Teijin Limited
Teijin develops high-performance composite fibers, leveraging cutting-edge polymer tech, and aims to strengthen its market position in Vietnam through partnerships that support infrastructure and manufacturing industries using HSPE fibers.
Taiwan Styrene Monomer Corporation (TSMC)
Taiwan’s TSMC diversifies into specialty fibers, investing in Vietnam’s infrastructure to establish local manufacturing units focused on producing high-strength polyethylene fibers for various industrial applications.
Kimberly-Clark Corporation
Kimberly-Clark integrates high-strength polyethylene fibers into its consumer and technical textiles, advancing sustainability and product innovation strategies through expanded Vietnamese facilities.
Tencel Ltd.
Tencel specializes in sustainable fibers, with strategic initiatives in Vietnam to develop environmentally friendly HSPE fibers to meet rising regional demand for green textile products.
Indorama Ventures
Indorama's focus on chemical and fiber manufacturing includes bolstering Vietnamese production lines to accelerate the supply of high-strength polyethylene fibers amid rising domestic and regional demand.
SABIC Innovative Plastics
SABIC is advancing its polymer composite capabilities, investing in Vietnam to develop high-strength fibers catering to automotive and industrial sectors with a focus on sustainability and technological innovation.
Hyosung Tex Corporation
Hyosung Tex is expanding its Vietnamese manufacturing footprint, emphasizing high-strength fiber production for industrial uses, supported by regional R&D centers for advanced polymer development.
Strategic Business Developments

- June 2023 – Hyosung Advanced Materials – Announced new capacity expansion for HSPE fibers in Vietnam – Enhances regional production capacity to meet surging demand from automotive and industrial sectors.
- April 2023 – Celanese Corporation – Launched innovative high-strength PE fiber variant in Vietnam – Strengthens product portfolio, targeting industrial and transportation applications with advanced durability features.
- August 2022 – TSMC – Formed joint venture with local Vietnamese company – Aimed at establishing a sustainable fiber manufacturing plant, ensuring enhanced regional supply chain resilience.
- January 2023 – Indorama Ventures – Invested in Vietnam-based fiber manufacturing infrastructure – Significantly increases output capacity to support growing domestic and export markets.
- May 2022 – SABIC – Implemented new technology platform inVietnam – Focused on high-performance, sustainable HSPE fiber production to reduce environmental footprint and meet green standards.
Frequently Asked Questions
What is the Vietnam High Strength Polyethylene Fibers Market?
The Vietnam High Strength Polyethylene Fibers Market comprises the production, demand, and distribution of durable, high-tensile polyethylene fibers used in industries like construction, defense, and sporting goods within Vietnam. It reflects regional shifts towards advanced, lightweight composite materials.
What is the current market size of Vietnam High Strength Polyethylene Fibers Market?
As of 2026, the market size is estimated at approximately USD 2.4 Billion, driven by rising infrastructural development, increased defense spending, and the adoption of high-strength fibers in Vietnam’s manufacturing sectors, with a steady year-over-year growth rate.
What factors are driving the Vietnam High Strength Polyethylene Fibers Market?
Market growth is primarily fueled by Vietnam’s expanding construction activities, increased military modernization, and the growing demand for lightweight, high-performance composites. Government initiatives and foreign investments further bolster the market's expansion.
Which Vietnamese city leads the Vietnam High Strength Polyethylene Fibers Market?
Hanoi, being Vietnam’s capital and industrial hub, leads the market due to its concentration of manufacturing facilities, government agencies, and corporate investments focused on high-strength fiber production and application development.
Which segment is expected to grow the fastest?
The industrial and construction segment is projected to exhibit the highest growth through 2034, driven by infrastructure upgrades and increased construction projects requiring durable, high-performance materials such as polyethylene fibers.
Who are the leading companies operating in the Vietnam High Strength Polyethylene Fibers Market?
Key players include local and international firms such as Hyosung, Toyobo, and Vietnam-based manufacturers that focus on innovation, quality assurance, and strategic partnerships to enhance their market presence in Vietnam.
Analyst Perspective
The Vietnam High Strength Polyethylene Fibers Market is poised for sustained growth, driven by evolving manufacturing standards and increasing demand across construction, defense, and fishing sectors. Long-term, the market is expected to benefit from ongoing infrastructure development within cities such as Ho Chi Minh City and Hanoi, which present significant opportunities for fiber adoption in reinforced concrete and maritime applications. Technological advancements in fiber manufacturing that enhance tensile strength and durability will be critical, prompting increased investments in research and precision production facilities. Competitive intensity is likely to remain high as both domestic and international players vie for market share, emphasizing innovation and cost efficiency. Strategically, investors should prioritize establishing local supply chains and fostering partnerships with Vietnam’s expanding industrial clusters to capitalize on rising demand. Considering the diversity of urban growth patterns and the government’s focus on infrastructure resilience, city-specific strategies will be essential. In the long term, competitive differentiation will hinge on technological innovation and localized value chain integration, securing Vietnam’s position as a key regional hub for high-strength polyethylene fibers.
