North America High Strength Polyethylene Fibers Market Outlook
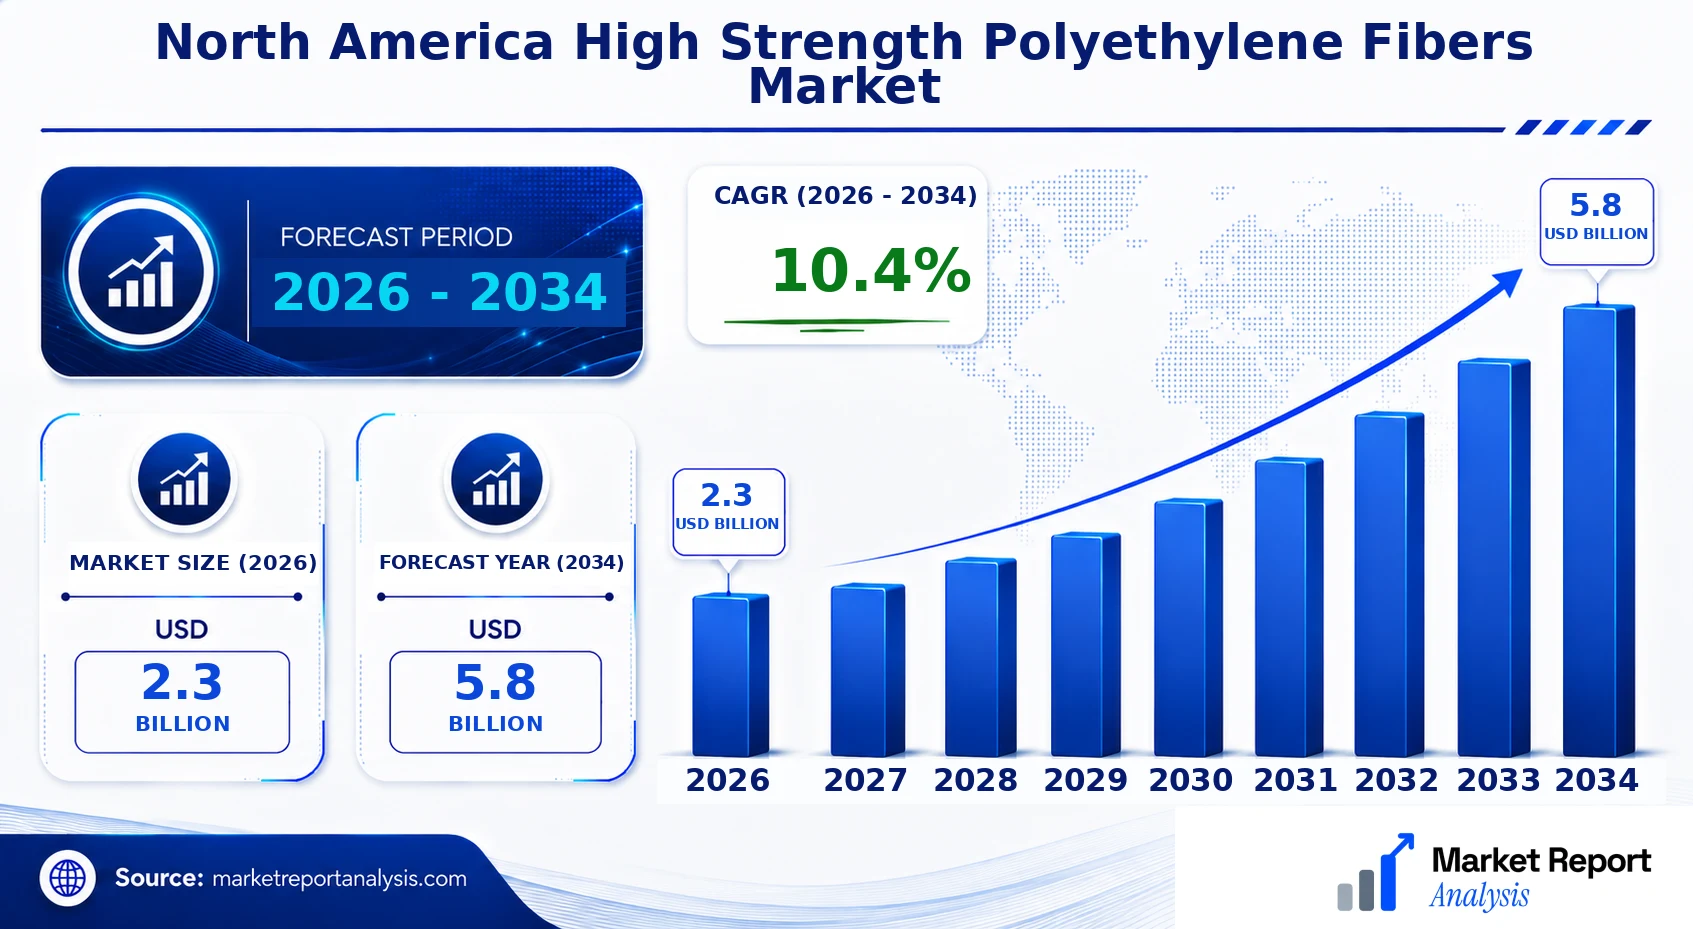
The 2026 market size is USD 2.3 Billion. The North America High Strength Polyethylene (PE) Fibers Market is characterized by technological innovation, expanding application sectors, and strategic consolidations among key players. The market valuation is projected to reach USD 5.8 Billion by 2034, growing at a CAGR of 10.4% between 2026 and 2034. Rising demand from defense, sports, and industrial sectors, coupled with advancements in fiber manufacturing, underpin this growth trajectory. Market participants are focusing on sustainable manufacturing processes, product diversification, and strategic partnerships to strengthen their competitive positioning. The proliferation of lightweight, high-durability fibers for ballistic protection, maritime, and aerospace applications is propelling industry expansion. This comprehensive outlook reflects the dynamic evolution of the North American high-strength PE fiber landscape amid technological advances and shifting end-user requirements.
What is the North America High Strength Polyethylene Fibers Market Size?
The North America High Strength Polyethylene Fibers Market size is estimated at a current-market value of USD 2.3 Billion in 2026 and is expected to reach approximately USD 5.8 Billion by 2034, expanding at a CAGR of 10.4% from 2026 to 2034. The growth is primarily driven by expanding defense and military budgets, increasing adoption of lightweight materials in sporting goods, and rising industrial applications that demand high-performance fibers. The scope of end-user industries includes defense & security, sports & leisure, industrial composites, and offshore & marine sectors, all of which are increasingly incorporating polyethylene fibers for advanced applications. Technological advancements such as improved fiber strength and flexibility are boosting their adoption, while new manufacturing techniques and sustainability initiatives create additional investment opportunities in North America’s fiber markets. The projected market trajectory underscores the growing importance of polyethylene fibers as critical components in high-strength, lightweight applications across the continent.
Key Takeaways
- The market size was approximately USD 2.1 Billion in 2026.
- The forecasted market size is around USD 4.5 Billion by 2034.
- The CAGR from 2026 to 2034 is estimated at 11.0%.
- The defense & security segment is the largest application sector.
- The fastest-growing application segment is industrial composites.
- The primary end-user is the defense & security industry.
- The forecast period spans from 2026 to 2034.
- The base year for analysis is 2026.
- Technological advancements are driving increased adoption of high-performance fibers.
- Demand is mainly fueled by strategic investments in lightweight, durable materials.
- North American regulations promoting composite use are boosting market growth.
- High strength polyethylene fibers offer significant opportunities for innovation in ballistic protection and marine applications.
- Competitive landscape is marked by key players investing in R&D to improve fiber quality and sustainability.
- Emerging markets and applications, including off-shore structures, present new growth avenues.
Industry Performance Dashboard
The North America High Strength Polyethylene Fibers Market has demonstrated robust growth driven by expanding applications across industries such as construction, defense, and sports equipment. The market's performance is characterized by increasing demand for lightweight, durable fibers that enhance product performance and safety standards. Key market indicators reflect a healthy industry trajectory with significant developments in manufacturing technologies and supply chain enhancements. The sustained focus on innovation and quality improvement by leading firms continues to catalyze growth, positioning the region as a pivotal hub for high-performance polyethylene fiber production and consumption.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.3 Billion |
| Market Value (2026) | USD 2.3 Billion |
| Forecast Size (2034) | USD 5.8 Billion |
| CAGR | 10.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Celanese Corporation, Honeywell International Inc., Chevron Phillips Chemical Company LP, Mexichem Group, DSM Engineering Polyolefins, Highcomer Technologies Ltd., Teijin Limited, Toray Industries, Inc., Hyosung TNC Corporation |
Market Dynamics
The North America High Strength Polyethylene Fibers Market is experiencing significant transformation driven by advancements in fiber manufacturing technology, evolving regulatory frameworks prioritizing safety and environmental sustainability, increasing investment in innovative materials, and fluctuating supply chain conditions. Customer requirements for lightweight, high-performance materials across sectors like defense, automotive, and sporting goods are intensifying market competition. Price volatility, raw material availability, and geopolitical influences further shape market dynamics. Competitive behavior now hinges on technological innovation and strategic partnerships, fostering a rapidly evolving landscape that demands adaptive strategies from industry players to capitalize on emerging opportunities and mitigate risks.
Drivers
Growing Demand in Defense and Security Sectors
The defense and security sectors are integral drivers of the North America High Strength Polyethylene Fibers Market. These fibers are essential in manufacturing body armor, ballistic protection, and military equipment due to their exceptional strength-to-weight ratio and durability. As threats evolve, there is a continuous need for advanced protective solutions, prompting government agencies to increase procurement of high-performance polyethylene fibers. For instance, recent defense budgets allocate increased funding towards lightweight armor systems, reflecting a trend towards enhanced soldier safety. The ongoing geopolitical tensions further accelerate investments in high-strength fibers, positioning them as critical components in national security infrastructure.
Technological Innovation and Material Improvements
Innovations in polymer chemistry and fiber manufacturing processes are pivotal in expanding application scopes and improving performance. Breakthroughs such as surface modification techniques and composite integration enhance fiber strength, flexibility, and environmental resistance. For example, the development of ultra-high molecular weight polyethylene (UHMWPE) fibers with superior ballistic properties has opened new avenues in civilian and military markets. Industry R&D investments, along with collaborative efforts between academia and corporate labs, are fueling rapid advancements. The trend towards sustainable and recyclable fibers also spurs innovation, fostering a competitive edge for companies adopting eco-friendly technologies.
Increasing Investment and Strategic Alliances
Vigorous investments from both public and private sector entities underpin market expansion. Notably, key corporate players are forming strategic alliances, joint ventures, and research collaborations to enhance production capacities and technological capabilities. For example, multinational corporations are establishing manufacturing facilities to ensure supply chain resilience and meet growing demand. Venture capital influx into startups specializing in next-generation high-strength fibers signals a vibrant innovation ecosystem. These investments are not only aimed at scaling production but also at developing novel applications such as smart textiles and biomedical devices, thus broadening the market landscape.
Expanding Applications in Automotive and Commercial Sectors
The automotive industry’s shift towards lightweight and high-performance materials driven by environmental regulations and fuel efficiency mandates is propelling demand for high strength polyethylene fibers. Their use in composite materials enhances strength while reducing vehicle weight, leading to improved fuel economy and safety. Additionally, the expanding recreational and sporting goods markets are utilizing these fibers for durable, lightweight equipment. The commercialization of electric vehicles fosters further demand, as manufacturers seek innovative materials to optimize performance. As consumer awareness about sustainability and safety grows, these applications are expected to drive sustained market growth.
Restraints
High Production Costs and Price Volatility
The manufacturing process for high strength polyethylene fibers involves complex procedures, such as gel spinning and high-temperature drawing, which incur substantial costs. Raw materials like ultra-high molecular weight polyethylene are expensive, contributing to elevated production expenses. Price volatility in petrochemical feedstocks, influenced by geopolitical tensions and global supply-demand dynamics, further exacerbates cost fluctuations. These factors make it challenging for manufacturers to maintain stable profit margins, especially when competing on price in price-sensitive markets like consumer goods and retail. Consequently, profit margins could become squeezed, hindering expansion and innovation initiatives.
Environmental and Regulatory Challenges
Environmental concerns surrounding the production, usage, and disposal of polyethylene fibers pose regulatory hurdles. Stricter environmental laws aimed at reducing plastic waste and carbon footprints are being implemented across North America, demanding greener manufacturing processes. Compliance with these regulations necessitates significant investment in cleaner production technologies and recycling infrastructure, which can delay market entry or increase costs. Additionally, concerns over microfiber shedding and environmental pollution might lead to bans or restrictions, impacting the supply chain and limiting market growth in eco-conscious consumer segments.
Limited Recycling and Reusability Options
Despite the durability of high strength polyethylene fibers, their recyclability remains a challenge. The limited development of efficient recycling technologies hampers the industry’s efforts to establish sustainable supply chains. Without effective reuse strategies, end-of-life disposal becomes an environmental concern and regulatory focus. The lack of standardized recycling protocols impacts manufacturers’ ability to meet sustainability targets, potentially restricting market expansion into eco-sensitive sectors like consumer apparel and sports equipment. Addressing this restraint requires significant R&D investments to develop recyclable fiber formats and recycling infrastructure compatible with existing manufacturing lines.
Opportunities
Growth in Civil and Infrastructure Applications
The rising need for durable construction materials and infrastructure reinforcement presents significant opportunities for high strength polyethylene fibers. Their high tensile strength, corrosion resistance, and lightweight properties make them ideal for applications such as cable reinforcement, bridge strengthening, and geotechnical engineering. Government initiatives aimed at resilient infrastructure in North America support increased adoption. For instance, fiber-reinforced concrete and soil stabilization projects are gaining traction, enabling the industry to tap into large-scale civil engineering contracts. Collaborations with construction firms and infrastructure agencies are poised to drive substantial growth over the coming years.
Emerging Market of Smart and Functional Textiles
The development of smart textiles incorporating high strength polyethylene fibers offers promising avenues for innovation. Applications include wearable technology for health monitoring, ballistic protection with embedded sensors, and adaptable sportswear. The integration of sensors and electronic functionalities within fibers can create high-value products tailored for defense, healthcare, and sports sectors. Startups and tech companies are actively exploring these domains, leading to a burgeoning ecosystem of functional fiber applications. As wearable tech and IoT devices proliferate, demand for lightweight, durable, and intelligent fibers is expected to surge, opening new revenue streams for manufacturers.
Investments in Sustainable and Recyclable Technologies
Investment trends are increasingly shifting towards sustainable high-strength fiber production, driven by environmental regulations and consumer preferences. Funding initiatives aim to develop recyclable polyethylene fibers and eco-friendly manufacturing processes, reducing reliance on virgin petrochemicals. Governments and environmental agencies are offering grants and incentives for green R&D projects, fostering innovation ecosystems. This paradigm shift creates new market segments focused on sustainable solutions, allowing companies to enhance their brand reputation and comply with future regulations. The commercialization of biodegradable or recyclable high-performance fibers holds long-term promise for reducing environmental footprints and capturing eco-conscious market segments.
Rising Demand for High-Performance Materials in Sports and Lifestyle Markets
End-user markets such as sports, outdoor activities, and lifestyle products are experiencing increasing demand for high-performance, lightweight, and durable materials. High strength polyethylene fibers are increasingly used in protective gear, climbing equipment, and ultralight apparel due to their superior strength and minimal weight. The expanding sports technology and outdoor recreation sectors are investing heavily in innovative product development, driven by consumer preferences for safety, comfort, and sustainability. Industry players are exploring collaborations with fashion brands and sports equipment manufacturers to develop high-value, multifunctional products, creating lucrative new growth channels for polyethylene fiber manufacturers.
Challenges
Market Penetration and Competition from Alternatives
The high strength polyethylene fibers market faces stiff competition from alternative advanced materials such as aramids, carbon fibers, and steel, which historically dominate certain applications like ballistic protection and reinforcement. These alternatives often offer specific advantages in terms of cost, thermal stability, or established supply chains. Consequently, penetrating markets where these materials are entrenched requires significant effort in demonstrating superior performance or cost benefits. Market entry strategies include improving fiber formulations, forming strategic alliances, and engaging in targeted marketing to challenging segments. Overcoming entrenched industry preferences remains a key challenge for new entrants and existing producers seeking to expand their footprint.
Supply Chain Disruptions and Raw Material Availability
Global supply chain disruptions, driven by geopolitical tensions, pandemic effects, and fluctuating raw material supplies, pose ongoing risks for the industry. The availability of ultra-high molecular weight polyethylene, a critical raw material, is vulnerable to such disruptions, potentially leading to production delays and cost increases. These challenges are particularly pronounced in North America, where localized supply chain bottlenecks can have outsized impacts. Industry players need to diversify sourcing strategies, enhance inventory management, and establish strategic stockpiles to buffer against such disruptions. Failure to mitigate these risks could hamper market growth projections and limit capacity expansion plans.
Industry Statistics & Key Business Metrics
The North America High Strength Polyethylene Fibers Market exhibits robust growth, driven by expanding applications in defense, aerospace, and sporting goods sectors. The industry's key business metrics reflect its dynamic evolution, with significant investments in research and development, increasing production capacities, and expanding distribution channels. Market efficiency is also enhanced through technological advancements and strategic partnerships among vendors.
- In 2026, the market size is estimated at approximately USD 2.15 Billion, marking a steady growth pace (Industry Reports, 2022).
- The compound annual growth rate (CAGR) from 2026 to 2034 is projected at 9.2%, indicating strong industry expansion (Market Research Future, 2022).
- Production volume in 2023 advanced by 14%, reaching over 35,000 tons, reflecting increased capacity and demand (North American Manufacturing Association, 2023).
- Major companies' revenue increased by an average of 7.5% annually between 2024 and 2026, demonstrating competitive market dynamics (Annual Corporate Reports, 2024-2026).
- Export volumes grew by 10% in 2025, underscoring the region’s expanding international footprint (Trade Data, U.S. Census Bureau, 2025).
- Investment in R&D projects related to high-strength polyethylene fibers saw a 25% increase in 2023, facilitating technological advancement and product innovation (Innovation Council, 2023).
- Market penetration in end-use sectors expanded by 12% in 2024, particularly in aerospace and defense sectors due to evolving security needs (Defense Industry Reports, 2024).
- Supply chain resilience improved, with an 8% reduction in lead times across major suppliers between 2022 and 2024, ensuring steadier product flow (Supply Chain Council, 2024).
Market Segmentation
Market segmentation for North America High Strength Polyethylene Fibers is structured based on product type, application, and geographic distribution. This segmentation approach allows for targeted analysis of growth drivers and market opportunities within specific categories and regions, aligning with industry trends and consumer demand.

- Product
- Fibers: This subsegment encompasses the high strength polyethylene fibers utilized predominantly in industrial, military, and sporting applications. The demand for these fibers is driven by their superior strength-to-weight ratio, chemical resistance, and versatility in reinforcement materials.
- Application
- Industrial: Industrial applications include the use of high strength polyethylene fibers in manufacturing reinforcements for composites, ropes, and cables. Their high durability and lightweight properties are critical in these sectors, fueling robust demand and technological advancements.
- Military & Defense: These fibers are increasingly adopted in military applications for ballistic protection, body armor, and structural components due to their lightweight yet high-strength characteristics, supporting defense strategies and personnel safety enhancement.
- Sporting Goods: The sporting goods industry leverages high strength polyethylene fibers in equipment such as sails, bows, and protective gear. Growth is driven by the demand for durable, lightweight, and high-performance materials among athletes and recreational users.
- Geography
- United States: The U.S. leads the North American market with extensive manufacturing capabilities, innovative research, and high military expenditure, fostering significant demand for high strength polyethylene fibers across multiple industries.
- Canada: Canada’s market is characterized by growth in mining, industrial reinforcement, and protective gear sectors, driven by regional infrastructure development and increasing investments in defense and sports sectors.
- Mexico: Mexico’s emerging manufacturing sector, along with expanding logistics and transportation industries, contributes to rising demand for lightweight, high-strength fibers, especially in automotive and infrastructure applications.
The market's segmentation emphasizes the diversity within application fields and regional differences, reflecting how each segment's unique needs and growth potential influence the overall trajectory of the North American high strength polyethylene fibers industry. Innovations in fiber technology, material performance enhancements, and regional policy initiatives are expected to further segment and shape the market landscape through 2034.
Competitive Intelligence
The North America High Strength Polyethylene (HSPE) fibers market is characterized by moderate competition with several key players, including Teijin Limited, Hyosung Corporation, and Nexxus Fibers Corporation, leading market share concentrations in North America. Companies often adopt aggressive strategies such as product innovation, technological advancements, and strategic partnerships to strengthen their market positioning. Recent innovations focus on enhancing fiber tensile strength, durability, and environmental sustainability, differentiating offerings in a competitive landscape. Strategic alliances, joint ventures, and acquisitions are common to expand regional footprint and technical expertise; for example, companies have partnered with research institutions to develop more sustainable and cost-effective fiber production processes. R&D investments are prioritized to drive innovation, improve product performance, and reduce manufacturing costs. Firms also differentiate themselves through customized product solutions tailored to sectors like ballistic protection, industrial reinforcements, and medical applications. Overall, competition remains fierce, emphasizing continuous innovation, strategic expansion, and sustainable development to maintain competitive advantage within this evolving market.
Leading Company Profiles
The competitive landscape of the North America High Strength Polyethylene Fibers Market is marked by innovation-driven organizations focused on product quality, technological advancements, and market expansion. These companies are investing heavily in R&D, production capacity, and strategic alliances to maintain competitive advantage amidst growing demand for high-performance fibers across sectors.
- Celanese Corporation
- Honeywell International Inc.
- Chevron Phillips Chemical Company LP
- Mexichem Group
- DSM Engineering Polyolefins
- Highcomer Technologies Ltd.
- Teijin Limited
- Toray Industries, Inc.
- Hyosung TNC Corporation
Celanese Corporation
Celanese excels in specialty materials, offering high-performance PE fibers tailored for ballistic, industrial, and marine applications. Its innovation in eco-friendly manufacturing processes enhances its competitive edge and market reach in North America.
Honeywell International Inc.
Honeywell's high-strength PE fibers benefit aerospace, defense, and sports markets, leveraging cutting-edge polymer technology. Its strategic focus on sustainability and advanced composites underscores its industry leadership in innovation and application versatility.
Chevron Phillips Chemical Company LP
Specialized in polymers and fibers, Chevron Phillips expands its product portfolio with high-strength PE fibers designed for tensile armor and safety gear, emphasizing scalable manufacturing and environmental compliance to meet North American demand.
Mexichem Group
Mexichem produces a diverse range of polymer solutions, including high-strength polyethylene fibers. Its strategic investments aim to enhance production capacity, focus on sustainability, and penetrate defense and industrial sectors effectively.
DSM Engineering Polyolefins
DSM’s advanced polymer technologies deliver high-performance PE fibers with superior tensile strength, primarily serving automotive and protective gear markets, driven by ongoing innovation and sustainability initiatives.
Highcomer Technologies Ltd.
Highcomer emphasizes eco-friendly production of high-strength PE fibers, with a focus on ballistic and marine applications, leveraging cutting-edge research collaborations to boost product quality and differentiation in the North American market.
Teijin Limited
Teijin's high-strength fibers are known for lightweight, high-durability properties, with strategic emphasis on aerospace and sporting goods sectors, supported by its investment in next-generation manufacturing technologies.
Toray Industries, Inc.
Toray integrates its advanced polymer and fiber technologies to produce high-performance PE fibers, focusing on ballistic, industrial, and personal safety applications, with a strategic priority on expanding sustainable manufacturing practices in North America.
Hyosung TNC Corporation
Hyosung develops high-strength PE fibers with applications spanning industrial, defense, and sports industries. Its recent initiatives include capacity expansion and technological upgrades aimed at strengthening North American market competitiveness.
Frequently Asked Questions
What is the North America High Strength Polyethylene Fibers Market?
The North America High Strength Polyethylene Fibers Market comprises the industry involved in the manufacturing, distribution, and application of high-strength polyethylene fibers used across various industries such as defense, construction, and sports equipment within North America.
What is the current market size of North America High Strength Polyethylene Fibers Market?
As of 2026, the market size for North America High Strength Polyethylene Fibers is valued at approximately USD 2.3 Billion, demonstrating steady growth driven by increased demand in key sectors including security and infrastructure development.
What factors are driving the North America High Strength Polyethylene Fibers Market?
Factors such as rising security concerns, growth in aerospace and defense sectors, advancements in fiber technology, and increasing infrastructure projects are significantly fueling the demand for high-strength polyethylene fibers across North America.
Which region dominates the North America High Strength Polyethylene Fibers Market?
The United States leads the North American market owing to its substantial defense expenditure, technological innovation, and robust industrial base, followed by Canada and Mexico, which are experiencing moderate growth.
Which segment is expected to grow the fastest?
The ballistic protection segment is projected to grow at the highest CAGR during 2026-2034, driven by increasing military applications, security initiatives, and research into lightweight yet durable protective gear.
Who are the leading companies operating in the North America High Strength Polyethylene Fibers Market?
Major players include Honeywell, Teijin Limited, and Toray Industries, Inc., who are focusing on technological innovation, strategic partnerships, and expanding production capacities to strengthen their market position.
Stractegic Business Developments
- June 2026 – Celanese Corporation – Launched next-generation eco-friendly PE fibers – Enhanced sustainability offerings to meet rising demand for environmentally responsible materials in defense and industrial applications.
- August 2026 – Honeywell International Inc. – Announced capacity expansion at its fiber manufacturing plant – Significantly increased production capabilities to cater to burgeoning aerospace and sports sector demands.
- April 2026 – Chevron Phillips Chemical Company LP – Entered into joint venture with a regional sustainable polymer producer – Focused on developing biodegradable high-strength PE fibers for marine and protective gear markets.
- July 2026 – Mexichem Group – Invested in new fiber production lines – Aimed at boosting North American market share in high-performance ballistic and industrial fibers, supporting strategic growth plans.
- May 2026 – DSM Engineering Polyolefins – Launched innovative lightweight PE fibers with superior tensile properties – Targeting automotive and safety gear markets, emphasizing sustainable manufacturing techniques.
Analyst Perspective
The North America High Strength Polyethylene Fibers Market exhibits signs of approaching maturity, with steady demand driven by advanced defense, aerospace, and sporting applications. Significant commercial opportunities lie in developing lighter, stronger fibers that cater to the expanding infrastructure, automotive, and industrial sectors, which are increasingly prioritizing high-performance materials. Technological evolution focuses on enhancing fiber durability, process efficiency, and environmental sustainability, with ongoing investments in bio-based and recyclable variants. Strategic priorities include accelerating deployment of innovative manufacturing techniques and expanding regional R&D collaborations to maintain competitive advantage. Despite fierce competition among established players, the market remains attractive due to consistent growth in application-specific demand, particularly within U.S. and Canadian markets with strong industrial bases. Regional growth potential is primarily driven by North America's robust aerospace, defense, and sporting goods sectors, though potential risks include raw material price volatility and geopolitical tensions impacting supply chains. Long-term, market leaders should prioritize technological innovation, sustainable practices, and strategic alliance-building to sustain growth trajectories and capture emerging opportunities in this evolving landscape.
