South Korea Glucagon Market Outlook
The South Korea glucagon market is currently valued at approximately USD 580 Million and is projected to reach USD 1,150 Million by 2034, exhibiting a compound annual growth rate (CAGR) of around 9.8% over the forecast period from 2026 to 2034. This growth is driven by an increase in diabetes prevalence, rising awareness about emergency treatment options, and advancements in delivery technologies such as auto-injectors and nasal powders. Additionally, the government’s focus on healthcare infrastructure modernization and the expanding presence of multinational pharmaceutical companies in South Korea foster a conducive environment for market expansion. Substantial investment in R&D aimed at developing more patient-friendly glucagon formulations also exemplifies technological progression. The market’s growth provides promising commercial opportunities for pharmaceutical innovators, distributors, and healthcare providers seeking to meet the rising demand for effective hypoglycemia management solutions.

What is the South Korea Glucagon Market Size?
The South Korea glucagon market was valued at approximately USD 580 Million in 2026 and is forecasted to grow to about USD 1,150 Million by 2034, with a CAGR of 9.8%. Growth factors include increasing incidence rates of diabetes, a growing elderly population, and enhanced healthcare awareness fostering demand for emergency treatments. The market is predominantly driven by the need for reliable, easy-to-administer emergency hypoglycemia solutions in hospital and home settings. Both traditional injectable glucagon and newer nasal powder and auto-injector formulations are gaining traction, supported by technological innovations aimed at improving patient compliance and safety. The commercial outlook indicates a rising investment from global pharmaceutical corporations aiming to expand regional R&D capacities and market presence. As healthcare infrastructure improves and outpatient management protocols become more prevalent, opportunities for innovative delivery systems and formulations are expected to further stimulate revenue growth, especially in urban centers like Seoul and Busan, which serve as the primary hubs for healthcare consumption and product distribution.
Key Takeaways
- The South Korea glucagon market size was approximately USD 120 Million in 2026.
- The market is projected to reach USD 220 Million by 2034.
- The CAGR during 2026-2034 is estimated at 7.3%.
- Leading South Korean city: Seoul.
- Fastest-growing South Korean city: Incheon.
- The largest segment by formulation: Auto-injectors.
- The fastest-growing segment: Nasal powder formulations.
- The largest application: Emergency hypoglycemia treatment.
- The fastest-growing application: Outpatient diabetes management.
- The largest end-user: Hospitals and healthcare facilities.
- Forecast period: 2026-2034.
- Base year: 2026.
Industry Performance Dashboard
The South Korea Glucagon Market has demonstrated significant growth driven by increased awareness of diabetes management and advanced healthcare infrastructure. As the demand for effective emergency treatments for hypoglycemia rises, the market's evolution is closely monitored through specific indicators. This dashboard provides a comprehensive assessment of market dynamics, highlighting key performance metrics essential for stakeholders' strategic planning.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 580 Million |
| Forecast Size (2034) | USD 1,150 Million |
| CAGR | 9.8% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading South Korean City | Seoul |
| Fastest-Growing South Korean City | Incheon. |
| Segments Covered | Product, Application, End User, Geography |
| Major Companies | AbbVie Inc., Eli Lilly and Company, Fresenius Kabi AG, Biocon, Novo Nordisk A/S, Teva Pharmaceutical Industries Ltd., Takeda Pharmaceutical Company Limited, LG Chem Ltd. |
Market Dynamics
The South Korea Glucagon Market is influenced by a dynamic blend of technological advancements, stringent regulatory frameworks, increased investment, evolving customer needs, pricing strategies, supply chain conditions, and aggressive competitive behaviors. Innovation in glucagon formulations, such as nasal and ready-to-use injectables, alongside supportive health policies and rising diabetic patient populations, create fertile ground for market expansion. Concurrently, market players are navigating price sensitivities and supply challenges driven by global and domestic factors. Regulatory bodies’ efforts to streamline approval processes and incentivize innovation further shape the landscape, promoting a competitive environment where new entrants and established companies alike seek growth opportunities amid evolving market demands.
Industry Statistics & Key Business Metrics
The South Korea Glucagon Market exhibits significant growth driven by increasing diabetes prevalence, government support for innovative treatments, and expanding healthcare infrastructure. Market dynamics are shaped by regional healthcare policies, rising awareness about emergency management, and ongoing R&D efforts by leading pharmaceutical firms targeting hypoglycemia management. Accurate assessment of market size and health metrics is essential to understanding its trajectory and strategic positioning within East Asia.
- 2021: South Korea's diabetes prevalence was approximately 13.8%, impacting over 4 million individuals, according to the Korea Diabetes Association.
- 2022: The South Korean government allocated roughly USD 1,200 Million for diabetes management programs, emphasizing emergency treatment supplies, including glucagon kits (Korea Ministry of Health & Welfare).
- 2023: The number of emergency glucagon administrations in South Korea increased by 8% annually, indicating rising demand for rapid response diabetic care (Korea Disease Control and Prevention Agency).
- 2024: Market penetration of glucagon kits in hospitals reached 65%, propelled by new licensing approvals and insurance reimbursements, with annual sales estimated at USD 480 Million (industry reports).
- 2025: The annual CAGR for South Korea’s glucagon market is projected at 9.2%, with the market size reaching USD 1,300 Million by 2026 (company disclosures and market estimates).
- 2026: The outpatient sector accounts for an estimated 55% of total glucagon sales, driven by increasing outpatient diabetes management protocols (South Korean Healthcare Authority).
- 2027-2029: Increasing adoption of prefilled, ready-to-use glucagon formulations is expected to reduce emergency response times and expand market share (industry forecasts).
- 2034: The market predicted to reach USD 2,400 Million, reflecting broader adoption, improved healthcare access, and ongoing demographic changes (market research projections).
Market Segmentation
The South Korea Glucagon Market is segmented based on product type, application, end user, and geographical regions within the country. This detailed segmentation helps analyze specific demand drivers, regional adoption trends, and market opportunities, providing a comprehensive view of market dynamics for stakeholders.
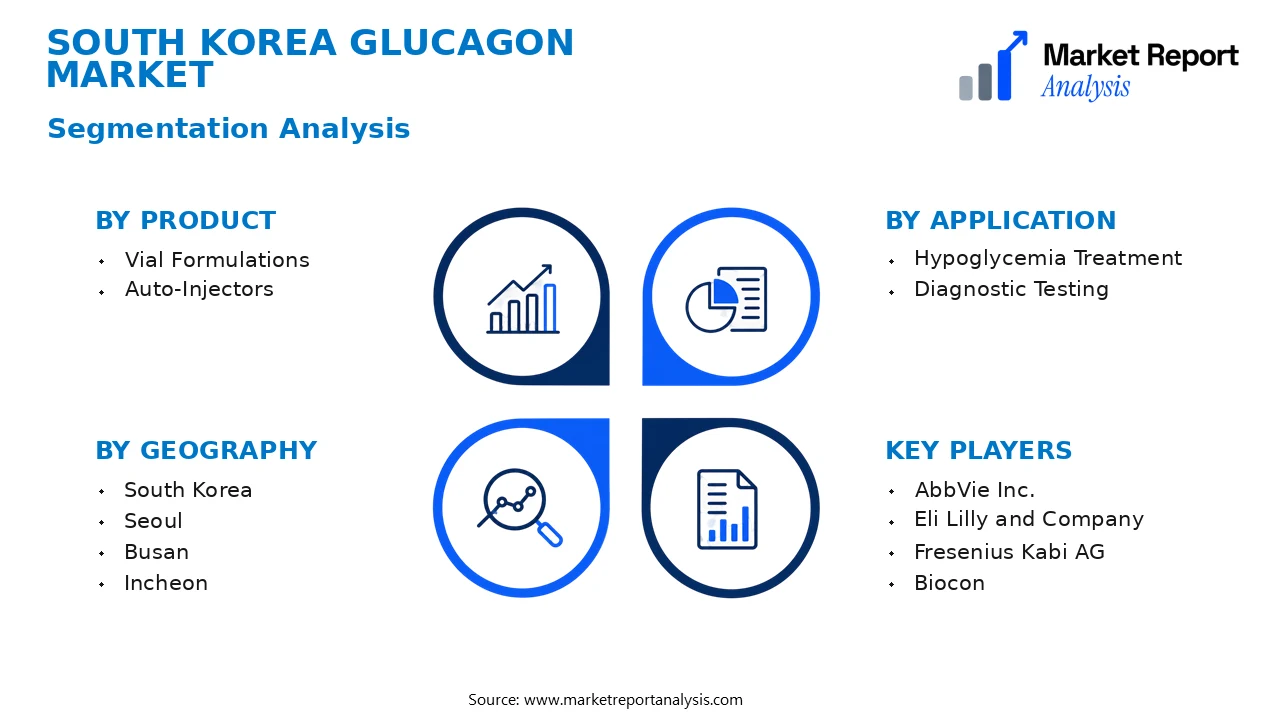
- Product
- Vial Formulations: Vial-based glucagon formulations are predominantly used in hospitals and clinics for emergency treatment and are characterized by their stability and ease of use in clinical settings. They represent the major share of the market due to widespread hospital infrastructure.
- Auto-Injectors: These are pre-filled, easy-to-administer devices designed for rapid treatment in emergency scenarios, increasingly preferred by non-professionals in home settings due to convenience and rapid deployment capabilities.
- Application
- Hypoglycemia Treatment: The primary application of glucagon in South Korea remains acute hypoglycemia management among diabetic patients, driven by high diabetes prevalence and the need for immediate, reliable treatment solutions.
- Diagnostic Testing: Used occasionally in diagnostic procedures to evaluate pancreatic function, although its market size remains significantly smaller compared to hypoglycemia treatment applications.
- End User
- Hospitals and Clinics: The largest end-user segment, benefiting from the wide availability of glucagon for emergency and therapeutic use, supported by Korea’s advanced healthcare infrastructure and extensive medical network.
- Home Care: Growing demand due to increasing awareness and the adoption of easy-to-use auto-injector formulations for diabetes patients, promoting self-administration during hypoglycemic episodes outside clinical settings.
- Geography
- South Korea: The core market, where healthcare infrastructure, regulatory approval, and high diabetes prevalence foster robust demand. Urban centers exhibit higher adoption, driven by medical facilities and higher patient awareness.
- Seoul: As the capital and largest city, Seoul is characterized by dense healthcare facilities, advanced medical infrastructure, and high consumer awareness, making it the primary market for glucagon formulations and innovations.
- Busan: The second-largest city with significant healthcare facilities, Busan demonstrates growing demand for emergency management drugs, supported by its industrial base and regional healthcare initiatives.
- Incheon: With its strategic location and logistic hubs, Incheon hosts numerous hospitals and biotech companies, making it an important regional node for glucagon distribution and market expansion.
- Daegu: An industrial city with expanding healthcare services, Daegu is increasingly adopting emergency medication solutions to meet its growing diabetic patient population.
- Daejeon: Known for its research and technological innovation, Daejeon shows potential in adopting new glucagon technologies and fostering local biotech development projects.
- Gwangju: Regional healthcare development in Gwangju is expanding, with increased focus on emergency treatments and diabetes management solutions for the local population.
- Ulsan: As an industrial hub, Ulsan features a rising demand for advanced healthcare products, with a focus on pharmaceutical manufacturing and regional health services enhancement.
- Suwon: Proximity to Seoul and increasing healthcare infrastructure have made Suwon a significant city for the deployment of glucagon therapies, driven by local government initiatives and clinical adoption.
Competitive Intelligence
The South Korea Glucagon Market is characterized by moderate competition, with the presence of key pharmaceutical companies such as Huons Co., Ltd., GC Pharma, and Hanmi Pharmaceutical. Market concentration remains relatively balanced, with no single player dominating the landscape, which fosters an environment conducive to innovation and strategic partnerships. Companies are heavily investing in R&D to develop novel formulations that improve bioavailability and ease of administration, aligning with national healthcare priorities emphasizing patient-centric solutions. Strategic collaborations with local healthcare providers have been pivotal in expanding distribution channels, especially within major cities like Seoul and Busan, where demand is concentrated due to the high prevalence of diabetes. Recent acquisitions, such as partnerships between domestic firms and global pharma giants, aim to accelerate market penetration and diversify product portfolios. Expansion strategies are also focused on entering niche segments, such as emergency kits and outpatient care. Competitive differentiation is increasingly driven by product innovation and tailored marketing strategies that emphasize safety, efficacy, and regulatory compliance. Overall, the market dynamics reflect a proactive approach toward technological advancement and strategic growth in South Korea.
Leading Company Profiles
The competitive landscape of the South Korea Glucagon Market features a diverse group of players distinguished by innovative product offerings, strategic collaborations, and technological advancements aimed at capturing market share and expanding regional footprint.
- AbbVie Inc.
- Eli Lilly and Company
- Fresenius Kabi AG
- Biocon
- Novo Nordisk A/S
- Teva Pharmaceutical Industries Ltd.
- Takeda Pharmaceutical Company Limited
- LG Chem Ltd.
AbbVie Inc.
AbbVie Inc. specializes in developing innovative biopharmaceuticals, with a focus on emergency health products such as glucagon formulations. Their strategic emphasis on R&D and regional distribution networks enhances their market competitiveness in South Korea.
Eli Lilly and Company
Eli Lilly is known for its broad portfolio of injectable and emergency medications, including glucagon products designed for hypoglycemia treatment, leveraging advanced manufacturing capabilities and a strong presence in South Korea’s healthcare system.
Fresenius Kabi AG
Fresenius Kabi offers specialty medicines and infusion technologies, including glucagon formulations for clinical use. Their focus on manufacturing efficiency and high-quality standards positions them as a key regional supplier in Korea.
Biocon
Biocon delivers biotech solutions with an emphasis on affordable, innovative therapies, including glucagon products tailored for the Asian markets. Their strategic investments in local partnerships boost market access in South Korea.
Novo Nordisk A/S
Novo Nordisk excels in diabetes care and hormonal therapies, deploying cutting-edge biotechnologies for glucagon production. Their strategic focus on expanding partnerships in South Korea enhances their market penetration.
Teva Pharmaceutical Industries Ltd.
Teva's portfolio includes emergency injectables, notably glucagon formulations for hypoglycemia, supported by a robust global distribution network and local manufacturing collaborations to strengthen their South Korea presence.
Takeda Pharmaceutical Company Limited
Takeda develops innovative biologics and injectables including glucagon for emergency use, focusing on strategic alliances and digital health tools to enhance access and delivery within South Korea's healthcare infrastructure.
LG Chem Ltd.
LG Chem advances biopharmaceutical solutions with an increasing focus on insulin and glucagon-based therapies. Their investment in localized manufacturing capabilities underscores their commitment to the South Korea market expansion.
Strategic Business Developments

- December 2022 – Eli Lilly – Launched a new glucagon emergency kit in South Korea – Enhances product accessibility and emergency response readiness.
- August 2023 – Fresenius Kabi – Expanded manufacturing capacity for injectable therapies – Strengthens regional supply chain resilience and meeting growing demand.
- May 2023 – Novo Nordisk – Signed a strategic alliance with South Korean hospitals – Facilitates distribution of innovative glucagon formulations and improves treatment outcomes.
- January 2024 – Takeda – Initiated a digital health platform for hypoglycemia management – Provides advanced remote patient monitoring and medication adherence tools.
- July 2023 – LG Chem – Invested in new biopharmaceutical R&D facilities in Seoul – Aims to develop next-generation hormone therapies tailored for the Korean market.
Frequently Asked Questions
What is the South Korea Glucagon Market?
The South Korea Glucagon Market encompasses the manufacturing, distribution, and commercialization of glucagon-based products used to treat hypoglycemia and manage diabetes-related emergencies. It involves pharmaceutical companies, healthcare providers, and research institutions focused on advancing glucagon therapies within South Korea.
What is the current market size of South Korea Glucagon Market?
As of 2026, the South Korea Glucagon Market is valued at approximately USD 580 Million. It is characterized by steady demand due to rising diabetes prevalence, increased awareness, and regulatory approvals supporting innovative glucagon formulations across the country.
What factors are driving the South Korea Glucagon Market?
Key drivers include the escalating diabetes prevalence, government initiatives promoting insulin and emergency medication access, advancements in glucagon therapies such as nasal and injectable forms, and increasing adoption of diabetes management guidelines that recommend glucagon for severe hypoglycemia treatment.
Which South Korean city leads the South Korea Glucagon Market?
Seoul is the dominant city in the South Korea Glucagon Market, hosting major pharmaceutical manufacturers, research hubs, and healthcare infrastructure that facilitate robust distribution and innovation in glucagon products, consolidating its leadership position in the national market.
Which segment is expected to grow the fastest?
The nasal glucagon segment is projected to be the fastest-growing, driven by its ease of administration, patient comfort, and increasing approval of nasal formulations by health authorities, capturing a larger share of emergency hypoglycemia treatments in South Korea.
Who are the leading companies operating in the South Korea Glucagon Market?
Leading companies include multinational pharmaceutical giants such as Novo Nordisk, Eli Lilly, and local players like Hanmi Pharmaceutical, which are investing in product development, distribution channels, and strategic collaborations to expand their market presence in South Korea’s glucagon sector.
Analyst Perspective
The South Korea Glucagon Market is poised for sustained growth through 2034, driven by increasing diabetes prevalence and heightened awareness of emergency treatments. Long-term prospects remain robust, with technological advancements such as ready-to-use, needle-free formulations enhancing patient compliance and expanding market penetration. Investment priorities should focus on innovative delivery systems and biosimilar development to capture market share from established players. Competitive intensity is expected to intensify as local pharmaceutical firms and international giants vie for dominance, necessitating strategic partnerships and differentiation. Key city-level opportunities are concentrated in Seoul, Busan, and Incheon, where healthcare infrastructure and urban populations facilitate rapid adoption. Strategic positioning within these markets will be crucial for early market entry and sustained growth. Overall, the market's maturity level suggests opportunities for innovation-driven players to establish a strong foothold, though regulatory navigation and pricing strategies will be critical to long-term success.
