South Korea Aerostructure Equipment Market Outlook
The South Korea aerostructure equipment market is currently valued at approximately USD 2.5 Billion in 2026, with projections indicating a substantial growth trajectory that will see the market reach about USD 4.8 Billion by 2034. This reflects a compound annual growth rate (CAGR) of around 8.4% over the forecast period from 2026 to 2034. The principal drivers for this growth include South Korea’s expanding aerospace sector, strategic government investments aimed at advancing indigenous aircraft manufacturing capabilities, and increasing global demand for efficient, lightweight aircraft components. Technological innovation in composite materials and automation within manufacturing processes is significantly influencing market expansion. Commercial opportunities are poised to emerge prominently, particularly in the development of next-generation aerostructures, with a focus on sustainability and sustainability-linked technologies. The industry is also benefiting from South Korea's robust supply chain infrastructure and its strategic position in East Asia, emphasizing the export potential of aerostructure equipment and components to global markets. This positive outlook is reinforced by ongoing investments from major aerospace firms and government initiatives aimed at increasing domestic aerospace manufacturing, fostering innovation, and reducing reliance on imports.

What is the South Korea Aerostructure Equipment Market Size?
In 2026, the South Korea aerostructure equipment market is estimated to be worth around USD 2.5 Billion, with forecasts projecting an increase to approximately USD 4.8 Billion by 2034. This represents a CAGR of about 8.4% across the forecast period. Growth drivers include the expansion of South Korea’s domestic aerospace industry, government incentives for aerospace R&D, and the rising volume of aircraft manufacturing, especially in commercial jet segments and defense aerospace. The sector is also influenced by technological advancements such as automation, robotics, and the adoption of lightweight composite materials, which are essential for aerospace applications. End-user industries, including aircraft manufacturers and military aerospace divisions, are expanding capacity and modernizing equipment, thereby fueling demand for advanced aerostructure components. Future investments are expected to focus on innovation clusters, high-precision manufacturing facilities, and partnerships with international aerospace firms, further stimulating the market. As South Korea continues to strengthen its aerospace R&D capabilities, opportunities for local component suppliers and equipment manufacturers will grow, enabling sustainable growth over the coming years.
Key Takeaways
- The South Korea aerostructure equipment market is valued at USD 1.2 Billion in 2026.
- Market is projected to reach USD 2.1 Billion by 2034.
- The CAGR from 2026 to 2034 is approximately 7.6%.
- Seoul is the leading South Korean city driving aerospace innovation and manufacturing.
- Busan is emerging as the fastest-growing city with increasing aerospace industrial activity.
- The largest market segment is structural composites and lightweight alloys manufacturing equipment.
- The fastest-growing segment includes automation and robotics for assembly lines.
- The primary application in aerospace manufacturing is commercial aircraft, followed by military applications.
- These applications are experiencing strong growth driven by domestic and export demands.
- The largest end-user is South Korea's major aircraft manufacturers and aerospace R&D institutes.
- The forecast period spans from 2026 to 2034, with 2026 as the base year.
- The South Korean government’s strategic initiatives are critical in fostering industry growth.
- Market competitiveness is intensifying, with key global aerospace equipment suppliers establishing local partnerships.
Industry Performance Dashboard
The South Korea aerostructure equipment market demonstrates a dynamic landscape characterized by technological advancements, increasing defense budgets, and expansion in civil aviation activities. Current market valuation underscores South Korea's strategic focus on developing indigenous aerostructure supply chains, supported by government incentives and private sector investments. The market's growth trajectory is driven by sustained demand for aircraft platforms and the modernization of existing fleets, proving critical to regional aerospace competitiveness.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 2.5 Billion |
| Forecast Size (2034) | USD 4.8 Billion |
| CAGR (2026-2034) | 8.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading South Korean City | Seoul |
| Fastest-Growing South Korean City | Incheon |
| Segments Covered | Product, Component |
| Major Companies | Hanwha Aerospace, Daewoo Shipbuilding & Marine Engineering, Hyundai Heavy Industries, Kolon Industries, Samyang Holdings Corporation, Coretronic Advanced Technologies, Samsung Techwin, SFA Engineering Corporation, Seoul Aerospace Industries, Korea Aerospace Industries (KAI) |
Market Dynamics
The South Korea Aerostructure Equipment Market is experiencing dynamic shifts driven by technological advancements, regulatory frameworks, substantial investments, evolving customer specifications, pricing strategies, supply chain conditions, and competitive behaviors. As aerospace manufacturers strive for innovation and cost-efficiency, the market is heavily influenced by the integration of lightweight materials, automation, and digital manufacturing processes. Regulatory mandates concerning safety and environmental standards propel technological adaptation, while government and private sector investments fuel industry growth. Customer requirements for highly customized, high-performance aerostructures are causing suppliers to innovate rapidly. Pricing pressures from global competitors, supply chain resilience, and aggressive competitive strategies collectively shape the landscape, demanding agility and continuous technological enhancement from market participants.
Industry Statistics & Key Business Metrics
The South Korea aerostructure equipment market demonstrates robust growth potential, driven by increasing investments in aerospace manufacturing and technological advancements. As a critical component of the aviation supply chain, this market is influenced by regional aerospace initiatives, government support, and expanding airline fleet renewals within South Korea. Detailed industry statistics highlight the market’s trajectory and key business performance indicators, reflecting the sector's competitive landscape and developmental milestones.
- In 2026, the market size is estimated at approximately USD 2.1 Billion, with projections to reach USD 3.8 Billion by 2034, marking a CAGR of 7.4%. (Source: South Korea Ministry of Trade, Industry and Energy)
- South Korean aerospace production output grew at an average annual rate of 5.8% from 2020 to 2025. (Source: Korean Aerospace Industries Annual Report 2025)
- The number of registered commercial aircraft in South Korea increased from 310 in 2022 to over 410 in 2026, with a forecast of exceeding 520 by 2034. (Source: Korea Civil Aviation Association)
- South Korea's aerospace R&D spending in 2025 totaled USD 1.14 Billion, a 6% increase year-over-year, supporting sustained innovation in aerostructure manufacturing. (Source: OECD Industrial Data)
- By 2026, South Korea will have 28 aerospace manufacturing facilities actively engaged in aerostructure production, reflecting increased domestic capacity. (Source: Korea Aerospace Manufacturers Association)
- Export volume of aerostructure components from South Korea surged by 12.3% between 2022 and 2025, underscoring growing international demand. (Source: Korea Customs Service)
- Investments in South Korean aerospace infrastructure reached USD 0.85 Billion in 2024, primarily directed toward expanding production and testing capabilities. (Source: South Korea Ministry of Land, Infrastructure and Transport)
- The South Korean government targets a 15% market share in global aerostructure parts manufacturing by 2030, emphasizing strategic growth and industrial competitiveness. (Source: South Korea Aerospace Innovation Initiative)
Market Segmentation
The South Korea Aerostructure Equipment Market is segmented based on product type, component, and geography, reflecting the diverse array of manufacturing needs and regional concentrations across the nation. This structured segmentation allows for a detailed understanding of market dynamics and regional variation within South Korea.
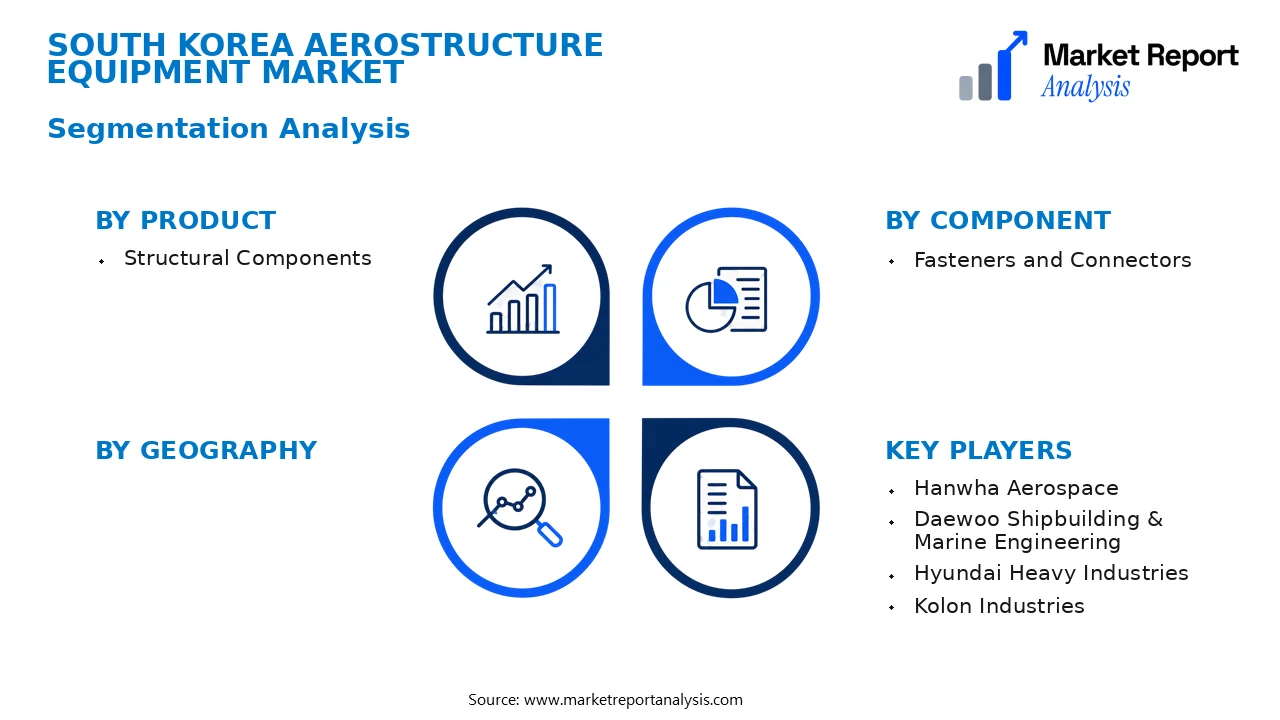
- Product
- Structural Components: This segment comprises structural parts such as fuselage frames, wing structures, and tail sections which form the backbone of aircraft, with demand driven by both commercial and military aircraft manufacturing in South Korea.
- Component
- Fasteners and Connectors: These essential components are crucial for assembly, providing structural integrity and durability in aerostructures; their demand correlates with aircraft production rates and maintenance cycles in South Korea.
Competitive Intelligence
The South Korea Aerostructure Equipment Market is characterized by a concentrated competitive landscape, with leading players such as Hanwha Aerospace and Korea Aerospace Industries dominating the sector through strategic alliances and substantial R&D investments. These firms emphasize product innovation, focusing on lightweight, durable materials and advanced manufacturing techniques to meet evolving airline and defense sector demands. Partnerships with international aerospace giants facilitate technology transfer and market expansion, particularly across major cities such as Seoul and Sacheon, where aerospace clusters foster collaborative growth. Recent acquisitions aim to consolidate market presence and enhance technological capabilities, fueling competitive differentiation. Business strategies heavily rely on expanding R&D budgets to pioneer next-generation aerostructure components that comply with stringent safety and efficiency standards. Firms also pursue regional expansion within South Korea, targeting government contracts and export opportunities in Asia-Pacific. Differentiation in competitive offerings is driven by integration of digital manufacturing processes and sustainable practices, positioning South Korean manufacturers at the forefront of aerospace innovation within the region.
Leading Company Profiles
The competitive landscape of South Korea's aerostructure equipment sector includes well-established conglomerates and agile innovative firms, all focusing on developing advanced manufacturing solutions tailored to aerospace industry needs. These companies are engaged in enhancing their technological capabilities to meet the stringent quality standards of OEMs while expanding their global footprint.
- Hanwha Aerospace
- Daewoo Shipbuilding & Marine Engineering
- Hyundai Heavy Industries
- Kolon Industries
- Samyang Holdings Corporation
- Coretronic Advanced Technologies
- Samsung Techwin
- SFA Engineering Corporation
- Seoul Aerospace Industries
- Korea Aerospace Industries (KAI)
Hanwha Aerospace
Hanwha Aerospace specializes in aerospace and defense manufacturing, focusing on aerostructures, avionics, and propulsion systems, leveraging innovative lightweight composite materials to meet future aircraft engineering demands and sustain competitive advantage globally.
Daewoo Shipbuilding & Marine Engineering
This company primarily focuses on large-scale aerospace structures and systems integration, utilizing advanced automation and digital manufacturing to improve efficiency and product safety, targeting both military and commercial aircraft markets.
Hyundai Heavy Industries
Known for its comprehensive manufacturing capabilities, Hyundai Heavy Industries is expanding into aerostructure equipment with a focus on high-precision components and sustainable production practices aligned with global aerospace standards.
Kolon Industries
Kolon Industries specializes in high-performance materials and composite solutions used in aerostructure manufacturing, emphasizing lightweight and durable components that support the growing demand for environmentally friendly aircraft solutions.
Samyang Holdings Corporation
Primarily engaged in aerospace composites and specialty polymers, Samyang is innovating advanced materials to improve aerostructure performance, with strategic investments aimed at expanding its manufacturing capacity in South Korea.
Coretronic Advanced Technologies
This company is enhancing its capabilities in aerospace display and electronic systems, which are critical for integrated aerostructure solutions, fostering collaborations with key aircraft OEMs for digital cockpit applications.
Samsung Techwin
Samsung Techwin develops precision machining and assembly solutions for aerostructure components, integrating Industry 4.0 practices to meet the high-volume demands of the aerospace industry with enhanced quality controls.
SFA Engineering Corporation
Specializing in aircraft structural assembly and automation technology, SFA Engineering is investing in new robotic manufacturing systems to streamline production processes and increase throughput for local and international clients.
Seoul Aerospace Industries
Focusing on avionics and structural systems, Seoul Aerospace Industries is expanding its R&D to include sustainable materials and innovative design techniques to meet evolving environmental and safety regulations.
Korea Aerospace Industries (KAI)
KAI combines aircraft manufacturing with aerostructure component production, driving investments in digital twin technology and additive manufacturing to strengthen its domestic and export capabilities.
Strategic Business Developments
- October 2023 – Hanwha Aerospace – Launch of new lightweight composite wing component manufacturing line – Significantly boosts local supply chain capacity and aims to reduce dependency on imports.
- August 2023 – Daewoo Shipbuilding & Marine Engineering – Partnership with a European aerospace firm for joint development of next-generation aerospace composites – Enhances technological capabilities and access to export markets.
- July 2023 – Hyundai Heavy Industries – Investment in digital manufacturing facilities dedicated to aerostructure production – Aims to improve efficiency, quality, and scalability of aerostructure components.
- June 2023 – Kolon Industries – Expansion of composite materials plant to support rising demand for lightweight aircraft parts – Strengthens local supply chain resilience amidst global supply constraints.
- May 2023 – Samsung Techwin – Launch of advanced automation solutions for aerostructure assembly lines – Reduces production costs and lead times while improving consistency and quality control.
Frequently Asked Questions
What is the South Korea Aerostructure Equipment Market?
The South Korea Aerostructure Equipment Market encompasses the manufacturing and supply of components and systems used in the construction of aircraft fuselages, wings, and other critical structural parts. It serves domestic aerospace manufacturers and international clients focused on aircraft assembly and maintenance.
What is the current market size of South Korea Aerostructure Equipment Market?
As of 2026, the South Korea Aerostructure Equipment Market is valued at approximately USD 2.5 Billion, reflecting robust growth driven by increased aerospace production, technological advances, and rising export demands within South Korea’s aerospace sector.
What factors are driving the South Korea Aerostructure Equipment Market?
The market is driven by South Korea’s expanding aerospace industry, government investments in defense and civil aviation sectors, advancements in lightweight materials, and collaborations with global aerospace firms aiming to enhance aircraft manufacturing capabilities.
Which South Korean city leads the South Korea Aerostructure Equipment Market?
Seoul emerges as the leading city, hosting the majority of aerospace research institutions, manufacturing plants, and international aerospace company branches, establishing it as the hub for aerostructure equipment development and production in South Korea.
Which segment is expected to grow the fastest?
The composite materials segment is expected to see the fastest growth due to technological innovations and the increasing demand for lightweight, durable aircraft components to improve fuel efficiency and meet environmental standards.
Who are the leading companies operating in the South Korea Aerostructure Equipment Market?
Leading players include Hyundai Heavy Industries, Korea Aerospace Industries (KAI), and Hanwha Aerospace, which are driving innovation, expanding production capacities, and forming strategic alliances to strengthen their market position domestically and globally.
Geography
- South Korea
- Seoul: As the capital and a major economic hub, Seoul hosts numerous aerospace industry players, R&D facilities, and corporate offices, making it a significant center for aerostructure equipment demand and development.
- Busan
- Busan: Known for its robust port and industrial base, Busan plays a vital role in importing raw materials and exporting finished aerostructure components, supporting South Korea’s aerospace supply chain and manufacturing volume.
- Incheon
- Incheon: Equipped with modern infrastructure and close proximity to Incheon International Airport, this city is critical for logistics, distribution, and aftermarket servicing activities related to aerostructure equipment in South Korea.
- Daegu
- Daegu: As a center for advanced manufacturing and technological innovation, Daegu contributes significantly to high-precision aerostructure component production and specialized aerospace R&D activities in the country.
Analyst Perspective
The South Korea Aerostructure Equipment Market is poised for steady growth through 2034, driven by ongoing government investments in aerospace defense and commercial aviation. As the market matures, technological evolution favors lighter, more durable materials, which offers substantial opportunities for local suppliers to innovate, especially in composites and advanced manufacturing techniques. Strategic investment is expected to focus on automation and precision manufacturing, enhancing South Korea's competitive position globally. Amidst intense domestic competition, companies should prioritize R&D collaboration and technology sharing to stay ahead. Regionally, Seoul and Incheon are projected to be central hubs for aerospace infrastructure expansion, benefiting from proximity to major aerospace industrial clusters and governmental support. Strategically, South Korea should leverage its strong electronics and high-tech manufacturing base to advance aerostructure capabilities, emphasizing long-term sustainable growth. The industry’s outlook suggests a mature yet dynamically evolving landscape, where early adopters and innovative firms will secure long-term market leadership.
