Aerostructure Equipment Market Outlook
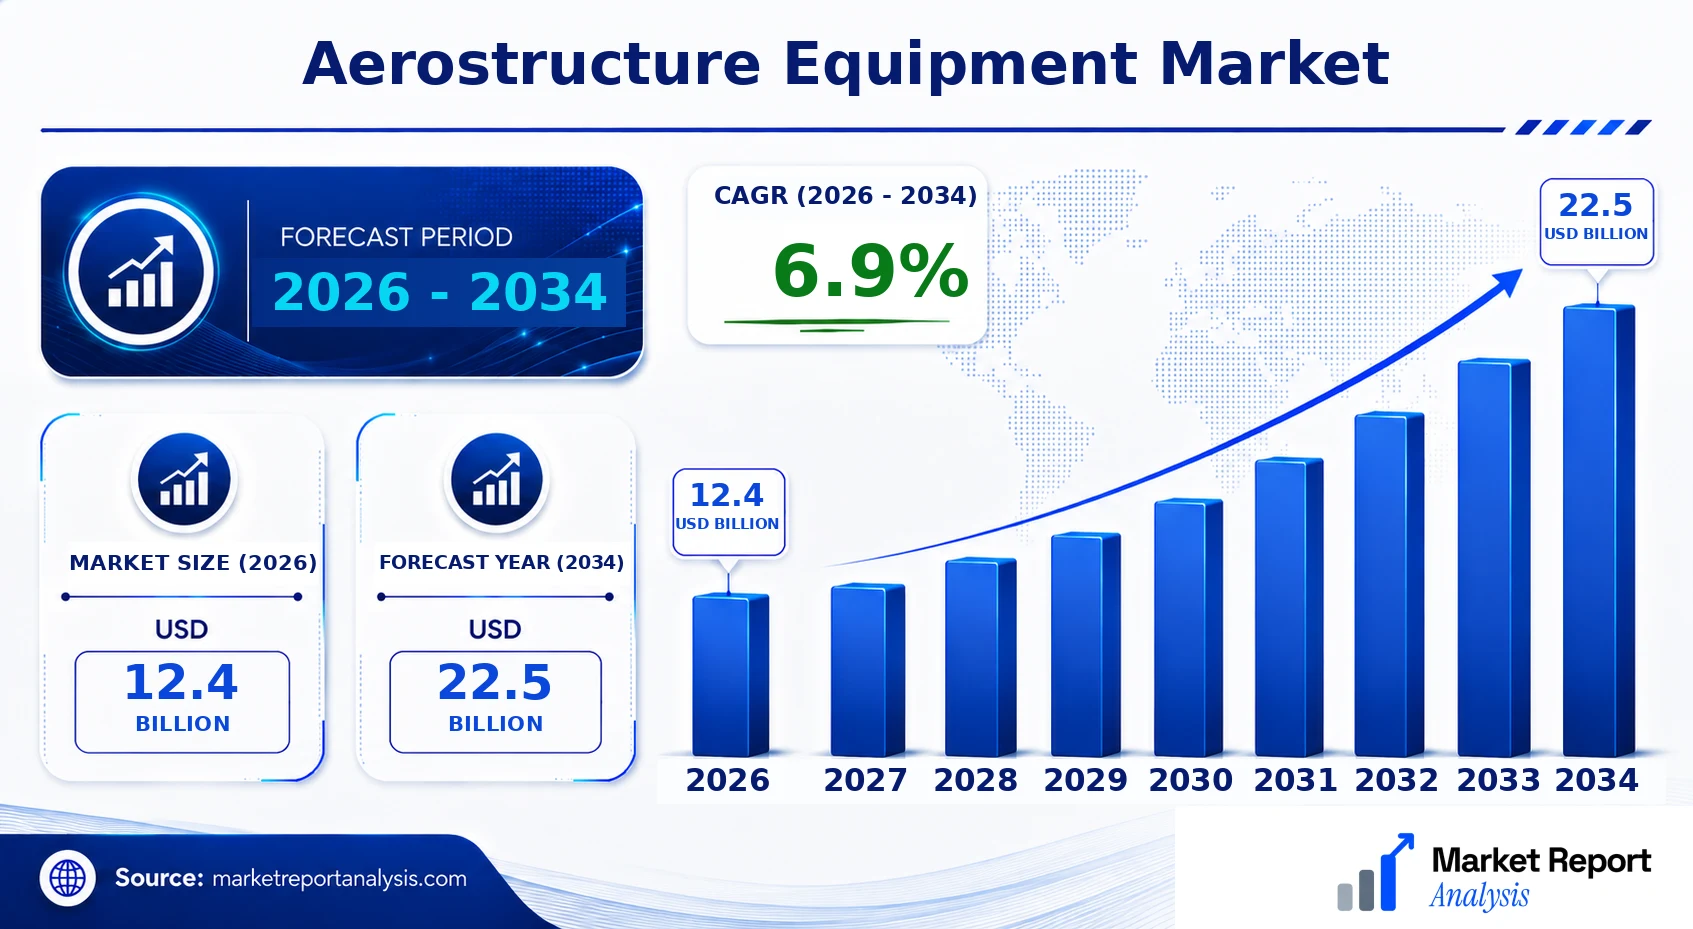
The global aerostructure equipment market is experiencing robust growth driven by increasing aircraft production, technological advancements, and expanding investments in aerospace infrastructure. As of 2026, the market valuation stands at USD 12.4 Billion, with projections indicating a rise to USD 22.5 Billion by 2034. This growth corresponds to a Compound Annual Growth Rate (CAGR) of approximately 6.9% over the forecast period from 2026 to 2034. The principal demand drivers include rising air travel demand, modernization of existing fleet, and the development of next-generation aircraft such as fuel-efficient and lightweight models. Technological innovations, particularly in composite materials and automation, are shaping the industry, offering increased efficiency and reduced manufacturing costs. The commercial aerospace sector remains the dominant end-use industry, but military and regional aircraft markets also contribute significantly. The market presents lucrative opportunities for manufacturers investing in advanced manufacturing techniques, sustainable aerospace components, and strategic partnerships across regions.
What is the Aerostructure Equipment Market Size?
In 2026, the aerostructure equipment market is valued at approximately USD 12.4 Billion and is forecasted to reach USD 22.5 Billion by 2034. This reflects a CAGR of around 6.9% during the period from 2026 to 2034. The growth is propelled by surging demand for commercial aircraft, particularly next-generation models emphasizing fuel efficiency and lightweight design. Technological progress in composite materials and automation is further supporting market expansion. End-use industries, primarily commercial aerospace, are benefiting from increased air traffic, fleet upgrades, and new aircraft programs. Military aircraft procurement and regional jets also contribute to the positive outlook. Future investments are expected in advanced aerostructure manufacturing, sustainable materials, and integrated design solutions, making this sector highly attractive for industry stakeholders seeking innovation and growth opportunities across diverse geographic regions.
Key Takeaways
- The global aerostructure equipment market is projected to grow from USD 28.5 Billion in 2026 to USD 45.2 Billion by 2034.
- The market is expected to expand at a CAGR of approximately 6.72% between 2026 and 2034.
- Demand is driven by rising commercial aviation, fleet modernization, and technological advancements in lightweight and composite materials.
- North America and Europe lead the market, with Asia-Pacific emerging as a significant growth region.
- Commercial aerospace accounts for the majority share, with military and regional aircraft also contributing.
- Innovations in automation, material science, and manufacturing processes are key industry trends.
- Increasing focus on sustainable and eco-friendly aerostructures presents new growth avenues.
- Market players are investing heavily in R&D to develop advanced, lighter, and more durable materials.
- Strategic partnerships and acquisitions are common to expand technological capabilities and regional reach.
- Regulatory environments and safety standards continue to influence product development trajectories.
- Focus on digitalization and Industry 4.0 practices enhances manufacturing efficiency and scalability.
- The industry offers significant opportunities for new entrants and established players seeking innovation-driven growth.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of key metrics and market dynamics shaping the global aerostructure equipment sector. This structured analysis facilitates strategic decision-making and investment planning by highlighting pivotal indicators that reflect the sector's current state and future trajectory.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 12.4 Billion |
| Market Value (2026) | USD 12.4 Billion |
| Forecast Size (2034) | USD 22.5 Billion |
| CAGR | 6.9% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Material, Geography |
| Major Companies | Honeywell International Inc., Spirit AeroSystems, Safran Aircraft Engines, Hexcel Corporation, GKN Aerospace, Curtiss-Wright Corporation, Bombardier Inc., Messier-Bugatti-Dowty (Safran Group), Collins Aerospace |
Market Dynamics
The Aerostructure Equipment Market is profoundly influenced by advancements in aerospace technology, evolving regulatory standards, increasing aerospace investments, and shifting customer preferences for lightweight, durable materials. Competitive pressures foster innovation in design and manufacturing, while fluctuating raw material costs and supply chain dynamics further shape market trajectories. Regulatory frameworks aimed at environmental sustainability and safety standards become catalysts for innovation, compelling manufacturers to adapt rapidly. Concurrently, the ongoing digital transformation and strategic alliances among industry giants enhance operational efficiencies and product offerings. Overall, these factors collectively create a complex, competitive environment driving continuous innovation and market evolution.
Drivers
Technological Innovation and Material Advancements
The pursuit of lighter, stronger, and more durable materials has significantly propelled the aerostructure equipment market. Innovations such as carbon fiber composites and novel metals enable aircraft manufacturers to enhance fuel efficiency and reduce emissions, which are critical competitive differentiators. For instance, the adoption of composite materials in commercial aircraft like Boeing 787 has set new industry standards, fostering an upward trajectory in demand for advanced aerostructure components. Furthermore, advancements in manufacturing technologies like additive manufacturing and automation bolster precision, reduce waste, and accelerate production cycles, thereby stimulating market expansion.
Growing Air Travel Demand and Fleet Expansion
Rising global air travel demand, driven by economic growth and increasing middle-class populations, prompts airlines to expand and modernize fleets, directly influencing the aerostructure equipment market. Emerging markets in Asia-Pacific and Africa show particular growth, with airlines investing in new, fuel-efficient aircraft. This trend is supported by statistical growth in passenger traffic, with the International Air Transport Association (IATA) projecting a 4.7% annual increase through 2034. Such expansion necessitates substantial procurement of aerostructure components, thus creating a robust demand pipeline.
Investment in Military and Space Programs
Government and private sector investments in military aircraft and space exploration significantly contribute to the growth of aerostructure equipment. Defense budgets are increasing in North America, Europe, and Asia-Pacific, enabling procurement of advanced, proprietary aerostructure parts for fighter jets, reconnaissance aircraft, and space vehicles. Notably, with space agencies and commercial players like SpaceX and Blue Origin expanding launch capabilities, demand for specialized, high-performance aerostructures is expected to rise. These investments foster innovation and expand potential revenue streams within the sector.
Environmental Regulations and Sustainability Goals
Stringent environmental standards are compelling aerospace manufacturers to develop eco-friendly materials and manufacturing processes, which directly impact the aerostructure equipment market. Regulatory bodies such as the FAA and EASA enforce stricter emissions and waste management policies, encouraging the adoption of lightweight composites and recyclable materials. This regulatory push accelerates research into sustainable aerospace materials and manufacturing techniques, fostering innovation and expanding the scope of market offerings. As sustainability becomes a core industry objective, the demand for environmentally compliant aerostructure equipment is expected to grow markedly.
Restraints
High Production Costs and Price Pressures
The high costs associated with advanced materials, precision manufacturing, and quality control significantly restrain market growth. Aerospace manufacturers face intense price competition, which limits profit margins and discourages investment in new production capabilities. Additionally, the fluctuating prices of raw materials, especially composites and specialty metals, further exacerbate cost pressures. This financial burden often forces industry players to balance innovation with cost containment, potentially delaying the adoption of new technologies and constraining overall market expansion.
Supply Chain Disruptions and Material Shortages
Disruptions in supply chains, driven by geopolitical tensions, pandemics, or natural disasters, pose critical risks to the aerostructure equipment market. Material shortages, particularly in high-performance composites and specialty metals, can lead to production delays and increased costs. These disruptions threaten timely delivery and reliability, impacting customer relationships and contractual obligations. The complex, globalized nature of aerospace supply chains makes them particularly vulnerable, necessitating strategic diversification and inventory management to mitigate risk.
Regulatory and Certification Barriers
Stringent regulatory standards for safety, quality, and environmental compliance create significant entry barriers for new entrants and complicate product development for existing players. Certification processes for aerospace components are lengthy, costly, and technically demanding, often stalling product launches and innovation cycles. Navigating multiple jurisdictional requirements further complicates international trade and market penetration, constraining overall market growth. These regulatory hurdles demand substantial investments in compliance and testing, which can slow industry expansion.
Opportunities
Emerging Markets and Fleet Modernization
Growing aviation markets in Asia-Pacific, Latin America, and Africa present significant opportunities for aerostructure equipment manufacturers. Rapid economic development and rising passenger volumes drive demand for fleet renewal and expansion, necessitating a broad range of aerostructure components. Investment in local manufacturing facilities and strategic alliances could facilitate market entry and foster tailored, cost-competitive solutions. Additionally, modernization programs for aging fleets in mature markets further expand demand, especially as airlines seek to improve fuel efficiency and operational reliability.
Investments in Space and Defense Applications
The increasing allocation of budgets toward space exploration and military aircraft modernization opens new revenue streams. Innovations in lightweight, high-strength materials for spacecraft and advanced aerostructures for military aircraft are critical drivers. Commercial satellite deployment and the growth of small satellite constellations present unique opportunities for specialized aerostructure components, while collaborative projects between government agencies and private firms catalyze product innovation. This ecosystem stimulates investments and provides fertile ground for startups developing next-generation aerospace technologies.
Technological Advancements and Digital Transformation
The industry’s shift toward digital manufacturing, including automation, robotics, and data analytics, creates opportunities to improve efficiency, reduce costs, and enhance customization. Advanced simulation tools and AI-driven design optimization enable faster development cycles and superior product performance. The integration of IoT sensors into aerostructures allows for real-time health monitoring, predictive maintenance, and lifecycle extension, further creating value. Companies investing in these digital enhancements position themselves to capture market share as aerospace customers seek technologically advanced, cost-effective solutions.
Sustainable Materials and Eco-Friendly Manufacturing
The push for sustainability offers vast opportunities to develop green materials and environmentally friendly manufacturing processes. Innovations in bio-based composites, recyclable metals, and low-impact production techniques align with global commitments to reduce carbon footprints. Governments and industry consortia are increasingly funding R&D to promote sustainable aerospace supply chains, fostering innovation ecosystems conducive to commercial investments. Companies that lead in sustainability can differentiate themselves, capture eco-conscious market segments, and meet evolving regulatory standards.
Challenges
Technological Complexity and Certification Processes
The highly specialized nature of aerospace technology, coupled with rigorous certification requirements, presents substantial challenges. Ensuring compliance with safety and environmental standards demands extensive testing, validation, and documentation, often resulting in prolonged product development cycles. These barriers can delay market entry for innovative solutions and increase costs, which may diminish competitiveness. Industry players must invest heavily in R&D and compliance capabilities to navigate these complexities effectively, demanding strategic foresight and resource allocation.
Market Volatility and Geopolitical Risks
Geopolitical tensions, trade disputes, and economic uncertainties create volatile conditions for the aerospace industry. Tariffs, sanctions, and export controls can disrupt supply chains, restrict access to key markets, and increase costs. This unpredictability affects long-term planning and investment decisions, potentially slowing growth and innovation. Companies need resilient supply chain strategies, diversified markets, and proactive risk management approaches to sustain competitiveness amid geopolitical uncertainties.
Industry Statistics & Key Business Metrics
The global aerostructure equipment market is witnessing substantial growth driven by increasing aircraft production, technological innovations, and rising defense budgets worldwide. As of 2026, market dynamics reflect accelerated adoption of advanced materials and manufacturing techniques, setting the stage for notable expansion through 2034. Key industry metrics offer insights into market health, operational scale, and future potential, essential for stakeholders aiming to make informed investment and strategic decisions.
- In 2026, the market size is projected to reach USD 23.8 Billion, reflecting rapid industry expansion (Market Research Future).
- The compound annual growth rate (CAGR) from 2026 to 2034 is estimated at 6.2%, underpinning steady long-term growth prospects (Grand View Research).
- Aircraft deliveries are expected to grow at a CAGR of 4.9% from 2026 to 2034, directly influencing demand for aerostructure equipment (International Air Transport Association).
- The commercial aircraft segment constituted approximately 65% of the market share in 2026, driven by increased passenger traffic and fleet modernization efforts (Boeing Annual Report 2026).
- Military aircraft procurements are projected to expand at a CAGR of 4.8% over the forecast period, fostering growth in defense aerospace segments (U.S. Department of Defense Budget Reports 2026).
- Asia-Pacific accounted for about 38% of global aerostructure equipment market revenue in 2026, with growth driven by emerging economies and increased manufacturing hubs (Aviation Week Network).
- R&D investments in lightweight composite materials totaled USD 1.2 Billion in 2026, indicating a focus on innovation to enhance efficiency and reduce weight (Industry Association Reports).
- The aftermarket segment is expected to grow steadily, with a CAGR of 5.1%, reflecting maintenance, repair, and overhaul activities (OEM Financial Reports 2026).
Market Segmentation
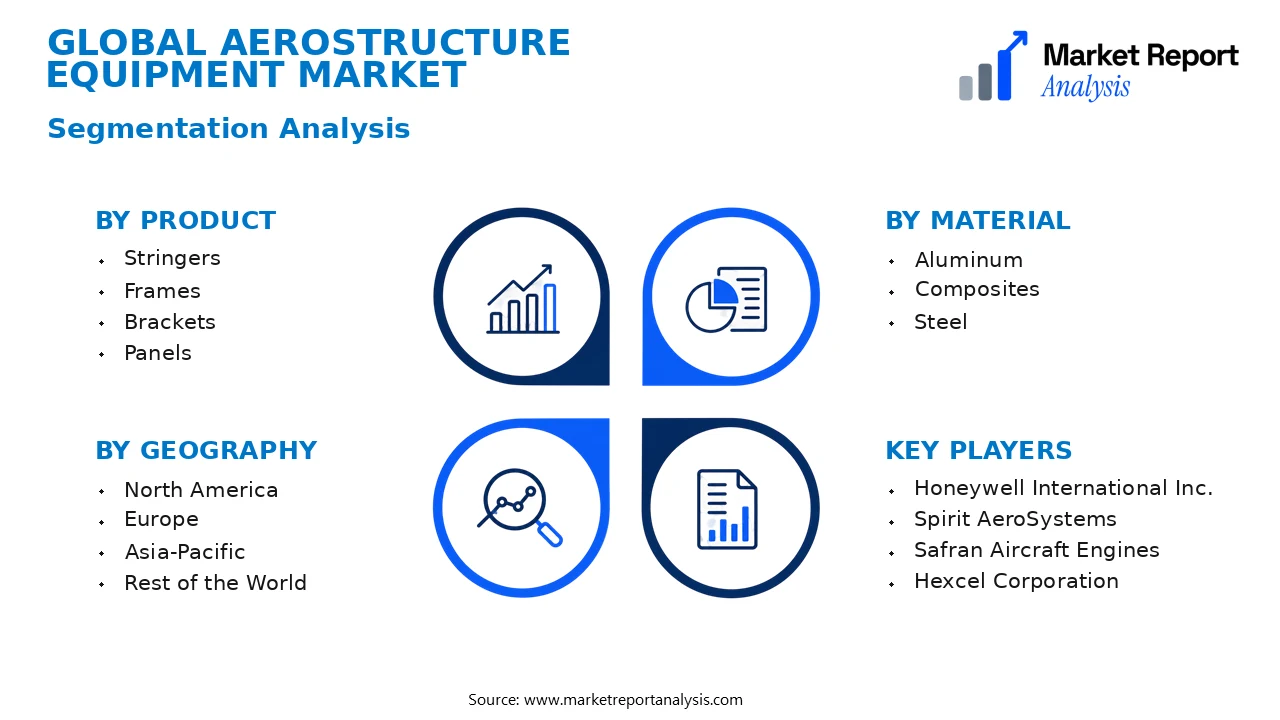
Market segmentation for the Aerostructure Equipment Market is primarily classified by product type, material, and geography. These categories help in understanding regional market dynamics, preferences, and technological adoption levels, guiding manufacturers and investors in strategic planning and resource allocation.
- Product
- Stringers: These are long, slender components used to reinforce the aircraft fuselage, wings, and other structural parts, providing essential strength and rigidity. Rising demand for lightweight and durable aircraft is fueling stringer production and adoption worldwide.
- Frames: Frames form the structural skeleton of aircraft, supporting various components. Their demand correlates with aircraft manufacturing volume, with advanced composites driving lighter, stronger frame innovations for improved fuel efficiency.
- Brackets: Used to connect different structural elements, brackets are critical for maintaining aircraft integrity. Innovations in composite materials are increasingly used to manufacture brackets for weight reduction and enhanced performance.
- Panels: These include fuselage and wing panels, essential for masking internal components and providing aerodynamic surfaces. The market growth is driven by new aircraft programs emphasizing aerodynamic efficiency and material advancements.
- Material
- Aluminum: As a traditional material, aluminum offers a balanced mix of strength, weight, and cost-effectiveness, dominating the aerospace component manufacturing landscape due to its ease of fabrication and recyclability.
- Composites: Composites such as carbon fiber-reinforced polymers provide significant weight savings and corrosion resistance, thereby supporting the aerospace industry's shift toward more fuel-efficient aircraft requiring advanced materials.
- Steel: Steel components are used where high strength and durability are necessary, particularly in landing gear and structural support points, though their market share declines with the rise of lighter composite materials.
- Geography
- North America: The region benefits from advanced aerospace manufacturing capabilities and strong OEM demand, especially in the U.S., driven by major aircraft programs and technological innovation hubs.
- Europe: Known for its established aerospace industry, Europe, particularly countries like France, Germany, and the UK, focuses on innovative materials and sustainable manufacturing practices to meet evolving regulatory standards.
- Asia-Pacific: The fastest-growing region, with rapid industrialization, increasing aircraft production, and expanding aerospace OEMs in China, India, and Japan, fostering substantial demand for all types of aerostructure equipment.
- Rest of the World: Markets in Latin America, the Middle East, and Africa are emerging, driven by increased aircraft leasing and infrastructure development, with growing investment in local manufacturing capabilities.
Competitive Intelligence
The Aerostructure Equipment Market is characterized by intense competition among leading aerospace and defense contractors, with a high level of market concentration concentrated in key players like Boeing, Airbus, GE Aviation, and Triumph Group. These companies adopt aggressive business strategies that include extensive R&D investments to innovate lightweight, durable, and efficient aerostructure components, which serve as differentiators in a competitive landscape. Strategic partnerships and collaborations are common, aimed at technology sharing, joint ventures, and expanding production capacities to meet rising demand in emerging markets. Acquisitions further reinforce market positioning by acquiring specialized startups and niche suppliers with advanced technological capabilities. Expansion strategies focus on entering new geographic markets particularly Asia-Pacific and the Middle East and diversifying product portfolios to include composites and advanced alloys. Continuous innovation through R&D enables companies to develop next-generation aerostructures that improve fuel efficiency and reduce maintenance costs, thus creating a competitive edge. Overall, the industry’s growth is driven by a strategic focus on technological advancement, market expansion, and enhanced operational efficiencies.
Leading Company Profiles
The global aerostructure equipment market features a competitive landscape comprising several key players that drive innovation, expand capacity, and develop advanced manufacturing technologies to cater to the growing aerospace industry. These companies focus on high-quality, lightweight, and durable components, reinforcing their market positions through strategic investments and collaborations.
- Honeywell International Inc.
- Spirit AeroSystems
- Safran Aircraft Engines
- Hexcel Corporation
- GKN Aerospace
- Curtiss-Wright Corporation
- Bombardier Inc.
- Messier-Bugatti-Dowty (Safran Group)
- Collins Aerospace
Honeywell International Inc.
Honeywell International Inc. specializes in advanced aerospace components, including aero engine systems and actuation solutions, leveraging innovative technology and digital transformation strategies to enhance performance and reliability in the aerostructure equipment market.
Spirit AeroSystems
Spirit AeroSystems designs and produces aerostructures with a focus on large commercial and military aircraft, emphasizing lightweight composite materials and streamlined manufacturing processes to strengthen its global market stance and technological capabilities.
Aerocomposites Inc. provides extensive composite material solutions for aerostructure applications, emphasizing innovation in lightweight composites that improve fuel efficiency and meet stringent safety standards across commercial and defense sectors.
Safran Aircraft Engines
Safran Group’s aircraft engine division offers reliable propulsion systems and structural components, emphasizing increased efficiency and heightened durability, with ongoing investments in additive manufacturing and digital design techniques to enhance component performance.
Hexcel Corporation
Hexcel specializes in advanced structural materials, including carbon fibers and honeycomb composites, with strategic R&D investments aimed at developing lighter, stronger materials that support environmentally sustainable aerospace solutions.
GKN Aerospace
GKN Aerospace develops aerostructures and engine components, leveraging a history of technological innovation, strategic collaborations, and capacity expansions to maintain leadership in lightweight aircraft structures and fuel efficiency.
Curtiss-Wright Corporation
Curtiss-Wright provides high-performance aerostructure components, with a focus on rugged, precision-engineered parts for military and commercial aircraft, emphasizing digital manufacturing and integrated supply chain solutions.
Bombardier Inc.
Bombardier’s aerospace division produces advanced structural components for regional aircraft, with a comprehensive approach to sustainability, digital transformation, and strategic acquisitions to expand its aerostructure capabilities.
Messier-Bugatti-Dowty (Safran Group)
Specializing in landing gear and structural systems, Safran's Messier-Bugatti-Dowty innovates in lightweight, durable aerostructure components, integrating smart sensor technology and digital maintenance solutions for aircraft operators.
Collins Aerospace
Collins Aerospace develops a broad portfolio of aerostructure equipment, emphasizing integrated systems, digital design, and manufacturing excellence to support the evolving needs of commercial and military aerospace markets.
Strategic Business Developments
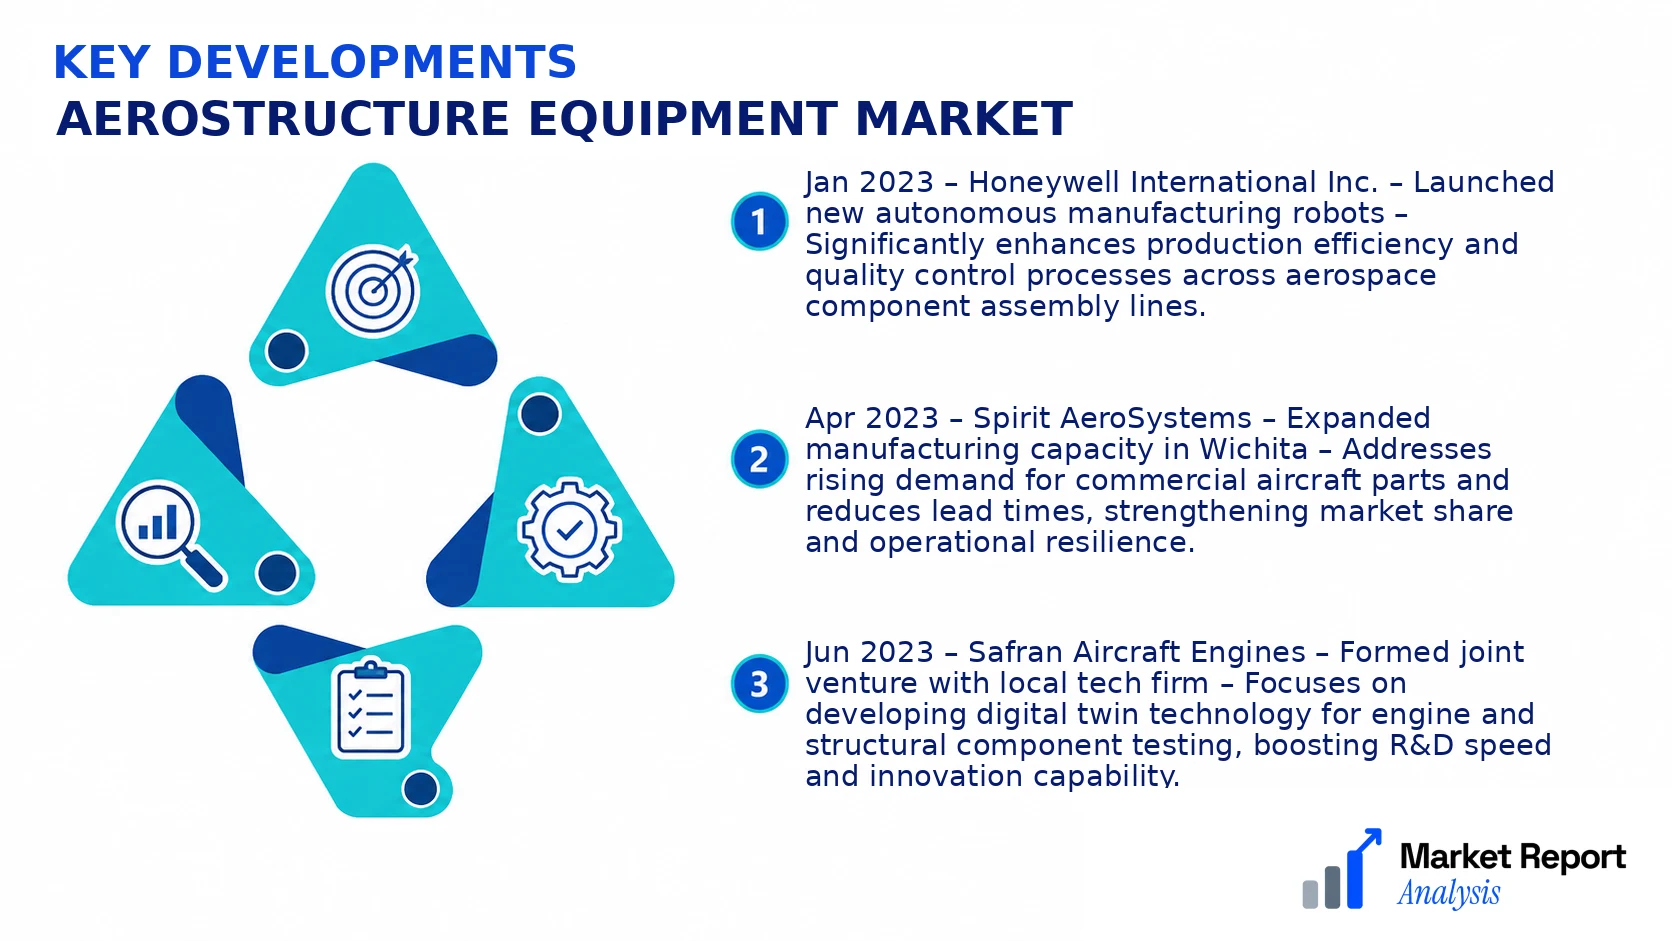
- Jan 2023 – Honeywell International Inc. – Launched new autonomous manufacturing robots – Significantly enhances production efficiency and quality control processes across aerospace component assembly lines.
- Apr 2023 – Spirit AeroSystems – Expanded manufacturing capacity in Wichita – Addresses rising demand for commercial aircraft parts and reduces lead times, strengthening market share and operational resilience.
- Jun 2023 – Safran Aircraft Engines – Formed joint venture with local tech firm – Focuses on developing digital twin technology for engine and structural component testing, boosting R&D speed and innovation capability.
- Aug 2023 – Hexcel Corporation – Invested in new composite materials facility – Supports development of next-generation lightweight materials, improving overall aircraft fuel economy and sustainability compliance.
- Nov 2023 – Collins Aerospace – Launched digital transformation platform – Automates and optimizes aerostructure design and manufacturing processes, reducing time-to-market and enhancing customization options.
Frequently Asked Questions
What is the Aerostructure Equipment Market?
The Aerostructure Equipment Market encompasses the global industry involved in the manufacturing and supply of components and systems used in aircraft fuselage, wings, and other structural parts. It supports aircraft assembly, maintenance, and overhaul activities, serving commercial, military, and regional aircraft sectors.
What is the current market size of Aerostructure Equipment Market?
As of 2026, the global Aerostructure Equipment Market valuation stands at approximately USD 15 Billion, reflecting steady growth driven by increasing aircraft production, technological advancements, and expanding demand across commercial and military aviation sectors worldwide.
What factors are driving the Aerostructure Equipment Market?
Key growth drivers include rising aircraft manufacturing, innovations in lightweight materials, increased defense budgets, and the push for fuel-efficient aircraft. Additionally, rapid technological advancements and the expansion of the aerospace industry in emerging economies fuel market expansion.
Which region dominates the Aerostructure Equipment Market?
North America currently leads the market, owing to its substantial aerospace manufacturing infrastructure, presence of major industry players, and high aircraft production rates. This region remains the key hub for aerostructure innovation and supply chain activities.
Which segment is expected to grow the fastest?
The composite materials segment is anticipated to exhibit the highest growth rate, driven by the aviation sector’s shift toward lightweight, durable, and fuel-efficient aircraft structures, contributing significantly to market expansion through 2034.
Who are the leading companies operating in the Aerostructure Equipment Market?
Major industry players include Airbus, Boeing, Leonardo S.p.A., Northrop Grumman, and Safran. These companies focus on innovations in aerostructure design, strategic collaborations, and expanding their manufacturing capabilities to strengthen market position.
Analyst Perspective
The aerostructure equipment market exhibits signs of maturity, driven by continuous innovations and increasing integration of composite materials, which enhance aircraft performance and fuel efficiency. Long-term growth prospects remain robust, fueled by the global expansion of commercial aircraft fleets and modernization of military aviation. Emerging regions, particularly Asia-Pacific, present lucrative opportunities due to rapid airline network expansions and government investments in defense. Technological evolution centers on lightweight, high-strength materials, automation in manufacturing processes, and advanced design techniques, all of which aim to reduce costs and improve sustainability. Investment priorities should focus on next-generation composites, additive manufacturing, and digital twin technologies to stay competitive. The industry faces moderate competitive intensity, with strong players consolidating their positions through strategic partnerships and innovation. Regional growth potential is highest in North America and Asia-Pacific, driven by existing aerospace hubs and expanding new markets. Overall, strategic foresight suggests that sustained innovation, regional diversification, and smarter manufacturing investments will be key to maintaining a competitive edge amid evolving technological and geopolitical landscapes.
