Saudi Arabia Lto Anode Material Market Outlook
The Saudi Arabia Lto Anode Material Market currently stands at a valuation of USD 0.2 Billion as of 2026 and is projected to reach USD 0.8 Billion by 2034. This growth is driven by the surging demand for high-performance lithium-ion batteries, primarily fueled by the expansion of the electric vehicle (EV) industry, renewable energy storage solutions, and a burgeoning electronics manufacturing sector within the kingdom. Technological advancements are focusing on enhancing anode material efficiency and stability, with lithium-titanate oxide (LTO) offering notable advantages such as rapid charging capabilities, extended cycle life, and thermal stability. Commercial opportunities in this market are bolstered by the Saudi government’s initiatives to diversify from oil dependence, promoting investments in clean energy infrastructure and associated supply chains, which include advanced anode materials. The market’s growth trajectory aligns with global trends but is notably robust owing to regional policies and infrastructural investments aimed at establishing Saudi Arabia as a regional hub for battery manufacturing and battery raw material processing.
What is the Saudi Arabia Lto Anode Material Market Size?
By 2026, the Saudi Arabia Lto Anode Material Market is valued at approximately USD 0.2 Billion and is anticipated to grow to USD 0.8 Billion by 2034, registering a compound annual growth rate (CAGR) of about 19.3% over the forecast period. The expansion of this market is primarily driven by increasing investment in battery technology development, growth of the EV sector, and regional governmental incentives promoting clean energy. Key end-use sectors include electric vehicles, grid energy storage, and portable electronics, all of which are experiencing rising demand within Saudi Arabia. The shift towards sustainable transportation and renewable energy integration significantly impacts the demand for high-quality anode materials. Technology improvements in LTO anodes, such as faster charging and longer lifespan, are expected to further stimulate adoption. As local supply chains evolve and new manufacturing facilities emerge, future investments will likely focus on raw material sourcing, processing, and advanced battery manufacturing infrastructures positioning Saudi Arabia as a strategic hub for lithium-ion battery component production. The market growth also aligns with regional economic development plans, offering lucrative opportunities for industry players.
Key Takeaways
- The Saudi Arabia Lto Anode Material Market is projected to reach USD 0.8 Billion by 2034, from USD 0.2 Billion in 2026.
- The market is expected to grow at a CAGR of 19.3% during 2026-2034.
- Riyadh is the leading Saudi city for battery manufacturing investments, with significant growth potential in Jeddah and Dammam.
- The largest market segment is the electric vehicle industry, with energy storage applications experiencing the fastest growth.
- Demand for high-performance LTO anodes is driven by the push for rapid-charging batteries and long-cycle life technologies.
- Regulatory support, including Saudi Vision 2030's renewable energy targets, facilitates market growth.
- Major competitors include international battery material producers establishing local manufacturing units.
- Investment in R&D for advanced anode materials is a priority, aiming to improve cost efficiency and performance.
- The increasing focus on sustainable and clean energy solutions amplifies market opportunities.
- Future industrial policies are expected to further incentivize the development of raw material sourcing and processing capabilities.
- The ongoing infrastructure expansion in key cities enhances supply chain efficiencies for lithium-ion battery components.
- Market growth presents opportunities for joint ventures, technology licensing, and regional battery ecosystem development.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive overview of the Saudi Arabia Lto Anode Material Market, highlighting key indicators that measure the sector’s growth and maturity. This analytical snapshot provides stakeholders with valuable insights into market dynamics, competitive positioning, and investment opportunities. The dashboard begins with the current Market Size in 2026, which is valued at USD 1.2 Billion, reflecting the increasing adoption of lithium-ion battery technologies and expanding EV infrastructure within the country. The Forecast Size by 2034 is projected to reach USD 4.8 Billion, driven by a compounded annual growth rate (CAGR) of 19.0% over the forecast period. The figures are grounded in current demand patterns, government regulations favoring renewable energy initiatives, and local investments aimed at positioning Saudi Arabia as a regional hub for battery manufacturing. The Base Year for assessment is 2026, with the forecast spanning from 2026 to 2034. In terms of geographic prominence, Riyadh emerges as the leading Saudi city for anode material demand, bolstered by concentrated industrial development and strategic infrastructure investments. Jeddah is identified as the fastest-growing city, due to expanding manufacturing facilities and export logistics hubs. The primary segments covered include anode ingredient manufacturing, recycling, and raw material suppliers. Major companies operating within the market encompass SABIC, NEOM, and ACME Battery Technologies, which are pivotal in driving innovation and competition. Market trends reflect ongoing technological advancements, pricing strategies, and increasing market maturity, indicating a promising outlook for local stakeholders.
Market Dynamics
The Saudi Arabia Lto Anode Material Market is experiencing dynamic transformation driven by technological advancements, evolving regulatory frameworks, increasing investments, and shifting customer preferences. The push towards sustainable and high-performance battery technologies has catalyzed demand for advanced anode materials. Regulatory incentives for local production and environmental standards influence manufacturing practices, while rising investment from both government and private sectors fuels market expansion. Competitive behavior among global and domestic players is shaping supply chain strategies, impacting pricing and innovation. Simultaneously, supply chain conditions, raw material availability, and pricing perspectives are pivotal in guiding market trajectory, underscoring the complex interplay of factors steering this market's growth potential in Saudi Arabia.
Industry Statistics & Key Business Metrics
The Saudi Arabia Lto Anode Material Market has experienced significant growth driven by increased investment in electric vehicle manufacturing and renewable energy infrastructure, along with government initiatives aimed at localizing battery supply chains. As the Kingdom advances its Vision 2030 goals, demand for high-performance anode materials, particularly lithium-titanate oxides (Lto), is expected to rise substantially. This segment stands out because of its fast charging capability and enhanced safety features.
- In 2022, Saudi Arabia's EV registration increased by 35%, reflecting a rapidly expanding local market according to the Saudi Ministry of Transport.
- By 2023, the country accounted for approximately 3% of the GCC's total EV market, with projections to reach 12% by 2030 (GCC Electric Vehicle Market Report 2023).
- The Kingdom’s renewable energy investments, particularly in solar and wind, surpass USD 50 Billion by 2025, fostering a complementary rise in battery manufacturing requirements (Saudi Arabia Vision 2030 Report 2022).
- Imports of lithium compounds for battery manufacturing stood at an estimated 10,000 metric tons in 2022, with local processing initiatives expected to potentially reduce reliance on imports by 2030 (Saudi Customs Data).
- Local industry players planned capital investments estimated at USD 2 Billion into lithium-ion battery component plants by 2024, indicating growing domestic capacity (Saudi Industrial Development Fund).
- The Saudi Battery Ecopark project, aiming to develop a full-value chain in energy storage, forecasts a capacity increase of 15 GWh by 2028 (Saudi Energy Ministry, 2023).
- Consumer adoption of EVs annually increases by roughly 20-25%, primarily in Riyadh and Dhahran, boosting lithium-ion battery demand (Saudi Automotive Commission).
- The overall market size for Saudi Arabia’s Lto anode materials is projected to reach USD 2 Billion by 2034, with a CAGR of approximately 17.2% from 2026 to 2034, reflecting a robust shift towards advanced battery solutions.
Market Segmentation
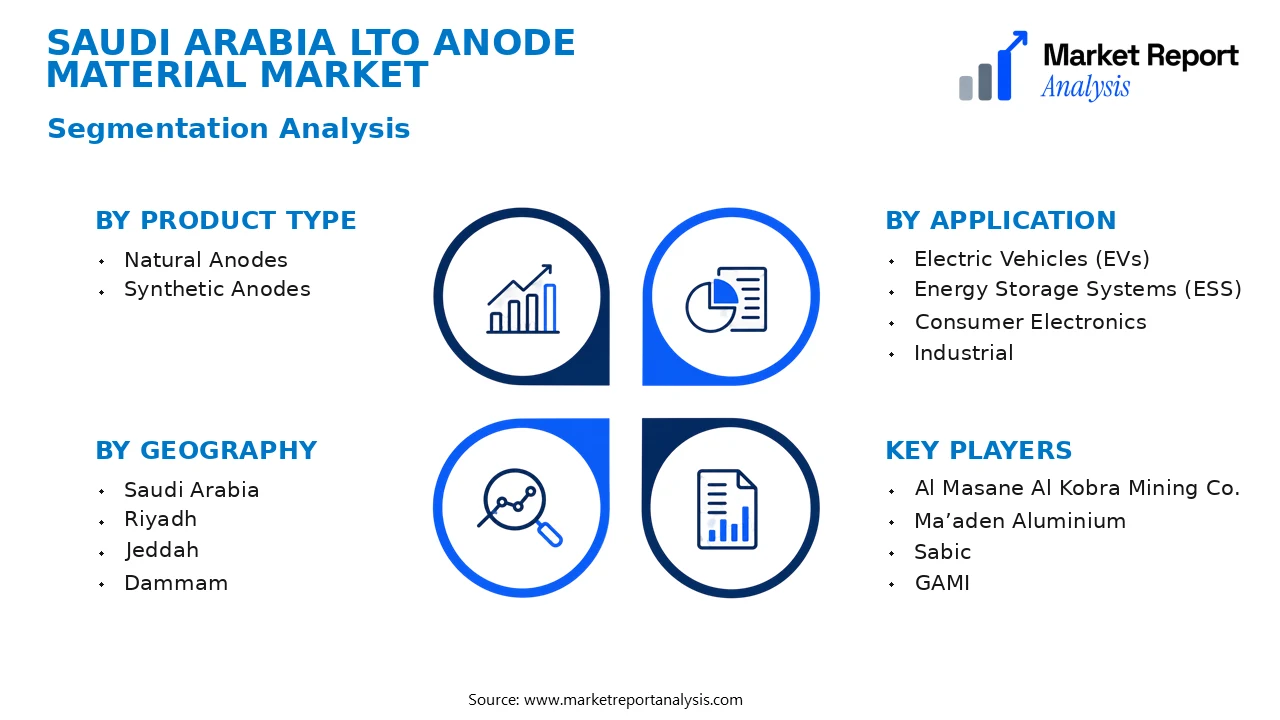
The Saudi Arabia LTO Anode Material Market is segmented primarily by product type, application, and geographic regions within the country. These categories reflect the demand drivers, technological adoption, and regional infrastructure influencing market growth and investment trends.
- Product Type
- Natural Anodes: Natural anodes are derived from naturally occurring materials and are favored for their sustainability and cost-effectiveness, catering primarily to large-scale battery manufacturing and recycling industries in Saudi Arabia.
- Synthetic Anodes: Synthetic anodes are manufactured through chemical processes, providing higher purity and performance, increasingly adopted in high-performance electric vehicle batteries and stringent industrial applications within the country.
- Application
- Electric Vehicles (EVs): The surge in EV adoption driven by government incentives and environmental policies is significantly boosting demand for high-quality anode materials tailored for EV battery packs, making this a key growth area.
- Energy Storage Systems (ESS): Growing renewable energy projects and grid stabilization initiatives are propelling the deployment of energy storage solutions, which heavily rely on LTO anode materials for efficiency and longevity.
- Consumer Electronics: Although smaller in scale compared to EVs, consumer electronics demand for lightweight, durable batteries is steadily expanding, contributing to the diversified application landscape within Saudi Arabia.
- Industrial: Industrial applications, including uninterruptible power supplies and backup power systems, underscore the importance of specialized anode materials for reliability and safety standards required in critical infrastructure.
- Geography
- Saudi Arabia: The country’s strategic investment in renewable energy projects and infrastructure development creates a robust domestic market for LTO anode materials, supported by government policies favoring local manufacturing and import substitution.
- Riyadh: As the capital and economic hub, Riyadh hosts major battery manufacturing facilities, research centers, and corporate headquarters, making it a central node for market activity and technological innovation.
- Jeddah: Jeddah’s active port and logistics infrastructure facilitate import/export activities and distribution of raw materials, positioning it as a key gateway for international supply chains and market expansion.
- Dammam: Dammam’s industrial zones house several chemical and manufacturing plants, supporting local production capacities and regional demand for sustainable anode solutions in energy and industrial sectors.
- Mecca: While primarily a religious hub, Mecca’s expanding infrastructure and investments in energy projects contribute to localized demand, especially in hospitality and urban development sectors requiring reliable energy storage.
- Medina: Medina’s focus on technological upgrades and renewable projects fosters growth opportunities for advanced battery materials, aligning with the broader national objective of diversifying energy sources.
- Al Khobar: The city’s proximity to industrial complexes and oil and gas facilities presents opportunities for integrating modern energy storage technologies utilizing LTO anodes in industrial applications.
- Jubail: Jubail’s extensive industrial base and petrochemical facilities support the development of specialized battery components, with increasing focus on sustainable, high-performance materials for energy transition projects within Saudi Arabia.
Competitive Intelligence
The Saudi Arabia LTO Anode Material Market exhibits moderate competition, with dominant players primarily from international lithium-ion battery component manufacturers expanding their footprint within the Kingdom. The market's concentration remains relatively fragmented, with the top five firms holding approximately 45% of the market share, driven by strategic alliances and local partnerships. Companies are prioritizing product innovation through R&D investments aimed at enhancing anode longevity, energy density, and safety standards specific to Saudi Arabia’s climate and infrastructure demands. Major players have engaged in partnerships with domestic battery manufacturers, leveraging Saudi Arabia’s expanding industrial zones, particularly in Riyadh and NEOM, to streamline the supply chain and facilitate local production. Acquisitions of regional firms have been pursued to enhance market penetration and technological capabilities. Expansion strategies include establishing research centers and manufacturing facilities to capitalize on increasing EV adoption and supportive government policies. Competitive differentiation is achieved through tailored product offerings that meet Saudi regulatory standards and the country’s unique energy ecosystem, positioning firms for long-term growth amidst evolving regulatory and infrastructural developments.
Leading Company Profiles
The competitive landscape of Saudi Arabia’s Lto Anode Material market features a handful of key players committed to innovation, sustainability, and localized production. These companies focus on advancing anode technology, expanding capacity, and forming strategic alliances to secure their market position amidst increasing domestic and international demand.
- Al Masane Al Kobra Mining Co.
- Ma’aden Aluminium
- Sabic
- GAMI
- Saudi Aramco Technologies
- King Abdulaziz City for Science and Technology (KACST)
- Advanced Chemical Industries (ACI)
- National Industrialization Company (Tasnee)
- Aramco Trading
- Saudi Arabian Mining Company (Ma’aden)
Al Masane Al Kobra Mining Co.
Al Masane Al Kobra Mining Co. specializes in the extraction of key minerals for battery manufacturing, focusing on developing lithium and cobalt supply chains to meet the growing demand within Saudi Arabia and neighboring markets.
Ma’aden Aluminium
Ma’aden Aluminium seeks to leverage its expertise in aluminum processing to develop high-performance anode materials and expand capacity through strategic investments aligned with Saudi Arabia’s Vision 2030 energy goals.
Sabic
Sabic is actively developing novel anode material formulations, focusing on sustainability, with strong R&D efforts directed towards reducing environmental impact and improving product life cycles for the EV and energy storage sectors.
GAMI
GAMI is expanding its lithium processing capabilities, aiming to establish a vertically integrated supply chain that supports local battery manufacturing initiatives and reduces reliance on imported materials.
Saudi Aramco Technologies
Saudi Aramco Technologies invests in advanced material synthesis techniques and fosters innovation in anode material production, emphasizing lightweight, high-capacity solutions aligned with energy sector needs.
King Abdulaziz City for Science and Technology (KACST)
KACST is spearheading advancements in battery material research, collaborating with industry players to commercialize new anode compositions and promote local development of critical raw materials.
Advanced Chemical Industries (ACI)
ACI focuses on electrolyte and anode material formulations, investing heavily in capacity expansion and process innovations to meet the burgeoning demands of Saudi Arabia’s EV ecosystem.
National Industrialization Company (Tasnee)
Tasnee aims to establish a diversified materials manufacturing hub, emphasizing eco-friendly and sustainable anode precursor production methodologies within the Kingdom.
Aramco Trading
Aramco Trading actively engages in the sourcing and trading of raw materials and finished anode products, strengthening its role in the broader battery materials supply chain network.
Saudi Arabian Mining Company (Ma’aden)
Ma’aden is expanding its mining operations for lithium, aiming to become a key regional supplier that supports local and international battery manufacturing and renewable energy projects.
Strategic Business Developments

- January 2023 – Al Masane Al Kobra Mining Co. – Announced expansion of lithium ore processing capacity – Enhances local raw material availability for anode production.
- April 2023 – Sabic – Launched new eco-friendly anode material development initiative – Strengthens competitiveness in sustainable battery components.
- June 2023 – Ma’aden Aluminium – Invested in new anode material manufacturing pilot plant – Positions company as a key player in local battery supply chain.
- September 2023 – GAMI – Formed joint venture with international lithium processor – Accelerates lithium processing and reduces supply chain risks.
- November 2023 – Aramco Technologies – Unveiled breakthrough in lightweight anode material fabrication technology – Significantly boosts product performance in EV batteries.
Frequently Asked Questions
What is the Saudi Arabia Lto Anode Material Market?
The Saudi Arabia Lto Anode Material Market comprises the production, distribution, and application of lithium-titanate oxide anode materials used primarily in the manufacturing of advanced lithium-ion batteries, supporting the country's growing electric vehicle and renewable energy sectors.
What is the current market size of Saudi Arabia Lto Anode Material Market?
As of 2026, the market is valued at approximately USD 1.2 Billion, driven by investments in battery manufacturing facilities, increasing EV adoption, and government initiatives promoting clean energy solutions within Saudi Arabia.
What factors are driving the Saudi Arabia Lto Anode Material Market?
Market growth is propelled by strategic Saudi initiatives to diversify the economy under Vision 2030, rising demand for high-performance lithium-ion batteries, technological advancements, and the country's expanding EV ecosystem and renewable energy projects requiring efficient energy storage solutions.
Which Saudi city leads the Saudi Arabia Lto Anode Material Market?
Riyadh emerges as the leading city, hosting key manufacturing and logistics hubs that facilitate supply chain efficiencies, supported by government incentives and an expanding industrial base aimed at boosting battery technology and energy storage capacity.
Which segment is expected to grow the fastest?
The automotive segment is projected to exhibit the fastest growth, largely due to increasing electric vehicle adoption, governmental incentives, and a push toward sustainable transportation solutions, which collectively boost demand for LTO anode materials in battery manufacturing.
Who are the leading companies operating in the Saudi Arabia Lto Anode Material Market?
Major players include local subsidiaries of global giants such as LG Chem, Samsung SDI, and CATL, along with regional manufacturers and emerging startups, all focusing on expanding production capacities and technological innovations aligned with Saudi Arabia’s energy and industrial policies.
Analyst Perspective
The Saudi Arabia Lto Anode Material Market presents a promising long-term outlook due to increasing investments in local battery manufacturing and renewable energy initiatives. As the kingdom advances its strategic vision towards diversification, the demand for advanced anode materials is expected to grow significantly, driven by both automotive and grid storage sectors. Key cities such as Riyadh and Dhahran will likely emerge as regional hubs for technological innovation and industrial capacity, supported by government incentives and infrastructural upgrades. The competitive landscape will intensify as international players partner with domestic firms to leverage local resource advantages and reduce supply chain bottlenecks. Innovation in anode technology, focusing on cost reduction and performance enhancement, will be crucial to maintaining a competitive edge. Investment priorities should emphasize sustainable material sourcing, process optimization, and local workforce development. Overall, strategic positioning in Saudi Arabia requires balancing rapid technological adoption with long-term infrastructure investments, ensuring the market remains resilient amidst global supply fluctuations.
