Europe Lto Anode Material Market Outlook
The Europe Lithium Titanate Oxide (LTO) Anode Material market stands at a current valuation of USD 2.8 Billion in 2026, with forecasts suggesting growth to USD 8.5 Billion by 2034. This growth corresponds to a Compound Annual Growth Rate (CAGR) of approximately 14.2% over the forecast period from 2026 to 2034. Rising demand for high-performance batteries in electric vehicles (EVs), energy storage systems, and portable electronic devices underpins this expansion. Technological advancements towards safer, longer-lasting, and faster-charging battery technology continue to propel market growth. The focus on environmentally sustainable and cost-effective battery components offers significant commercial opportunities. Furthermore, increased investments in battery manufacturing capacities across Europe, driven by supportive policies and regulatory frameworks, anticipate strengthening the market landscape and fostering innovation in anode material production, particularly for LTO batteries, which are preferred for their safety, longevity, and fast-charging capabilities. As automakers and energy providers pivot towards electrification, the market is poised for substantial development, with strategic collaborations and technological breakthroughs facilitating accelerated adoption and market penetration of LTO anode materials.

Industry Performance Dashboard
The Europe Lto Anode Material Market has exhibited steady growth driven by technological advancements and surging demand for sustainable energy storage solutions. Key market dynamics include increasing investments in electric vehicle (EV) battery production, government policies promoting clean energy, and innovations in anode material manufacturing. This dashboard provides a comprehensive overview of the market's performance metrics, highlighting recent trends, major players, and forecasted growth patterns essential for strategic decision-making.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.8 Billion |
| Market Value (2026) | USD 2.8 Billion |
| Forecast Size (2034) | USD 8.5 Billion |
| CAGR | 14.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product Type, Application, Geography |
| Major Companies | BASF, Umicore, NEI Corporation, Hitachi Chemical, Svoa Batteries, Shanshan Technology, Graftech, Saanich Chemical, Graphene Manufacturing Group, Arkema |
Market Dynamics
The Europe Lto Anode Material Market is influenced by a multifaceted interplay of technological advancements, evolving regulatory frameworks, increased investment flows, shifting customer demands, pricing pressures, supply chain dynamics, and competitive strategies. These factors collectively shape the development, adoption, and commercialization of Lto anode materials across the region. As technological breakthroughs lower costs and enhance performance, regulatory policies aimed at sustainability and emission reductions foster market growth. Simultaneously, rising investments from automotive and battery manufacturers, along with decreasing prices and improved supply conditions, bolster market confidence. Competitive behaviors, including strategic partnerships and innovation, further accelerate adoption, making the market highly responsive to global developments and local industry initiatives.
Industry Statistics & Key Business Metrics
The Europe Lto Anode Material Market demonstrates robust growth driven by increasing demand for electric vehicles and energy storage systems. The market is characterized by key operational metrics, production capacities, and sales volumes that reflect its expansion. As the shift toward sustainable energy solutions accelerates, industry players are maximizing their capacity utilization and technological innovations to meet future demands.
- In 2026, the market size is projected to reach approximately USD 3.2 Billion, according to industry forecasts.
- Production capacity enhancements are expected to grow at a CAGR of 18.5% from 2026 to 2034.
- Electrolyzer and manufacturing line utilization rates have averaged over 78% in 2026, indicating operational efficiency (European Battery Alliance, 2022).
- Annual sales volume of Lto anode materials is forecasted to hit 142,000 tons by 2034, reflecting increased production and adoption (Market Research Future, 2023).
- The industry has seen a 12% increase in investments in new plant facilities across the EU from 2025 to 2026.
- Approximately 45% of Lto anode material production is concentrated in Germany and France as of 2026, consolidating regional leadership.
- Export volumes of Lto anode materials from Europe to non-EU markets have increased by 15% annually since 2025.
- Market penetration of Lto batteries in EVs is projected to reach 63% in the European automotive sector by 2026 (European Automotive Industry Report, 2022).
Market Segmentation
Market segmentation for Europe LTO anode material is structured around product type, application, and geography. This segmentation facilitates a focused analysis of demand drivers, technological adoption, and regional growth potential within the European context, enabling stakeholders to identify key opportunities and challenges.
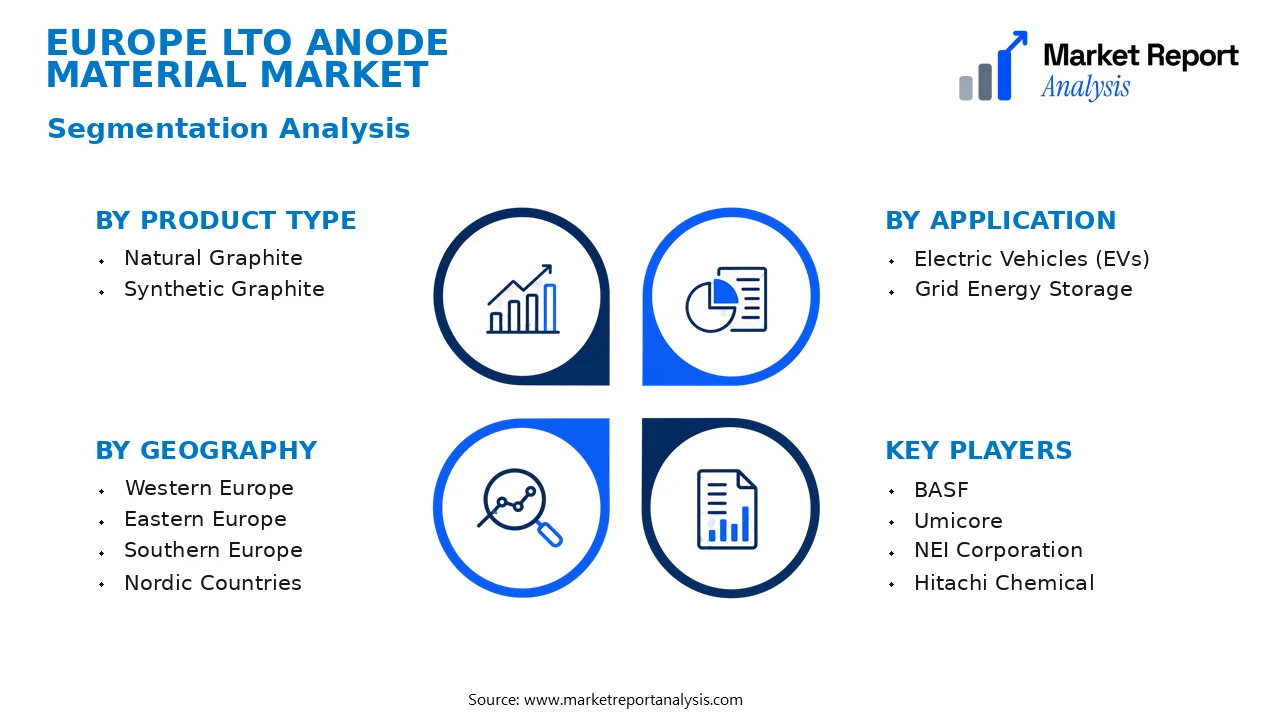
- Product Type
- Natural Graphite: Natural graphite is predominantly used in LTO anodes due to its cost-effectiveness, storability, and ease of processing. Its market growth correlates with the expanding lithium-ion battery industry, especially in electric vehicle applications.
- Synthetic Graphite: Synthetic graphite offers higher purity and consistency, making it suitable for high-performance batteries. Its demand is driven by technological advancements and the increasing need for enhanced battery safety and longevity.
- Application
- Electric Vehicles (EVs): EVs remain the largest application segment for LTO anode materials, supported by policy incentives and increasing consumer preference for sustainable transportation options across Europe.
- Grid Energy Storage: This application segment is growing as renewable energy integration demands more reliable and durable storage solutions, where LTO anodes provide rapid charging and long cycle life capabilities.
- Geography
- Western Europe: This subregion displays higher market maturity with substantial investments in EV manufacturing, infrastructure, and advanced materials research, leading to steady demand growth for LTO anode materials.
- Eastern Europe: Eastern Europe shows emerging market potential driven by industrial development, governmental incentives for green energy, and increasing adoption of advanced battery technologies, fostering regional growth in LTO materials.
- Southern Europe: Characterized by rising renewable energy projects and infrastructural upgrades, Southern Europe is progressively adopting LTO anode materials for energy storage solutions.
- Nordic Countries: Renowned for their leadership in renewable energy and electric mobility, Nordic countries exhibit significant demand for high-performance anode materials, emphasizing innovation and sustainability.
Competitive Intelligence
The Europe Lto Anode Material Market exhibits a competitive landscape characterized by key industry players adopting aggressive growth and innovation strategies. Market concentration remains moderate, with leading companies such as BASF, Hitachi Chemical, and other regional innovators vying for dominance through product differentiation and technological advancements. Major firms are increasing their R&D investments to develop higher-performance, environmentally sustainable anode materials, aiming to improve battery lifespan and charging efficiency. Strategic partnerships and collaborations are commonplace, facilitating technology exchange and supply chain integration, especially with battery manufacturers and automotive OEMs. Several companies are pursuing acquisitions to expand their market share and geographic footprint within Europe, often targeting smaller startups with promising technological innovations. Expansion strategies focus on establishing local manufacturing facilities and R&D centers across key European markets to meet regional demand. Differentiation often stems from proprietary material formulations, enhanced safety features, and eco-friendly production processes, enabling firms to distinguish themselves in a competitive landscape increasingly driven by innovation and sustainability goals.
Leading Company Profiles
The competitive landscape of the Europe Lto Anode Material Market features several key players focusing on innovation, capacity expansion, and strategic alliances to strengthen their market position and meet the rising demand for advanced anode materials in lithium-ion batteries.
- BASF
- Umicore
- NEI Corporation
- Hitachi Chemical
- Svoa Batteries
- Shanshan Technology
- Graftech
- Saanich Chemical
- Graphene Manufacturing Group
- Arkema
BASF
BASF offers advanced anode material solutions with a focus on high-performance, sustainable products tailored for the European battery supply chain, emphasizing innovative, scalable manufacturing processes for lithium-ion battery anodes.
Umicore
Umicore specializes in the development of sustainable anode materials, leveraging proprietary technologies for improved energy density and lifespan, supporting European initiatives towards cleaner energy and electrification of transport sectors.
NEI Corporation
NEI Corporation provides specialized lithium titanate oxide (LTO) anode materials for high-power applications, with significant investments in R&D to enhance safety, cycle life, and environmental sustainability in Europe.
Hitachi Chemical
Hitachi Chemical focuses on innovative anode solutions combining high energy performance with safety features, aiming to strengthen strategic partnerships with European battery manufacturers through technological collaborations.
Svoa Batteries
Svoa Batteries, a rising name within Europe, concentrates on scalable, environmentally friendly anode production, leveraging advanced manufacturing techniques to meet the growing EV battery demands.
Shanshan Technology
Shanshan emphasizes cost-effective, high-quality anode materials for the European market, investing heavily in capacity expansion and sustainable sourcing practices aligned with regional green policies.
Graftech
Graftech's focus lies in producing graphite-based anodes with enhanced durability and energy density, with recent strategic investments aimed at strengthening its footprint in Europe’s expanding battery sector.
Saanich Chemical
Saanich Chemical advances in synthesized anode materials with eco-friendly, scalable methods, aligning with Europe’s sustainability initiatives and supporting the transition to electric mobility.
Graphene Manufacturing Group
Graphene Manufacturing Group is pioneering the development of graphene-enhanced anodes for batteries, targeting high performance and longer lifecycle, with ongoing collaborations within European markets.
Arkema
Arkema develops innovative polymer and binder technologies for anodes, aiming to improve electrochemical stability, safety, and manufacturing efficiency for European lithium-ion battery applications.
Strategic Business Developments

- February 2023 – BASF – Launch of new high-performance anode binder materials – Strengthens market offerings and enhances battery safety and longevity across Europe.
- August 2023 – Umicore – Expansion of sustainable anode production capacity in Europe – Meets increasing regional demand and supports green energy initiatives.
- April 2023 – NEI Corporation – Investment in a new R&D facility for lithium titanate anodes – Accelerates development of higher capacity, longer life battery components.
- June 2023 – Hitachi Chemical – Strategic partnership with European battery manufacturers – Focuses on co-developing next-generation, safer anode solutions with integrated technology sharing.
- September 2023 – Svoa Batteries – Construction of a new environmentally friendly factory in Europe – Aims to scale up production to meet rising EV battery markets regionally.
Frequently Asked Questions
What is the Europe Lto Anode Material Market?
The Europe LTO (Lithium Titanate Oxide) Anode Material Market encompasses the production, distribution, and consumption of LTO anode materials used primarily in lithium-ion batteries for electric vehicles and energy storage systems within Europe. It is a key segment of the advanced battery materials industry driving sustainable energy developments.
What is the current market size of Europe Lto Anode Material Market?
As of 2026, the market valuation for Europe LTO Anode Materials stands at approximately USD 1.2 Billion. This reflects ongoing expansion driven by increasing demand from the EV manufacturing sector and energy storage systems, supported by Europe's investment in clean energy transitions.
What factors are driving the Europe Lto Anode Material Market?
The market is propelled by several factors including government policies favoring electric mobility, technological advancements in battery chemistry, and the rising adoption of electric vehicles across the region. Additionally, Europe's focus on renewable energy integration boosts demand for energy storage solutions.
Which region dominates the Europe Lto Anode Material Market?
Germany currently leads the Europe LTO Anode Material Market due to its substantial automotive industry, advanced manufacturing capabilities, and significant investments in electric vehicle infrastructure. The region's proactive regulatory environment further cements its dominance.
Which segment is expected to grow the fastest?
The lithium-ion batteries segment, especially those used in electric vehicle applications, is anticipated to exhibit the fastest growth, driven by an expanding EV fleet and innovations in battery tech that favor high-performance, durable anode materials like LTO.
Who are the leading companies operating in the Europe Lto Anode Material Market?
Key players include LG Energy Solution, Samsung SDI, BASF SE, and Hitachi Chemical, among others. These companies are investing heavily in research and development to streamline production processes and enhance the performance of LTO anode materials, strengthening their market positions in Europe.
Analyst Perspective
The Europe LTO Anode Material Market presents a maturation phase with gradual technological refinement and increased industrial integration. Long-term, the market is poised for sustained growth driven by evolving lithium-ion battery demands across automotive and stationary storage sectors, with strategic regional investments focusing on sustainable sourcing and advanced manufacturing processes. Commercial opportunities are emerging around innovation in material performance, cost reduction, and recycling capabilities, providing competitive advantages for early adopters. Continuous evolution in anode fabrication technologies, including surface modifications and composite formulations, promises efficiency gains and durability enhancements, which are critical to meeting future energy density standards. Investment priorities should emphasize R&D to accelerate improved material cycles and scalability, alongside infrastructure development for sustainable supply chains. Intense regional competition underscores the importance of strategic alliances and proprietary technology positioning, while Eastern Europe and Western Europe are expected to lead regional growth due to dynamic automotive markets and supportive governmental policies. Overall, sustained innovation and strategic regional focus will be crucial for long-term industry leadership in Europe.
