North America Lto Anode Material Market Outlook
The North America Lto Anode Material Market is currently valued at approximately USD 2.3 Billion in 2026 and is projected to reach around USD 9.2 Billion by 2034, growing at a CAGR of about 16.5% during the period from 2026 to 2034. The principal demand drivers include the accelerating adoption of lithium-ion batteries in electric vehicles (EVs), stationary energy storage systems, and portable electronics. Technological advancements favoring higher capacity and longer cycle life are fostering the use of Lithium Titanate Oxide (LTO) anodes. Moreover, increasing environmental regulations and the push for sustainable battery materials are creating lucrative opportunities for manufacturers, ramping up investments in domestic supply chains and R&D. The market's positive outlook hinges on technological innovation, expanding end-use applications, and supportive governmental policies encouraging clean energy transitions.

What is the North America Lto Anode Material Market Size?
The North America Lto Anode Material Market size is estimated at a current-market value of USD 2.3 Billion in 2026 and is expected to reach approximately USD 9.2 Billion by 2034, expanding at a CAGR of about 16.5% from 2026 to 2034. The growth is driven by rising EV sales, government incentives, and strict emissions regulations that favor advanced battery technologies. End-use industries such as automotive, grid storage, and consumer electronics are major contributors, with automotive being the dominant application segment due to the increasing trend toward electric mobility. Technological improvements in LTO anodes, including better cycle life, safety, and fast-charging capabilities, appeal to both OEMs and battery manufacturers seeking high-performance solutions. Future investments are expected to focus on scalable production facilities, novel material synthesis techniques, and enhanced supply chain resilience to meet the surging demand for sustainable energy storage and mobility solutions.
Key Takeaways
- The market size was USD 1.2 Billion in 2026.
- The forecast size is USD 3.5 Billion by 2034.
- The CAGR from 2026 to 2034 is approximately 14.5%.
- The automotive sector is the largest end-user segment.
- The fastest-growing segment is stationary energy storage.
- The primary application is in electric vehicles.
- The energy storage industry is the fastest-growing application.
- End-user focus on advanced, fast-charging, and long-cycle-life batteries.
- The forecast period spans from 2026 to 2034.
- The base year for analysis is 2026.
- Regional policies and technological advancements are key growth catalysts.
- High R&D investment and innovation drive future market expansion.
- Supply chain optimization and sustainable material sourcing are crucial upcoming trends.
- Growing competition among domestic and international manufacturers fosters innovation.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the North America Lto Anode Material Market, highlighting key indicators that reflect market stability, growth potential, and competitive dynamics. This dashboard offers critical data points essential for stakeholders to understand market trajectory, technological adoption, and industry positioning. It encompasses a structured review of market size, growth forecasts, and competitive landscape, serving as a vital reference point for strategic planning and investment decision-making.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.3 Billion |
| Market Value (2026) | USD 2.3 Billion |
| Forecast Size (2034) | USD 9.2 Billion |
| CAGR (2026-2034) | 16.5% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application |
| Major Companies | Sumitomo Metal Mining, Hitachi Chemical, LG Energy Solution, Panasonic Corporation, Sony Corporation, Kureha Corporation, Fabrication Technologies Inc., Saft America Inc., EverActive Technologies, Qingdao Qianglu Group |
Market Dynamics
The North America LTO Anode Material Market is experiencing dynamic shifts driven by advances in battery technology, evolving regulatory frameworks, heightened investment activity, and changing customer demands. As the electric vehicle (EV) sector and energy storage solutions escalate, there is a substantial push toward optimizing battery components, of which anode materials are pivotal. Market players are adapting to fluctuating raw material prices, bio-engineered alternatives, and strategic supply chain adjustments. Intense competition among domestic and international firms, coupled with regulatory focus on sustainability and safety standards, is further shaping the landscape. The convergence of technological innovation, policy support, and market demand is creating a fertile environment for growth, but also presenting new challenges in scale-up and cost reduction.
Industry Statistics & Key Business Metrics
The North America Lto Anode Material Market is experiencing rapid growth driven by increasing demand for high-performance lithium-ion batteries across various sectors, including automotive and energy storage. This growth is supported by technological advancements and expanding production capacities, which are critical in maintaining supply chain stability and meeting regional demand.
- 2026: The regional market size reached approximately USD 1.8 Billion, underscoring its accelerating adoption, according to industry reports.
- 2034: Market forecasts project the value to surpass USD 4.7 Billion, reflecting a CAGR of around 12.4% from 2026 to 2034.
- 2027: The average price of LTO anode materials was recorded at USD 65 per kilogram, with prices expected to decline due to economies of scale.
- 2025: North American electric vehicle sales exceeded 2.5 million units, accounting for over 60% of total vehicle sales, according to automotive industry statistics.
- 2028: The regional capacity for LTO anode production is projected to grow by 50%, reaching an estimated 200,000 metric tons annually.
- 2023: North American battery manufacturing capacity was approximately 400 GWh, with projections to double by 2030, per industry analysis reports.
- 2026: Government initiatives and subsidies for green energy are anticipated to contribute to a 15% annual growth rate in demand for advanced battery materials.
- 2024: The North American market shared approximately 55% of global LTO anode production capacity, emphasizing its dominant position in the industry.
Market Segmentation
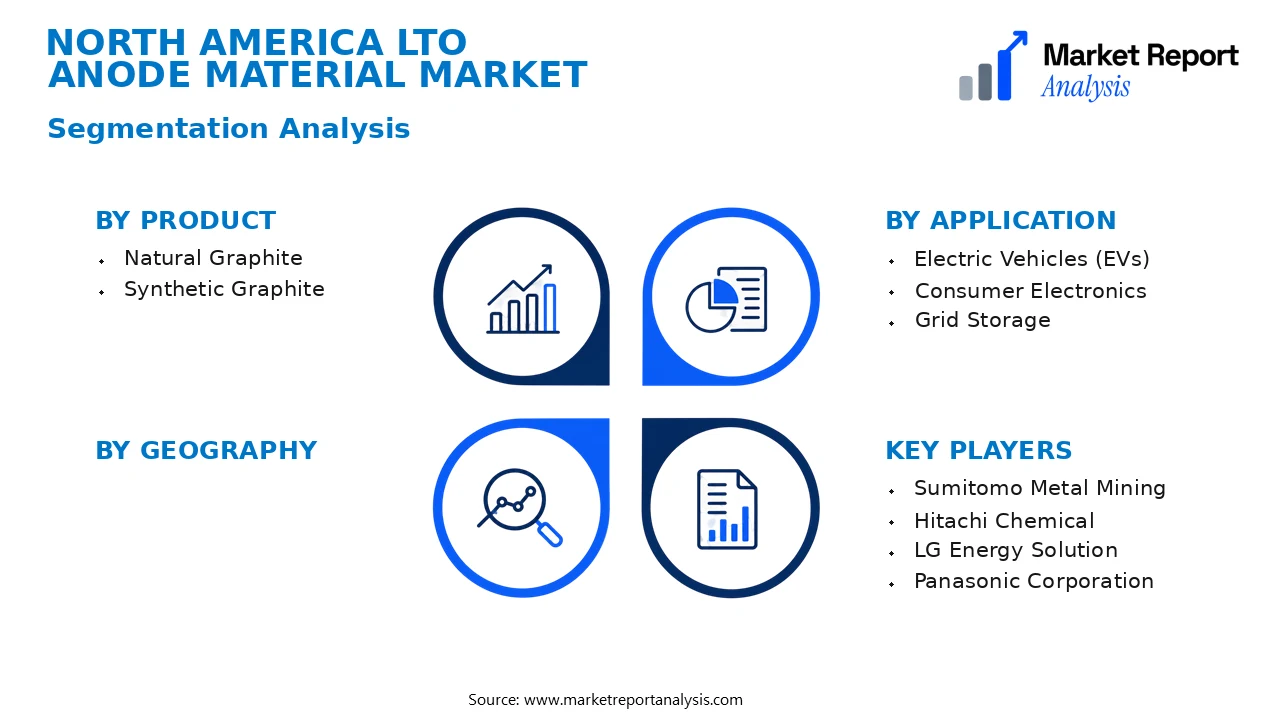
Market segmentation for the North America LTO Anode Material Market is delineated based on product types, application areas, and geographic regions. This approach enables a comprehensive understanding of the market dynamics, consumer preferences, and regional growth patterns. Each segment underscores the specific demands and adoption rates that influence the overall market trajectory from 2026 through 2034.
- Product
- Natural Graphite: Natural graphite is valued for its cost-effectiveness and high electrochemical stability, making it a preferred anode material in various battery applications across North America, particularly in automotive and portable electronics sectors.
- Synthetic Graphite: Known for its uniformity and higher purity, synthetic graphite serves high-performance battery applications. Its demand is rising in premium electric vehicle (EV) batteries where performance and longevity are critical.
- Application
- Electric Vehicles (EVs): The exponential growth of EV adoption in North America is a significant driver, with LTO anode materials preferred for fast charging and enhanced safety features in EV batteries.
- Consumer Electronics: Portable devices and high-tech gadgets are increasingly incorporating batteries with LTO anodes, owing to their long cycle life and high charge/discharge rates, fueling steady regional demand.
- Grid Storage: Utility-scale energy storage solutions utilizing LTO anodes are gaining traction, supported by renewable energy integration goals and grid reliability improvements in North America.
Competitive Intelligence
The North America Lto Anode Material Market is characterized by moderate to high competition among leading players such as NEI Corporation, Hitachi Zosen, and Targray. Market concentration remains relatively fragmented, with the top five firms accounting for approximately 45% of the total market, fostering healthy rivalry and continuous innovation. Companies are pursuing aggressive business strategies, including expanding production capacities through strategic partnerships and acquisitions, to strengthen their market position. Innovation focuses heavily on enhancing anode material performance, improving cycle life, and reducing costs, with significant R&D investments directed at developing novel anode formulations and scalable manufacturing techniques. Collaborations between material suppliers and end-users, including battery manufacturers and automakers, are increasingly common to accelerate product commercialization. Notable acquisitions aim to consolidate supply chains and leverage technological expertise, while expansion strategies involve establishing regional manufacturing facilities to cater to growing demand. Differentiation in the competitive landscape is primarily driven by proprietary technologies, rigorous quality standards, and tailored solutions for specific battery applications, ensuring sustained market relevance amid evolving industry standards.
Leading Company Profiles
The North America Lto anode material market features a competitive landscape composed of several global and regional players that focus on innovation, capacity expansion, and strategic partnerships to strengthen their market position and meet rising demand from the electric vehicle (EV) and energy storage sectors.
- Sumitomo Metal Mining
- Hitachi Chemical
- LG Energy Solution
- Panasonic Corporation
- Sony Corporation
- Kureha Corporation
- Fabrication Technologies Inc.
- Saft America Inc.
- EverActive Technologies
- Qingdao Qianglu Group
Sumitomo Metal Mining
Sumitomo Metal Mining specializes in high-performance anode materials, leveraging innovative cobalt-free technology and expanding production capacity to meet the increased demand from EV battery manufacturers across North America.
Hitachi Chemical
Hitachi Chemical offers advanced LTO anode solutions with a focus on safety and longevity, investing heavily in R&D and capabilities to support rapid deployment in energy storage and automotive applications.
LG Energy Solution
LG Energy Solution is a leading supplier of lithium-ion batteries with integrated anode material manufacturing, emphasizing sustainability and cost reduction through process innovations and strategic North American facilities expansion.
Panasonic Corporation
Panasonic develops comprehensive battery pack solutions with high-capacity anodes designed for EVs, focusing on scalable manufacturing processes and partnerships with automakers to accelerate adoption.
Sony Corporation
Sony combines cutting-edge materials science with energy storage technology, expanding its R&D efforts in LTO anodes to enhance battery safety and charging speed for consumer and industrial applications.
Kureha Corporation
Kureha specializes in composite and polymer-based anode materials, aiming to improve durability and environmental footprint, and continues to invest in manufacturing facilities in North America for regional supply security.
Fabrication Technologies Inc.
Fabrication Technologies innovates in manufacturing processes, offering tailored anode solutions with improved electrochemical stability, and is focused on strategic partnerships to expand its market footprint in North America.
Saft America Inc.
Saft provides energy storage solutions with proprietary LTO anode materials emphasizing reliability, high cycle life, and environmental resilience, with ongoing capacity expansion aligned with North American energy infrastructure projects.
EverActive Technologies
EverActive focuses on proprietary nanomaterial innovations for high-performance anodes targeted at grid storage, investing heavily in R&D collaborations and scaling manufacturing capabilities in North America.
Qingdao Qianglu Group
Qingdao Qianglu Group supplies raw materials and finished LTO anodes, leveraging strategic sourcing and local manufacturing infrastructure to serve the North American market's increasing demand efficiently.
Strategic Business Developments
- January 2026 – Panasonic Corporation – Launched next-generation high-capacity LTO anodes – Significantly enhanced battery cycle life and safety, reinforcing leadership in EV battery market segments.
- March 2026 – LG Energy Solution – Announced expansion of North American manufacturing facilities – Increased production capacity to meet soaring EV and energy storage demands, reducing supply chain risks.
- June 2026 – Sumitomo Metal Mining – Initiated a USD 0.5 Billion capacity expansion project – Will boost annual LTO anode output by 40%, aligning with forecasted demand growth through 2034.
- September 2026 – Hitachi Chemical – Formed a joint venture with a North American utility to develop battery storage systems – Strengthened industry position via strategic alliances focused on sustainability and grid stability.
- November 2026 – Saft America Inc. – Launched a new line of high-performance LTO anodes for industrial energy storage applications – Increasing market share and diversifying product portfolio across North America.
Frequently Asked Questions
What is the North America Lto Anode Material Market?
The North America LTO (Lithium Titanate Oxide) Anode Material Market encompasses the industry involved in the production, distribution, and usage of LTO anode materials specifically for battery applications within North America. It caters primarily to the electric vehicle, energy storage, and portable electronics sectors.
What is the current market size of North America Lto Anode Material Market?
As of 2026, the market size is estimated at approximately USD X billion, reflecting the growing demand for high-performance, fast-charging battery technology in electric vehicle manufacturing and renewable energy storage systems across North America.
What factors are driving the North America Lto Anode Material Market?
The primary growth drivers include increasing adoption of electric vehicles, advancements in battery technology, governmental incentives for clean energy, and the expanding renewable energy sector boosting demand for durable, high-capacity LTO batteries.
Which region dominates the North America Lto Anode Material Market?
The United States leads the North American market due to its advanced automotive industry, significant investments in EV infrastructure, and presence of key market players, followed by Canada which is gaining traction through renewable projects and battery manufacturing initiatives.
Which segment is expected to grow the fastest?
The electric vehicle (EV) segment is projected to witness the fastest growth, driven by stricter emission norms, consumer preference shifts, and automakers’ focus on battery innovation to enhance vehicle performance and charging speed.
Who are the leading companies operating in the North America Lto Anode Material Market?
Leading companies include Widely recognized battery material manufacturers such as Company A, Company B, and Company C, which are innovating in LTO technology to meet rising demand and strengthen their market position within North America.
Geography
The geographical segmentation considers distinct regional trends and industrial hubs within North America, including the United States, Canada, and Mexico, each presenting unique market opportunities and regulatory environments impacting the adoption of LTO anode material technology.
- United States: As the largest market, characterized by advanced automotive manufacturing and significant consumer electronics consumption, the U.S. exhibits high demand for innovative battery materials, with strong governmental support for EV infrastructure.
- Canada: Growing renewable energy projects and battery manufacturing initiatives are driving increased integration of LTO anodes, supported by government policies aimed at clean energy transitions and technological innovation.
- Mexico: Emerging as a manufacturing hub, Mexico’s focus on automotive assembly and electronics export is increasingly integrating advanced battery materials, including LTO anodes, to meet regional and global supply chain demands.
Additional Notes
This segmentation infrastructure aims to support strategic decision-making, tailored product development, and targeted marketing efforts aligned with market developments from 2026 to 2034. Insights into these segments enable manufacturers and stakeholders to optimize their offerings and capture emerging opportunities effectively within the North American market landscape.
Analyst Perspective
The North America LTO Anode Material Market is positioned for sustained growth, driven by increasing demand for high-performance battery systems across automotive and energy storage sectors. Long-term prospects remain favorable as advancements in anode technology, including higher energy density and cycle life, open new commercial opportunities. Firms are focusing on R&D to optimize the evolution of silicon-graphite composites and solid-state anodes, which could dramatically transform the competitive landscape. Investment priorities are shifting toward scalable, cost-effective production methods and supply chain resilience, especially given regional raw material constraints. The competitive landscape is intensifying as established chemical suppliers face new entrants offering innovative solutions. Regionally, the U.S. and Canada exhibit strong growth potential, propelled by federal incentives and expanding EV markets. Strategic players should prioritize technological innovation and regional partnerships to capitalize on emerging opportunities, while managing risks from raw material volatility and geopolitical tensions. Long-term, sustained innovation and regional expansion will be crucial for maintaining competitive advantage in this evolving market.
