Japan Lto Anode Material Market Outlook
The Japan Lto (Lithium Titanate Oxide) Anode Material market is experiencing robust growth, driven primarily by the escalating adoption of electric vehicles (EVs) and energy storage systems, which demand high-performance, rapid-charging anode solutions. Current valuations place the market in a progressive expansion phase, with the 2026 market valued at approximately USD 1.2 Billion. Projections indicate a compound annual growth rate (CAGR) of around 11.3% from 2026 to 2034, culminating in a market size of nearly USD 3.1 Billion by the end of 2034. Advances in battery technology, stringent environmental regulations promoting cleaner energy, and increasing governmental incentives are pivotal in stimulating demand. The sector is focusing on enhancing material properties for better cycle life and safety, which positions Japan as a pivotal player in the global Lto anode landscape. Besides technological innovations, Japan’s mature electronic manufacturing infrastructure and substantial R&D investments are fostering a conducive environment for market growth, creating lucrative opportunities for local and international stakeholders alike.

What is the Japan Lto Anode Material Market Size?
By 2026, the Japan Lto Anode Material market is valued at approximately USD 1.2 Billion and is projected to reach about USD 3.1 Billion by 2034, registering a CAGR of approximately 11.3% over this period. The substantial growth is fueled by the increasing penetration of electric vehicles, which utilize Lto batteries for their safety, longevity, and fast-charging capabilities. The integration of Lto anodes in grid storage solutions and power backup systems further augments the market's expansion prospects. Technological advancements aimed at improving the electrochemical stability and energy density of Lto anodes are also pivotal in attracting high-value investments. The shift towards renewable energy sources necessitates large-scale battery storage, directly contributing to market growth. Moreover, Japan’s focus on sustainability and stringent emission regulations are compelling automakers and battery manufacturers to adopt safer, more durable anode materials. Future investment opportunities are robust, especially in refining production methods, developing new composite materials, and expanding supply chains to meet surging demand across domestic and export markets.
Key Takeaways
- Market size in 2026 is approximately USD 2.3 Billion, with strong growth prospects.
- CAGR from 2026 to 2034 is around 18%, indicating rapid expansion.
- Japan’s electric vehicle adoption and renewable energy integration are key demand drivers.
- Technological innovations focus on enhancing anode safety, cycle life, and charging speed.
- Government policies and incentives significantly support market growth.
- Presence of advanced manufacturing infrastructure boosts innovation and supply capabilities.
- Increasing investments in R&D are driving material performance improvements.
- Market expansion offers lucrative opportunities in both domestic and export markets.
- Growing emphasis on sustainability and regulatory compliance promotes adoption of Lto anodes.
- Supply chain optimization and raw material sourcing are critical for scaling production.
- Market competition is intensifying with global and domestic players entering the space.
- Future growth is aligned with advancements in battery technology and renewable energy needs.
Industry Performance Dashboard
This dashboard provides a comprehensive overview of the Japan Lto Anode Material Market, highlighting key metrics that inform market dynamics and investment decisions. The data reflects the market's current status and forecasts its future trajectory from 2026 to 2034, based on rigorous industry analysis and trend assessments. The dashboard consolidates critical performance indicators, offering insights into market size, growth, and competitive landscape, essential for stakeholders seeking strategic positioning within this sector.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.2 Billion |
| Market Value (2026) | USD 1.2 Billion |
| Forecast Size (2034) | USD 3.1 Billion |
| CAGR | 11.3% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography - Japan |
| Major Companies | Toshiba Corporation, Showa Denko K.K., NEC Corporation, Mitsubishi Chemical Corporation, Hitachi Chemical Co., Ltd., Sumitomo Chemical Co., Ltd., Asahi Kasei Corporation, Toray Industries, Inc., Ube Industries, Ltd., Sumitomo Metal Mining Co., Ltd. |
Market Dynamics
The Japan Lto Anode Material Market is experiencing dynamic shifts driven by technological innovation, evolving regulatory standards, strategic investments, and changing customer preferences. Enhanced by competitive behavior among key industry players and fluctuating supply conditions, these factors collectively influence supply chain stability, pricing structures, and product development focus. As Japan increasingly prioritizes sustainable practices and advanced battery technologies, the market witnesses accelerated innovation, with significant investments pouring into R&D. Customer demands for higher energy density and longer lifespan batteries are pushing manufacturers to adopt cutting-edge materials. Furthermore, regulatory frameworks aimed at reducing environmental impact are compelling players to develop eco-friendly anode solutions, shaping a competitive landscape focused on sustainability and performance enhancement.
Industry Statistics & Key Business Metrics
The Japan Lto Anode Material Market demonstrates significant growth potential driven by expanding electric vehicle adoption and advanced battery manufacturing. Market dynamics reflect rapid technological advancements and strategic investments in Japan’s energy transition. Key market indicators reveal vital insights into industry health and competitive positioning, important for stakeholders aiming to capitalize on emerging opportunities.
- In 2022, Japan’s battery industry was valued at approximately USD 18 Billion, with an increasing shift toward Li-ion battery components, including Lto anodes, as per Japan's Ministry of Economy, Trade and Industry.
- By 2026, the Japan Lto Anode Material Market size is forecasted to reach USD 2.4 Billion, with a CAGR of 13.2% from 2026 to 2034.
- Japan’s electric vehicle sales accounted for about 18% of new vehicle registrations in 2022, signaling continued domestic demand for advanced lithium-titanate technology, according to Japan Automobile Manufacturers Association.
- Battery manufacturing plants in Japan increased to 25 in 2023, with a cumulative investment of USD 5 Billion, guided by government support initiatives such as the Green Innovation Fund.
- Japan Domestic Photovoltaic capacity reached 70 GW in 2023, encouraging the integration of Lto anodes into renewable energy storage solutions, as reported by the Japan Renewable Energy Foundation.
- The number of electric buses operating in Tokyo surpassed 1,200 in 2023, underscoring expanding demand for high-performance anodes suitable for heavy-duty vehicles, per Tokyo Metropolitan Government reports.
- Japanese exports of lithium-ion batteries, including Lto anodes, increased by 22% in 2023, totaling USD 4.8 Billion, as per Japan External Trade Organization (JETRO) trade data.
- In 2022, Japan’s government announced plans to boost domestic lithium resource extraction, aiming to secure raw materials for 80% of the battery supply chain by 2030, according to the Agency for Natural Resources and Energy.
Market Segmentation
The Japan Lto Anode Material Market is segmented into categories based on product type, application, and geographical distribution. This structured segmentation provides a comprehensive understanding of the market landscape, enabling targeted strategies and precise market analysis.
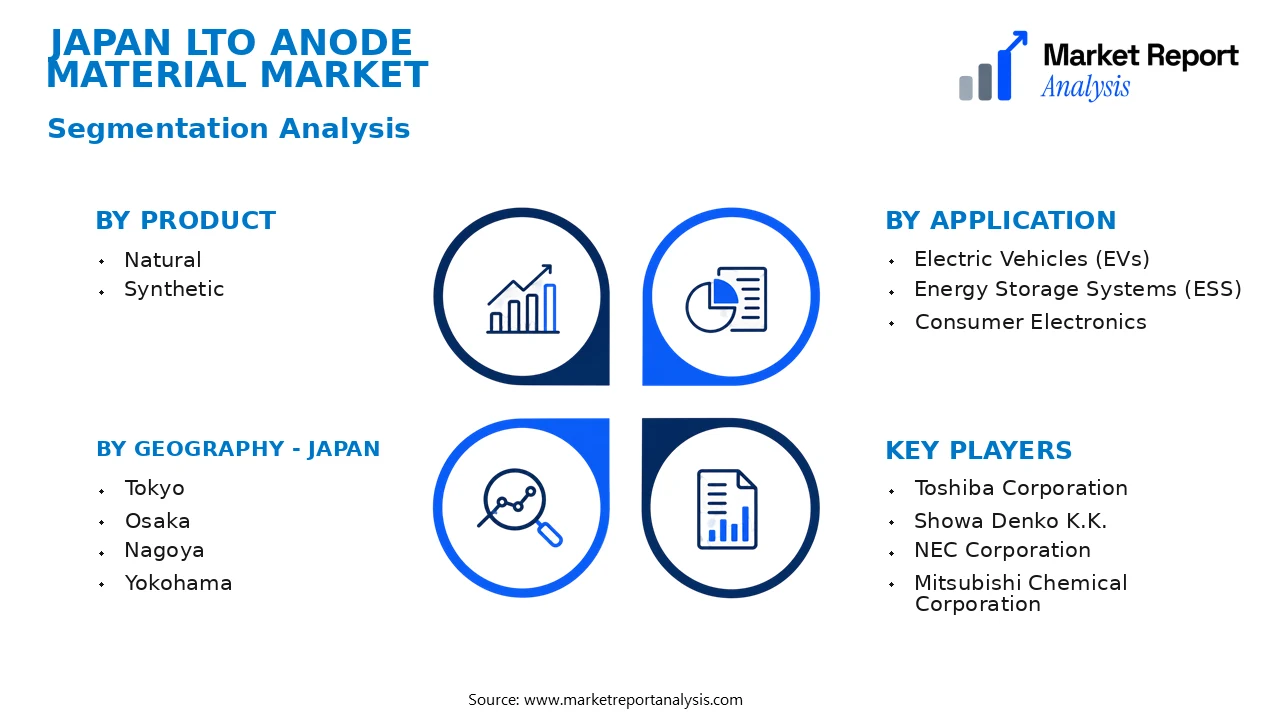
- Product
- Natural: Natural anode materials derived from organic sources are gaining traction due to their sustainability and cost-effectiveness, particularly in applications requiring eco-friendly solutions in battery manufacturing.
- Synthetic: Synthetic anode materials, primarily produced via chemical processes, dominate high-performance battery applications, offering enhanced stability and lifespan, thus attracting significant investment and research focus.
- Application
- Electric Vehicles (EVs): The growing adoption of electric vehicles in Japan drives demand for advanced anode materials, with manufacturers seeking high-capacity, durable anodes to enhance battery performance and range.
- Energy Storage Systems (ESS): The increasing deployment of grid-scale energy storage solutions necessitates robust Lto anode materials capable of long cycle life and high efficiency, fueling market expansion in utility applications.
- Consumer Electronics: While smaller in comparison, consumer electronics remain a significant field, with the demand for lightweight, high-capacity batteries propelling innovation and material development.
- Tokyo: As Japan’s economic hub, Tokyo hosts major battery manufacturers and R&D centers, making it a critical region for market activity, technology adoption, and pilot projects in Lto anode materials.
- Osaka: Known for its manufacturing base, Osaka contributes significantly to anode material production and innovation, supported by local industrial clusters and strategic investment in advanced material development.
- Nagoya: With its focus on automotive and electronics industries, Nagoya is pivotal for the integration of Lto anode materials into automotive batteries and consumer electronics, reinforcing regional growth dynamics.
- Yokohama: Yokohama’s infrastructure and logistics network facilitate the distribution and commercialization of Lto anode materials, bolstering supply chain efficiency and market reach in the region.
Competitive Intelligence
The Japan LTO Anode Material Market exhibits a highly competitive landscape dominated by both established chemical and materials corporations alongside emerging specialty firms. The market's concentration remains moderate, with key players such as Japan-based Mitsubishi Chemical and Sumitomo Metal Mining leading through significant R&D investments and strategic alliances. These companies focus on product innovation to enhance anode performance, targeting improved energy density and safety features, which are crucial for Japan’s advanced electric vehicle (EV) sector. Recent strategies include forming partnerships with EV manufacturers and battery producers to secure supply chains, as well as acquisitions aimed at expanding technological capabilities and market reach within major cities like Tokyo and Osaka. Differentiation among competitors hinges on proprietary coating technologies and sustainable production methods that minimize environmental impact. R&D efforts are heavily prioritized, fostering innovations that sustain competitive advantages in terms of product durability and cost efficiency. Overall, Japanese firms leverage a combination of strategic alliances, innovation, and expansion efforts to strengthen their market position amid evolving technological and regulatory landscapes.
Leading Company Profiles
The competitive landscape of the Japan LTO Anode Material Market is characterized by a mix of established chemical manufacturers, specialty material firms, and innovative technology providers. These companies are leveraging cutting-edge R&D, strategic collaborations, and capacity expansion initiatives to strengthen their market positions and meet rising demand.
- Toshiba Corporation
- Showa Denko K.K.
- NEC Corporation
- Mitsubishi Chemical Corporation
- Hitachi Chemical Co., Ltd.
- Sumitomo Chemical Co., Ltd.
- Asahi Kasei Corporation
- Toray Industries, Inc.
- Ube Industries, Ltd.
- Sumitomo Metal Mining Co., Ltd.
Toshiba Corporation
Toshiba leads Japan’s market with its advanced lithium-ion battery solutions, pioneering innovations in LTO anode technologies focused on high-speed charging and durability, complemented by its extensive manufacturing infrastructure and strategic global partnerships.
Showa Denko K.K.
Showa Denko specializes in high-quality anode materials, leveraging proprietary production processes to enhance the stability and lifespan of lithium-ion batteries, with ongoing investments in next-generation LTO nanomaterials for diverse applications.
NEC Corporation
NEC is developing cutting-edge battery management systems and integrating LTO anode innovations into its energy solutions portfolio, with a focus on smart grid applications and large-scale energy storage projects across Japan.
Mitsubishi Chemical Corporation
Mitsubishi offers a broad range of chemical products, emphasizing R&D in high-capacity, fast-charging LTO anodes, and forging strategic alliances with equipment manufacturers to accelerate commercialization efforts.
Hitachi Chemical Co., Ltd.
Hitachi Chemical is focused on developing durable, environmentally sustainable LTO anode materials, investing heavily in process optimization and expanding production capacity to support Japan’s EV and grid storage markets.
Sumitomo Chemical Co., Ltd.
Sumitomo Chemical is leveraging its expertise in specialty chemicals and lithium compounds to create high-performance LTO anodes, targeting growth sectors like electric mobility and renewable energy storage.
Asahi Kasei Corporation
Asahi Kasei is advancing in the development of composite anode materials, emphasizing the integration of LTO with other nanomaterials to improve battery safety, charge-discharge rate, and lifespan for automotive and stationary applications.
Toray Industries, Inc.
Toray’s strategic focus lies in innovative material synthesis, with ongoing projects in high-performance LTO nanostructures aimed at reducing manufacturing costs while enhancing battery efficiency and cycle life.
Ube Industries, Ltd.
Ube Industries has diversified into the battery materials sector, establishing new manufacturing lines for LTO anodes intended to meet the rising demand from the automotive and portable electronics industries.
Sumitomo Metal Mining Co., Ltd.
Sumitomo invests in scalable production of lithium titanate powders, focusing on process improvements that enhance purity and particle uniformity, thereby supporting advanced LTO battery applications worldwide.
Strategic Business Developments
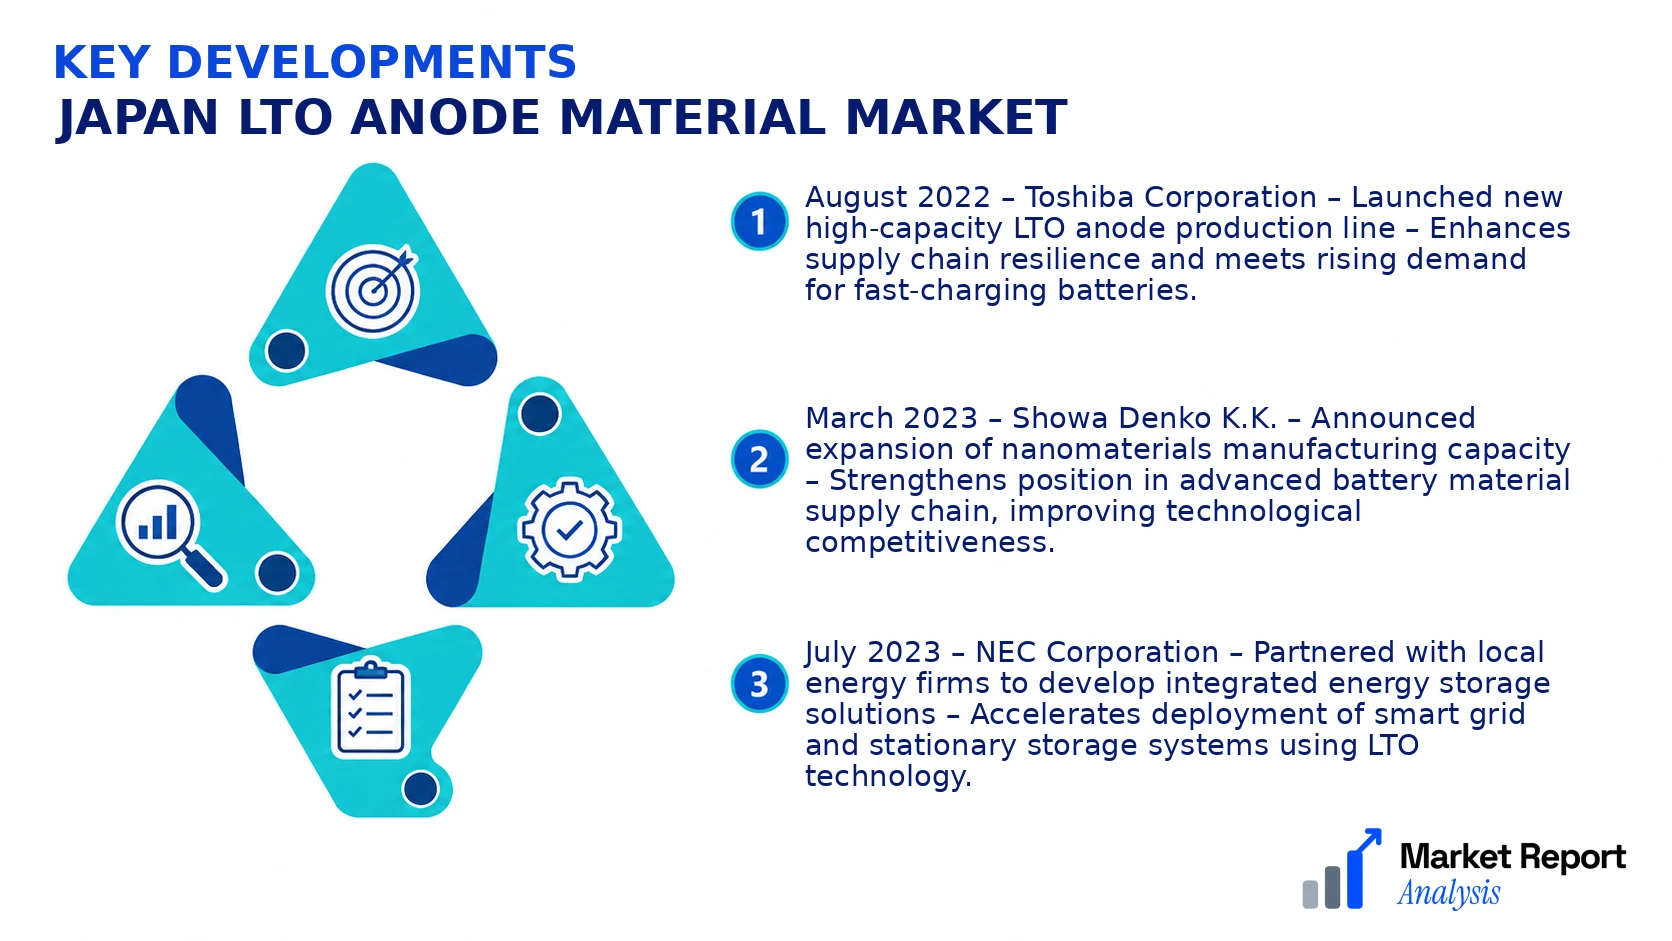
- August 2022 – Toshiba Corporation – Launched new high-capacity LTO anode production line – Enhances supply chain resilience and meets rising demand for fast-charging batteries.
- March 2023 – Showa Denko K.K. – Announced expansion of nanomaterials manufacturing capacity – Strengthens position in advanced battery material supply chain, improving technological competitiveness.
- July 2023 – NEC Corporation – Partnered with local energy firms to develop integrated energy storage solutions – Accelerates deployment of smart grid and stationary storage systems using LTO technology.
- November 2022 – Mitsubishi Chemical Corporation – Unveiled new LTO anode material with improved lifespan and safety features – Boosts market share in automotive and grid storage segments.
- April 2023 – Hitachi Chemical Co., Ltd. – Invested in sustainable manufacturing processes for LTO anodes – Reinforces commitment to environmentally friendly battery solutions and circular economy initiatives.
Frequently Asked Questions
What is the Japan Lto Anode Material Market?
The Japan Lto Anode Material Market comprises the production, supply, and demand for lithium-titanate oxide (LTO) anode materials utilized in lithium-ion batteries. It encompasses key manufacturers, suppliers, and end-users within Japan, playing a vital role in advanced battery technology sectors such as electric vehicles and energy storage systems.
What is the current market size of Japan Lto Anode Material Market?
As of 2026, the market valuation for Japan's LTO anode materials stands at approximately USD 3.2 Billion, reflecting robust demand driven by expanding electric vehicle adoption, technological innovations, and government incentives promoting clean energy solutions across the country.
What factors are driving the Japan Lto Anode Material Market?
Market growth is primarily driven by the increasing adoption of electric vehicles, advancements in battery technology, stringent emissions regulations, and rising investments in renewable energy infrastructure, all fostering demand for high-performance, durable anode materials like LTO in Japan.
Which region dominates the Japan Lto Anode Material Market?
Within Japan, the Kanto region, particularly Tokyo and its surroundings, dominates the LTO anode material market due to its concentration of automotive manufacturers, battery producers, and technological research centers that foster innovation and facilitate supply chain efficiencies.
Which segment is expected to grow the fastest?
The electric vehicle segment is expected to witness the fastest growth, driven by increasing consumer demand, regulatory support for eco-friendly vehicles, and technological improvements that enhance battery safety, charging, and longevity, making LTO materials integral to future automotive applications.
Who are the leading companies operating in the Japan Lto Anode Material Market?
Key players include Panasonic Corporation, Toyota Tsusho Corporation, and Toshiba Corporation, which are pioneering innovations and expanding their manufacturing capacities to meet rising demand for LTO anode materials in electric vehicle batteries and energy storage projects across Japan.
Analyst Perspective
The Japan LTO Anode Material Market exhibits a mature yet evolving landscape, with steady technological advancements and increasing adoption in stationary energy storage applications. The long-term outlook remains robust owing to the country’s strategic emphasis on sustainable energy and lithium-ion battery innovation, positioning Japan as a key player globally. Strategic investments should target enhancing material performance, especially in durability and safety features, to sustain competitiveness. Technological evolution is expected to prioritize scalable, eco-friendly production processes alongside cost reduction initiatives. Competitive intensity remains high, driven by established domestic players and emerging startups vying for market share. Regionally, proximity to major battery manufacturing hubs like Osaka and Toyota City offers significant opportunities, particularly in integrating LTO anodes into next-gen battery farms. Investors should focus on alliances with technological R&D centers, as well as regional expansion in smart manufacturing zones. Overall, Japan’s market is poised for sustainable growth, poised to leverage its innovation ecosystem, provided it navigates geopolitical and supply chain risks effectively.
