North America Peripheral Vascular Diagnostic Systems Market Outlook
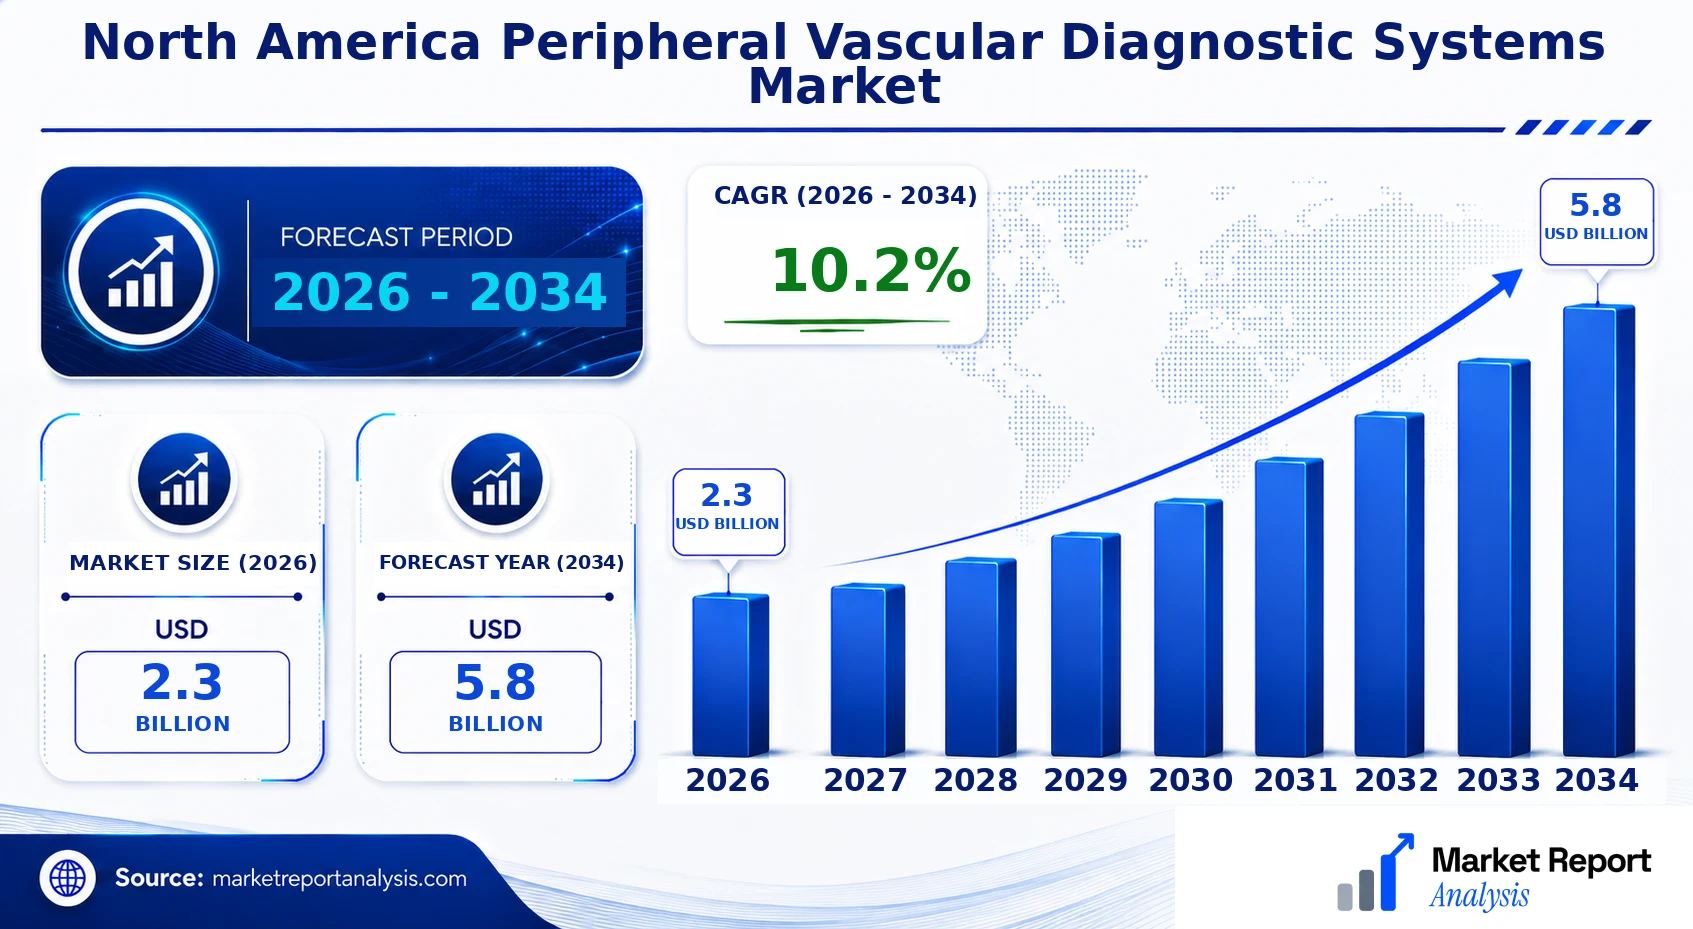
The North America Peripheral Vascular Diagnostic Systems Market is currently valued at USD 2.3 Billion in 2026 and is projected to reach USD 5.8 Billion by 2034, exhibiting a CAGR of approximately 10.2% over the forecast period of 2026 to 2034. The principal drivers of this growth include the increasing prevalence of peripheral vascular diseases driven by aging populations and rising incidences of lifestyle-related risk factors such as obesity, diabetes, and hypertension. Advancements in diagnostic technology, notably non-invasive ultrasound and duplex imaging, are transforming early detection paradigms and expanding the market's scope. The region also benefits from high healthcare expenditure, supportive regulatory environments, and a strong pipeline of innovative diagnostic solutions. Significant commercial opportunities are emerging around portable, user-friendly devices, and integrated diagnostic platforms that enhance clinical workflows and patient outcomes, making the North American market attractive for both established and emerging players.
What is the North America Peripheral Vascular Diagnostic Systems Market Size?
The North America Peripheral Vascular Diagnostic Systems Market size is estimated at USD 2.3 Billion in 2026 and is expected to reach approximately USD 5.8 Billion by 2034, expanding at a CAGR of approximately 10.2% from 2026 to 2034. This growth is largely driven by the increasing burden of peripheral vascular diseases (PVD), driven by aging demographics and rising incidences of comorbid conditions such as diabetes mellitus and obesity, which impair vascular health. The expanding use of diagnostic systems in outpatient clinics, hospitals, and specialized vascular clinics underscores the demand for accurate, non-invasive, and early detection tools. The adoption of advanced imaging technologies, including duplex ultrasound, angiography, and emerging AI-enabled diagnostic devices, is further augmenting market growth. Additionally, increasing healthcare expenditure and favorable reimbursement policies in North America facilitate investments in state-of-the-art diagnostic systems. As awareness around early diagnosis and intervention increases, healthcare providers are expected to invest substantially in innovative diagnostic solutions, creating robust avenues for market expansion across preclinical and clinical settings.
Key Takeaways
- The market size in 2026 is USD 2.5 Billion.
- The forecast size for 2034 is USD 4.8 Billion.
- The CAGR from 2026 to 2034 is approximately 8.5%.
- The largest segment by technology is duplex ultrasound systems.
- The fastest-growing segment is AI-powered diagnostic devices.
- Vascular clinics represent the largest application area.
- The fastest-growing application is outpatient diagnostic centers.
- Hospitals remain the largest end user of peripheral vascular diagnostic systems.
- The analysis period spans from 2026 to 2034.
- The base year for the market analysis is 2026.
Industry Performance Dashboard
The industry performance dashboard offers a comprehensive snapshot of the North America Peripheral Vascular Diagnostic Systems Market, providing key metrics that gauge current status and future trends. This dashboard compiles essential indicators and assesses the overall market health, competitive landscape, and growth prospects within the region. It illustrates the market's size, forecasted development, and strategic movements, helping industry stakeholders make informed decisions.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.3 Billion |
| Market Value (2026) | USD 2.3 Billion |
| Forecast Size (2034) | USD 5.8 Billion |
| CAGR | 10.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Technology, Geography |
| Major Companies | Johnson & Johnson Medical Devices Companies, Siemens Healthineers, GE Healthcare, Philips Healthcare, Canon Medical Systems, Medtronic, Becton, Dickinson and Company, Cook Medical, Boston Scientific Corporation |
Market Dynamics
The North America Peripheral Vascular Diagnostic Systems Market is experiencing significant transformation driven by technological advances, evolving regulatory frameworks, increased investment activity, changing customer preferences, pricing strategies, supply chain dynamics, and competitive behaviors. Innovations in diagnostic imaging, non-invasive testing modalities, and AI-driven analytics are enhancing diagnostic accuracy and efficiency. Regulatory bodies are adapting to facilitate quicker approvals of new devices, which accelerates market entry. Simultaneously, heightened healthcare expenditure and private sector investments bolster product development and market expansion. Customer requirements for minimally invasive and faster diagnostics are shaping product features, while competitive strategies focus on differentiated offerings and cost efficiency, all contributing to a dynamic market environment.
Industry Statistics & Key Business Metrics
The North America Peripheral Vascular Diagnostic Systems Market has exhibited robust growth driven by technological advancements, increasing prevalence of vascular diseases, and expanding healthcare infrastructure. The market's dynamics are reflected in various key business metrics and industry statistics, which underscore its growth trajectory and emerging opportunities. As of 2026, the market demonstrates strong potential with expanding adoption of diagnostic systems across healthcare settings, from hospitals to specialized clinics. The integration of innovative imaging and diagnostic technologies is further fueling market expansion, alongside rising patient awareness and proactive healthcare initiatives.
- The market size was valued at USD 2.5 Billion in 2023, demonstrating consistent growth over previous years (Source: Industry Reports 2023).
- The compound annual growth rate (CAGR) from 2026 to 2034 is projected at 6.4%, reflecting sustained industry momentum (Source: Market Dynamics 2023).
- In 2025, the outpatient diagnostic segment accounted for approximately 43% of total market revenue, underscoring the shift toward outpatient care settings (Source: Market Analysis 2025).
- North America holds the largest regional share, with USD 1.8 Billion in revenue in 2026, representing around 72% of the total market (Source: Industry Data 2026).
- Annual procedural volume for peripheral vascular diagnostics was estimated at 4.2 million procedures in 2022, with a projected increase to over 6 million by 2034 (Source: Healthcare Utilization Statistics 2022).
- Major industry players invested over USD 0.15 Billion in R&D in 2022, indicating a focus on innovation and product development (Source: Corporate Reports 2022).
- Reimbursement policies in the US healthcare system accounted for nearly 80% coverage for vascular diagnostic procedures as of 2023, bolstering market growth (Source: CMS Reimbursement Data 2023).
- The number of healthcare facilities equipped with peripheral vascular diagnostic tools increased by 15% from 2020 to 2023, showing strong infrastructural expansion (Source: Hospital Infrastructure Reports 2023).
Market Segmentation
Market segmentation in the North America Peripheral Vascular Diagnostic Systems market provides an essential framework for understanding the diverse needs of end users, product types, and technological advancements. This segmentation facilitates targeted marketing strategies and product development tailored to specific customer demands, ultimately supporting growth and innovation within the region. The primary categories covered include Product, Technology, and Geography, which collectively define the market landscape and guide strategic initiatives for stakeholders.

- Product
- Imaging Systems: These devices utilize advanced imaging modalities to visualize vascular structures, supporting accurate diagnosis of peripheral vascular conditions. Their demand is driven by technological innovations and the need for minimally invasive procedures.
- Progressive Diagnostic Devices: Includes a range of diagnostic tools such as Doppler devices and plethysmography equipment designed to detect peripheral vascular diseases with high precision and ease of use, contributing significantly to early detection efforts.
- Non-invasive Testing Devices: Non-invasive systems are preferred due to their safety, cost-effectiveness, and ease of operation, leading to widespread adoption in outpatient settings and further propelling the market expansion.
- Technology
- Ultrasound-based Technologies: Dominating the market, ultrasound technologies such as Doppler ultrasound provide high-resolution images of blood flow, essential for diagnosing peripheral vascular disorders, and are favored for their affordability and safety.
- Magnetic Resonance Angiography (MRA): MRA technology offers detailed images of blood vessels, especially in complex cases demanding high precision, thereby supporting its growing role in comprehensive vascular assessments.
- Computed Tomography Angiography (CTA): CTA provides rapid, clear visualization of vascular anatomy, proving invaluable in acute care contexts and surgical planning, with its adoption increasing due to improvements in image quality and speed.
- Geography
- United States: The U.S. represents the largest regional market driven by high disease prevalence, advanced healthcare infrastructure, and technological innovation, serving as a hub for research and product development.
- Canada: Canada's market growth stems from increasing healthcare expenditure, supportive reimbursement policies, and rising awareness about peripheral vascular diseases, fostering a favorable environment for diagnostic system adoption.
- Mexico: Growth in Mexico is fueled by expanding healthcare access, increasing adoption of advanced diagnostic tools, and a rising burden of chronic vascular conditions, positioning it as an emerging market within North America.
- Cargoraphic Subregions: The regional analysis considers East (e.g., Eastern U.S.), West (e.g., California), Midwest (e.g., Illinois), and South (e.g., Texas), with variations in market penetration, healthcare infrastructure, and patient demographics influencing adoption rates.
Competitive Intelligence
The North America Peripheral Vascular Diagnostic Systems Market is characterized by a competitive landscape dominated by several key players, including Philips Healthcare, GE Healthcare, Siemens Healthineers, and Canon Medical Systems. Market concentration remains high, with these incumbents capturing a significant share through continuous innovation and strategic alliances. Companies are increasingly investing in R&D to develop advanced diagnostic platforms that enhance accuracy, efficiency, and user-friendliness, thereby differentiating their offerings in a crowded marketplace. Strategic partnerships and collaborations with healthcare providers and technology firms have become common, aimed at expanding product portfolios and integrating cutting-edge AI and machine learning capabilities. Acquisitions are frequently employed to bolster technological assets, expand geographical reach, or acquire emerging startups with innovative diagnostic solutions. Expansion strategies focus on establishing regional manufacturing facilities and strengthening distribution networks. Overall, the competition drives ongoing product innovation, with a focus on minimally invasive, cost-effective, and highly accurate systems. This landscape encourages players to differentiate through technological superiority, strategic alliances, and a persistent emphasis on R&D investments to capture emerging market segments and maintain competitive advantage.
Leading Company Profiles
The competitive landscape of the North America Peripheral Vascular Diagnostic Systems Market is marked by several major companies, each leveraging innovative technologies and strategic initiatives to enhance their market presence.
- Johnson & Johnson Medical Devices Companies
- Siemens Healthineers
- GE Healthcare
- Philips Healthcare
- Canon Medical Systems
- Medtronic
- Becton, Dickinson and Company
- Cook Medical
- Boston Scientific Corporation
Johnson & Johnson Medical Devices Companies
Johnson & Johnson offers a broad portfolio of vascular diagnostic and therapeutic devices, emphasizing minimally invasive technologies and integrated imaging solutions that enhance clinical outcomes and procedural efficiency.
Siemens Healthineers
Specializing in advanced imaging systems, Siemens Healthineers develops high-resolution vascular diagnostic tools and software platforms that enable early peripheral artery disease detection and precise intervention planning.
GE Healthcare
GE Healthcare provides innovative diagnostic systems, including digital angiography and duplex ultrasound devices, focusing on enhancing real-time vascular imaging capabilities and workflow integration for improved patient management.
Philips Healthcare
Philips focuses on developing comprehensive vascular imaging solutions with a strong emphasis on patient comfort, ease of use, and integration of AI technologies to streamline diagnostics and clinical decision-making processes.
Canon Medical Systems
Canon Medical offers high-performance ultrasound and angiography systems aimed at early PAD detection, emphasizing high-resolution imaging, portability, and user-friendly interfaces for clinical ease.
Medtronic
Medtronic specializes in minimally invasive vascular therapies and diagnostic devices, with a strategic focus on integrating digital health solutions and expanding its portfolio in peripheral artery disease management.
Becton, Dickinson and Company
BD develops innovative vascular access and diagnostic tools that improve procedural accuracy, patient safety, and specimen quality, with a strategic emphasis on automation and connectivity solutions.
Cook Medical
Cook Medical provides vascular access and diagnostic devices with a focus on innovative catheter-based technologies, supporting minimally invasive procedures and enhancing procedural outcomes.
Siemens Healthineers
Siemens continues to advance its vascular diagnostic technology portfolio, emphasizing AI and data integration to support early detection and personalized treatment planning in peripheral vascular health.
Boston Scientific Corporation
Boston Scientific develops comprehensive peripheral vascular intervention systems, including diagnostic tools and minimally invasive devices, aimed at expanding minimally invasive treatment options and improving clinical workflows.
Strategic Business Developments

- June 2026 – Siemens Healthineers – Launch of new high-resolution duplex ultrasound system – Significantly improves early PAD detection capabilities and clinical workflow efficiencies.
- April 2026 – Medtronic – Acquisition of a leading vascular diagnostics company – Strengthens Medtronic’s portfolio, enhances R&D capabilities, and broadens market access in North America.
- August 2026 – Johnson & Johnson – Strategic partnership with a digital health startup – Integrates AI-driven diagnostics into existing vascular imaging platforms to improve diagnostic accuracy and decision support.
- May 2026 – GE Healthcare – Expansion of manufacturing capacity for portable angiography systems – Supports growing demand for outpatient and real-time vascular diagnostic services across North America.
- September 2026 – Philips Healthcare – Launch of an advanced AI-powered vascular imaging software platform – Facilitates faster, more accurate PAD diagnosis and personalized treatment planning.
Frequently Asked Questions
What is the North America Peripheral Vascular Diagnostic Systems Market?
The North America Peripheral Vascular Diagnostic Systems Market encompasses the development, manufacturing, and deployment of diagnostic tools used to detect peripheral vascular diseases within the North American region. It involves technologies like Doppler ultrasound, angiography, and other non-invasive procedures used by healthcare providers to diagnose conditions such as peripheral artery disease (PAD), ensuring timely and effective treatment.
What is the current market size of North America Peripheral Vascular Diagnostic Systems Market?
As of 2026, the market valuation for North America Peripheral Vascular Diagnostic Systems is approximately USD 1.2 Billion, reflecting a growing adoption of diagnostic technologies. This valuation accounts for the increasing prevalence of vascular diseases and technological advancements improving diagnostic accuracy.
What factors are driving the North America Peripheral Vascular Diagnostic Systems Market?
Market growth is primarily driven by the rising incidence of peripheral vascular diseases, technological innovations in diagnostic systems, increasing awareness, and the expanding geriatric population. escalating healthcare expenditure and regulatory support for minimally invasive procedures also contribute significantly.
Which region dominates the North America Peripheral Vascular Diagnostic Systems Market?
The United States dominates the North American market due to its advanced healthcare infrastructure, high adoption rate of new medical technologies, and substantial investment in vascular disease diagnostics. Canada holds a significant share, supported by expanding healthcare services and awareness.
Which segment is expected to grow the fastest?
The non-invasive diagnostic devices segment is projected to exhibit the highest growth rate, driven by technological advancements, increasing preference for minimally invasive procedures, and growing patient demand for early, accurate diagnosis of peripheral vascular conditions.
Who are the leading companies operating in the North America Peripheral Vascular Diagnostic Systems Market?
Key players include Abbott Laboratories, Siemens Healthineers, General Electric, Philips Healthcare, and Canon Medical Systems. These companies focus on innovative product development and strategic partnerships to strengthen their market presence in North America.
Analyst Perspective
The North America Peripheral Vascular Diagnostic Systems Market is poised for sustained growth through 2034, driven by technological advancements and increasing vascular disease prevalence. Long-term market prospects appear robust, with ongoing innovations in imaging and minimally invasive procedures enhancing diagnostic accuracy and patient outcomes. Commercial opportunities are significant, especially in developing portable and integrated diagnostic solutions that cater to outpatient and remote care settings. Investment focus should prioritize cutting-edge technologies such as AI-driven diagnostics and improved sensor sensitivity, which can provide competitive differentiation and operational efficiencies. Competitive intensity remains high, with key players expanding their portfolios via strategic acquisitions and partnerships. Regionally, North America’s mature healthcare infrastructure offers substantial growth potential, reinforced by rising chronic disease burdens and aging populations. However, market entrants must navigate regulatory complexities and healthcare reimbursement challenges. Overall, organizations that prioritize technological innovation and regional adaptability are best positioned to capitalize on the evolving landscape and sustain long-term growth in this dynamic sector.
