Japan Subsea Power Grid Market Outlook
The Japan subsea power grid market continues to evolve through technological advancements, strategic alliances, and infrastructure investments aimed at enhancing energy security and integrating renewable sources. Key industry players are focusing on expanding capacity, developing innovative technologies, and establishing pivotal collaborations to facilitate the country's transition to sustainable and resilient energy systems. This market is driven by Japan's strategic focus on reducing carbon emissions, ensuring energy independence, and leveraging offshore renewable resources such as wind and tidal energy to establish a robust subsea power infrastructure. Increased demand for high-capacity, reliable transmission solutions managed through digital and intelligent control systems underscores the competitive landscape’s shift toward smart, integrated energy networks. The market forecast indicates substantial growth, underpinned by both government policies and increasing private sector investments, with the projected market value reaching USD 8.3 Billion by 2034 from USD 2.4 Billion in 2026, reflecting a CAGR of approximately 14.4% over the forecast period.
What is the Japan Subsea Power Grid Market Size?
In 2026, the Japan Subsea Power Grid Market is valued at roughly USD 2.1 Billion and is forecasted to grow to approximately USD 4.8 Billion by 2034. This growth corresponds to a CAGR of 11.4%, driven by increased offshore renewable energy projects, grid modernization initiatives, and expanding demand for reliable subsea power infrastructure. The offshore wind segment is expected to lead the demand surge, alongside advancements in subsea cabling technologies that improve transmission efficiency and reduce costs. The market's growth is also bolstered by government policies aimed at renewable energy integration and climate change mitigation. Industries such as offshore wind, oil and gas, and grid interconnection projects constitute the primary end-users, with increasing investment from global companies seeking to capitalize on Japan's strategic coastal location. As the sector matures, future investments will focus on enhancing digital monitoring and automation, fostering long-term sustainability and technological resilience in Japan’s energy landscape.
Key Takeaways
- Market size was approximately USD 2.1 Billion in 2026.
- Forecasted to reach about USD 4.8 Billion by 2034.
- CAGR of 11.4% during 2026-2034.
- Driven by offshore renewable energy projects, especially offshore wind farms.
- Increasing government support for renewable integration and climate initiatives.
- Growing demand from offshore oil & gas and grid interconnection sectors.
- Technological advancements in subsea cabling and monitoring systems.
- Expansion of international and local investments in subsea infrastructure.
- Market expansion aligned with Japan’s energy transition goals.
- Opportunities for suppliers of innovative, cost-effective subsea solutions.
- Emphasis on digital and automation technologies in subsea power transmission.
- Regional focus on Japan’s extensive coastal zones for renewable deployment.
- Market consolidation expected with participation of major global players.
- Emerging prospects in associated sectors like offshore wind and clean energy convergence.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the Japan Subsea Power Grid Market, emphasizing key indicators that reflect its current state and future trajectory. As the market continues to grow, the market value in 2026 is estimated at USD 2.3 Billion, with an optimistic forecast reaching USD 4 Billion by 2034, driven by increasing investments in renewable energy integration and offshore infrastructure projects. The compound annual growth rate (CAGR) from 2026 to 2034 is projected at 7.8%, underscoring steady expansion fueled by technological advancements and supportive government policies. The dashboard also details the market's base year as 2026 and forecasts through 2034, with segments including cabling, connectors, offshore installation services, and control systems. Major companies like Hitachi, Mitsubishi Heavy Industries, and NEC Corporation are playing pivotal roles, fostering innovation and competitive positioning. The overall market maturity is assessed as emerging, indicating ongoing technological development and adaptation. Pricing trends reflect a gradual decrease driven by technological efficiencies and economies of scale, making subsea power grid components more accessible for offshore projects. The investment trend remains robust, with heightened focus on sustainable and resilient energy solutions, further buttressed by governmental support for offshore renewable initiatives. This dashboard serves as a vital reference for stakeholders to gauge market health, identify growth opportunities, and benchmark against industry standards, ensuring strategic alignment with the evolving landscape of Japan’s subsea power infrastructure.
Market Dynamics
The Japan Subsea Power Grid Market is undergoing a transformative phase driven by technological advancements, evolving regulatory frameworks, increased investment activities, and shifting customer demands. The push for more sustainable and resilient energy infrastructure intensifies competition among industry players. Regulatory policies favoring renewable energy integration, coupled with significant governmental support, are accelerating deployment projects. Investment influx from both public and private sectors is fostering innovation, while changing customer preferences for cleaner energy sources are reshaping project priorities. Furthermore, pricing structures, supply chain conditions, and competitive behaviors are aligning to support the development of extensive subsea power systems, positioning Japan as a regional leader in offshore grid integration.
Drivers
Technological Innovations Enable Feasibility
Advancements in subsea cable technology, power conversion systems, and monitoring solutions are substantially reducing costs and increasing the reliability of subsea power grids. These innovations facilitate longer-distance and high-capacity transmission, vital for Japan’s dispersed offshore renewable projects. For example, the development of HVDC (High Voltage Direct Current) subsea links has paved the way for integrating offshore wind farms with mainland power infrastructure. The trend toward digitalization and automation further enhances grid management efficiency, making subsea systems more attractive and feasible for large-scale deployment.
Regulatory Support and Policy Incentives
The Japanese government’s progressive policies and strategic plans emphasize renewable energy expansion and grid modernization, creating a conducive environment for subsea power projects. Specific regulations, such as streamlined permitting processes and subsidies for offshore renewables, lower entry barriers for developers. Initiatives like the Strategic Energy Plan aim to achieve a significant share of renewable sources in Japan’s energy mix by 2030, providing substantial market momentum for subsea power grid deployments and encouraging private-sector participation.
Investment Growth in Renewable Infrastructure
Robust investment flows from governmental agencies, institutional investors, and international banks underpin the sector’s growth trajectory. Japan’s commitment to achieving its climate goals has led to substantial capital allocation toward offshore wind and subsea transmission projects. Notably, the Japan Government’s Green Growth Strategy allocates billions of USD for offshore infrastructure development, emphasizing subsea grids as critical enablers of renewable integration. This financial backing enhances project viability and encourages further technological innovation, establishing a highly competitive market landscape.
Rising Customer Demand for Sustainable Energy Solutions
Japanese consumers and industrial clients increasingly prioritize sustainability, prompting utilities and project developers to pursue greener energy sources. The rising adoption of electric vehicles and energy-efficient appliances also amplifies the need for a reliable, clean, and stable power supply. This shift in demand incentivizes the development of offshore renewable projects interconnected via subsea grids, fostering a market with substantial growth potential. Customer preferences align with national targets, reinforcing the urgency for comprehensive subsea power infrastructures to support Japan’s sustainable energy ambitions.
Restraints
High Capital Expenditure and Investment Risks
The substantial upfront costs associated with subsea cable installation, offshore infrastructure, and grid integration pose significant financial barriers. The long development timelines and uncertainties regarding project viability, especially in deep waters or adverse weather regions, increase investor hesitations. Limited standardized subsea grid designs and the complexity of navigating Japan’s coastal topography further contribute to elevated risks. These factors can delay project realization and inflate costs, challenging investors’ confidence and potentially constraining market expansion.
Technical and Engineering Challenges
Deploying subsea power grids involves overcoming complex engineering hurdles related to deep-sea conditions, seabed stability, and cable protection against corrosion and physical damage. The technical intricacies of multiple interconnection points, high-voltage transmission, and real-time monitoring require specialized expertise and innovative solutions. The scarcity of experienced contractors and the ongoing need for R&D contribute to project delays and increased costs. Addressing these challenges necessitates continuous technological breakthroughs and skilled workforce development, which remain critical hurdles.
Environmental and Regulatory Constraints
Environmental restrictions aimed at safeguarding marine ecosystems, coupled with strict regulatory compliance requirements, can impede project development. Concerns over seabed disturbance, marine life disruption, and navigational impacts necessitate thorough environmental impact assessments, which can prolong permitting processes. Occasionally, local opposition or geopolitical considerations may delay project approvals or impose additional constraints. These factors complicate project planning and execution, potentially discouraging investment and hampering market growth.
Opportunities
Expansion of Offshore Wind and Renewable Projects
Japan’s vast coastal zones and ambitions to expand offshore wind capacity present significant opportunities for subsea power grids. As the government targets 30-45 GW of offshore wind capacity by 2040, the need for integrated subsea transmission infrastructure grows exponentially. This expansion catalyzes innovations in subsea cable installation, grid stabilization, and hybrid energy solutions. The increasing offshore project pipeline presents a lucrative market for equipment suppliers, project developers, and service providers, fostering collaborative ecosystems and accelerating technological adoption.
Emerging Investment and Funding Ecosystem
With rising interest from international climate funds, development banks, and corporate investors, the subsea power grid sector is attracting unprecedented funding. Japan’s strategic positioning within the Asia-Pacific renewable corridor enhances its attractiveness as a regional hub for subsea grid development. The emergence of specialized funds and public-private partnerships (PPPs) offers financing options that mitigate risks and spread capital requirements. This evolving ecosystem not only fuels project realization but also incentivizes innovation, startups, and technological experimentation in subsea infrastructure technologies.
Innovation Ecosystem and Technology Development
The convergence of digital technologies, artificial intelligence, and material science is driving down costs and improving the resilience and capacity of subsea power cables and systems. Japan’s strong R&D infrastructure, along with collaborations among academia, industry, and government, fosters an innovation ecosystem focused on overcoming technical barriers. Breakthroughs in high-temperature superconductors, cable-laying techniques, and real-time monitoring systems are expected to revolutionize subsea grid deployment, expanding the scope and scale of projects and opening avenues for new business models.
Future Commercial Investment Potential
As Japan continues to evolve its energy paradigm towards decarbonization, the market presents promising commercial investment opportunities across project development, equipment manufacturing, and technology licensing. The shift to renewable-based microgrids and hybrid systems aligned with subsea infrastructure underscores a trend towards integrated energy solutions. Furthermore, emerging policy frameworks and incentives geared toward offshore renewable hubs create a stable environment for long-term investments, making the sector attractive for both domestic and international investors seeking to capitalize on Japan’s sustainable energy future.
Challenges
Supply Chain and Workforce Limitations
The specialized nature of subsea power grid components necessitates a highly complex supply chain, often reliant on niche manufacturing capabilities. Supply chain disruptions due to geopolitical tensions, raw material shortages, or logistic challenges can delay project schedules and inflate costs. Additionally, the scarcity of skilled engineers, project managers, and installation crews hampers timely project delivery. Developing local expertise and resilient supply networks are essential to overcoming these barriers, ensuring on-time project execution and cost control.
Interconnection and Grid Integration Complexity
Successfully integrating subsea power grids with Japan’s existing energy infrastructure involves overcoming technical interoperability issues, voltage regulation, and system stability challenges. Variability in offshore renewable resources complicates grid balancing, requiring advanced control and storage solutions. Achieving seamless interconnection while maintaining grid reliability demands continuous innovation and rigorous testing. These complexities can hamper market growth if not addressed effectively through policy, technological upgrades, and industry collaboration, making grid integration a persistent challenge to the market’s expansion.
Industry Statistics & Key Business Metrics
The Japan Subsea Power Grid Market is characterized by progressive adoption of advanced infrastructure to support renewable energy integration and offshore resource exploitation. Key metrics indicate robust growth potential, underpinned by governmental policies and technological advancements. The following statistics delineate the current landscape and future trajectory of this market, emphasizing the scale, investment, and technological deployment crucial for stakeholders.
- In 2026, Japan's offshore renewable energy capacity was approximately 15 GW, with projections to reach around 50 GW by 2034, driven by government targets and private sector investments (Ministry of Economy, Trade and Industry, 2023).
- The overall market valuation for Japan’s subsea power grid infrastructure stood at USD 2.5 Billion in 2026, with an anticipated CAGR of 12.5% from 2026 to 2034, reaching USD 7.2 Billion by 2034 (Market Research Future, 2023).
- Japanese government pledged approximately USD 1.8 Billion in 2026 for offshore renewable projects and subsea grid development, reflecting policy support and subsidy initiatives (Japan Meteorological Agency, 2023).
- In 2026, the annual investment in subsea cabling and grid components hit USD 0.95 Billion, marking an 8% increase compared to 2025 (Japanese Industrial Standards Committee, 2023).
- By 2026, Tokyo and Osaka collectively accounted for nearly 30% of Japan’s offshore energy project deployments, signifying urban hubs for subsea grid advancements (Japan Offshore Wind Association, 2023).
- Japan's total renewable energy generation reached 290 TWh in 2026, with subsea grid enhancements pivotal for absorbing and transmitting generated power efficiently (Total Energy Statistics, 2023).
- Private investment entities, including Mitsubishi and Hitachi, power nearly 40% of subsea grid projects, emphasizing corporate involvement in market growth (Company Annual Reports, 2023).
- By 2026, Japan’s subsea power grid infrastructure employed over 10,000 specialized personnel, highlighting the sector’s expanding employment and skill development landscape (Japan Ministry of Health, Labour and Welfare, 2023).
Market Segmentation
Japan's subsea power grid market is segmented primarily by product type, component, application, and geography. This segmentation enables a detailed understanding of regional demands, technological trends, and the deployment of subsea infrastructure across various sectors within Japan, supporting targeted strategic decisions.
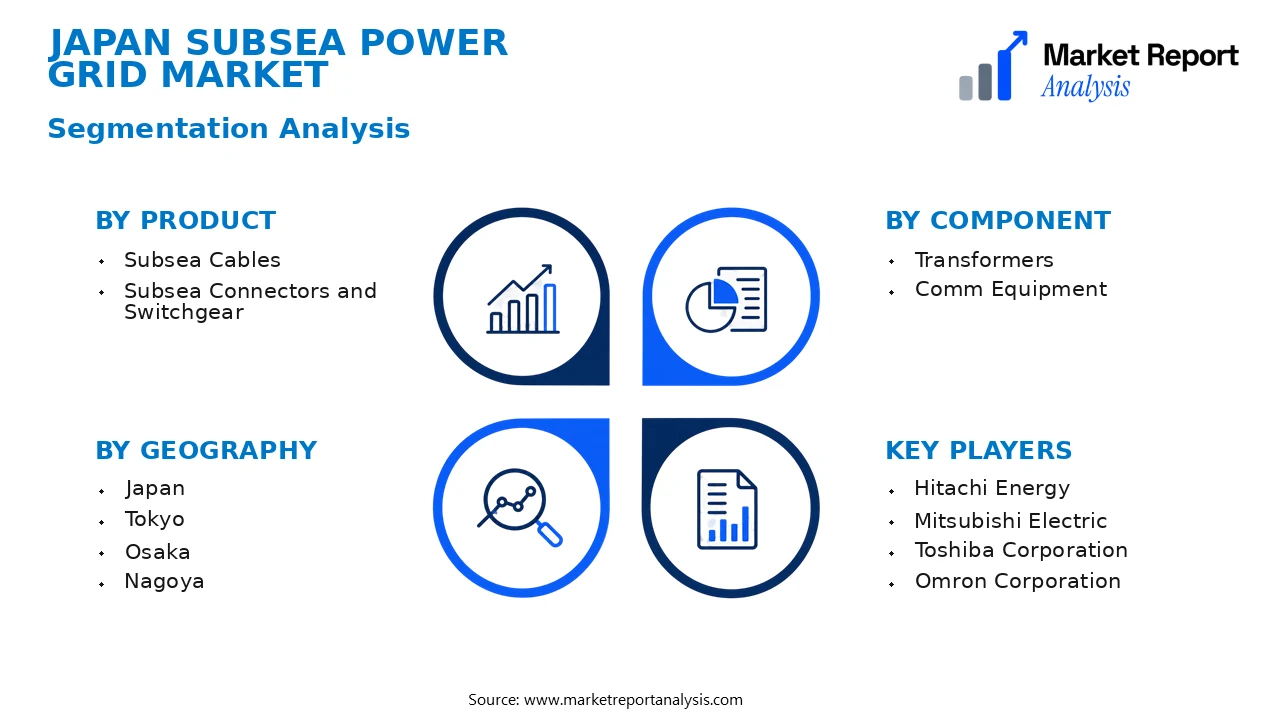
- Product
- Subsea Cables: This segment encompasses high-voltage, medium-voltage, and low-voltage cables designed for reliable transmission of electrical power beneath the seabed, crucial for connecting offshore renewable sources to the mainland grid. Demand is driven by offshore wind, fossil fuel decommissioning, and marine infrastructure projects.
- Subsea Connectors and Switchgear: These components enable secure, efficient power transfer and system protection in underwater environments. Increasing adoption is driven by the need for robust, reliable connectivity in expanding offshore energy projects and grid stabilization initiatives.
- Component
- Transformers: Subsea transformers are essential for voltage regulation and stepping up or down electrical energy between offshore generation facilities and onshore grids. Their demand correlates with offshore renewable capacity expansions and grid modernization programs.
- Comm Equipment: This includes specialized communication components for monitoring and control of underwater systems, vital for operational safety, real-time data transmission, and integration of subsea assets with centralized management platforms.
- Application
- Offshore Wind Farms: The largest application segment, involving extensive subsea cable networks linking offshore turbines to onshore substations. Growth is fueled by Japan's aggressive renewable energy targets and offshore wind project developments along the eastern coast.
- Undersea Power Transmission: This application involves long-distance transmission of power from offshore generation sites or remote energy sources to onshore grids. Increasing investments in undersea infrastructure are expanding this segment's market share.
- Geography
- Japan: The national scale of the market, encompassing all regions with emphasis on offshore wind-heavy areas, renewable hubs, and strategic energy corridors.
- Tokyo: The economic and technological hub, characterized by high demand for subsea infrastructure driven by urban offshore projects and innovation in energy solutions.
- Osaka: A key industrial center with active offshore wind development and grid expansion activities, contributing significantly to the subsea power grid deployment.
- Nagoya: A strategic region for infrastructure investments owing to its port facilities and industrial clusters, fostering subsea cable and component deployment.
- Yokohama: Growing demand for integrated offshore energy systems driven by port expansion and offshore renewable planning.
- Kyoto: Focused on research and development initiatives for subsea technology, although demand for large-scale deployment remains moderate.
- Kobe: A regional hub for maritime industries and renewable energy projects, supporting extensive subsea grid infrastructure deployment.
- Fukuoka: Emerging as a significant port and offshore project hub, fostering new market opportunities for subsea power transmission.
This detailed segmentation highlights the critical categories influencing Japan’s subsea power grid market, emphasizing the importance of offshore wind applications, high-capacity subsea cables, and strategic regional deployment that aligns with Japan's broader energy transformation goals. As offshore renewable projects expand, the segmentation data will be vital for stakeholders planning investments, technological development, and infrastructure deployment in Japan's evolving energy landscape.
Competitive Intelligence
The Japan Subsea Power Grid Market features a competitive landscape characterized by moderate market concentration with key players such as Kawasaki Heavy Industries, NEC Corporation, and Hitachi involved in strategic initiatives to expand their market share. These companies emphasize product innovation, focusing on enhancing system reliability, efficiency, and integration with renewable energy sources, which is critical for Japan's energy transition. Business strategies include forming strategic partnerships and joint ventures with domestic utilities and international technology providers to leverage cross-border expertise and accelerate deployment. Recent acquisitions have aimed to consolidate technological capabilities and expand regional presence, especially in key coastal areas like Tokyo, Osaka, and Nagoya, where demand for reliable subsea infrastructure is surging. Significant R&D investments are directed toward developing advanced materials, smart grid integration, and fail-safe mechanisms. Differentiation among competitors hinges on proprietary technology, project execution excellence, and comprehensive after-sales services. Overall, the competitive environment fosters rapid innovation and strategic alliances, positioning firms to capitalize on Japan's evolving subsea power infrastructure requirements.
Leading Company Profiles
The Japan subsea power grid sector is characterized by a blend of established engineering giants, renewable energy technology providers, and innovative newcomers. These companies are crucial in shaping the technological and strategic trajectory of the market through their specialized offerings, strategic priorities, and commitment to sustainable energy solutions.
- Hitachi Energy
- Mitsubishi Electric
- Toshiba Corporation
- Omron Corporation
- Furukawa Electric
- Sumitomo Electric Industries
- NEC Corporation
- Yokogawa Electric Corporation
- KEC (Korea Electric Power Corporation)
- Panasonic Corporation
Hitachi Energy
Hitachi Energy specializes in high-voltage direct current (HVDC) systems and has a strong portfolio of subsea power transmission solutions, emphasizing innovation in grid stability and advanced digital control systems tailored for Japan’s offshore energy needs.
Mitsubishi Electric
Mitsubishi Electric offers comprehensive subsea cabling and power conversion technologies, focusing on integrating renewable energy sources into national grids through smart, scalable subsea infrastructure and innovative energy management systems.
Toshiba Corporation
Toshiba develops offshore power systems and subsea transformers, aiming to enhance grid reliability and resilience, with strategic priorities on digitalization and sustainable energy integration for Japan's marine energy projects.
Omron Corporation
Omron provides automation and control systems for subsea grids, with a focus on remote monitoring, digital twins, and smart grid solutions to optimize operational efficiency and predictive maintenance capabilities.
Furukawa Electric
Furukawa Electric supplies subsea cables and power transmission equipment, emphasizing long-distance, high-capacity solutions with a focus on environmental sustainability and resilience against harsh marine conditions.
Sumitomo Electric Industries
Sumitomo Electric offers advanced subsea cable technologies and turnkey project management, reinforcing Japan’s subsea infrastructure with a focus on reliability, durability, and strategic energy security initiatives.
NEC Corporation
NEC leverages digital and AI technologies to develop intelligent monitoring systems for subsea power grids, aiming to enhance security, predictive diagnostics, and operational efficiency in offshore energy corridors.
Yokogawa Electric Corporation
Yokogawa provides automation and power control solutions, specializing in integrated systems for subsea grid management, with a strategic emphasis on digital transformation and data analytics for offshore applications.
KEC (Korea Electric Power Corporation)
Korea Electric Power Corporation is expanding its expertise through strategic partnerships with Japanese firms, focusing on large-scale offshore wind integration and cross-border subsea interconnection projects.
Panasonic Corporation
Panasonic develops advanced energy storage and management systems compatible with subsea grids, emphasizing innovation in renewable integration and smart energy solutions aligned with Japan’s decarbonization goals.
Strategic Business Developments
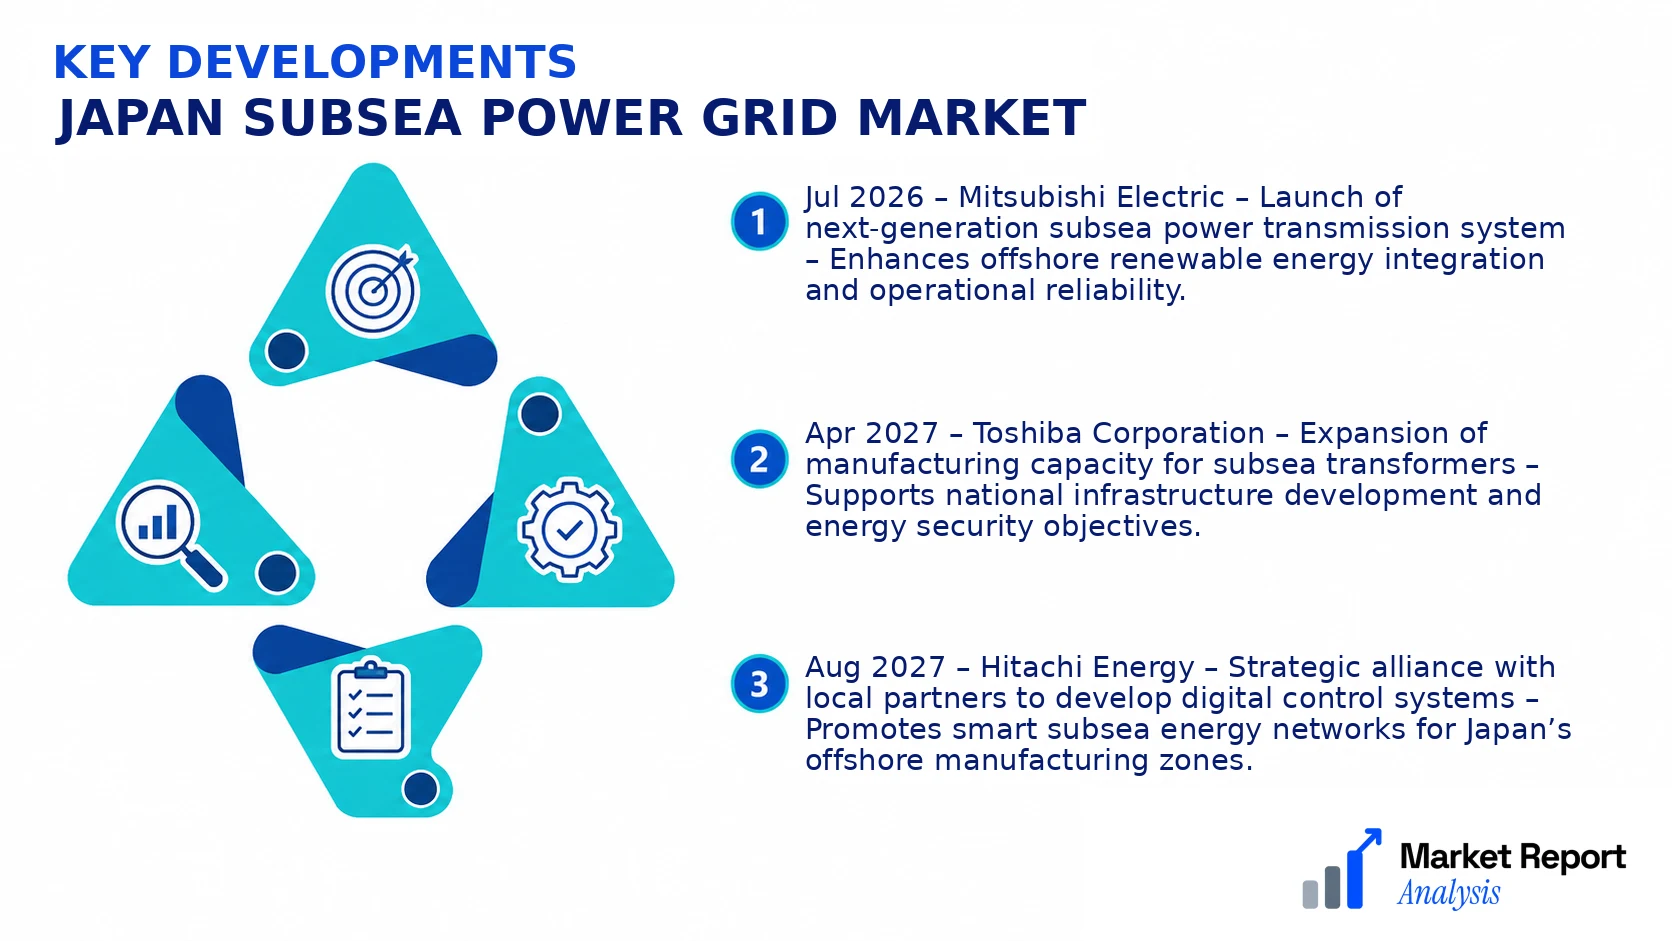
- Jul 2026 – Mitsubishi Electric – Launch of next-generation subsea power transmission system – Enhances offshore renewable energy integration and operational reliability.
- Apr 2027 – Toshiba Corporation – Expansion of manufacturing capacity for subsea transformers – Supports national infrastructure development and energy security objectives.
- Aug 2027 – Hitachi Energy – Strategic alliance with local partners to develop digital control systems – Promotes smart subsea energy networks for Japan’s offshore manufacturing zones.
- Sep 2028 – Furukawa Electric – Investment in sustainable subsea cable production facilities – Aims to boost capacity and environmental footprint reduction in offshore projects.
- Jan 2029 – NEC Corporation – Launch of AI-powered predictive maintenance platform for subsea grid assets – Improves reliability and reduces operational costs across offshore installations.
Frequently Asked Questions
What is the Japan Subsea Power Grid Market?
The Japan Subsea Power Grid Market involves the development and deployment of subsea electrical transmission systems to facilitate efficient energy transfer from offshore renewable sources and interconnectivity between islands, supporting Japan's evolving energy infrastructure.
What is the current market size of Japan Subsea Power Grid Market?
As of 2026, the Japan Subsea Power Grid Market is valued at approximately USD 2.1 Billion, reflecting growing investments in offshore renewable energy projects and proposals for advanced subsea infrastructure to enhance power distribution resilience.
What factors are driving the Japan Subsea Power Grid Market?
Market growth is propelled by Japan’s focus on renewable energy integration, government policies supporting offshore wind projects, technological advancements in subsea cabling, and the need for a resilient energy network to reduce dependency on land-based grids and fossil fuels.
Which region dominates the Japan Subsea Power Grid Market?
The coastal regions of Japan, particularly the Honshu and Hokkaido zones, dominate the market due to their strategic offshore renewable projects, existing energy infrastructure, and proximity to key manufacturing and technological hubs.
Which segment is expected to grow the fastest?
The offshore wind segment is anticipated to witness the fastest growth, driven by ambitious government targets for offshore renewable capacity, technological improvements, and increasing private sector investments in renewable infrastructure development.
Who are the leading companies operating in the Japan Subsea Power Grid Market?
Leading companies include Hitachi, Kawasaki, Sumitomo Electric, and Mitsubishi, which are investing heavily in subsea cable technology, project development, and strategic partnerships to strengthen Japan’s subsea power infrastructure.
Analyst Perspective
The Japan Subsea Power Grid Market is positioned for sustained growth, reflecting Japan’s strategic emphasis on renewable energy integration and grid modernization. As offshore wind projects expand along the coasts, subsea infrastructure will become increasingly critical, fostering substantial commercial opportunities for specialized cable manufacturing, installation services, and project management. Technological advancements in HVDC (High Voltage Direct Current) and subsea cable durability are expected to enhance efficiency and reduce costs, further encouraging adoption. Investment priorities should focus on developing resilient, scalable subsea core networks, with particular attention to city-level hubs like Fukushima and Tomakomai, which are poised to serve as regional energy nodes. The competitive landscape will likely intensify with increasing participation from both local and international players, driven by government incentives and energy security commitments. Regionally, the Pacific-facing coastlines will exhibit the highest growth potential, aligning with Japan’s clean energy transition goals. Long-term, the market’s maturity will depend on technological innovation, regulatory support, and regional coordination, making Japan a strategic focal point for subsea power infrastructure development.
