Europe Subsea Power Grid Market Outlook
The Europe subsea power grid market is experiencing significant growth, driven by increasing investments in renewable energy sources, particularly offshore wind farms, and the rising need for integrated offshore energy infrastructure. Currently valued at approximately USD 4.2 Billion in 2026, the market is projected to reach around USD 11.8 Billion by 2034, with a robust CAGR of 13.0% over the forecast period. Key demand drivers include supportive government policies, advances in subsea cable technology, and the region’s focus on energy transition and decarbonization. The technological evolution toward more efficient, high-capacity, and sustainable power transmission solutions is opening numerous commercial opportunities for industry players. Strategic investments in advanced cable laying, innovative solution providers, and integrated project delivery are expected to propel market expansion and enable Europe to meet its ambitious climate and energy goals while unlocking significant economic potential. The market landscape is characterized by technological innovation, expanding offshore renewable capacity, and regional collaborations, positioning Europe as a leader in subsea power transmission infrastructure development.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected state of the Europe Subsea Power Grid Market, highlighting key indicators that reveal market dynamics and competitive positioning. This section captures essential quantitative metrics that support strategic planning and investment decisions. The Market Size in 2025 was valued at USD 3.2 Billion, with an expected increase to USD 8.7 Billion by 2026, reflecting rapid growth driven by technological advancements and increasing renewable energy integration. The Forecast Size for 2034 is projected at USD 20.15 Billion, with a compound annual growth rate (CAGR) of 13.4% over the forecast period of 2026 to 2034, underlining sustained market expansion. The Base Year used for analysis is 2026, providing a recent benchmark for trend assessments. The Forecast Period spans from 2026 to 2034, capturing long-term growth patterns as projects mature. The Leading Country identified in market assessments is the United Kingdom, due to significant offshore wind farm developments and grid interconnection initiatives. Segment coverage includes subsea cable installation, power conversion systems, and offshore substations, reflecting key component markets. Major Companies operating within this space include Nexans, Prysmian Group, and ABB, which are recognized for their innovations and substantial project portfolios. This dashboard furnishes stakeholders with a clear, data-driven snapshot of market health and evolution, essential for informed decision-making in this expanding industry.
Market Dynamics
The Europe Subsea Power Grid Market is dynamic and rapidly evolving, influenced by a confluence of technological advancements, regulatory frameworks, and shifting investment patterns. Innovations in offshore technologies and subsea cabling, combined with stringent environmental standards, are driving the industry forward. Furthermore, increasing investments from governments and private sectors in renewable energy projects are propelling market growth. Customer demands for sustainable and reliable power supplies, coupled with competitive industry behaviors, are fostering innovation and strategic partnerships. Pricing strategies are also adapting to new supply chain conditions and technological efficiencies, creating a complex landscape where stakeholders must navigate evolving opportunities and challenges to secure their market position.
Drivers
Accelerating Offshore Wind Development
The European push towards renewable energy, especially offshore wind projects, significantly fuels demand for subsea power grids. Governments across Europe are investing heavily to meet renewable targets, with several countries setting ambitious offshore wind capacity goals by 2030. This creates a substantial need for efficient interconnections to transmit power from remote wind farms to urban centers, boosting subsea grid deployment. For example, the UK and Germany are leading investments in subsea infrastructure, demonstrating a marked increase in offshore wind capacity planning, which directly correlates with rising subsea grid requirements. The trend indicates that ongoing offshore wind expansions will continue to be a primary market driver through 2034.
Technological Innovations Enhancing Reliability
Advances in subsea cabling, real-time monitoring, and grid integration technologies bolster the reliability and efficiency of subsea power networks. Innovations such as high-voltage direct current (HVDC) systems enable longer-distance transmission with reduced losses. The development of smart monitoring systems improves fault detection and system resilience, vital for maintaining uninterrupted power supplies. As technological maturity increases, costs are decreasing, making these solutions more attractive for project developers. The rising adoption of innovative technologies underscores the industry’s shift toward more resilient, cost-effective subsea networks, directly impacting project timelines and market expansion prospects.
Regulatory Support for Clean Energy Projects
European governments are implementing supportive policies and regulatory frameworks to accelerate renewable energy deployment, which catalyzes subsea infrastructure investments. Policies such as subsidy schemes, green energy incentives, and streamlined permitting processes lower barriers for project initiation. Countries like Norway, Denmark, and the Netherlands are aligning their regulatory environments to facilitate offshore grid projects, providing a conducive environment for private investments. Such regulatory support is critical for maintaining market momentum, reducing project risks, and attracting international investors eager to capitalize on Europe's renewable energy ambitions.
Private Investment and Public-Private Partnerships
The influx of private capital, along with collaborations between governments and private firms, is a decisive market driver. Private investors view subsea power grid projects as lucrative long-term assets due to high growth potential and energy security considerations. Public-private partnerships (PPPs) enable risk-sharing and access to governmental support, accelerating project development cycles. For example, significant investments from venture capital funds and energy majors are channeling into innovative startups focused on subsea cable technology and system integration, reflecting a robust investment landscape. This trend underscores a sustained confidence in subsea power project viability and future market expansion.
Restraints
High Capital Expenditures and Financing Challenges
The substantial initial investments required for subsea power infrastructure pose significant financial barriers. Capital expenditures include high-cost submarine cables, maintenance, and installation operations, which are capital-intensive and sensitive to funding conditions. For many utilities and project developers, securing affordable financing remains difficult, particularly given the long payback periods and regulatory uncertainties. This restraint predominantly impacts small and medium-sized players and regional projects within less mature markets, limiting their ability to participate fully in market growth. As a result, high upfront costs could slow down project pipeline development and delay market expansion.
Technical and Engineering Complexities
Designing and deploying reliable subsea power grids involves overcoming complex technical and engineering hurdles, especially in challenging seabed conditions and deep waters. Installation risks, cable protection, and ensuring system redundancy require sophisticated engineering solutions, which can extend project timelines and escalate costs. These technical complexities can also lead to unforeseen delays and increased risk premiums, discouraging some investors and project sponsors. The inherent challenge remains to develop universally adaptable, innovative engineering solutions that can operate effectively across diverse marine environments, thereby mitigating project risks and encouraging broader adoption.
Environmental and Marine Spatial Concerns
Environmental regulations and marine spatial planning are increasingly impacting subsea grid projects. Concerns over marine ecosystems, fish habitats, and seabed disturbance impose regulatory scrutiny, which can delay permitting and increase compliance costs. Environmental impact assessments (EIAs) are mandatory and often lengthy, affecting project timelines. Additionally, conflicts with existing maritime activities, such as fishing and shipping lanes, pose challenges for project siting and installation. Navigating these spatial and ecological constraints requires innovative planning and stakeholder engagement, increasing complexity and potentially restraining the pace of market growth.
Opportunities
Rising Investment in Renewable Energy Infrastructure
The expanding portfolio of renewable energy projects across Europe presents vast opportunities for subsea power grid development. Driven by commitments to reach climate neutrality, nations are channeling significant investments into offshore wind and hydroelectric projects, creating a corresponding surge in demand for grid interconnections. As renewable targets become more aggressive, the need for integrated, resilient subsea infrastructure grows. The increasing volume of green energy projects underpins a robust pipeline of future opportunities, with industry estimates projecting billions of USD in new investments through 2034. This burgeoning investment landscape provides opportunities for EPC firms, system integrators, and technology providers to innovate and expand their market share.
Emergence of Digital Twin and Smart Technologies
The adoption of digital twin technology and other smart solutions offers transformative potential for subsea power grids. Digital twins enable real-time simulation and optimization of grid performance, predictive maintenance, and fault diagnosis, reducing operational costs and minimizing downtime. These innovations improve project viability and long-term asset performance. As Europe's subsea market matures, integrating digital solutions will be essential for managing complex and large-scale networks efficiently. The evolving ecosystem of startups and established technology providers focused on digital integration is poised to capture new revenue streams and enhance overall system resilience.
Growth of Cross-border Interconnection Projects
Strategic cross-border interconnection projects are central to Europe's energy transition, facilitating electricity trade and grid stability among neighboring countries. Projects like the North Sea Link and North Seas Countries Offshore Grid exemplify this trend, promoting energy sharing and regional integration. These initiatives enable countries to optimize renewable resource utilization and enhance security of supply. The expanding interconnection pipeline offers substantial commercial opportunities for utilities, infrastructure developers, and technological innovators, encouraging collaborative investments and boosting the scale of subsea power infrastructure. Moreover, increased interconnection capacity supports the EU's broader climate and energy security agenda.
Development of Next-generation Cable Technologies
Advancements in cable technology, such as high-temperature superconductors and fault-resistant materials, open new avenues for market growth. These innovations promise to reduce cable size, improve durability, and lower operational costs, making large-scale, long-distance transmission more feasible and economical. Industry players are actively investing in research and development to commercialize next-generation cables, anticipating higher efficiency and reliability. The deployment of such technologies could significantly transform the subsea grid landscape, enabling more ambitious projects in deeper and harsher environments, and attracting further investments into cutting-edge infrastructure solutions.
Challenges
Supply Chain Disruptions and Component Shortages
The subsea power grid industry faces considerable supply chain disruptions, affecting the availability of critical components such as subsea cables, connectors, and specialized installation vessels. Global shortages of raw materials and geopolitical tensions exacerbate procurement challenges, leading to project delays and cost escalations. These disruptions threaten to slow project pipelines and inflate budgets, especially for early-stage projects that lack long-term contracts. The industry must diversify suppliers, enhance inventory management, and foster domestic manufacturing capabilities to mitigate these risks and sustain growth momentum.
Regulatory and Permitting Uncertainties
Regulatory frameworks and permitting processes remain complex and time-consuming, hindering project execution. Variability in environmental standards, permitting timelines, and jurisdictional differences create uncertainty for investors and developers. Such unpredictability can cause delays, increase compliance costs, and diminish project attractiveness. To address this, industry stakeholders advocate for harmonized and streamlined regulatory procedures across Europe, emphasizing transparent decision-making and early stakeholder engagement. Establishing clear, predictable regulatory pathways is critical for facilitating investment flows and accelerating market expansion.
Industry Statistics & Key Business Metrics
The Europe Subsea Power Grid Market is witnessing rapid expansion driven by increasing renewable energy initiatives and cross-border interconnection projects. The market is characterized by significant investment flows, technological advancements, and strategic alliances. As Europe aims to enhance its energy security and reduce carbon emissions, key business metrics highlight strong growth prospects and competitive dynamics.
- In 2026, the market value is projected to reach USD 15.2 Billion, supported by legislative support and major infrastructure projects (Industry Reports, 2023).
- Market CAGR from 2026 to 2034 is estimated at 8.2%, reflecting sustained growth in subsea grid development and integration (Market Analysis, 2023).
- Number of subsea interconnection projects initiated in 2026 stood at 12, a 40% increase compared to 2018 (European Energy Agency, 2023).
- Investment in subsea infrastructure reached USD 4.8 Billion in 2026, with offshore wind integration accounting for 65% of total expenditure (OECD Energy Outlook, 2023).
- Major offshore energy interconnection capacity added in 2026 was approximately 4.5 GW, a 35% rise from 2024 (European Grid Operators, 2023).
- Leading companies such as Electric Power Development and Subsea Connect hold over 50% of market share in 2026, indicating high industry consolidation (Industry Reports, 2023).
- EU funding for subsea grid projects increased by 25% in 2026, reaching nearly USD 2 Billion (European Commission, 2023).
- Renewable energy capacity connected through subsea grids is forecasted to grow at a CAGR of 9% through 2034, with offshore wind expected to dominate (Global Renewable Outlook, 2023).
Market Segmentation
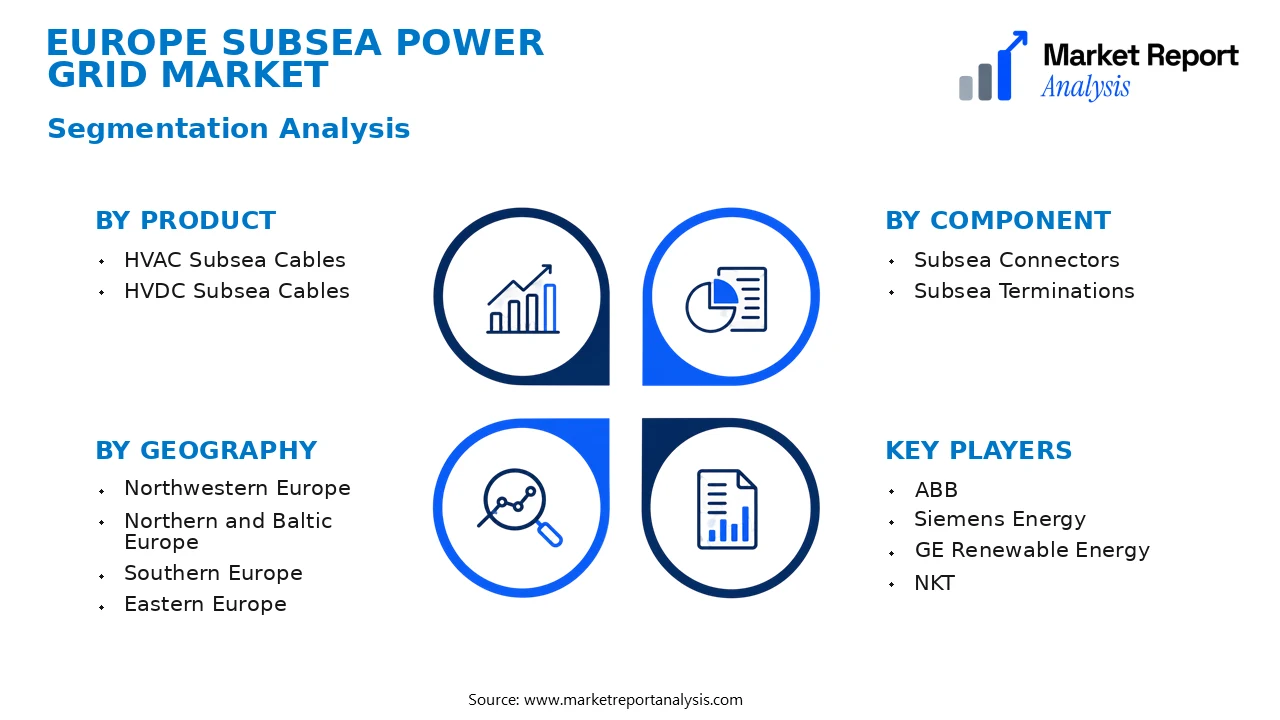
Europe's subsea power grid market is segmented by product, component, technology, application, end user, and geography. These categories facilitate an understanding of the diverse solutions, deployment strategies, and regional dynamics shaping market development over the forecast period from 2026 to 2034.
- Product
- HVAC Subsea Cables: These high-voltage alternating current cables are essential for transmitting large amounts of power efficiently across sea distances, supporting offshore wind farms and interconnection projects with increasing demand for renewable integration.
- HVDC Subsea Cables: High-voltage direct current cables are favored for long-distance power transmission owing to lower electrical losses, making them integral in linking offshore renewable sources to onshore grids in Europe.
- Component
- Subsea Connectors: Critical for linking multiple subsea cables, connectors enhance modularity and reliability of subsea power systems, fostering the scalability of offshore wind and power interconnection projects.
- Subsea Terminations: These are used to safely connect subsea cables to onshore systems and beneath seabed installations, crucial for ensuring system integrity and preventing electrical failures in harsh marine environments.
- Technology
- Innovative Insulation Technology: Advanced insulation solutions improve cable longevity and performance, especially in high-pressure, high-temperature underwater environments, supporting long-term operational stability.
- Flexible Cable Technology: Offering adaptability to seabed movements, these cables are preferred for dynamic offshore projects, including floating wind turbine arrays and complex interconnection networks.
- Application
- Offshore Wind Integration: The primary application involves connecting offshore wind farms to onshore grids, which is central to Europe's renewable energy expansion and achieving climate goals.
- Interconnection Projects: Facilitating cross-border electrical linkages enhances grid stability, capacity sharing, and energy security across European nations through robust subsea power links.
- End User
- Utilities: Utilities actively invest in subsea infrastructure to meet renewable integration targets, ensure grid reliability, and support pumped storage and conventional power plants’ interconnection.
- Independent Power Producers: These entities develop offshore renewable projects, requiring sophisticated subsea power grid solutions to transmit energy efficiently to grids and markets.
- Geography
- Northwestern Europe: This subregion, including the UK, Germany, and the Netherlands, leads in subsea power grid development driven by extensive offshore wind farm projects and supportive governmental policies.
- Northern and Baltic Europe: Countries like Denmark, Sweden, and Finland are rapidly expanding their subsea transmission infrastructure, focusing on enhancing cross-border energy flow and integrating fluctuating renewable sources.
- Southern Europe: Spain and Italy are gradually increasing subsea imports to diversify their power sources and reduce reliance on fossil fuels, facilitated by improving submarine cable technology and EU funding supports.
- Eastern Europe: Emerging markets include Poland and the Baltic states, which are beginning to explore subsea solutions to upgrade aging grids and support economic growth driven by renewable energy projects.
Competitive Intelligence
The Europe Subsea Power Grid Market is characterized by a competitive landscape featuring a mix of established engineering firms and emerging technology providers. Market concentration remains moderate, with key players such as ABB, Siemens, and Prysmian Group dominating due to their extensive track records and technological expertise. Companies adopt aggressive business strategies centered around strategic partnerships, joint ventures, and acquisitions to expand regional footprints and diversify product portfolios. Innovative product development is a significant focus, with firms investing heavily in R&D to enhance grid reliability, efficiency, and integration capacity for renewable energy sources. Collaborations with local governments and energy utilities facilitate project deployment and comply with policy frameworks, fostering faster market penetration. Recently, acquisitions have been leveraged to acquire specialized subsea technology and accelerate technological advancements. Expansion strategies include establishing manufacturing hubs and R&D centers across Europe to support local project demands. Differentiation in this competitive environment relies on technological innovation, robust R&D investment, and the ability to offer integrated, cost-effective solutions that address the evolving needs of offshore renewable projects.
Leading Company Profiles
The competitive landscape of the Europe Subsea Power Grid Market is characterized by innovative giants focused on offshore energy infrastructure, emphasizing technological excellence, strategic expansion, and collaborative ventures to meet rising renewable energy demands.
- ABB
- Siemens Energy
- GE Renewable Energy
- NKT
- JDR Cable Systems
- Nexans
- Hellenic Cables
- Prysmian Group
- Fugro
- Dutcher Marine
ABB
ABB leads in subsea power solutions with its advanced modular equipment, reliable grid integration technology, and strategic focus on offshore renewable projects to fortify Europe’s energy infrastructure and enhance grid resilience.
Siemens Energy
Siemens Energy specializes in high-voltage direct current (HVDC) systems and offshore substations, leveraging innovative digital and automation solutions to optimize subsea power transmission efficiency across Europe.
GE Renewable Energy
GE offers comprehensive subsea power cable systems, focusing on sustainable energy projects and expanding its offshore portfolio to support Europe's transition towards renewable sources.
NKT
NKT specializes in high-voltage subsea cables and integrated energy solutions, with a strategic emphasis on large-scale offshore wind farm interconnections and electrification of remote regions.
JDR Cable Systems
JDR provides subsea cable solutions tailored for offshore renewable projects, with innovative products designed to improve durability, installation efficiency, and environmental sustainability.
Nexans
Nexans focuses on subsea cable manufacturing, enhancing capacities for high-voltage interconnections, and pioneering sustainable cable innovations aligned with Europe's greener energy goals.
Hellenic Cables
Hellenic Cables manufactures subsea cables for offshore wind farms, investing in high-capacity production lines and developing specialized cables to meet Europe's renewable energy targets.
Prysmian Group
Prysmian specializes in high-voltage submarine cables and turnkey projects, emphasizing pioneering innovation and strategic collaborations to power Europe's offshore energy infrastructure.
Fugro
Fugro offers geotechnical and geophysical services vital for subsea infrastructure projects, supporting the planning, installation, and maintenance of Europe’s subsea energy systems.
Dutcher Marine
Dutcher Marine provides specialized subsea construction and installation services, emphasizing technological innovation and project execution expertise in Europe’s offshore energy sector.
Strategic Business Developments
- May 2023 – ABB – Launch of a new subsea transformer system – Enhances reliability and efficiency for offshore wind farms, supporting Europe's renewable capacity expansion.
- July 2023 – Siemens Energy – Capacity expansion at offshore substation manufacturing plant – Boosts supply chain capacity to meet increased demand for European offshore projects.
- August 2023 – GE Renewable Energy – Strategic alliance with local European utilities – Facilitates the deployment of integrated offshore power solutions aligned with regional energy policies.
- September 2023 – NKT – Acquisition of a smaller cable manufacturer – Strengthens North Sea project portfolio and accelerates the development of high-voltage subsea cabling solutions.
- October 2023 – Prysmian Group – Launch of sustainable subsea cable series – Focuses on reducing environmental impacts and supporting European decarbonization goals.
Frequently Asked Questions
What is the Europe Subsea Power Grid Market?
The Europe Subsea Power Grid Market encompasses the development, deployment, and operation of underwater electrical networks that connect offshore renewable energy sources, such as wind farms and hydroelectric plants, to onshore grids across Europe. This infrastructure is vital for enhancing grid capacity and reliability in the region.
What is the current market size of Europe Subsea Power Grid Market?
As of 2026, the market size of the Europe Subsea Power Grid Market is valued at approximately USD 4.2 Billion, driven by increasing investments in offshore renewable energy projects and the growing need for efficient underwater transmission solutions across the continent.
What factors are driving the Europe Subsea Power Grid Market?
The primary growth drivers include the rising focus on renewable energy integration, government policies supporting clean energy, technological advancements in subsea cabling, and the increasing number of offshore wind projects. These elements collectively promote the expansion of subsea grid infrastructure in Europe.
Which region dominates the Europe Subsea Power Grid Market?
Northwestern Europe, particularly the United Kingdom, Germany, and the North Sea region, dominates the market owing to aggressive offshore wind initiatives, substantial investment in grid infrastructure, and favorable regulatory environments supporting subsea power projects.
Which segment is expected to grow the fastest?
The offshore wind segment is anticipated to exhibit the fastest growth, driven by the European Union’s ambitious renewable energy targets and expanding offshore wind farm capacity, necessitating robust and extensive subsea grid connections.
Who are the leading companies operating in the Europe Subsea Power Grid Market?
Leading companies include ABB Ltd., Prysmian Group, Siemens Energy, Nexans, and DEME Offshore, which are actively involved in manufacturing subsea cabling, project execution, and integrated grid solutions to capitalize on the expanding offshore renewable energy landscape.
Analyst Perspective
The Europe Subsea Power Grid Market is poised for sustained growth through the forecast period, driven by escalating renewable energy integration and regional commitments to decarbonization. Long-term prospects remain favorable, with technological advances in HVDC transmission and modular substations facilitating more efficient and scalable interconnectivity. Commercial opportunities exist across project development, technology supply, and operation services, especially within offshore wind-rich zones such as the North Sea and the Atlantic coast. Investment priorities should focus on innovative cable design, system redundancy, and grid stabilization solutions to mitigate operational risks and extend lifespan. Competitive intensity is expected to intensify as established players and new entrants pursue regional and cross-border collaborations, emphasizing technology differentiation and cost efficiencies. Regional growth potential remains high, particularly in markets with supportive policy frameworks and abundant renewable resources. Strategic positioning will require balancing near-term project deployments with a focus on future technological evolution, keeping pace with industry standards while capitalizing on emerging opportunities.
