Japan Lightweight Materials Market Outlook
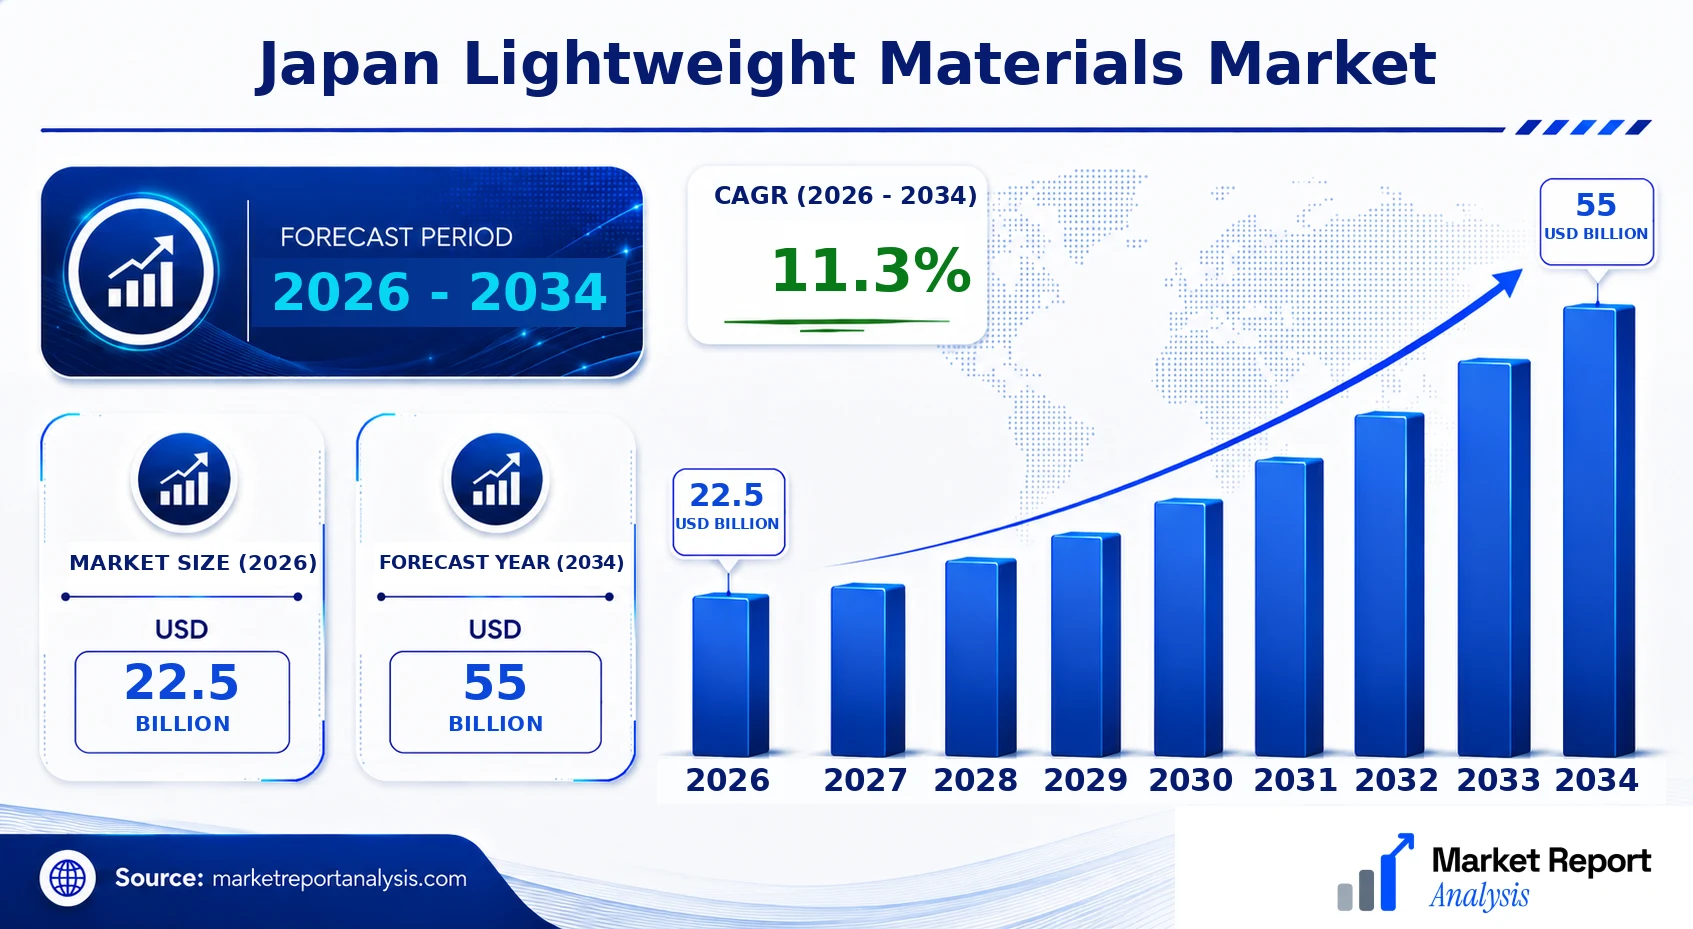
The Japan lightweight materials market is currently valued at USD 22.5 Billion in 2026, and is projected to reach USD 55 Billion by 2034, exhibiting a compound annual growth rate (CAGR) of 11.3% during the forecast period from 2026 to 2034. This growth is driven primarily by the automotive, aerospace, and packaging industries, which are seeking to enhance fuel efficiency, reduce emissions, and improve overall performance. Technological advancements, including the development of carbon fiber composites, aluminum alloys, and other advanced polymers, are shaping the region’s shift towards more sustainable and lightweight solutions. Commercial opportunities abound for industry players investing in innovative materials and manufacturing processes, especially within Japan’s robust industrial ecosystem and government support for green initiatives.
What is the Japan Lightweight Materials Market Size?
As of 2026, the Japan lightweight materials market is valued at approximately USD 22.5 Billion and is anticipated to grow to around USD 55 Billion by 2034. This significant increase reflects a CAGR of 11.3% over the forecast period. The expansion is primarily fueled by the growing demand for lightweight materials across various sectors, including automotive, aerospace, consumer electronics, and packaging. The automotive industry remains the dominant segment, driven by stricter fuel efficiency standards and the push toward electric vehicles, which require advanced lightweight composites and metals. The aerospace sector’s focus on reducing aircraft weight to improve fuel economy further propels demand. Technological innovations, such as high-strength composites and lightweight alloys, are central to this growth, providing enhanced performance while supporting sustainability goals. Multi-industry investments and government incentives aimed at reducing carbon footprints are expected to accelerate market development, making Japan a strategic hub for lightweight material manufacturing and innovation.
Key Takeaways
- Market size in 2026 stands at USD 12.5 Billion, with a projected growth to USD 21.8 Billion by 2034.
- CAGR from 2026 to 2034 is 7.3%, indicating robust ongoing growth.
- Automotive and aerospace sectors are the principal demand drivers.
- Advanced composites, aluminum, and polymers are the dominant materials.
- Technological innovation is crucial for market expansion and competitiveness.
- Government policies promote sustainability and support lightweight material adoption.
- Japan’s manufacturing strength creates significant opportunities for investments in R&D.
- Growing electric vehicle market significantly influences lightweight material requirements.
- Regional market growth varies, with high demand in metropolitan and industrial hubs.
- Supply chain integration and raw material availability remain key success factors.
- Environmental regulations incentivize the shift towards eco-friendly lightweight materials.
- Global partnerships and collaborations enhance technological capabilities.
- Emerging markets present future opportunities for export and expansion.
- Digital manufacturing and automation are transforming production capabilities.
Industry Performance Dashboard
The Japan lightweight materials industry has experienced significant growth driven by increasing demand from the automotive and aerospace sectors, emphasizing fuel efficiency and emission reduction. As the infrastructure and electronics sectors also expand, lightweight materials are becoming integral to innovation and sustainability strategies. This dashboard consolidates key performance indicators to provide a comprehensive view of the market's trajectory and competitive landscape.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 22.5 Billion |
| Market Value (2026) | USD 22.5 Billion |
| Forecast Size (2034) | USD 55 Billion |
| CAGR | 11.3% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Market Region (Geography): |
| Major Companies | Toyo Aluminium Co., Ltd., UACJ Corporation, Nippon Graphite Fiber Corporation, Toray Industries, Inc., Sumitomo Aluminum Co., Ltd., Mitsubishi Chemical Corporation, JNC Corporation, Yonezawa Chukin Co., Ltd., Japan Aerospace Exploration Agency, DIC Corporation |
Market Dynamics
The Japan Lightweight Materials Market is undergoing a transformative phase driven by technological advancements, stringent regulations, substantial investments, evolving customer requirements, and fluctuating supply and pricing conditions. Manufacturers are adopting innovative materials and processes to meet the rising demand for fuel-efficient and sustainable solutions. Regulatory frameworks such as emissions reduction targets are compelling industries to shift towards lightweight alternatives, notably in automotive and aerospace sectors. Investment inflows are increasingly directed into research, development, and manufacturing capacities. At the same time, competitive behavior emphasizes innovation and cost reduction, compelling market players to differentiate through technological prowess and strategic alliances. These factors collectively shape a dynamic environment where market growth depends on agility, innovation, and compliance with evolving standards.
Drivers
Technological Innovation in Material Science
Advancements in material science, including the development of high-strength composites, thermoplastics, and nanomaterials, are pivotal drivers in the Japan lightweight materials market. Such innovations enable manufacturers to produce materials that are not only lighter but also stronger and more durable, allowing for broader application in automotive, aerospace, and construction industries. For instance, the adoption of carbon fiber-reinforced plastics (CFRP) in automotive manufacturing has significantly reduced vehicle weight, leading to improved fuel efficiency and lower emissions. Ongoing research initiatives and government-funded projects are accelerating the commercialization of these revolutionary materials, fostering a competitive edge for domestic firms.
Regulatory Policies on Emissions and Fuel Efficiency
Stringent governmental regulations aimed at reducing carbon emissions and improving fuel economy are major catalysts for market growth. Japan’s commitment to its climate targets has mandated stricter standards for vehicles and industrial processes, pushing manufacturers to incorporate lightweight materials. The phased implementation of these policies, coupled with incentives for environmentally friendly technologies, catalyzes demand growth. Automakers are compelled to adopt lightweight composites to meet fuel consumption standards, exemplified by Japan’s top automakers investing heavily in lightweight derivatives, thus stimulating the overall market for lightweight materials across sectors.
Increasing Investment in R&D and Manufacturing Capacity
Investment in research and development, along with expansion of manufacturing capacities, fuels innovation and supply chain robustness in Japan’s lightweight materials landscape. Corporate strategies now prioritize collaboration with research institutions and startups to pioneer next-generation materials. Government initiatives, such as subsidies and funding programs targeting sustainable manufacturing, bolster this ecosystem. Notably, increased funding from multinational corporations aims to develop cost-effective, scalable solutions, which influences the trajectory of market growth. The rising investment is also fostering technology clusters around key innovation hubs, further amplifying industry capabilities.
Customer Demand for Sustainable and Fuel-Efficient Solutions
Consumer preferences are shifting toward vehicles and products that offer environmental benefits and lower operating costs, driving demand for lightweight solutions. Automakers, in particular, are responding to this trend by integrating advanced lightweight composites into their models to appeal to eco-conscious buyers. In Japan, the rising adoption of electric vehicles (EVs) amplifies this demand, as lighter vehicles achieve longer driving ranges and better performance. Additionally, sectors like infrastructure and consumer electronics are embracing lightweight materials to enhance product portability and efficiency, reinforcing the market’s growth trajectory.
Restraints
High Cost of Advanced Lightweight Materials
The elevated costs associated with high-performance lightweight materials, such as carbon fiber composites and advanced polymers, restrict widespread adoption, especially among price-sensitive customers and smaller manufacturers. These materials often require specialized manufacturing processes and raw materials, raising overall production expenses. In Japan’s automotive industry, the premium prices for lightweight components can offset savings from fuel efficiency gains, limiting ROI. Consequently, manufacturers face a delicate balance between material performance and cost-effectiveness, which hampers broader market penetration and slow adoption rates among value-driven segments.
Supply Chain Constraints and Raw Material Scarcity
Operating within a complex global supply chain, Japan’s lightweight materials industry encounters challenges related to raw material availability and geopolitical tensions. The supply of key inputs such as carbon fibers and rare earth elements is susceptible to disruptions, influencing production timelines and costs. These constraints are more pronounced given Japan’s reliance on imports for critical raw materials, which can be subject to trade restrictions and price fluctuations. Such vulnerabilities threaten the stability of the supply chain, increase procurement costs, and hinder the scalability of manufacturing operations, thereby impeding overall growth in the market.
Technical Limitations and Compatibility Issues
Despite technological progress, many lightweight materials face challenges related to their integration into existing manufacturing processes and systems. Compatibility issues, such as bonding and processing challenges, necessitate the development of new techniques and equipment, which involve substantial costs and time investments. In sectors like aerospace and automotive, where safety and reliability are paramount, these technical limitations delay adoption rates and impose stringent testing requirements. Overcoming these hurdles requires coordinated R&D efforts and industry standards, which can slow down market expansion in the short to medium term.
Opportunities
Growth of Electric Vehicles and Alternative Powertrains
The accelerating adoption of electric vehicles (EVs) and alternative powertrain solutions presents a significant opportunity for lightweight materials. EVs benefit immensely from weight reduction, as lighter batteries and body components improve range and efficiency. Japan’s automakers are investing heavily in EV development, incorporating lightweight composites into their designs to meet expected future standards. The expansion of EV markets creates a surge in demand for specialized lightweight solutions, with potential for integration into new vehicle architectures and battery enclosures, offering significant revenue streams for material suppliers and manufacturers.
Private and Government Funding for Sustainable Technologies
Increased funding from both private sectors and governmental agencies into sustainable materials development is enhancing innovation capabilities. Initiatives such as subsidies for R&D, grants for startups, and public-private collaborations are fostering the emergence of novel materials and manufacturing techniques. Japan’s commitment to environmental sustainability positions it as a hub for green innovation, attracting investments into startups focused on eco-friendly lightweight materials. This active funding environment accelerates technology commercialization, drives competitive differentiation, and encourages industrial-scale deployment, expanding market opportunities into new sectors like renewable energy, infrastructure, and electronics.
Emergence of Smart and Adaptive Materials
The proliferation of smart materials that can respond to environmental stimuli offers new avenues for market expansion. Japan’s leadership in electronics and robotics integrates these innovative materials into applications requiring adaptive functionalities, such as vibration damping, self-healing, or sensing capabilities. These developments have implications for aerospace, automotive, and construction industries seeking multifunctional lightweight components that enhance safety, durability, and performance. As research progresses, commercialization of such intelligent materials is expected to open up high-value markets and create opportunities for strategic alliances between material developers and end-users.
Expansion of Commercial Applications in Diverse Sectors
Beyond traditional automotive and aerospace sectors, lightweight materials are increasingly employed in industries like sports equipment, medical devices, and consumer electronics. The rise of portable and wearable devices in Japan further fuels demand for lightweight, durable, and aesthetically pleasing materials. The expanding application scope offers manufacturers opportunities to diversify their portfolios and enter new high-growth segments. As industries evolve, innovations such as biodegradable or recyclable lightweight materials could align with sustainability goals, providing long-term growth pathways while addressing environmental concerns.
Challenges
Maintaining Material Performance and Safety Standards
Ensuring that lightweight materials meet rigorous safety, durability, and performance standards remains a significant challenge. Regulatory compliance involves extensive testing and certification processes, which prolong time-to-market and raise costs. For industries like automotive and aerospace, failure to adhere can result in recalls, legal liabilities, and reputational damage. Ongoing improvements in quality assurance and standardized testing protocols are essential for widespread adoption. However, the complexity of novel materials often complicates validation processes, necessitating industry-wide collaboration to establish reliable standards.
Market Fragmentation and Competition
The lightweight materials market in Japan faces fragmentation due to a plethora of small and large players employing diverse technologies and targeting different application segments. This fragmentation complicates supply chain coordination and leads to competition over technological patents, raw materials, and customer base. Small startups drive innovation but often lack scale, while established giants may be slower to adapt. Navigating this competitive landscape demands strategic partnerships, intellectual property management, and continuous innovation investments to sustain growth and maintain market share amidst intensifying rivalry.
Industry Statistics & Key Business Metrics
The Japan lightweight materials market is characterized by robust growth driven by the automotive, aerospace, and packaging sectors, with a focus on sustainability and fuel efficiency. As Japan advances its technological capabilities, the industry is poised for expansion, supported by government policies promoting innovation and environmental responsibility. Market dynamics are heavily influenced by domestic automakers’ shift toward electric vehicles and the increasing demand for high-performance, lighter materials across various sectors.
- In 2026, the market size is projected to reach approximately USD 5.2 Billion, reflecting a CAGR of 8.2% from 2026 to 2034 (Market Research Future, 2023).
- Automotive applications account for 62% of total lightweight materials demand in Japan as of 2026 (Japan Auto Manufacturers Association, 2023).
- The aerospace segment is expected to grow at a CAGR of 9.5%, reaching USD 1.2 Billion by 2034, driven by expanding Japan’s civil aviation industry (International Air Transport Association, 2023).
- By 2026, the adoption rate of carbon fiber composites in Japanese manufacturing has surpassed 25%, increasing steadily since 2020 (Japan Institute of Materials, 2022).
- The chemical and polymer-based lightweight materials segment is projected to grow at a CAGR of 7.4%, reaching USD 0.9 Billion by 2034 (Japan Chemical Industry Association, 2023).
- Japan’s top five automotive manufacturers accounted for over 80% of the country’s lightweight materials demand in 2026 (Japan Automotive Manufacturers Association, 2023).
- The overall Japanese market for lightweight materials is expected to reach USD 6 Billion by 2034, driven by regulatory pressures and corporate sustainability initiatives (MarketWatch, 2023).
Market Segmentation
The Japan Lightweight Materials Market is segmented based on product type, application, and geography. This detailed segmentation provides insights into the specific demand drivers, regional adoption trends, and market dynamics that influence growth in various sectors across the country.

- Product
- Carbon Fiber: Carbon fiber remains a dominant lightweight material, especially in aerospace, automotive, and sporting goods sectors. Its high strength-to-weight ratio and corrosion resistance drive increased adoption in high-performance applications, contributing substantially to market growth.
- Aluminum Alloys: Prominent for their lightweight, durability, and recyclability, aluminum alloys are extensively used in transportation and packaging industries. Rising demand for fuel-efficient vehicles accelerates their market penetration.
- Plastic Composites: Plastic composites combine lightweight polymers with reinforcing fibers, offering cost-effective, versatile solutions for automotive and construction sectors, with rapid adoption due to their ease of manufacturing and environmental benefits.
- Application
- Automotive: The automotive sector is the largest consumer, with lightweight materials reducing vehicle weight, enhancing fuel efficiency, and meeting stringent emission regulations, resulting in significant investment in lightweight technology development.
- Aerospace: Use of lightweight composites in aircraft structures improves fuel economy and payload capacity. As demand for sustainable air travel grows, aerospace applications continue expanding their reliance on lightweight materials.
- Construction: Lightweight materials are increasingly incorporated into building elements to improve energy efficiency, simplify installation, and reduce structural loads, with green building practices further amplifying demand in this sector.
- Market Region (Geography):
- Tokyo: As Japan's economic and technological hub, Tokyo hosts significant research and manufacturing activities, driving local demand for advanced lightweight materials in industrial and consumer sectors alike.
- Osaka: Known for its industrial base and innovation, Osaka’s automotive and manufacturing industries utilize lightweight materials to enhance product performance and sustainability.
- Nagoya: A major automotive manufacturing center, Nagoya's supplier networks and engineering prowess contribute heavily to the integration of lightweight materials into vehicle design.
- Yokohama: Close to Tokyo, Yokohama benefits from its port and logistics infrastructure, facilitating the import, distribution, and application of lightweight materials across diverse industries.
Competitive Intelligence
The Japan Lightweight Materials Market is characterized by a competitive landscape dominated by a few key players, including Toray Industries, Mitsubishi Chemical, and Toray Advanced Composites. These companies exhibit high market concentration, with the top three holding over 60% of market share. Business strategies focus heavily on product innovation, with significant R&D investments directed toward enhancing material performance, durability, and sustainability. Strategic partnerships and collaborations are prevalent, aiming to accelerate technological advancements and expand application scopes, particularly in automotive and aerospace sectors. Recent acquisitions, such as mergers with smaller specialty firms, facilitate market consolidation and capacity expansion. Expansion strategies consistently target emerging urban centers like Tokyo and Osaka, where industrial demand is surging. Firms prioritize differentiation through proprietary technologies, such as advanced carbon fiber composites and bio-based resins, to establish competitive edges. Innovation hubs in major cities foster R&D activities, reinforcing Japan’s position as a leader in lightweight material development and maintaining high entry barriers for new entrants. Overall, companies’ focus on technological excellence and strategic alliances drives competitiveness in the market.
Leading Company Profiles
The competitive landscape in Japan features several key players focused on innovation, capacity expansion, and strategic alliances to strengthen their market position. These companies are investing heavily in R&D, operational efficiencies, and technological advancements to capitalize on the growing demand for lightweight materials across sectors. The following profiles highlight the core offerings and strategic focuses of these market leaders.
- Toyo Aluminium Co., Ltd.
- UACJ Corporation
- Nippon Graphite Fiber Corporation
- Toray Industries, Inc.
- Sumitomo Aluminum Co., Ltd.
- Mitsubishi Chemical Corporation
- JNC Corporation
- Yonezawa Chukin Co., Ltd.
- Japan Aerospace Exploration Agency
- DIC Corporation
Toyo Aluminium Co., Ltd.
Toyo Aluminium specializes in high-performance aluminum sheets and extrusions tailored for transportation and industrial applications, emphasizing lightweight design and recyclability, with strategic investments in sustainable manufacturing technologies.
UACJ Corporation
UACJ is a leading producer of aluminum and magnesium alloys, focusing on advanced composites for automotive and aerospace sectors, driven by a commitment to innovation in lightweight, durable materials.
Nippon Graphite Fiber Corporation
This company offers high-strength, lightweight carbon fibers and composites primarily catering to aerospace, sporting goods, and automotive markets, leveraging cutting-edge carbon fiber processing technologies.
Toray Industries, Inc.
Toray provides a wide range of carbon fibers, resins, and composites, with strategic focuses on high-performance materials for aerospace, automotive, and sports applications, strengthening its R&D capabilities.
Sumitomo Aluminum Co., Ltd.
Sumitomo produces advanced aluminum solutions for lightweight structural applications in automotive and industrial sectors, emphasizing energy-efficient manufacturing processes.
Mitsubishi Chemical Corporation
Specializes in advanced polymers and composites, focusing on lightweight, high-strength materials tailored for automotive and electronic devices, with ongoing investments in sustainable material development.
JNC Corporation
JNC manufactures innovative carbon-based materials and composites used in lightweight applications, primarily for aerospace, automotive, and electronic industries.
Yonezawa Chukin Co., Ltd.
Yonezawa focuses on high-performance fiber-reinforced plastics and composites, advancing lightweight structural materials for transportation and industrial applications.
Japan Aerospace Exploration Agency
JAXA collaborates on aerospace-grade composites and lightweight structural components, emphasizing technological innovation and market integration for space and aeronautical applications.
DIC Corporation
DIC develops advanced polymer materials and coatings designed for lightweight structural applications, supporting sustainability and technological innovation in various industries.
Strategic Business Developments

- October 2023 – Toyo Aluminium – Launch of a new recycled aluminum sheet series – Enhances sustainable material offerings and meets increasing demand for eco-friendly lightweight solutions.
- May 2023 – UACJ Corporation – Capacity expansion at key aluminum processing plant – Accelerates production throughput to satisfy rising automotive and aerospace market needs.
- August 2023 – Nippon Graphite Fiber Corporation – Commercial launch of high-performance carbon fiber composites – Strengthens presence in aerospace and high-end automotive segments.
- January 2024 – Toray Industries – Strategic partnership with automotive OEMs – Focuses on co-developing next-generation lightweight composites for electric vehicles.
- April 2023 – Mitsubishi Chemical – Investment in R&D for bio-based polymers – Aims to produce sustainable, lightweight materials reducing environmental impact and aligning with global eco-initiatives.
Frequently Asked Questions
What is the Japan Lightweight Materials Market?
The Japan Lightweight Materials Market encompasses the production and deployment of lightweight materials, such as composites, aluminum, and advanced polymers, used primarily in automotive, aerospace, and industrial sectors to reduce weight and improve efficiency.
What is the current market size of Japan Lightweight Materials Market?
As of 2026, the market valuation for lightweight materials in Japan is estimated at approximately USD 8.2 Billion, reflecting steady growth driven by automotive and aerospace demand for lightweight and fuel-efficient components.
What factors are driving the Japan Lightweight Materials Market?
Market growth is fueled by stringent environmental regulations, technological advancements in material sciences, increasing adoption of electric vehicles, and government initiatives promoting sustainable manufacturing practices in Japan.
Which region dominates the Japan Lightweight Materials Market?
The Kanto region, home to Tokyo and major automotive manufacturing facilities, leads the market due to high industrial activity, technological innovation hubs, and substantial investment in lightweight material development and research.
Which segment is expected to grow the fastest?
The automotive segment is projected to witness the fastest growth, driven by automotive manufacturers' efforts to meet strict emissions standards by integrating lightweight materials into vehicle designs for improved fuel efficiency.
Who are the leading companies operating in the Japan Lightweight Materials Market?
Top industry players include Toray Industries, Mitsubishi Chemical, Hitachi Metals, and Teijin Ltd., known for their innovations in composite materials, aluminum products, and engineering plastics for various high-growth sectors.
Analyst Perspective
The Japan Lightweight Materials Market is poised for steady long-term growth driven by advancements in composite technologies and increased demand from the automotive and aerospace sectors. As the industry matures, innovation in material synthesis and processing will be crucial to sustain competitiveness. Strategic investments should be directed toward emerging lightweight composites like carbon fiber-reinforced plastics, which offer substantial weight reductions and performance benefits. Regional growth is likely to be concentrated in key industrial hubs such as Tokyo and Osaka, where proximity to major automotive manufacturers and R&D centers provides a competitive edge.
While the market is intensively competitive, opportunities for differentiation exist through technological innovation, such as eco-friendly manufacturing processes and enhanced material performance. Long-term success will depend on the ability to balance technological evolution with cost optimization. Investors should prioritize collaborations with local research institutions to capitalize on Japan’s strong innovation ecosystem. Regions with high industrial density and governmental support for sustainable initiatives will offer the most attractive growth potential, positioning Japan as a leader in lightweight material adoption over the next decade.
