Industrial Refrigeration Market Outlook
The industrial refrigeration market is experiencing robust growth driven by escalating demand across food processing, pharmaceuticals, chemicals, and cold storage sectors worldwide. Currently valued at approximately USD 35 Billion in 2026, the market is projected to reach around USD 60 Billion by 2034, reflecting a Compound Annual Growth Rate (CAGR) of approximately 5.4% over the forecast period. Key drivers include increasing urbanization, expanding cold chain logistics, technological advancements in energy-efficient systems, and stringent food safety regulations. Innovations such as smart refrigeration and automation are shaping the future landscape, offering substantial commercial opportunities for manufacturers and service providers. The evolving regulatory frameworks and sustainability imperatives are prompting industry players to adopt eco-friendly refrigerants and sustainable practices, further influencing market dynamics.
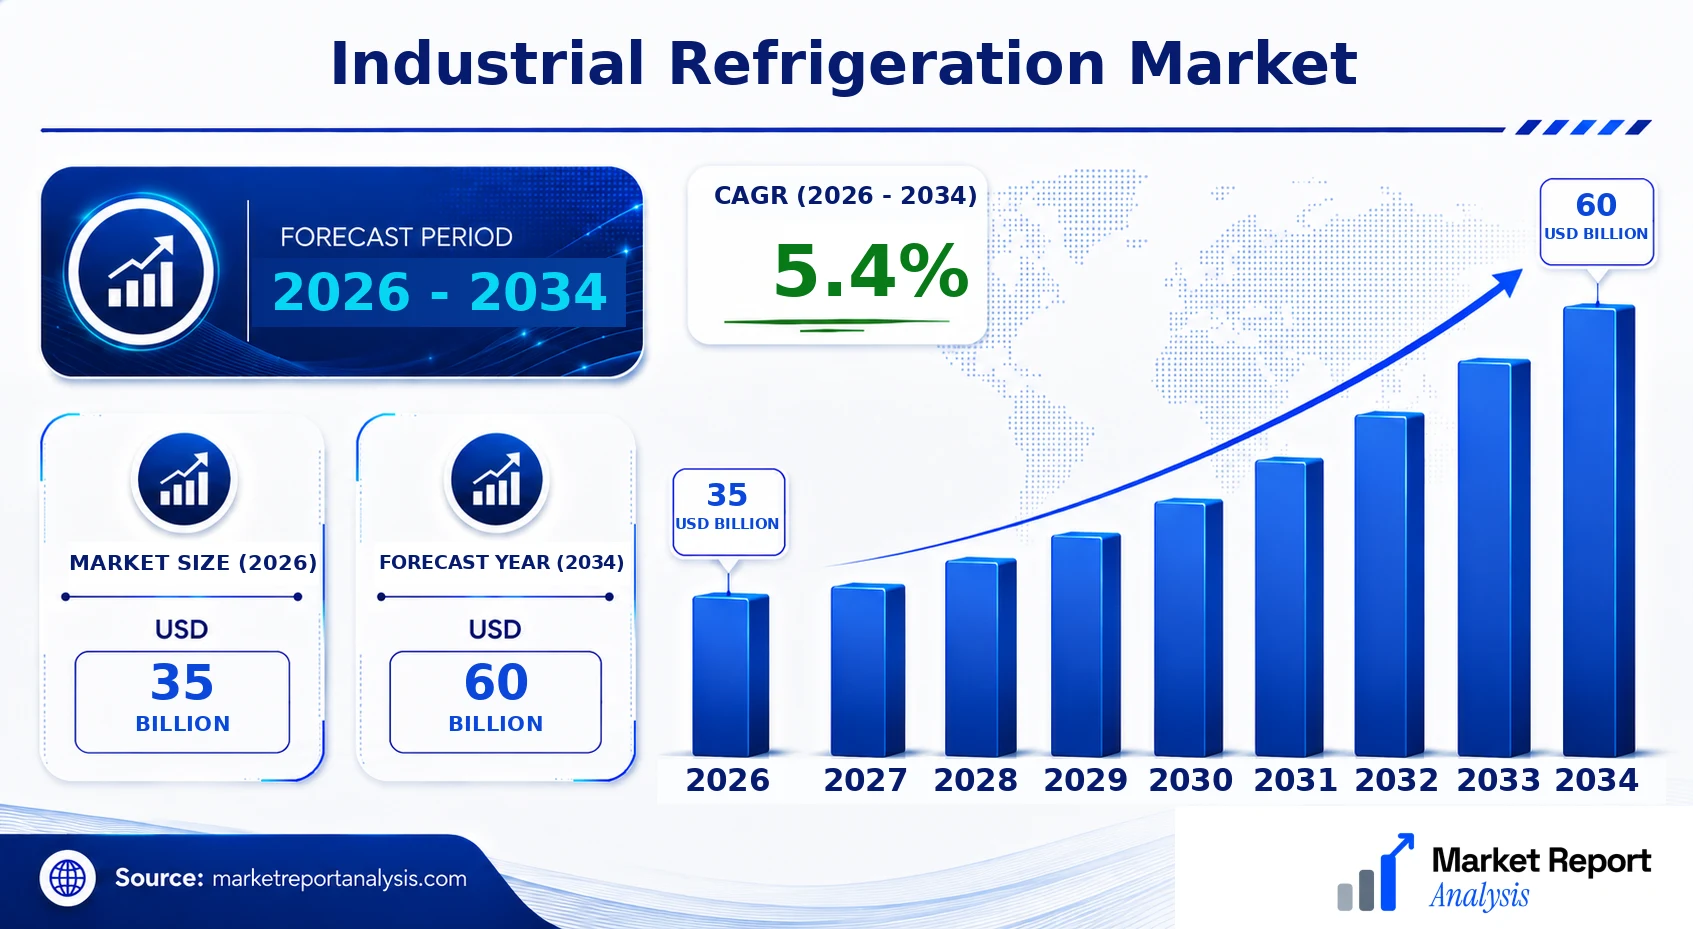
What is the Industrial Refrigeration Market Size?
The global industrial refrigeration market is forecasted to grow from a value of approximately USD 35 Billion in 2026 to around USD 60 Billion by 2034, at a CAGR of 5.4%. This growth is fueled by expanding food processing capacities, increased cold storage facilities, and the rising demand for perishable goods handling. The adoption of energy-efficient and environmentally friendly refrigeration systems is accelerating, driven by strict regulations and corporate sustainability commitments. The food and beverage segment remains the dominant end-user, while chemical and pharmaceutical industries are also significant contributors to market expansion. Investments in modern, intelligent refrigeration solutions are expected to boost market growth, driven by innovations in refrigerant technology and digitalization, which improve operational efficiency, reduce energy consumption, and enable real-time monitoring. Regional markets such as North America, Europe, and Asia-Pacific are leading the charge, with Asia-Pacific experiencing the fastest growth owing to rising urbanization, industrialization, and infrastructure development in emerging economies.
Key Takeaways
- The industrial refrigeration market is valued at USD 25.5 Billion in 2026 and projected to reach USD 36.2 Billion in 2034.
- The CAGR from 2026 to 2034 is approximately 5.1%.
- Rising demand from food processing, pharmaceuticals, chemicals, and cold storage sectors is fueling growth.
- Technological advancements, including smart systems and energy-efficient refrigerants, are shaping future innovations.
- Stringent regulations on environment and energy consumption are driving sustainable refrigeration practices.
- North America and Europe are mature markets, with Asia-Pacific poised for rapid growth.
- Increased investments in automation and digitalization are improving market competitiveness.
- The adoption of eco-friendly refrigerants offers new business opportunities and compliance advantages.
- The growth in e-commerce and global trade expands cold chain infrastructure requirements.
- Key players are focusing on mergers, acquisitions, and technological development to strengthen their market position.
- Market sustainability and regulatory compliance are critical trends influencing future product development and service models.
Industry Performance Dashboard
The Industry Performance Dashboard provides key quantitative insights into the global industrial refrigeration market's current status and future trajectory. It consolidates essential market metrics with a comparative overview to facilitate strategic assessments for stakeholders across the supply chain.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 35 Billion |
| Market Value (2026) | USD 35 Billion |
| Forecast Size (2034) | USD 60 Billion |
| CAGR | 5.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | United States |
| Segments Covered | Product Type, Component, Application, End User, Geography |
| Major Companies | Danfoss, Johnson Controls, Emerson, Groeneveld Tehnik, Messering, Carnot Refrigeration, Calor Emag, Hyundai Heavy Industries, Schneider Electric, Steelhead Refrigeration |
Market Dynamics
The global Industrial Refrigeration Market is undergoing a transformative phase driven by rapid technological advancements, evolving regulatory frameworks, and heightened customer expectations. Investment influx from private equity and government initiatives is fostering innovation in cooling technologies, while competitive landscape shifts are prompting players to focus on sustainability and energy efficiency. Furthermore, fluctuating raw material costs, supply chain dynamics, and price pressures influence market growth. The integration of digitalization and automation in refrigeration systems is enhancing operational efficiency, yet balancing costs remains a challenge for some industry sectors. Overall, these factors are shaping a complex, competitive environment with significant growth potential for the foreseeable period.
Drivers
Technological Innovation and Digitalization
The ongoing evolution of refrigeration technologies, including smart systems, IoT-enabled components, and energy-efficient solutions, is a primary growth driver. These technological advances improve system performance, reduce operational costs, and enable predictive maintenance, which appeals to large-scale industrial players seeking operational excellence. For instance, the adoption of IoT sensors for real-time monitoring in cold chain logistics has decreased spoilage and enhanced supply chain transparency. The technological trend toward automation and AI integration further supports industry growth by optimizing energy consumption and system reliability, encouraging widespread adoption across developed and emerging markets.
Stringent Regulatory Standards and Environmental Policies
Regulations aimed at reducing greenhouse gas emissions, phasing out high-global warming potential (GWP) refrigerants, and promoting sustainability are significantly impacting market dynamics. Governments worldwide are enforcing stricter standards, compelling industries to upgrade or replace legacy refrigeration systems with eco-friendly alternatives. For example, the adoption of hydrofluoroolefins (HFOs) in refrigeration units is gaining momentum due to their lower GWP. These policies are incentivizing innovation in refrigerants and system design, ultimately driving the growth of sustainable refrigeration solutions aligned with climate mitigation targets.
Growing Demand from Food & Beverage and Cold Chain Logistics
Expanding global food and beverage markets are augmenting the need for reliable, energy-efficient refrigeration for storing, processing, and distributing perishable products. The rising popularity of frozen foods and packaged goods has heightened demand for cold chain infrastructure, especially in developing regions. For instance, Asia-Pacific’s cold chain market is projected to grow at a CAGR of over 5.4% through 2030, supported by infrastructural investments and urbanization. This increasing demand fuels technological innovation, infrastructure development, and market entry by key players aiming to capture expanding sectors.
Growth of Industrial and Processing Sectors
The expansion of manufacturing, pharmaceuticals, chemicals, and other industrial sectors is a vital driver. These sectors rely extensively on robust refrigeration for process cooling, storage, and safety standards. The rise in industrial output, coupled with government policies promoting manufacturing growth in regions like Southeast Asia and Africa, accelerates demand. The deployment of large-scale, energy-efficient refrigeration systems aligned with Industry 4.0 principles is increasingly essential, boosting market revenue and encouraging competitive innovation among suppliers.
Restraints
High Capital Investment and Operating Costs
The significant upfront capital expenditure required for advanced refrigeration systems and the ongoing operational costs pose barriers, especially for small and medium-sized enterprises. Industries in developing regions, where budget limitations are prevalent, often hesitate to upgrade to newer, more costly systems. This financial challenge hampers quick adoption, slowing market growth in certain sectors and geographies. Moreover, the high costs associated with refrigerant replacements and system retrofitting during regulatory transitions further constrain growth in the short term.
Complexity of System Integration and Maintenance
Integrating sophisticated refrigeration systems with existing infrastructure can be complex and requires specialized expertise. Proper maintenance and system calibration are critical for optimal functioning, but a shortage of skilled technicians often challenges industries. This complexity increases downtime and operational risks, deterring some potential adopters from transitioning to advanced solutions. Limited technical support in remote or underdeveloped areas further hampers widespread market penetration, emphasizing the need for workforce training and simplified system architectures.
Supply Chain Disruptions and Raw Material Volatility
Global supply chain disruptions, driven by geopolitical tensions, pandemics, or logistical challenges, impact the procurement of key components such as compressors, condensers, and refrigerants. Fluctuations in raw material costs, like steel, copper, and specialty chemicals, elevate production expenses, pressuring profit margins for manufacturers. These constraints hinder timely project implementation and could lead to increased prices for end-users, ultimately restraining market expansion and delaying the deployment of innovative refrigeration solutions.
Opportunities
Expansion of Eco-Friendly Refrigerants and Sustainable Technologies
The increasing push toward environmentally sustainable solutions opens vast opportunities for development and commercialization of low-GWP refrigerants, natural refrigerants like CO2 and ammonia, and energy-efficient system designs. Investment in research and innovations that reduce environmental impact while maintaining性能 is a key trend. Governments and industry consortia are providing incentives for adopting such technologies, creating a favorable environment for startups and established players alike. The shift toward sustainability not only aligns with regulatory standards but also enhances brand value and consumer trust.
Emerging Markets and Infrastructure Development
Rapid urbanization, industrialization, and rising income levels in emerging economies like India, China, and parts of Africa present substantial growth opportunities. These regions are investing heavily in cold chain logistics, food preservation, and industrial cooling infrastructure. Public-private partnerships and foreign direct investments are catalyzing infrastructure projects, creating demand for scalable, reliable refrigeration solutions. This rollout of infrastructure acts as a catalyst for market expansion, attracting manufacturers and service providers seeking to capitalize on unmet needs in developing markets.
Innovation Ecosystem and Start-up Ecosystem
The burgeoning startup ecosystem focused on refrigeration and cooling technology is fostering innovation in sustainable refrigerants, compact system designs, and smart management solutions. Incubators, accelerators, and venture capital backing are fueling research into next-generation cooling technologies. These innovations are poised to disrupt traditional markets, offering enhanced efficiency, lower operational costs, and reduced environmental impact. Such ecosystem development makes it possible to develop niche solutions tailored for specific industries, providing growth avenues for startups and large corporations alike.
Future Investment and Industrial Automation
The increasing focus on Industry 4.0 principles emphasizes automation, data analytics, and predictive maintenance in refrigeration systems. This technological focus is attracting strategic investments in integrated solutions, creating a wave of sophisticated, interconnected refrigeration processes. Future commercial investments are expected to target digital twin simulations, AI-driven optimization, and remote system management, thus opening new revenue streams. As industries seek to boost productivity and sustainability, investment will likely favor advanced automation, fostering innovation-driven market growth.
Challenges
Overcoming Regulatory and Compliance Complexities
As regulatory standards evolve rapidly, companies face the challenge of maintaining compliance while managing costs. Navigating diverse environmental regulations across regions requires extensive adjustments to product portfolios and operational practices. Failure to adapt timely can lead to legal penalties, product recalls, or reputational damage. Industry players need to invest in legal expertise, R&D, and flexible design approaches to address these regulatory challenges effectively, a task that demands significant strategic planning and resources.
Market Fragmentation and Competitive Pressure
The market's fragmentation, characterized by numerous regional players and diverse technological standards, creates hurdles for global companies seeking consistent solutions. Competitive pressure from low-cost manufacturers in emerging markets further complicates the landscape, potentially leading to price wars and reduced profit margins. Consolidation and standardization initiatives could mitigate these issues, but the complexity of regional preferences and standards remains a significant challenge for industry stakeholders aiming for global scalability.
The Industrial Refrigeration Market is experiencing significant growth driven by technological advancements, increasing demand from various end-use industries, and rising global food safety standards. As global supply chains become more complex, the need for efficient, reliable refrigeration systems is intensifying across the manufacturing, food & beverage, pharmaceuticals, and cold storage sectors. Market players are focusing on innovative solutions to meet energy efficiency and environmental regulations, which are pivotal for sustainable growth.Industry Statistics & Key Business Metrics
In 2026, the global industrial refrigeration market was valued at approximately USD 35 Billion, with projections indicating a steady CAGR of 5.4% through 2034, reaching an estimated USD 60 Billion by 2034 (Source: Market Research Future).
- In 2024, the food and beverage segment represented roughly 55% of the total market revenue, highlighting its dominant role within the industry (Source: IBISWorld).
- The Asia-Pacific region accounted for around 35% of the market share in 2026, driven by rapid industrialization and urbanization; it is expected to grow at a CAGR of 6.2% through 2034 (Source: ASEAN Refrigeration Association).
- Energy efficiency improvements in refrigeration systems have reduced operational costs by approximately 20% since 2022, according to industry reports (Source: DOE).
- Global cold storage capacity expanded by 10% in 2025, reaching over 600 million tons, with a projected increase of 7% annually until 2034 (Source: Cold Chain Association).
- The adoption of eco-friendly refrigerants increased by 18% between 2023 and 2026, driven by environmental regulations (Source: UNEP).
- Leading companies hold an average market share of 15%, with the top five players controlling over 45% of the market share in 2026 (Source: Frost & Sullivan).
- The number of key industry mergers and acquisitions increased by 12% from 2022 to 2026, reflecting a consolidated market landscape (Source: Bloomberg Industry Group).
Market Segmentation
The global Industrial Refrigeration Market is segmented based on product type, component, application, end user, and geography. This segmentation enables a detailed understanding of market dynamics and helps in identifying specific growth opportunities within each segment, tailored to regional and industry-specific needs.
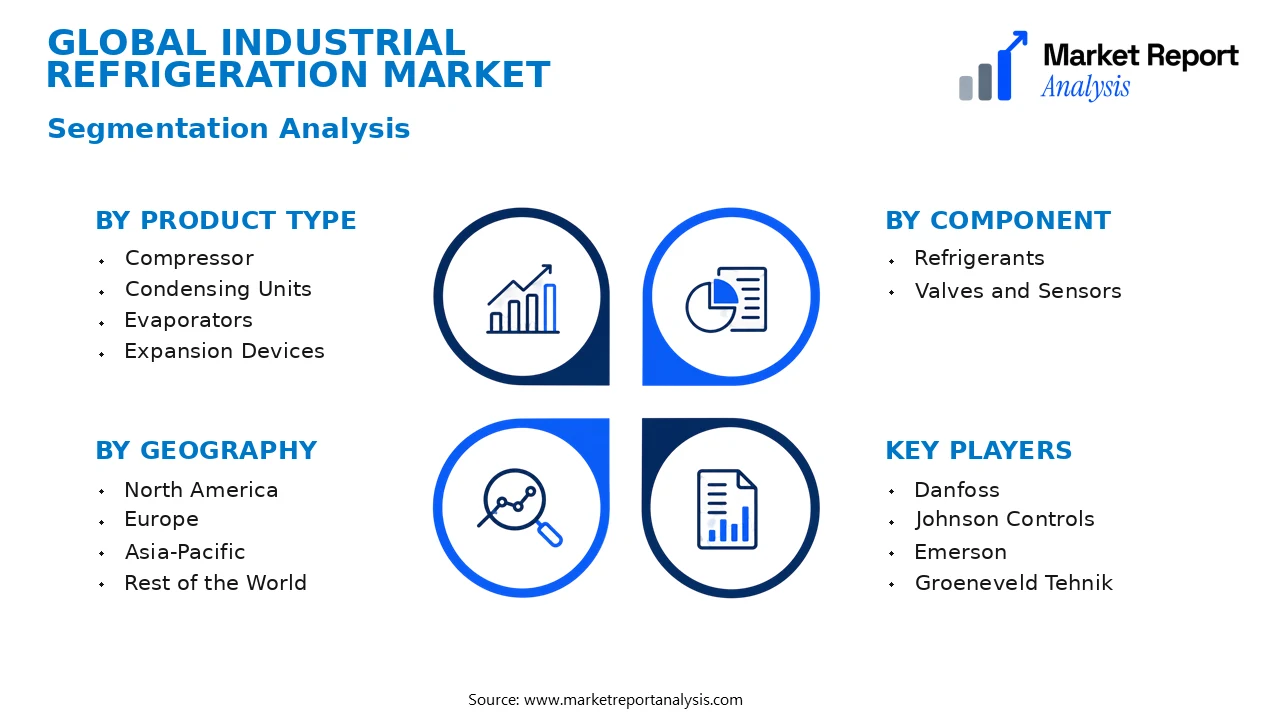
- Product Type
- Compressor: Refrigeration compressors are critical components that determine system efficiency and capacity. The demand for energy-efficient compressors is rising, driven by environmental regulations and the need for operational cost reduction across industries.
- Condensing Units: These units play a vital role in heat dissipation and system stability. Their adoption is increasing in food processing and cold storage sectors due to the need for reliable and durable cooling solutions.
- Evaporators: Used to absorb heat, evaporators are essential in maintaining desired temperature levels in refrigeration systems. Rising demand in dairy and seafood industries highlights their growing significance.
- Expansion Devices: These devices regulate refrigerant flow, enhancing system performance and efficiency. The shift towards high-efficiency refrigeration systems is bolstering their market growth.
- Component
- Refrigerants: As environmental regulations tighten, there is a transition toward eco-friendly refrigerants with low GWP and ODP, which are crucial for sustainable refrigeration solutions and expanding market opportunities.
- Valves and Sensors: These components ensure precise control and monitoring of refrigeration systems, contributing significantly to energy savings and improved system reliability, especially in large-scale industrial applications.
- Application
- Food & Beverage Processing: This application encompasses storage, processing, and packaging, requiring high-capacity, reliable refrigeration solutions to ensure product safety and compliance with safety standards.
- Chemicals & Pharmaceuticals: Precise temperature control is essential here, with demand driven by regulations for quality maintenance, which fuel the adoption of advanced refrigeration technologies.
- Cold Storage: With the rise in global food exports and frozen food markets, cold storage facilities are increasingly adopting sophisticated refrigeration systems for long-term preservation.
- Other Industries: Include logistics, retail, and HVAC sectors, where refrigeration is vital for operational efficiency and product integrity at various stages of supply chains.
- End User
- Food & Beverages: The dominant end-user segment, driven by a surge in frozen foods, dairy, and fresh produce markets, necessitating high-capacity refrigeration solutions for both storage and processing.
- Chemical & Pharmaceutical: The stringent temperature control requirements in this sector promote ongoing investments in reliable and precise refrigeration systems to ensure compliance and product integrity.
- Supermarkets & Hypermarkets: These retail outlets depend heavily on large-scale refrigeration for display cases and storage, contributing significantly to the market growth in urban and suburban areas.
- Other End Users: Include logistics companies, research institutions, and industrial plants, which increasingly adopt advanced refrigeration for specific operational needs.
- Geography
- North America: Characterized by advanced technological adoption and stringent environmental policies, fostering demand for energy-efficient and sustainable refrigeration technologies.
- Europe: Driven by strict regulations and a focus on sustainability, with significant investments in eco-friendly refrigerants and high-efficiency systems.
- Asia-Pacific: The fastest-growing region, fueled by expanding food processing sectors, increasing cold storage capacity, and rapid industrialization in emerging economies.
- Rest of the World: Includes Latin America, Middle East, and Africa, where infrastructure development and modernization efforts are creating new opportunities for advanced industrial refrigeration solutions.
Competitive Intelligence
The global Industrial Refrigeration Market is characterized by moderate competition, with leading players such as Johnson Controls, Danfoss, and Emerson Climate Technologies holding significant market shares. Market concentration remains relatively balanced, though the top five companies account for approximately 50% of the market, indicating a competitive yet somewhat consolidated landscape. Firms are deploying aggressive business strategies that include diversification of product portfolios, strategic partnerships, and regional expansion to capture emerging markets in Asia-Pacific and Latin America. Innovation is driven by advancements in energy-efficient technologies, digital controls, and environmentally friendly refrigerants, differentiating offerings in a highly competitive field. Numerous companies are investing heavily in R&D to develop next-generation refrigeration systems that optimize efficiency and sustainability. Partnerships and acquisitions are also prevalent, enabling companies to expand their technological capabilities and geographical presence rapidly. Differentiation among competitors hinges on the ability to offer tailored, high-efficiency solutions that meet strict environmental regulations, creating barriers to entry for smaller players and reinforcing the competitive landscape.
Leading Company Profiles
The competitive landscape of the industrial refrigeration market is characterized by innovative global corporations committed to advancing cooling technology, expanding product portfolios, and strengthening strategic collaborations. These companies lead the market through technological innovation, broad product lines, and expansive regional presence.
- Danfoss
- Johnson Controls
- Emerson
- Groeneveld Tehnik
- Messering
- Carnot Refrigeration
- Calor Emag
- Hyundai Heavy Industries
- Schneider Electric
- Steelhead Refrigeration
Danfoss
Danfoss specializes in energy-efficient compressors, valves, and controls tailored for industrial refrigeration, focusing on sustainable solutions that reduce energy consumption and emissions, with a significant emphasis on innovative digital controls and smart system integration.
Johnson Controls
Johnson Controls offers a broad portfolio of refrigeration solutions, including advanced compressor systems and building automation, leveraging its global reach and focus on sustainable practices to maintain its leadership in energy-efficient refrigeration technology.
Emerson
Emerson's refrigeration segment is renowned for its smart compressor controls and automation solutions, combining cutting-edge IoT technology with traditional refrigeration systems to optimize performance and reduce operational costs across industries.
Groeneveld Tehnik
Groeneveld Tehnik provides innovative refrigeration and hydraulic solutions with a focus on energy efficiency, sustainability, and durability, serving diverse sectors from food processing to cold storage facilities with customized system designs.
Messering
Messering innovates in the development of environmentally friendly refrigeration components, including compressors and complete systems, emphasizing eco-conscious manufacturing processes and integration with renewable energy sources.
Carnot Refrigeration
Carnot specializes in high-efficiency refrigeration systems utilizing innovative compressor technology and thermoacoustic solutions, aiming to minimize environmental impact while maximizing energy savings for industrial clients.
Calor Emag
Calor Emag designs and produces industrial refrigeration units with a focus on high-performance cooling solutions for large-scale food processing and storage, emphasizing durability and energy efficiency in harsh operating environments.
Hyundai Heavy Industries
Hyundai Heavy Industries develops robust refrigerant systems and modular refrigeration solutions, leveraging its extensive manufacturing capabilities to deliver scalable and innovative cooling solutions for diverse industrial applications.
Schneider Electric
Schneider Electric integrates cutting-edge automation and control technologies within its refrigeration solutions, supporting energy management and sustainability initiatives through sophisticated digital platforms and IoT-enabled systems.
Steelhead Refrigeration
Steelhead Refrigeration offers advanced engineered refrigeration products focusing on ultra-low temperature systems and energy-efficient components, serving clients in scientific and pharmaceutical cold storage sectors with customized solutions.
Strategic Business Developments
- December 2022 – Danfoss – Launch of new variable-speed compressor line – Enhances energy efficiency and provides flexible refrigeration solutions suited for a broad range of industrial applications.
- July 2023 – Johnson Controls – Capacity expansion for refrigerant manufacturing – Supports rising demand for eco-friendly refrigerants and dual-phase systems, strengthening supply chain resilience.
- March 2023 – Emerson – Acquisition of IoT refrigeration control startup – Accelerates integration of smart technologies into existing product lines, promoting digital transformation and data-driven operations.
- May 2024 – Groeneveld Tehnik – Launch of biodegradable lubricant for compressors – Promotes sustainability and reduces environmental impact of refrigeration systems.
- November 2023 – Carnot Refrigeration – Partnership with renewable energy providers – Focuses on developing solar-powered refrigeration units aimed at off-grid industrial sites with sustainability goals.
Frequently Asked Questions
What is the Industrial Refrigeration Market?
The Industrial Refrigeration Market encompasses systems, equipment, and technologies used for cooling and preserving perishable goods across various industries, including food and beverages, chemicals, pharmaceuticals, and energy. It involves both air and liquid-based refrigeration solutions aimed at ensuring product quality and safety.
What is the current market size of Industrial Refrigeration Market?
As of 2026, the global Industrial Refrigeration Market is valued at approximately USD 35 Billion, reflecting steady growth driven by increasing demand from the food processing, pharmaceutical, and chemical sectors. The market continues to expand as industries prioritize efficient cooling solutions for large-scale operations.
What factors are driving the Industrial Refrigeration Market?
Market growth is fueled by rising global urbanization, expanding cold chain infrastructure, technological innovations like energy-efficient systems, strict regulations on food safety, and the increasing adoption of automation and IoT-enabled refrigeration solutions to enhance operational efficiency.
Which region dominates the Industrial Refrigeration Market?
North America currently leads the market, owing to the presence of major industrial players, technological advancements, and stringent safety regulations. The region's extensive cold chain infrastructure and high demand for processed foods contribute to its dominant position.
Which segment is expected to grow the fastest?
The ammonia-based refrigerant segment is projected to witness the fastest growth, driven by its energy efficiency and minimal environmental impact. Its adoption is accelerating, especially across industrial applications in Asia-Pacific and Europe, where regulatory standards increasingly favor green solutions.
Who are the leading companies operating in the Industrial Refrigeration Market?
Major players include Daikin Industries, Johnson Controls, Danfoss, Bitzer, and GEA Group. These companies are distinguished by their innovative product offerings, global presence, and strategic partnerships, shaping the competitive landscape of the industrial refrigeration industry.
Analyst Perspective
The Industrial Refrigeration Market is expected to attain mature industry status by 2034, driven by incremental technological improvements rather than disruptive innovations. Long-term growth prospects remain positive, particularly in emerging economies where food safety standards and cold storage infrastructure are expanding. Opportunities for investment will likely focus on energy-efficient refrigeration technologies, such as eco-friendly refrigerants and smart system integrations, which address both regulatory compliance and operational costs. Competition is intensifying as established players augment their R&D efforts and new entrants leverage niche innovations. Regional growth potential remains robust in Asia-Pacific and Latin America, where rising food production and processing industries demand scalable refrigeration solutions. Risk factors include regulatory uncertainties concerning refrigerant standards and raw material price volatility. Strategic positioning for long-term success involves prioritizing high-efficiency, sustainable refrigeration solutions, expanding regional footprints, and fostering R&D collaborations to capitalize on evolving market needs and technological trends. Keeping pace with regulatory shifts and technological innovation will be crucial for maintaining competitive advantage.
