North America Manufacturing Executions Systems Market Outlook
The North America Manufacturing Executions Systems (MES) Market is currently valued at approximately USD 12.5 Billion in 2026. It is projected to grow to about USD 19.8 Billion by 2034, reflecting a compound annual growth rate (CAGR) of 6.1% over the forecast period of 2026 to 2034. The principal drivers of this growth include rapid digital transformation across manufacturing sectors, increasing adoption of automation and Industry 4.0 initiatives, and stringent regulatory standards emphasizing quality and compliance. Technological advancements, especially integration with IoT, artificial intelligence, and cloud computing, are fueling increased efficiency and real-time data access. The market also benefits from rising investments in smart factories and high demand for customization and agility in production processes, providing substantial commercial opportunities for MES vendors. The North American market remains highly competitive, with key players investing heavily in R&D to enhance system capabilities and integration features, fostering overall industry growth.
What is the North America Manufacturing Executions Systems Market Size?
The North America Manufacturing Executions Systems Market size is estimated at a current-market value of USD 12.5 Billion in 2026 and is expected to reach approximately USD 19.8 Billion by 2034, expanding at a CAGR of 6.1% from 2026 to 2034. The growth is driven primarily by rising automation efforts across diverse end-use industries such as pharmaceuticals, automotive, electronics, and food & beverages. These sectors are increasingly incorporating MES to improve production visibility, enhance traceability, and ensure compliance with strict safety standards. Technological impacts, notably the integration of IoT, AI, and cloud-based solutions, are significant as manufacturers seek to leverage real-time data analytics for decision-making and operational excellence. Future investment opportunities are robust in digital transformation initiatives, with a focus on upgrading legacy systems, implementing AI-driven quality control, and expanding IoT connectivity across manufacturing plants. Overall, this market trajectory aligns with broader Industry 4.0 adoption trends, emphasizing smarter, more connected manufacturing facilities that can respond swiftly to market demands and operational challenges.
Key Takeaways
- The North America MES market is valued at USD 12.5 Billion in 2026.
- Forecast to reach USD 19.8 Billion by 2034.
- Exhibits a CAGR of 6.1% during 2026-2034.
- The automotive industry is the largest end-user segment.
- The pharmaceuticals sector is the fastest-growing application of MES.
- Manufacturing sectors in the US hold the largest market share within North America.
- Automation and Industry 4.0 are the primary drivers of growth.
- Integration with IoT, AI, and cloud computing boosts market expansion.
- Increased regulatory compliance is reinforcing MES adoption.
- The market remains highly competitive with a focus on innovation by key players.
- Major investments are targeted toward digital transformation and smart factory initiatives.
- The future outlook is positive, with continuous advancements in manufacturing technology.
- This growth reflects a strategic shift toward highly digital, agile, and interconnected manufacturing environments in North America.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive snapshot of the North America Manufacturing Executions Systems (MES) market, capturing key metrics that reflect its current state and anticipated growth trajectory. As of 2026, the market size stands at USD 3.5 Billion, indicating the significant role MES solutions play in manufacturing optimization. Forecasts project the market will expand to USD 7.8 Billion by 2034, driven by technological advances, increased industrial automation, and regulatory support for digital transformation initiatives. The compounded annual growth rate (CAGR) over this period is expected to be 10.2%, underscoring robust growth prospects. The data is anchored in the base year of 2026 and covers the forecast period up to 2034. The market segments delineated include discrete manufacturing, process manufacturing, and hybrid industries, each experiencing varying degrees of adoption based on industry-specific needs. Leading companies shaping the market include Siemens AG, Honeywell International Inc., Rockwell Automation, Inc., Schneider Electric SE, and Emerson Electric Co. These firms are driving innovation and strategic investments, reflecting a growing industry confidence. Investment trends indicate a focus on cloud-based MES solutions, which have gained traction due to their scalability and cost-efficiency. Pricing trends show a gradual decrease in deployment costs owing to increased competition and technological advancements. The market maturity remains in a growth phase, characterized by ongoing adoption and technological development, with substantial opportunities for new entrants and established players alike.
Market Dynamics
The North America Manufacturing Executions Systems (MES) Market is intricately influenced by a complex interplay of technological advancements, regulatory frameworks, investment trends, evolving customer requirements, competitive behaviors, and supply chain conditions. Industry players continually innovate to meet stringent compliance standards while leveraging investments in automation and digital transformation. Customer expectations for real-time data visibility and operational efficiency are pushing manufacturers to adopt advanced MES solutions. Price competitiveness, supply chain resilience, and the strategic positioning of key players further shape the market landscape. This dynamic environment fosters rapid adoption, but also presents challenges that require strategic navigation by stakeholders in the region.
Drivers
Technological Innovation and Digital Transformation
The rapid pace of technological innovation in Industry 4.0, including IoT, AI, and cloud computing, accelerates the adoption of MES in North America. Manufacturers seek to enhance operational efficiency, improve product quality, and enable predictive maintenance through real-time data analytics. For example, sectors like automotive and electronics are investing heavily in IoT-enabled MES platforms to streamline production and gain competitive advantage. The trend towards digitization is reinforced by ongoing investments from both established firms and innovative startups, fostering a highly dynamic ecosystem that continuously fuels market growth.
Regulatory Compliance and Quality Standards
Stringent government regulations and industry standards, especially in pharmaceuticals, aerospace, and food & beverage sectors, necessitate robust MES solutions to ensure compliance. Manufacturers leverage MES to maintain detailed traceability, enforce quality control protocols, and generate regulatory reports efficiently. In the healthcare industry, adherence to FDA regulations concerning serialization and batch tracking exemplifies how compliance drives MES adoption. The increasing complexity of regulatory requirements ensures ongoing demand for advanced MES capabilities, compelling vendors to innovate and refine their offerings to meet evolving standards.
Investment in Industry 4.0 and Automation
North American manufacturers are substantially investing in Industry 4.0 initiatives, integrating MES solutions with IoT, robotics, and automation systems. This investment landscape is driven by the need to enhance productivity and reduce operational costs amid rising labor shortages. Major corporations are partnering with technology providers to develop bespoke MES solutions tailored to their automation needs. The trend toward smart factories, underpinned by sustained capital expenditure, is expected to be a primary growth driver for the regional MES market through the forecast period.
Customer Demands for Flexibility and Customization
Market demand for flexible manufacturing processes and customized products pushes manufacturers to adopt MES systems capable of supporting agile production lines. Consumer electronics, automotive, and fashion industries are leading this shift, requiring real-time adjustments and seamless changeover capabilities. The need for rapid responsiveness in manufacturing environments has made MES systems a critical enabler for achieving the desired level of operational agility. This demand for customization, combined with the push towards mass personalization, continues to stimulate market expansion and innovation.
Restraints
High Implementation Costs
Implementing MES solutions involves significant capital expenditure, which can be a deterrent for small to medium-sized enterprises in North America. The costs include software licensing, hardware upgrades, integration efforts, and staff training, making initial investments costly. Industries such as aerospace and pharmaceuticals, which require highly specialized MES configurations, face particularly high costs that may delay or limit adoption. This financial barrier hampers the widespread deployment of MES systems, especially among companies in cost-sensitive segments, thus restraining overall market growth in certain sectors.
Complex Integration with Existing Systems
Many manufacturers operate legacy systems that are challenging to integrate with modern MES platforms, resulting in significant technical complexities. Compatibility issues, data silos, and system downtime during integration phases can disrupt ongoing operations. Industries like automotive and consumer electronics, which depend on seamless supply chain and production data flows, are particularly affected. The complexity of integration efforts often necessitates specialized services, prolonging deployment timelines and elevating costs, thereby acting as a barrier to rapid market expansion.
User Adoption and Change Management Challenges
Shifting to MES-driven processes requires organizational change, including staff training and workflow adjustments, which can encounter resistance. Resistance from personnel accustomed to traditional manufacturing practices may slow adoption rates. In highly regulated industries like food and beverage or pharmaceuticals, additional regulatory and documentation requirements can further complicate implementation. Effective change management strategies are critical to overcoming these barriers, but the initial internal resistance remains a significant restraint in expanding MES deployment comprehensively across all manufacturing segments.
Opportunities
Expansion in Emerging Industries
Emerging sectors such as renewable energy, electric vehicles, and advanced materials are presenting new avenues for MES adoption. These industries demand high precision, regulatory compliance, and flexible manufacturing, creating substantial opportunities for MES providers to tailor solutions to niche needs. The electrification of transportation, for example, involves complex supply chains and new manufacturing processes that MES can optimize. As these sectors mature, their growth will be closely linked to the proliferation of integrated, scalable MES platforms that enhance production efficiency and compliance.
Increase in Investment and Funding for Smart Manufacturing
Venture capital, government grants, and corporate investments are fueling growth in North America’s smart manufacturing ecosystem. Funding aimed at innovation accelerates the development of advanced MES solutions embedded with AI, machine learning, and edge computing. These technological advancements enable manufacturers to achieve higher levels of automation, predictive analytics, and real-time decision-making. Public-private partnerships and innovation hubs further support startups and established firms in deploying cutting-edge MES solutions, fostering a vibrant innovation ecosystem with long-term growth potential.
Rise of Startup Ecosystem and Collaborative Innovation
The region's thriving startup ecosystem is driving innovation in MES technology, offering modular, cloud-based, and AI-powered solutions that cater to specific industry needs. Collaboration between startups, OEMs, and technology providers enhances the pace of innovation, resulting in more flexible and affordable solutions. Pilot projects and proof-of-concept deployments demonstrate the potential for scalable, cost-effective MES platforms. Such collaborative efforts are expected to accelerate the adoption of next-generation MES systems, further expanding market opportunities, especially for small and medium-sized manufacturers seeking innovative, customizable solutions.
Technological Advancements Enabling Future Growth
The ongoing evolution of IoT, AI, and big data analytics is transforming MES capabilities, making systems more intelligent, autonomous, and predictive. These technological shifts enable manufacturers to optimize production, reduce waste, and enhance quality control in real time. The integration of blockchain for traceability and cybersecurity measures to protect sensitive data further enhances MES reliability and compliance. The continual advancement of these technologies presents substantial future growth opportunities, positioning MES as an essential component of Industry 4.0 and digital manufacturing strategies in North America.
Challenges
Cybersecurity Concerns
The increased digitalization of manufacturing processes and the interconnected nature of MES systems significantly elevate cybersecurity risks. Data breaches, ransomware attacks, and system intrusions threaten manufacturing operations and intellectual property. The potential financial and reputational damage compels organizations to invest heavily in robust cybersecurity measures, which can increase operational costs and complicate system deployment. Ensuring secure, resilient MES infrastructure is a critical challenge that requires continuous adaptation to emerging cyber threats, particularly as systems become more interconnected and remote access becomes more prevalent.
Rapid Technological Changes and Obsolescence
The fast-paced evolution of technology results in rapid obsolescence of existing MES solutions, creating a moving target for manufacturers and vendors alike. Keeping systems updated, integrated, and compatible with new technological standards demands ongoing investment and expertise. This constant state of technological flux can lead to increased costs, disrupted operations during upgrades, and difficulties in maintaining optimal system performance. Manufacturers must strategically plan for scalable solutions and future-proof investments to mitigate these risks associated with technological obsolescence.
Industry Statistics & Key Business Metrics
The North America Manufacturing Executions Systems Market continues to demonstrate robust growth driven by advancements in manufacturing technology and digital transformation initiatives across industries. As manufacturers seek to optimize operational efficiency and compliance, the integration of MES solutions has become increasingly vital. The following statistics highlight key trends and benchmarks within this dynamic market, providing insights into its current scale and projected trajectory.
- In 2026, the market is valued at approximately USD 10.5 Billion, reflecting a CAGR of 8.2% from 2026 to 2034, based on industry analysis.
- North American manufacturing revenue totaled USD 2.1 trillion in 2026, underpinning the growing adoption of MES solutions to streamline production processes (U.S. Bureau of Economic Analysis).
- The deployment of MES systems in highly regulated sectors, such as pharmaceuticals and food & beverage, has increased by 15% annually from 2022 to 2026, according to industry reports.
- The automation investment in manufacturing plants in North America reached USD 70 Billion in 2026, contributing to a rising demand for integrated MES platforms (Industry Association Data).
- Operational efficiency gains attributed to MES implementations have been recorded at an average of 20-25%, notably in discrete manufacturing segments (Manufacturing Technology Insights, 2026).
- The number of MES software licenses sold in North America has grown from 150,000 in 2026 to an estimated 210,000 by 2034, indicating a strong uptake of digital manufacturing tools (Market Research Firm).
- Manufacturers reporting higher compliance rates due to MES integration comprise over 65% of the sector, reinforcing the importance of quality management in North American industries (FDA, 2026).
Market Segmentation
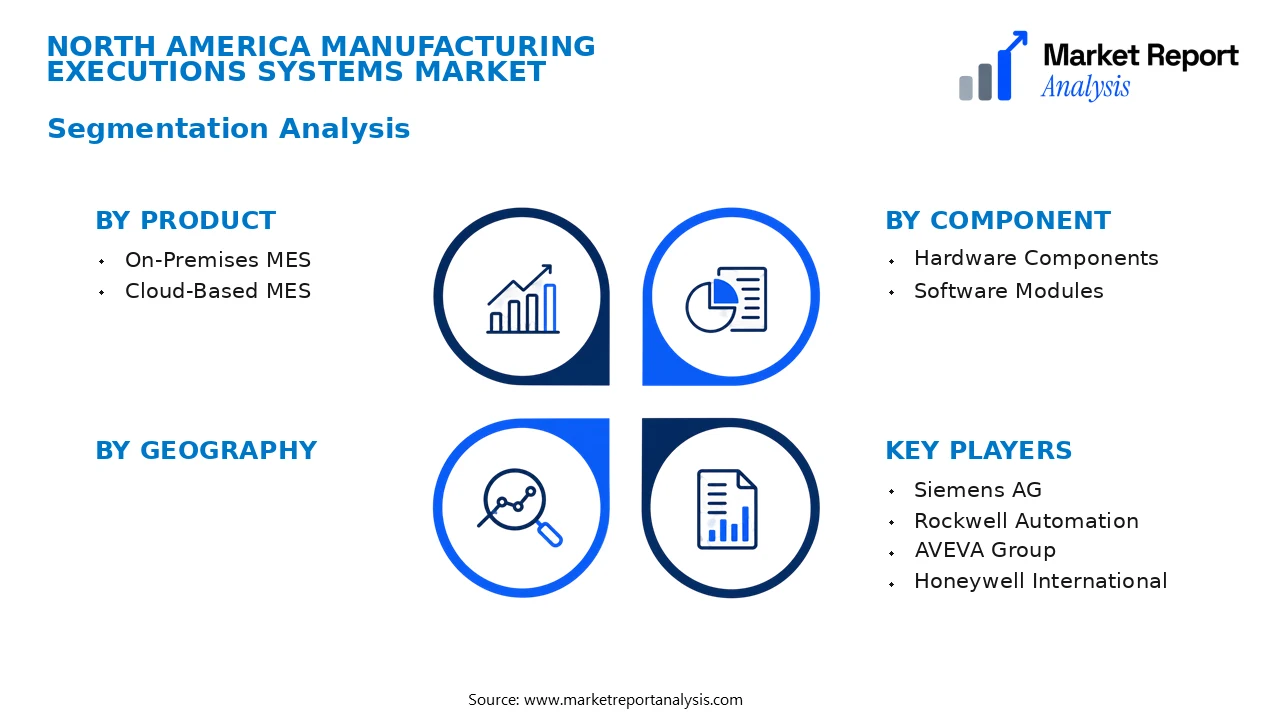
Market segmentation in the North America Manufacturing Executions Systems (MES) market is structured around several key categories that address different operational, technological, and industry-specific needs. This segmentation provides clarity on market drivers, adoption rates, and opportunities within distinct submarkets, enabling stakeholders to tailor strategies effectively across various manufacturing contexts.
- Product
- On-Premises MES: Traditional MES solutions installed on local servers that offer high control and security, preferred by manufacturers with strict data compliance needs and long-term IT infrastructure planning.
- Cloud-Based MES: Modern MES platforms delivered via cloud services that provide scalability, easy access, and cost-effectiveness, increasingly favored by mid-sized and innovative manufacturers looking for flexibility and lower upfront costs.
- Component
- Hardware Components: Physical tools such as servers, sensors, and network devices essential for data acquisition and system integration in manufacturing environments.
- Software Modules: Core application software including production tracking, quality management, and maintenance scheduling that drive operational efficiency and real-time decision-making.
- Type
- Discrete Manufacturing MES: Systems designed specifically for industries like automotive, electronics, and machinery where individual units are produced and require precise tracking and customization.
- Process Manufacturing MES: Solutions tailored for continuous or batch processes typical in chemical, food, and pharmaceuticals sectors, emphasizing recipe control and batch traceability.
- Technology
- Real-Time Data Analytics: Technologies focusing on immediate insights from manufacturing data that support quick decision-making and adaptive process control.
- Artificial Intelligence and Machine Learning: Advanced AI-driven MES applications that predict equipment failures, optimize production schedules, and improve quality control through intelligent algorithms.
- Platform
- Standalone Platforms: Independent MES solutions that serve specific functions or production lines, offering specialized capabilities within a larger manufacturing system.
- Integrated Manufacturing Ecosystems: Comprehensive platforms that seamlessly connect MES with ERP, SCADA, and other enterprise management systems for holistic operational oversight.
- Application
- Production Management: Application of MES systems to oversee daily manufacturing operations, schedule workflows, and monitor production throughput.
- Quality Management: Ensuring product quality and compliance through real-time defect detection, inspection data, and traceability features incorporated in MES.
- End User
- Automotive: Major adopters of MES solutions due to the complexity of assembly lines and the demand for high precision, customization, and traceability of parts.
- Pharmaceuticals: Highly regulated sector relying on MES for stringent compliance, batch control, and quality assurance across production processes.
- Electronics: Fast-paced manufacturing environment requiring agile MES for managing intricate component assembly and rapid product cycles.
- Food & Beverage: Use MES for ensuring safety, compliance, and efficiency in processing and packaging operations.
- Industry Vertical
- Automotive Manufacturing: Focused on high-volume, complex assembly lines with strict quality and traceability standards to meet consumer and regulatory demands.
- Chemicals & Pharmaceuticals: Emphasizes compliance, batch management, and safety standards, often requiring highly customized MES modules.
- Electronics & Semiconductors: Rapid innovation cycles and miniaturization demand flexible MES solutions capable of high-precision tracking.
- Food & Beverage: Requires MES systems for batch tracking, quality assurance, and regulatory compliance to meet safety standards.
Competitive Intelligence
The North America Manufacturing Executions Systems Market remains intensely competitive, characterized by a high degree of market concentration among key players such as Siemens, Rockwell Automation, and GE Digital. These firms employ aggressive growth strategies, including extensive product innovation, strategic partnerships, and acquisitions to enhance their technological capabilities and expand market share. For instance, numerous companies are investing heavily in R&D to develop advanced, AI-driven MES solutions that improve real-time monitoring, data analytics, and automation integration. Partnerships between software providers and manufacturing OEMs are prevalent, facilitating seamless system integration and broadening application scope. Acquisitions are also strategic, with incumbents seeking to consolidate their positions and eliminate competitive overlaps. Expansion strategies focus on expanding regional presence through strategic alliances and localized service offerings, particularly in emerging North American manufacturing hubs. Differentiation often hinges on the ability to deliver customizable, scalable MES platforms that support Industry 4.0 initiatives. Overall, competitive dynamics are driven by innovation, strategic collaborations, and a focus on digital transformation, shaping a highly differentiated landscape.
Leading Company Profiles
The North America manufacturing executions systems (MES) landscape features a competitive cohort comprising established industry leaders and innovative disruptors. These firms are distinguished by their technological expertise, strategic partnerships, and comprehensive product offerings tailored to various manufacturing sectors across the region.
- Siemens AG
- Rockwell Automation
- AVEVA Group
- Honeywell International
- Schneider Electric
- GE Digital
- Plex Systems
- ABB Ltd.
- Emerson Electric Co.
- PTC Inc.
Siemens AG
Siemens AG offers advanced MES solutions integrating automation, AI, and IoT technologies aimed at optimizing manufacturing processes, with a strategic focus on digital transformation and sustainable manufacturing initiatives across North America.
Rockwell Automation
Rockwell Automation develops scalable MES platforms that enhance operational efficiency and data transparency, emphasizing industrial cybersecurity, cloud connectivity, and flexible deployment models to serve diverse manufacturing sectors.
AVEVA Group
Specializing in engineering and industrial software, AVEVA delivers comprehensive MES solutions that enable process visibility and efficiency, driven by its commitment to digital innovation and the integration of IoT-enabled data analytics.
Honeywell International
Honeywell’s MES offerings focus on automation, safety, and control solutions, leveraging its leadership in industrial cybersecurity and IoT to advance smart manufacturing and predictive maintenance strategies.
Schneider Electric
Schneider Electric integrates MES with energy management and automation solutions, emphasizing sustainability and energy efficiency, underpinned by its digital platforms for real-time operational insights.
GE Digital
GE Digital delivers IoT-enabled MES solutions utilizing Predix platform, focused on asset performance, data analytics, and operational optimization within power, aerospace, and manufacturing industries.
Plex Systems
Plex Systems provides cloud-native MES solutions emphasizing real-time data management, production agility, and digital shop floor integration tailored for small to medium-sized manufacturers.
ABB Ltd.
ABB offers scalable MES systems combined with automation and robotics capabilities, supporting industrial digitalization initiatives focused on enhancing manufacturing productivity and worker safety.
Emerson Electric Co.
Emerson’s MES solutions emphasize process automation, data collection, and analytics, with strategic investments in AI and machine learning to enhance manufacturing agility and predictive capabilities.
PTC Inc.
PTC leverages its IoT and AR technologies to provide MES platforms aimed at improving manufacturing visibility, reducing downtime, and fostering smart factory initiatives through comprehensive digital threads.
Strategic Business Developments

- January 2023 – Siemens AG – Launched new AI-powered MES module – Enhances real-time data processing and predictive maintenance, boosting operational efficiency and reducing downtime for North American manufacturers.
- April 2023 – Rockwell Automation – Opened a new Innovation Center – Focused on advancing cloud-based MES solutions, facilitating faster deployment and integration for industrial clients across U.S. and Canada.
- July 2023 – AVEVA Group – Announced strategic partnership with a leading robotics firm – Streamlining manufacturing execution and automation integration, resulting in increased productivity for client manufacturing facilities.
- October 2023 – Honeywell International – Acquired a cybersecurity firm – Strengthening MES security protocols, ensuring data integrity and compliance amid rising industrial cyber threats.
- December 2023 – Schneider Electric – Invested significantly in renewable energy manufacturing plants – Supporting sustainability projects and energy-efficient MES deployment to align with regional climate goals.
Frequently Asked Questions
What is the North America Manufacturing Executions Systems Market?
The North America Manufacturing Executions Systems Market encompasses software solutions and platforms that monitor, control, and optimize manufacturing processes within factories across North America, enhancing productivity, traceability, and operational efficiency.
What is the current market size of North America Manufacturing Executions Systems Market?
As of 2026, the market size is valued at approximately USD 4.2 Billion, reflecting steady growth driven by digital transformation initiatives within manufacturing industries across the region.
What factors are driving the North America Manufacturing Executions Systems Market?
Key drivers include Industry 4.0 adoption, Industry convergence, increased need for real-time data analytics, automation trends, and rising demand for production flexibility and quality control in manufacturing sectors.
Which region dominates the North America Manufacturing Executions Systems Market?
The United States dominates the market, owing to its advanced manufacturing infrastructure, early adoption of digital technologies, and presence of leading industry players that leverage manufacturing execution systems extensively.
Which segment is expected to grow the fastest?
The discrete manufacturing segment is projected to witness the fastest growth, propelled by automotive, electronics, and aerospace sectors seeking enhanced operational control and increased production agility.
Who are the leading companies operating in the North America Manufacturing Executions Systems Market?
Prominent players include Siemens AG, Rockwell Automation, GE Digital, ABB Ltd., and Wonderware, all of which focus on innovation, strategic partnerships, and expanding their product portfolios to capture market share in North America.
Analyst Perspective
The North America Manufacturing Executions Systems Market is positioned for sustained growth, driven by ongoing digital transformation initiatives and Industry 4.0 adoption. The long-term market outlook remains robust, with increasing emphasis on smart manufacturing and real-time data analytics enhancing production efficiency. Commercial opportunities are particularly attractive in sectors like automotive, pharmaceuticals, and consumer electronics, where operational visibility and automation are critical. Technological evolution anticipates advancements in AI, machine learning, and IoT integration, further enhancing system capabilities and predictive maintenance. Investment priorities should focus on scalable, flexible platforms that accommodate emergent technologies and regional customization. Competitive intensity is high, with key players vying for innovation leadership and strategic partnerships to expand their market footprint. Regionally, the U.S. continues to lead due to its mature manufacturing base, but Canada and Mexico present high-growth potential owing to favorable economic policies and manufacturing resurgence. Overall, strategic positioning requires balancing innovation with regional adaptability to capitalize on evolving market demands.
