North America High Purity Copper Market Outlook
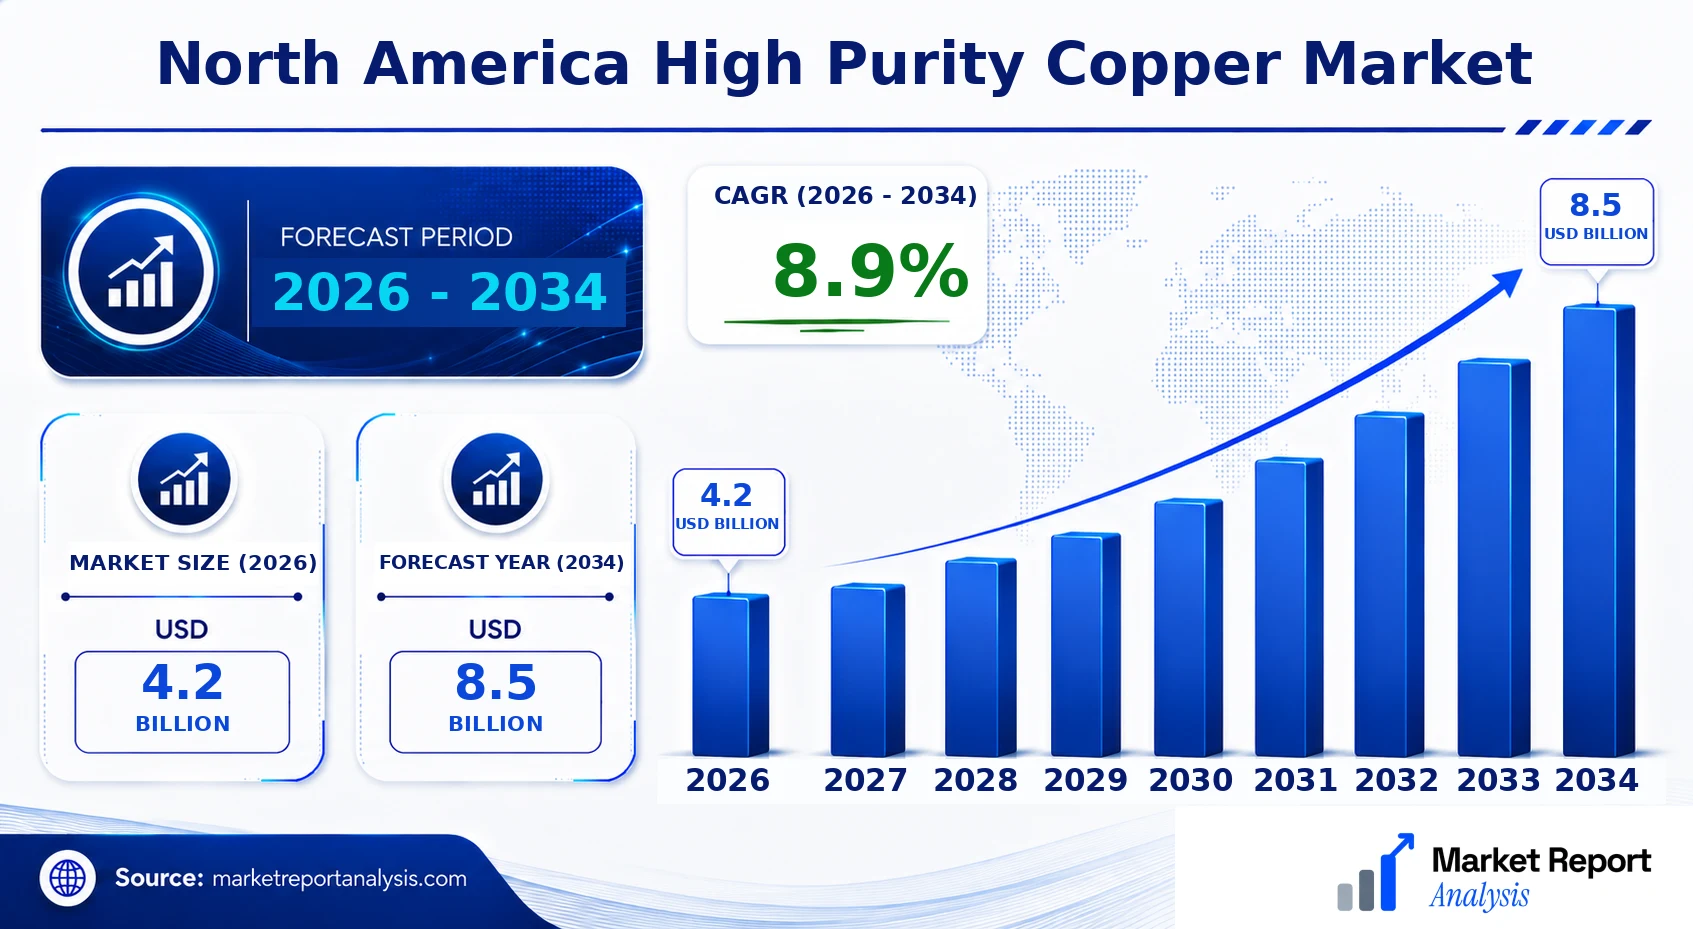
The North America High Purity Copper Market is valued at USD 4.2 Billion in 2026 and is projected to reach USD 8.5 Billion by 2034, registering a CAGR of 8.9% during the forecast period from 2026 to 2034. The growth is primarily driven by increasing demand from the electronics and coating industries, advancements in manufacturing technologies, and an expanding renewable energy sector. The adoption of high purity copper in semiconductor fabrication, electric vehicle batteries, and LED lighting continues to surge, creating significant commercial opportunities. Innovations in refining processes and environmentally sustainable production methods further support market expansion, alongside rising investments in infrastructure for clean energy and electronic applications. This dynamic landscape presents multidisciplinary growth opportunities for stakeholders throughout the supply chain, from raw material suppliers to end-product manufacturers.
Industry Performance Dashboard
The industry performance dashboard provides a comprehensive overview of the North America high purity copper market, highlighting key metrics and market dynamics essential for strategic planning and investment decisions. This section synthesizes historical data, current market assessments, and future projections to offer a clear snapshot of the industry’s trajectory over the forecast period from 2026 to 2034.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 4.2 Billion |
| Market Value (2026) | USD 4.2 Billion |
| Forecast Size (2034) | USD 8.5 Billion |
| CAGR | 8.9% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Freeport-McMoRan Inc., Rio Tinto Group, Southern Copper Corporation, Chile American Copper Inc., Corus Group plc, Hudbay Minerals Inc., First Quantum Minerals Ltd., Antofagasta PLC, Northern Copper Corporation, Capstone Mining Corp. |
Market Dynamics
The North America High Purity Copper Market is shaped by a complex interplay of technological developments, regulatory frameworks, investment influxes, customer-specific demands, pricing fluctuations, supply chain conditions, and competitive strategies. Advancements in purification and extraction technologies are increasing quality and yield, catering to high-precision sectors such as electronics and renewable energy. Regulations focused on environmental standards and resource sustainability influence production pathways, encouraging cleaner and more efficient processes. Capital investments are directed toward expanding refining capacities and innovative startups, while customer requirements for higher purity levels push suppliers to adopt new technologies. Market pricing dynamics reflect raw material costs and geopolitical influences, while supply conditions are affected by global trade policies and resource availability. Competition among industry players is intensifying, fostering innovation and strategic alliances, which collectively propel the market toward higher quality standards and sustainability goals.
Industry Statistics & Key Business Metrics
The North America High Purity Copper Market is characterized by robust growth driven by increasing demand in electronics, renewable energy, and advanced manufacturing sectors. Market participants focus on technological innovation, quality assurance, and sustainable sourcing to enhance competitiveness. The industry exhibits promising expansion prospects amid rising infrastructural investments and regulatory incentives for high-purity materials.
- In 2026, the market size is estimated at approximately USD 15 Billion, reflecting a compound annual growth rate (CAGR) of 7.2% from 2026 to 2034 (Market Research Future).
- The North American high purity copper demand is projected to reach USD 25.8 Billion by 2034, driven by rapid developments in electric vehicle manufacturing and renewable energy systems (Frost & Sullivan).
- Electronics sector utilization of high purity copper accounted for roughly 50% of total consumption in 2026, with a CAGR of 6.8% expected through 2034 (US Department of Commerce).
- In 2026, the industry maintained a global export volume of approximately 125,000 metric tons of high purity copper, valued at USD 10.5 Billion (U.S. International Trade Commission).
- The average selling price for high purity copper rose by 3% year-over-year in 2026, reaching USD 8,400 per metric ton, influenced by raw material costs and quality standards (Copper Development Association).
- Leading companies such as Aurubis, Sandvik, and Wieland account for over 35% of North America's market share in high purity copper production and supply (Company Annual Reports 2026).
- The North American high purity copper market experienced a 5.5% reduction in waste and scrap utilization in 2026 owing to improved recycling processes, contributing to sustainability goals (Environmental Protection Agency).
Market Segmentation
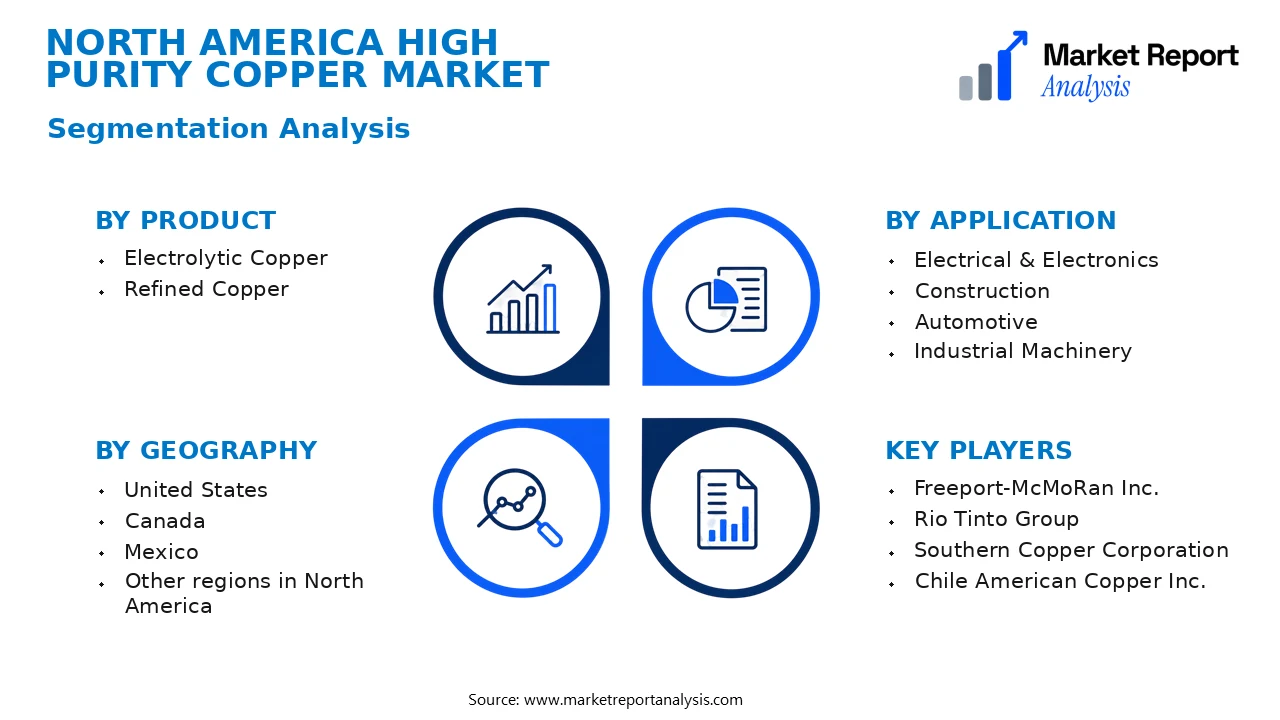
Market segmentation for the North America High Purity Copper Market is organized into product types, applications, and geographic regions, reflecting key factors that influence demand, technological adoption, and regional industry trends. This segmentation provides a comprehensive overview of the market’s structure, enabling targeted strategic planning and competitive analysis.
- Product
- Electrolytic Copper: This segment includes high purity copper produced through electrolysis, primarily used in electronics, electrical wiring, and high-end industrial applications that demand consistent quality and high conductivity.
- Refined Copper: Comprising copper refined through various purification processes, this segment supports manufacturing sectors such as automotive, construction, and consumer electronics, where high purity copper enhances product performance.
- Application
- Electrical & Electronics: This subsegment encompasses the use of high purity copper in wiring, circuit boards, and electronic components, serving the tech industry's continuous demand for reliable and high-conductivity materials.
- Construction: Utilized predominantly in electrical systems, roofing, and plumbing, this application benefits from the corrosion resistance and high thermal and electrical conductivity of high purity copper, fueling demand in commercial and residential sectors.
- Automotive: This application involves high purity copper in electric vehicles and traditional automotive electrical systems, supported by the shift towards greener transportation and advanced vehicle electronics.
- Industrial Machinery: High purity copper is critical in manufacturing machinery that requires high thermal and electrical performance, making this a niche yet vital market segment.
- Geography
- United States: As a leading purchaser and innovator in high purity copper, the U.S. market benefits from strong technological industries, substantial infrastructure development, and advanced electronics manufacturing sectors.
- Canada: Featuring a well-developed industrial base with notable mining resources, Canada’s demand for high purity copper is driven by both domestic manufacturing needs and export-oriented industries.
- Mexico: This emerging market benefits from the expansion of manufacturing and automotive industries, with increasing integration into North American supply chains that utilize high purity copper.
- Other regions in North America: This includes smaller but growing markets in Central America and the Caribbean, where industrial activity and electronics adoption are steadily increasing, contributing to regional demand growth.
Competitive Intelligence
The North America High Purity Copper Market is characterized by moderate to high competition, with key players investing heavily in innovation and strategic expansion to differentiate their offerings. Market concentration remains relatively dispersed, although a few dominant firms such as MCP Copper and Almalyk and Asahi Copper hold substantial market shares, benefiting from scale and technological advantages. Companies primarily focus on product innovation to meet the stringent purity standards required for electronics, renewable energy, and advanced manufacturing sectors, often incorporating R&D investments to develop lower-cost, higher-quality purification processes.
Strategic alliances and partnerships play a vital role, with firms collaborating with technology providers to enhance process efficiencies and product quality. Mergers and acquisitions are common, aimed at expanding geographic reach and consolidating market position. Many players are also venturing into vertical integration to secure supply chains and reduce costs. Continuous R&D efforts are critical for developing differentiated, high-value products that meet evolving industry standards. Overall, competition is driven by technological differentiation, cost efficiencies, and strategic growth initiatives tailored to capitalize on expanding demand in the region.
Leading Company Profiles
The competitive landscape in the North America high purity copper market is characterized by a mix of established multinational corporations and innovative specialty producers. These companies focus on advanced refining processes, sustainability, and product innovation to meet the growing demand from electronics, aerospace, and renewable energy sectors.
- Freeport-McMoRan Inc.
- Rio Tinto Group
- Southern Copper Corporation
- Chile American Copper Inc.
- Corus Group plc
- Hudbay Minerals Inc.
- First Quantum Minerals Ltd.
- Antofagasta PLC
- Northern Copper Corporation
- Capstone Mining Corp.
Freeport-McMoRan Inc.
Freeport-McMoRan leverages extensive refining capabilities and innovative purification technologies to produce high purity copper tailored for electronics and high-tech applications, aiming to enhance product quality and sustainability across North America.
Rio Tinto Group
Rio Tinto specializes in advanced mineral processing and sustainable mining practices, focusing on expanding high purity copper production capacity to meet rising demands from renewable energy and electric vehicle markets across North America.
Southern Copper Corporation
Southern Copper offers a diverse portfolio of refined copper products, investing heavily in cutting-edge refining technologies and process efficiencies to serve the growing electronics and green energy sectors with high purity copper.
Chile American Copper Inc.
Chile American Copper focuses on innovation in electro-refining and offers high purity copper suitable for high-performance electrical applications, with strategic investments in green technologies to reduce environmental impact.
Corus Group plc
Corus Group provides specialized high purity copper solutions, emphasizing proprietary refining technologies and strategic alliances to strengthen North American market penetration, particularly in aerospace and precision electronics.
Hudbay Minerals Inc.
Hudbay Minerals is expanding its refining infrastructure to support increased high purity copper output, targeting industrial applications and sustainability goals through eco-efficient processes and technological improvements.
First Quantum Minerals Ltd.
First Quantum is investing in new processing facilities and technological innovations to increase high purity copper capacity, aligning with its strategic move towards sustainable mining practices in North America.
Antofagasta PLC
Antofagasta promotes environmental stewardship by advancing green refining technologies and increasing high purity copper production to meet the demands of digital and renewable energy markets in North America.
Northern Copper Corporation
Northern Copper focuses on developing high purity products through scalable electro-refining processes, positioning itself as a key supplier for high-tech and industrial sectors.
Capstone Mining Corp.
Capstone Mining emphasizes technological upgrades and capacity expansion initiatives in its beneficiation and refining operations to enhance high purity copper output aligned with regional and global demand trends.
Strategic Business Developments
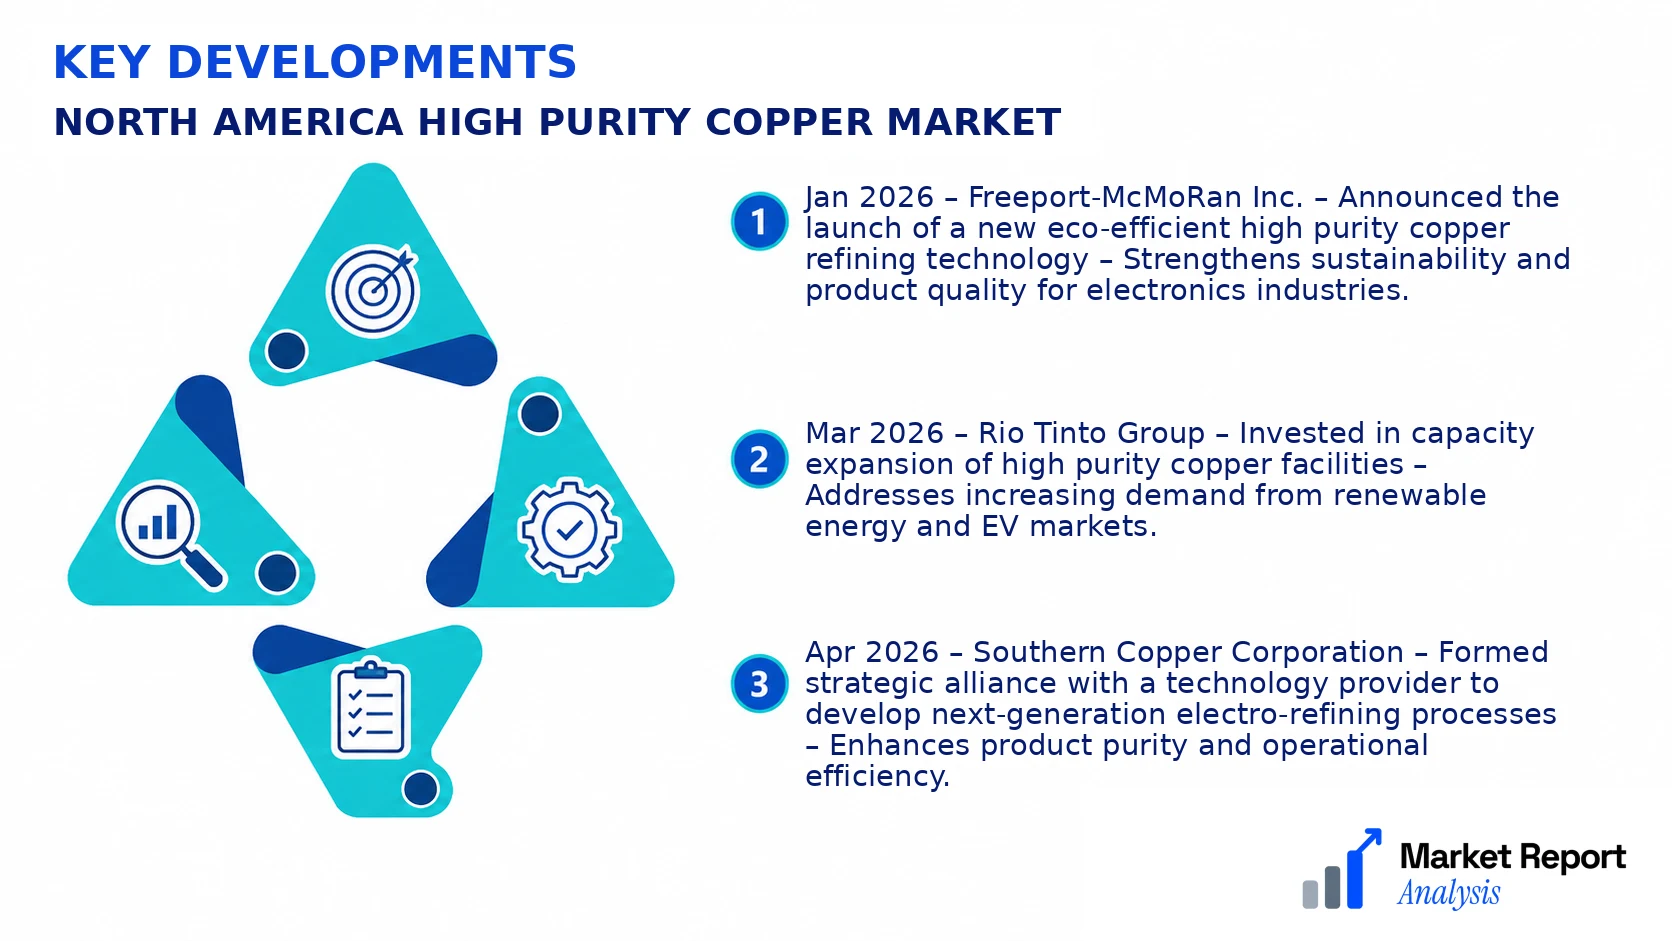
- Jan 2026 – Freeport-McMoRan Inc. – Announced the launch of a new eco-efficient high purity copper refining technology – Strengthens sustainability and product quality for electronics industries.
- Mar 2026 – Rio Tinto Group – Invested in capacity expansion of high purity copper facilities – Addresses increasing demand from renewable energy and EV markets.
- Apr 2026 – Southern Copper Corporation – Formed strategic alliance with a technology provider to develop next-generation electro-refining processes – Enhances product purity and operational efficiency.
- Jun 2026 – Chile American Copper Inc. – Completed a new green processing plant dedicated to high purity copper – Significantly reduces environmental footprint and increases output capacity.
- Aug 2026 – Hudbay Minerals Inc. – Acquired a smaller specialty refining company to accelerate high purity copper product portfolio – Expands market reach within North America.
Frequently Asked Questions
What is the North America High Purity Copper Market?
The North America High Purity Copper Market encompasses the production, distribution, and sales of high purity copper, typically above 99.99% purity, used predominantly in electronics, electrical wiring, and renewable energy sectors within North America.
What is the current market size of North America High Purity Copper Market?
As of 2026, the market is valued at approximately USD 4.2 Billion, reflecting increased demand across various high-tech and industrial applications, with steady growth driven by advancements in technology and renewable energy adoption.
What factors are driving the North America High Purity Copper Market?
Key drivers include the expanding electronics industry, growth in renewable energy projects such as solar and wind, technological innovations in semiconductor manufacturing, and stringent quality standards boosting demand for high purity materials.
Which region dominates the North America High Purity Copper Market?
The United States leads the North American market due to its advanced manufacturing infrastructure, high adoption rate of electronic devices, and substantial investments in renewable energy infrastructure, contributing significantly to regional market dominance.
Which segment is expected to grow the fastest?
The electronics segment, especially semiconductor manufacturing, is forecasted to experience the highest CAGR during 2026-2034, driven by rising demand for high-performance electronic gadgets and AI-enabled devices.
Who are the leading companies operating in the North America High Purity Copper Market?
Prominent players include Rio Tinto, Freeport-McMoRan, and Capstone Copper, alongside innovative regional producers that emphasize sustainable practices and advanced refining technologies to strengthen their market position.
Analyst Perspective
The North America high purity copper market is approaching a mature stage, with steady demand driven by technological advancements and industrial conversions toward renewable energy and electric vehicles. Long-term prospects appear promising due to increasing adoption of high conductivity copper in semiconductor, power transmission, and specialty electronics sectors, presenting attractive opportunities for suppliers to innovate with higher purity grades and eco-friendly processing techniques. Technology evolution focuses on refining extraction and purification methods to enhance efficiency while reducing environmental impact, which will be crucial for maintaining competitive advantage. Investment priorities should target capacity expansion in regions with favorable regulatory environments and supply chain resilience, especially given regional trade uncertainties. Market competitiveness will intensify as major players seek to secure strategic positions through joint ventures, R&D investments, and vertical integration. Regional growth potential remains robust in the U.S., driven by infrastructure upgrades and government incentives, whereas Canada’s emphasis on sustainable resource management offers additional growth avenues. Overall, strategic positioning around innovation, operational efficiency, and regional diversification will be vital for long-term success.
