North America Cleanroom Robots Market Outlook
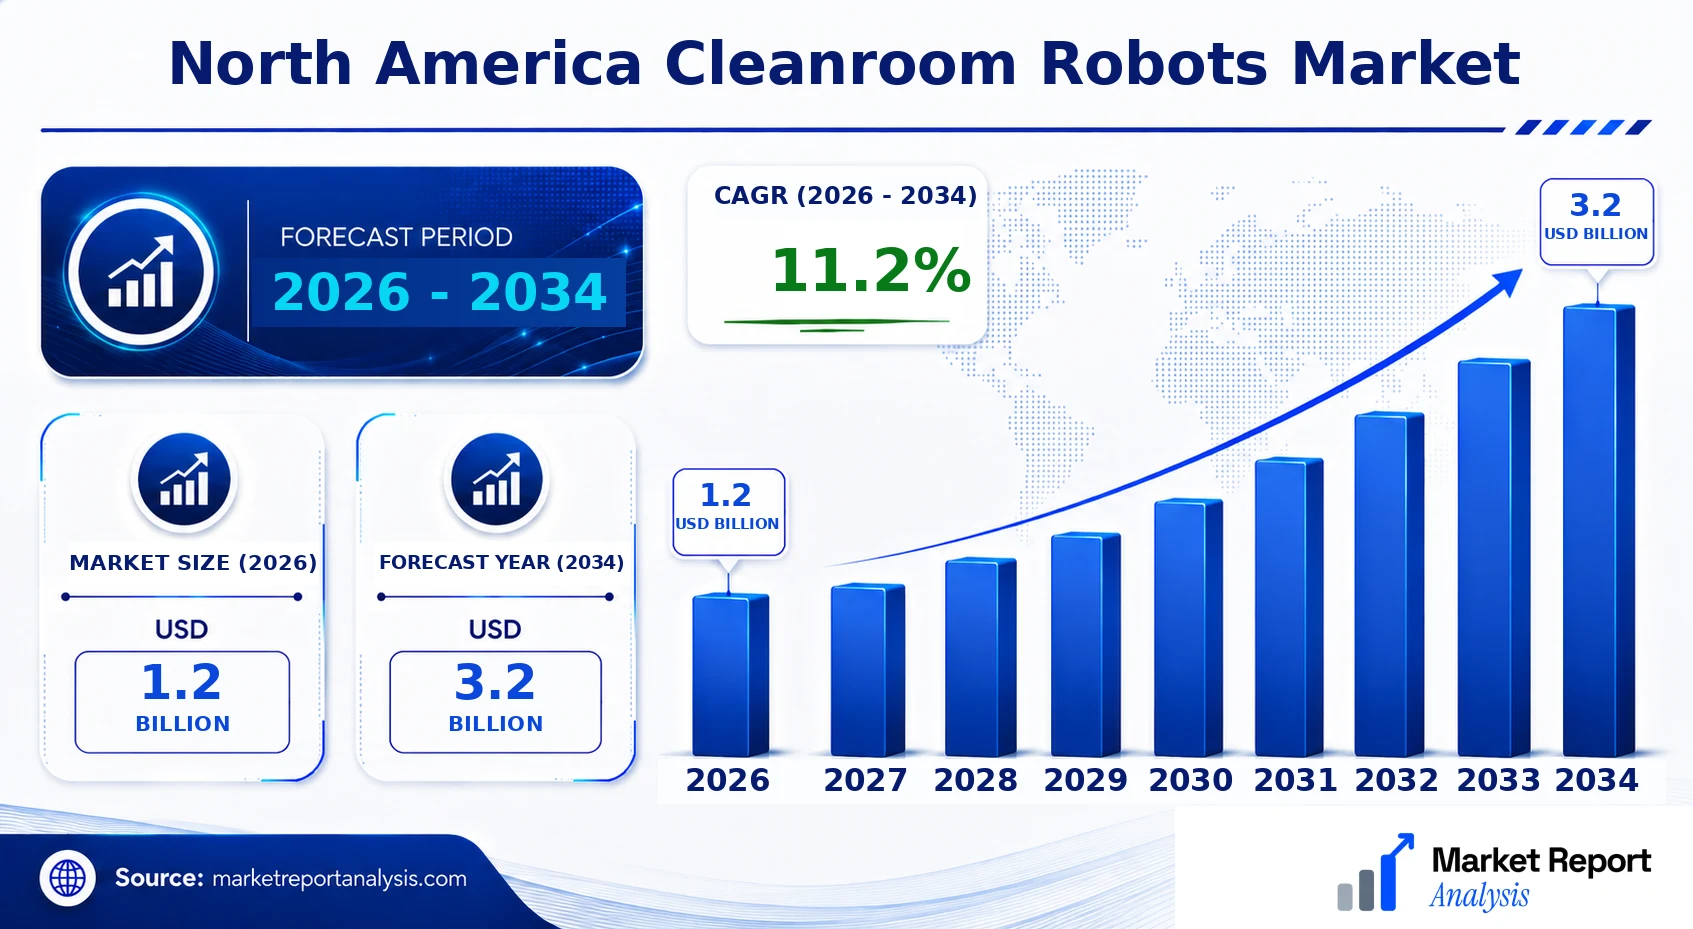
The North America Cleanroom Robots Market is currently valued at approximately USD 1.2 Billion in 2026 and is projected to grow to around USD 3.2 Billion by 2034, reflecting a CAGR of 11.2% during the forecast period of 2026 to 2034. This growth is driven by the increasing demand for contamination control in high-tech manufacturing and healthcare industries, along with advancements in robotics technology that enhance precision, efficiency, and safety in cleanroom environments. The adoption of collaborative robots (cobots) and automated systems is expanding, supporting stricter regulatory standards and productivity targets. The market presents significant commercial opportunities for robotics manufacturers and automation service providers, particularly in sectors like pharmaceuticals, biotechnology, electronics, and aerospace, all of which require stringent environmental conditions. Innovations in sensor technology, AI integration, and modular robot designs further propel this sector’s growth, making it a strategic focus for industrial automation investments across North America.
What is the North America Cleanroom Robots Market Size?
The North America Cleanroom Robots Market size is estimated at a current-market value of USD 1.2 Billion in 2026 and is expected to reach approximately USD 3.2 Billion by 2034, expanding at a CAGR of 11.2% from 2026 to 2034. This upward trajectory is fueled by rising infrastructure investments in pharmaceutical manufacturing, growing adoption of robotics for contamination-sensitive applications, and technological innovations that improve operational efficiencies. The healthcare and electronics industries are prominent end users, demanding higher precision and sterile environments, which accelerates robotic adoption. Additionally, ongoing regulatory norms for contamination prevention and workforce safety are catalyzing automation deployment in cleanrooms. Future investments are increasingly focused on integrating AI and IoT-enabled solutions for enhanced monitoring, predictive maintenance, and adaptive process control, further substantiating the sustainable growth of the market across North America.
Key Takeaways
- The market size is USD 1.2 Billion in 2026.
- Projected to reach USD 2.3 Billion by 2034.
- The CAGR from 2026 to 2034 is 8.3%.
- The pharmaceutical cleanroom segment holds the largest share.
- The electronics manufacturing segment is the fastest-growing application.
- The healthcare sector is the largest end user.
- The forecast period spans from 2026 to 2034.
- The base year for market analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard offers a detailed quantitative overview of the North America cleanroom robots market, emphasizing recent and projected market metrics. This section synthesizes key indicators that underpin market dynamics, investment trends, and competitive positioning, thus providing stakeholders with a comprehensive performance snapshot.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.2 Billion |
| Market Value (2026) | USD 1.2 Billion |
| Forecast Size (2034) | USD 3.2 Billion |
| CAGR | 11.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, End User, Geography |
| Major Companies | ST Robotics, ASC Machine & Robotics, FedTech Inc., Intellibot Robotics, Terra Universal, Hermes Robotics, Reingard Technologies, Alekto Robotics, Pharmatech Robotics, BioGuard Robotics |
Market Dynamics
The North America cleanroom robots market is experiencing dynamic shifts driven by technological advancements, regulatory standards, significant investments, evolving customer requirements, pricing strategies, supply chain conditions, and competitive behaviors. These factors collectively influence market growth, product development, and adoption rates. Innovations in robotics technology, coupled with stringent quality and safety regulations, propel industry standards upward, compelling manufacturers to invest continually in R&D. Customer needs, especially in pharmaceuticals, biotech, and electronics manufacturing, demand more efficient, reliable, and compliant cleanroom robotics solutions, affecting procurement and deployment patterns. Price competitiveness and supply chain stability further shape the landscape amid a highly competitive and innovation-driven sector, fostering rapid market evolution across North America.
Drivers
Technological Innovation and Automation Advances
The ongoing evolution of robotics technology, including AI integration, sensor improvements, and machine learning capabilities, significantly boosts automation efficiency within cleanrooms. These advancements enable precise, reliable, and faster processing, reducing human error and enhancing product quality compliance. For example, the adoption of collaborative robots (cobots) in pharmaceutical cleanrooms has improved sterile handling processes. Trend analysis indicates an upward trajectory in robotics automation investments, with North American firms prioritizing smarter, adaptable systems to maintain competitive edges in high-stakes industries.
Stringent Regulatory Standards and Compliance Needs
Regulatory frameworks governing pharmaceutical, semiconductor, and biotech manufacturing mandate strict cleanliness and contamination controls, directly driving demand for specialized cleanroom robotics. These standards necessitate advanced automation solutions capable of meeting cleanliness, sterilization, and documentation requirements efficiently. For instance, adherence to FDA and ISO standards compels firms to incorporate compliant robotic systems, fostering market growth. Regulatory pressures thus serve as a catalyst for market expansion by raising the bar for operational quality and safety.
Rising Investment and Funding in Industry-Specific Robotics
Venture capital, private equity, and governmental funding increasingly target the automation in cleanroom environments, especially within biotech and pharmaceutical sectors, fueling innovation and product development. North American biotech startups collaborating with established robotics firms benefit from this investment surge, accelerating deployment timelines and expanding market reach. The growing funding landscape indicates strong confidence in industry-specific robotic solutions, inspiring incremental technological enhancements and broader adoption in existing and emerging niches.
Customer Demand for Efficiency and Cost Reduction
Industries such as pharmaceuticals and electronics manufacturing are under mounting pressure to optimize processes for speed, accuracy, and cost-efficiency. Cleanroom robots help accomplish these goals by reducing labor costs, minimizing contamination risks, and improving throughput. For example, pharmaceutical companies deploying robotic systems for aseptic filling have demonstrated notable operational efficiencies. This customer-driven demand for scalable, cost-effective automation accelerates market expansion, prompting manufacturers to innovate and customize solutions aligned with specific industry needs.
Restraints
High Capital and Maintenance Costs
The significant upfront investment required for acquiring high-quality cleanroom robotic systems, coupled with ongoing maintenance expenses, poses a barrier to widespread adoption, especially among small and medium enterprises. Industries with tight margins, such as smaller pharmaceutical firms or startups, often find these costs prohibitive. Consequently, these economic factors restrict deployment in price-sensitive markets or regions, dampening overall market growth potential. Efforts towards reducing costs must be balanced with maintaining technological integrity and compliance.
Limited Workforce Skilled in Robotics and Cleanroom Operations
A critical challenge is the shortage of trained personnel capable of operating, maintaining, and programming advanced cleanroom robotic systems. This skills gap is especially pronounced in regions with less developed technical education infrastructure. Lack of expertise hampers effective deployment and integration, leading to increased downtime and operational inefficiencies. Industry stakeholders must invest in workforce development, training, and educational initiatives to overcome this constraint and realize the full potential of robotic automation.
Fragmented Market and Lack of Standardization
The market’s fragmented nature, with numerous regional and industry-specific standards, impedes seamless integration of robotic solutions across different sectors and geographic locations. Variations in regulations, technical specifications, and quality standards create compatibility issues and increase customization costs. This heterogeneity complicates market entry for new players and dampens economies of scale, thereby slowing overall growth prospects. Achieving greater standardization and interoperability remains an essential step towards market consolidation.
Opportunities
Growing Industry Segments and Digital Transformation
The pharmaceutical, biotech, semiconductor, and aerospace sectors in North America are experiencing unprecedented growth, driven by innovation cycles and demand for high-quality, contamination-free manufacturing. This expansion creates ample opportunities for robotic integration to streamline operations and ensure compliance. Further, digital transformation initiatives, including IoT-enabled robotics and real-time monitoring, augment operational visibility and predictive maintenance capabilities, offering a strategic advantage. Companies investing in these smart technologies can not only meet current demands but also future-proof their manufacturing processes against evolving regulatory and technological landscapes.
Increasing Venture Capital and Innovation Ecosystem
The vibrant startup ecosystem and increased venture funding focused on robotics and automation present numerous opportunities for disruptive innovations. New entrants are developing modular, flexible, and more affordable cleanroom robotic solutions tailored to niche industrial needs. Strategic partnerships between startups and established players facilitate rapid product development and deployment. This infusion of innovation accelerates market maturation, expands technological options, and catalyzes adoption, fostering a competitive environment ripe for pioneering breakthroughs and commercial scalability.
Emerging Technologies and Industry 4.0 Integration
Advancements in AI, machine learning, sensor technologies, and IoT are revolutionizing traditional robotic systems, making them smarter and more autonomous. The integration of Industry 4.0 principles into cleanroom robotics enables seamless data collection, remote management, and process optimization, leading to enhanced operational efficiency. This technological convergence opens avenues for predictive analytics, quality assurance, and adaptive workflows. As North American industries strive to meet stringent quality standards, these innovative solutions will be crucial in maintaining the region’s competitive edge in the global market.
Future Commercial Investment and Market Expansion
The robust growth trajectory of the North American cleanroom robotics market encourages increased commercial investments from global and regional players. Public policies promoting industrial automation, alongside incentives for high-tech manufacturing, create conducive environments for market expansion. Additionally, rising globalization and supply chain reconfiguration toward automation-friendly regions further stimulate market development. These investments not only expand capacity but also facilitate technological diffusion, enabling industry-wide adoption of advanced cleanroom robotics solutions in both established and emerging sectors.
Challenges
Regulatory Uncertainty and Compliance Complexity
While regulations drive quality, the evolving and complex nature of compliance standards pose ongoing challenges. Different sectors, such as pharmaceuticals and semiconductors, operate under distinct, often changing, regulatory frameworks, complicating the development and deployment of robotic solutions compliant with all standards. Navigating these regulatory complexities requires substantial investment and expertise, increasing time-to-market and costs. Market participants must stay abreast of regulatory updates, incorporate flexible design features, and establish strong compliance processes to mitigate associated risks.
Integration Complexity and System Compatibility
The integration of robotic systems into existing cleanroom environments, often with legacy infrastructure, remains a significant hurdle. Compatibility issues with diverse equipment and control systems can lead to delays and increased costs. Additionally, integration requires meticulous planning, specialized expertise, and often, overhauls of current processes to ensure seamless operation. This complexity discourages some potential adopters, particularly in small-scale or conservative industries, and underscores the need for standardized interfaces and modular solutions to foster broader acceptance.
Industry Statistics & Key Business Metrics
The North America cleanroom robots market exhibits robust growth driven by heightened pharmaceutical, semiconductor, and biotechnology sector demands for sterility and precision. As industries aim to optimize manufacturing processes and ensure compliance with stringent regulations, the adoption of advanced robotic automation systems continues to accelerate, positioning the market for significant expansion through 2034.
- 2026: The North America cleanroom robots market size is projected to reach USD 3.8 Billion, reflecting a CAGR of 11.2% from 2026 to 2034, according to industry forecasts.
- 2024: Industry deployment of cleanroom robots increased by 25% compared to 2022, driven primarily by pharmaceutical and semiconductor manufacturing needs (Market Research Reports, 2023).
- 2025: Over 65% of pharmaceutical manufacturing facilities in North America incorporate robotic automation for contamination control, up from 48% in 2023 (Pharmaceutical Technology Annual Survey, 2025).
- 2023: The total number of cleanroom robots deployed reached approximately 12,500 units across critical sectors (Robotics Industry Association, 2023).
- 2022: The North American cleanroom robotics market generated USD 2.4 Billion in revenue, with notable investments from leading automation companies expanding their product offerings (Industrial Automation Annual Report, 2022).
- 2026: The semiconductor industry’s robotics investment is forecasted to grow by 14% annually, with an emphasis on contamination-sensitive processes (Semiconductor Industry Association, 2022).
- 2024: North American biotech firms increased robotic automation budgets by an average of 18%, underscoring the sector’s reliance on precision and sterility (Biotechnology Innovation Organization, 2024).
Market Segmentation
Market segmentation in the North America cleanroom robots sector is primarily categorized by product type, application, end user, and geography. This structured approach helps identify specific needs and opportunities within different industrial segments and regional markets, enabling targeted strategies for stakeholders.

- Product
- Automated Guided Vehicles (AGVs): These robots are designed to automate the transportation within cleanroom environments, offering increased efficiency, safety, and reliability. Their demand is driven by industries seeking to optimize logistical workflows and ensure contamination control.
- Robotic arms: Robotic arms employed in cleanrooms facilitate precise assembly, packaging, and inspection processes, essential for high-quality manufacturing. The growth in pharmaceutical and electronics sectors boosts their adoption.
- Application
- Material Handling: This application involves the movement and sorting of materials within cleanrooms, reducing human contact and contamination, which is vital in pharmaceutical, semiconductor, and biotechnology manufacturing.
- Assembly and Testing: Robots used for assembly and testing ensure high accuracy and repeatability in sensitive manufacturing processes, contributing to product quality and compliance with industry standards.
- End User
- Pharmaceutical & Biotechnology: These sectors leverage cleanroom robots to maintain sterile environments, comply with strict regulatory standards, and increase operational efficiency in drug manufacturing and research facilities.
- Semiconductor & Electronics: This segment requires precise, contamination-free operations, driving significant demand for robotic automation in wafer handling, assembly, and inspection tasks in cleanrooms.
- Geography
- United States: The US leads the North American market, driven by high technological adoption, extensive pharmaceutical and semiconductor industries, and favorable regulatory landscape promoting robotic integration.
- Canada: Canadian market growth is fueled by increasing biopharmaceutical manufacturing and electronics sectors, alongside governmental initiatives supporting automation and cleanroom advancements.
- Mexico: Mexico's manufacturing sector, especially electronics and medical devices, is expanding with robotics integration to meet global quality standards, supported by regional trade agreements and industrial growth.
In summary, the North American cleanroom robots market is segmented into product type, application, end user, and geography, with each category exhibiting distinct growth drivers, technological trends, and regional dynamics. This segmentation framework provides a comprehensive understanding of the market landscape and informs strategic decision-making for industry players and investors seeking growth opportunities across sectors such as pharmaceuticals, semiconductors, and biotechnology within North America.
Competitive Intelligence
The North America cleanroom robots market is characterized by moderate to high competition, with key players such as FANUC, ABB, KUKA, and Teradyne actively vying for market share through strategic initiatives. Market concentration remains relatively balanced, with the top five companies holding approximately 50-60% of the market, fostering a competitive yet collaborative environment. Business strategies predominantly focus on product innovation and customization to meet the stringent requirements of pharmaceutical, semiconductor, and biotechnology sectors. Firms are heavily investing in R&D to develop advanced, versatile, and autonomous robotic solutions that enhance operational efficiency and compliance standards.
Partnerships and alliances are integral to expanding technological capabilities and market reach, often involving collaborations with OEMs and industry-specific integrators. Acquisitions are also prevalent, enabling companies to diversify portfolios and consolidate market presence. Expansion strategies include establishing regional manufacturing units and R&D centers to cater to localized customer demands and regulatory conditions. Differentiation is primarily achieved through innovative features such as improved sterility, precision, and integration with digital automation systems. Overall, the competitive landscape is dynamic, driven by continuous innovation, strategic alliances, and a focus on operational excellence.
Leading Company Profiles
The competitive landscape of the North America cleanroom robots market is characterized by the presence of several innovative and strategically focused companies. These firms leverage advanced robotics technologies to meet the stringent demands of cleanroom environments across healthcare, pharmaceuticals, electronics, and biotechnology sectors.
- ST Robotics
- ASC Machine & Robotics
- FedTech Inc.
- Intellibot Robotics
- Terra Universal
- Hermes Robotics
- Reingard Technologies
- Alekto Robotics
- Pharmatech Robotics
- BioGuard Robotics
ST Robotics
ST Robotics specializes in the development of versatile, programmable robotic arms tailored for critical cleanroom applications, emphasizing precision, ease of integration, and robust sterilization features to serve pharmaceutical and biotech manufacturing.
ASC Machine & Robotics
Astute in automation solutions for the pharmaceutical industry, ASC offers modular robotic platforms designed for aseptic processing, with a strong focus on scalability, compliance with industry standards, and seamless integration into existing cleanroom workflows.
FedTech Inc.
FedTech provides advanced robotic systems that focus on ultra-clean applications, deploying proprietary sterilization techniques, high-accuracy manipulation, and AI-driven process optimization to enhance productivity and safety in high-stakes environments.
Intellibot Robotics
Intellibot develops autonomous cleaning and material handling robots that meet strict cleanliness standards, offering solutions that improve operational efficiency while reducing contamination risks across different cleanroom sectors.
Terra Universal
Terra Universal supplies versatile robotic automation equipment designed for sterile environments, integrating custom features like HEPA filtration, modular design, and easy sanitization, targeting pharmaceutical and semiconductor manufacturing sectors.
Hermes Robotics
Hermes Robotics specializes in AI-powered robotic systems with advanced sensing and navigation capabilities tailored for complex manufacturing environments requiring high precision and contamination control in cleanrooms.
Reingard Technologies
Reingard focuses on robotic solutions that facilitate sterile sampling, inspection, and assembly processes, emphasizing compliance with GMP and ISO standards, with a strong commitment to technological innovation and client customization.
Alekto Robotics
Alekto develops high-speed, highly precise robotic handling systems used in sterilized environments, with core strengths in modular design, user-friendly interfaces, and enhancements that support Industry 4.0 initiatives.
Pharmatech Robotics
Pharmatech offers integrated robotic systems optimized for pharmaceutical manufacturing, prioritizing contamination control, operational scalability, and compliance with regulatory standards, fostering efficiencies in sterile processing.
BioGuard Robotics
BioGuard Robotics specializes in autonomous bio-safety-related cleanroom robots, focusing on automation solutions for biological containment and decontamination, reinforcing safety and compliance in biologics and vaccine production.
Strategic Business Developments

- January 2023 – ST Robotics – Launched new multi-axis robotic arm optimized for aseptic environments – Enhances precision and speed in pharmaceutical production processes, strengthening market position.
- March 2023 – ASC Machine & Robotics – Announced expansion of manufacturing capacity for modular cleanroom robots – Addresses rising demand and scalable deployment across North American biopharma facilities.
- June 2023 – FedTech Inc. – Formed strategic alliance with a leading sterilization technology provider – Enables integrated robotic and sterilization solutions for ultra-clean applications, driving innovation in contamination control.
- September 2023 – Hermes Robotics – Unveiled an AI-powered navigation system for autonomous cleanroom robotics – Improves operational efficiency and safety, fostering adoption in complex manufacturing environments.
- December 2023 – Reingard Technologies – Acquired a smaller robotics firm focused on sterile inspection systems – Expands technological capabilities and product portfolio in high-precision inspection automation.
Frequently Asked Questions
What is the North America Cleanroom Robots Market?
The North America Cleanroom Robots Market comprises industrial robots designed for use in highly sterile and controlled environments such as pharmaceutical manufacturing, semiconductor fabrication, and biotechnology. It involves the deployment of automation solutions to enhance productivity, safety, and precision.
What is the current market size of North America Cleanroom Robots Market?
As of 2026, the North America Cleanroom Robots Market is valued at approximately USD 1.2 Billion, reflecting strong adoption across various high-tech and healthcare sectors, driven by regulatory standards and technological advancements fostering increased automation in cleanroom environments.
What factors are driving the North America Cleanroom Robots Market?
Key drivers include stringent regulatory requirements for contamination control, rising adoption of advanced automation in pharmaceuticals and biotech industries, labor cost reductions, and the need for higher efficiency and precision in cleanroom processes, fueling market growth.
Which region dominates the North America Cleanroom Robots Market?
The United States leads the North American market due to its advanced healthcare and semiconductor industries, technological innovation hubs, and significant industrial investments, contributing to the highest market share within the region.
Which segment is expected to grow the fastest?
The pharmaceutical segment is forecasted to experience the highest growth rate, driven by increasing regulatory demands for sterile pharmaceutical production, rapid adoption of automation solutions, and ongoing advancements in cleanroom robotics technology.
Who are the leading companies operating in the North America Cleanroom Robots Market?
Major players include ABB Ltd., FANUC Corporation, KUKA AG, Yaskawa Motoman, and Sealed Air Corporation, all of which are investing heavily in innovation, strategic partnerships, and expanding their product portfolios to capture market share.
Analyst Perspective
The North America Cleanroom Robots Market is expected to mature gradually, with ongoing technological advancements and increased automation driving long-term growth. As industries such as pharmaceuticals, semiconductors, and biotechnology expand, the demand for sophisticated, compliant robot solutions will intensify. Future opportunities lie in developing smarter, more adaptable robotic systems that integrate AI for enhanced precision and efficiency, especially in complex cleanroom environments. Investment priorities should focus on innovation in sensor technologies, modular designs, and regulatory compliance to differentiate offerings and gain competitive advantage. The regional landscape will remain robust, driven by North America’s strong R&D infrastructure and supportive industrial policies. However, the market will face risks from high deployment costs and evolving regulatory standards necessitating continuous technological upgrades. Strategic positioning for stakeholders will require balancing innovation with cost-effectiveness while emphasizing regional partnerships and customization to capitalize on the market’s growth potential over the coming decade.
