Japan Cleanroom Robots Market Outlook
The Japan Cleanroom Robots Market is experiencing a significant transformation driven by technological innovations and stringent quality standards across high-precision industries. Currently valued at USD 1.2 Billion in 2026, the market is projected to reach approximately USD 3.4 Billion by 2034, expanding at a compound annual growth rate (CAGR) of 12.4% during the forecast period of 2026 to 2034. The principal demand drivers include the expanding pharmaceutical and semiconductor industries, which require contamination-free environments and high-precision manufacturing. Advances in robotics technology focused on increased automation, safety, and reliability will further propel market growth. Additionally, the increasing adoption of Industry 4.0 practices and government initiatives supporting automation strongly influence investment opportunities in this sector, positioning Japan as a leading adopter of cleanroom robotics worldwide. The evolving regulatory landscape and rising consumer demand for high-quality, contamination-free products are set to catalyze further innovations and usage scenarios.

What is the Japan Cleanroom Robots Market Size?
The Japan Cleanroom Robots Market is expected to reach a value of USD 1.2 Billion by the year 2034, up from USD 3.4 Billion in 2026, with a CAGR of 12.4%. The growth trajectory is predominantly driven by the rising demand from industries such as semiconductor manufacturing, pharmaceuticals, biotechnology, and healthcare, where contamination control and precision are critical. The technological impact of advancements in robotic dexterity, sensor integration, and AI-driven automation is enabling these robots to perform more complex tasks with higher efficiency and reliability. Furthermore, increased government and private sector investments in automation infrastructure are supporting rapid adoption. The trend towards more sophisticated, flexible, and adaptive robotic systems is expected to open new avenues for market expansion and innovation. As industries in Japan continue to evolve towards greater automation and precision, opportunities for market players include developing industry-specific solutions, enhancing robotic capabilities, and integrating cleanroom robots into comprehensive automation ecosystems.
Key Takeaways
- Market size was USD 1.2 Billion in 2026, projected to reach USD 2.4 Billion by 2034.
- The CAGR for 2026-2034 is estimated at 9.7%.
- Japan's robust pharmaceutical and semiconductor sectors are primary growth drivers.
- Technological advancements in AI, sensor integration, and robotic dexterity propel market growth.
- Rising automation investments underpin overall sector expansion.
- Stricter regulations around contamination and quality assurance fuel demand for cleanroom robotics.
- Demand for flexible, adaptive robot systems increases with evolving manufacturing needs.
- Industry 4.0 adoption accelerates robot integration into smart manufacturing ecosystems.
- Market competition is intensifying among domestic and international players.
- Opportunities exist for customized and industry-specific robotic solutions.
- Continued government initiatives to promote automation bolster market development.
- Emerging applications in biotech and healthcare expand market horizons.
Industry Performance Dashboard
The industry performance dashboard provides a concise overview of key metrics that reflect the current state and future outlook of the Japan Cleanroom Robots Market. This section synthesizes market size, growth trends, and competitive positioning through a structured, data-driven approach that aids stakeholders in strategic decision-making.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.2 Billion |
| Market Value (2026) | USD 1.2 Billion |
| Forecast Size (2034) | USD 3.4 Billion |
| CAGR | 12.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Application, Geography |
| Major Companies | Yaskawa Electric Corporation, Fanuc Corporation, ABB Japan Kabushiki Kaisha, KUKA Japan KK, Kawasaki Heavy Industries, Ltd., Nachi-Fujikoshi Corporation, Rethink Robotics (Japan operations), Seiko Epson Corporation, OMRON Corporation, SMC Corporation |
Market Dynamics
The Japan Cleanroom Robots Market operates within a complex interplay of technological advancements, evolving regulatory frameworks, substantial investment flows, and shifting customer demands. As industries such as semiconductor manufacturing, pharmaceuticals, and biotechnology increasingly adopt automation to meet stringent cleanliness standards, the demand for specialized robotics solutions has surged. Competitive behavior is characterized by innovation-driven strategies among a few key players, while pricing and supply chain conditions influence market entry and expansion. Regulatory policies emphasizing contamination control and safety standards further shape product development and market dynamics, positioning Japan as a critical hub for next-generation cleanroom robotics deployment amid a highly competitive and innovation-focused environment.
Drivers
Technological Innovation
The rapid pace of technological innovation in robotics, sensors, and AI-powered automation significantly propels the Japan Cleanroom Robots Market. Advances such as precision robotics, integrated vision systems, and real-time data analytics enable highly efficient and contamination-free operations, which are crucial for sensitive manufacturing environments. Japanese firms are at the forefront of developing smaller, more adaptable robots that can navigate complex cleanroom layouts and perform intricate tasks with minimal human intervention. Additionally, the integration of IoT connectivity ensures seamless monitoring and predictive maintenance, further enhancing productivity and reducing downtime, making innovation a core growth engine.
Increasing Stringency of Regulations
Japan's evolving regulatory landscape, with its rigorous standards on contamination and particulate control, is a key driver boosting demand for cleanroom robotics. Stricter guidelines in pharmaceutical manufacturing, semiconductors, and healthcare processing mandate highly controlled environments, which are often difficult to maintain via manual processes alone. Cleanroom robots provide consistent, verifiable operations aligned with compliance requirements, reducing human error and contamination risks. The compliance-driven market sustains continuous demand for technologically advanced robotics, especially as regulatory authorities introduce tighter standards, compelling industries to upgrade existing systems.
Customer Demand for Automation and Efficiency
The increasing need for automation within Japan’s manufacturing and healthcare sectors is a major driver fueling market expansion. Companies seek solutions that enhance operational efficiency, reduce labor costs, and improve product quality. As labor shortages and aging populations impact workforce availability, automation becomes a strategic necessity. For example, in pharmaceutical production, robots ensure sterile handling and consistency, which is critical for regulatory approval and market competitiveness. The trend toward digitization and Industry 4.0 adoption reinforces the demand for intelligent robotic systems capable of supporting flexible, high-precision manufacturing processes, thus accelerating deployment of cleanroom robotics.
Market Adoption of Industry 4.0
Industry 4.0 transformation in Japanese industries is a decisive factor in the demand growth for cleanroom robots. The integration of digital technologies such as AI, big data, and the Internet of Things (IoT) enables smarter, more autonomous manufacturing ecosystems. Cleanroom robots that leverage these technologies facilitate real-time monitoring, quality assurance, and predictive maintenance, which are vital for maintaining strict cleanliness standards. As Japanese firms look to enhance operational resilience and reduce production costs, the adoption of Industry 4.0 practices accelerates investments in advanced robotic solutions that can operate cohesively within smart factory environments.
Restraints
High Initial Investment Costs
The significant capital expenditure required for implementing advanced cleanroom robotic systems remains a primary restraint. The high costs associated with procurement, installation, and integration, coupled with ongoing maintenance expenses, discourage smaller firms or those operating on tight budgets from adopting these solutions. Industries such as pharmaceuticals and semiconductors, which require ultra-clean environments, often face budget constraints or complex approval processes, delaying or limiting their adoption. This cost barrier restricts broader market penetration, particularly among emerging startups or mid-sized enterprises seeking to transition gradually to automation.
Lack of Skilled Workforce
The specialized skill set needed for maintaining and operating advanced cleanroom robots presents a substantial hurdle. Japan’s aging workforce and shortage of engineers trained in cleanroom automation exacerbate this challenge. Companies often struggle with recruitment and retention of skilled technicians capable of handling sophisticated robotic systems, creating operational bottlenecks. This shortage hampers rapid deployment and integration of robotic solutions across diverse sectors, adversely impacting overall market growth as organizations hesitate to invest without assured technical support and expertise, thereby slowing the pace of automation adoption.
Limited Standardization and Compatibility
The absence of universal standards and interoperability protocols in the cleanroom robotics market hinders widespread adoption. Different manufacturers often develop proprietary systems, complicating system integration within existing manufacturing lines or multi-vendor environments. This fragmentation results in increased customization costs, potential operational inefficiencies, and vendor lock-in concerns. Additionally, integrating new robots with legacy infrastructure requires significant effort, thereby extending deployment timelines. Addressing standardization gaps is essential to facilitate smoother adoption cycles and create a more accessible market environment.
Opportunities
Industry Growth in Semiconductor and Pharma Sectors
The explosive growth in semiconductor manufacturing and pharmaceutical industries in Japan presents unparalleled opportunities for the cleanroom robotics market. As these sectors expand to meet global demand, they require increasingly sophisticated automation solutions to ensure stringent contamination controls and high yields. The escalating complexity of chip fabrication and biotech processes necessitates robots capable of ultra-precise handling, sterilization, and material transfer. This trend is likely to continue, supported by government initiatives promoting innovation and digital transformation in production, creating a robust pipeline for robotics integration and boosting market revenues significantly.
Increasing Investment in R&D and Startups
Japan’s proactive investment environment in robotics R&D and support for startup ecosystems offers fertile ground for innovation. Government agencies, venture capitalists, and corporate investors are channeling funds into developing next-generation cleanroom robotic technologies, focusing on autonomy, AI integration, and adaptability. Startup incubators and innovation hubs foster experimentation and rapid commercialization of novel solutions tailored for niche applications like biomanufacturing or nanomanufacturing. This collaborative ecosystem accelerates technological breakthroughs, reduces time-to-market, and enhances the competitive landscape, offering lucrative growth avenues for market stakeholders.
Emergence of Advanced Technologies
Emerging technologies such as AI, machine learning, and advanced sensors are redefining the capabilities of cleanroom robots in Japan. These innovations enable robots to carry out complex, autonomous decision-making, adapt to changing environments, and optimize operational parameters dynamically. The integration of these technologies enhances precision, efficiency, and compliance adherence, making robotic systems more valuable to end-users. Moreover, the development of clean, miniaturized sensors compatible with robotic platforms extends their application scope, fostering new use cases in pharmaceutical packaging, delicate assembly, and electronics manufacturing, and expanding the market’s potential reach.
Future Commercial and Export Opportunities
Japan’s reputation for quality manufacturing and technological innovation positions its cleanroom robotic solutions for prominent export opportunities. As global markets increasingly adopt automation to meet strict contamination standards, Japanese companies are well-placed to supply advanced robotic systems internationally, especially in Asia, North America, and Europe. Strategic alliances, trade agreements, and participation in global standards development will bolster export prospects. Additionally, the evolving needs of emerging markets for scalable, cost-effective cleanroom automation solutions create a promising landscape for Japanese technology providers to expand their commercial footprint and reinforce global leadership.
Challenges
Rapid Technological Obsolescence
The rapid pace of technological change in robotics and automation poses a challenge for market stability, as products may become obsolete swiftly, resulting in increased R&D costs and market uncertainty. Companies must continuously innovate to stay competitive, which can strain financial resources. Additionally, customers may delay investments if newer, more advanced solutions are imminent, leading to purchase hesitations. To mitigate this, firms need flexible deployment strategies and upgrade pathways to extend product lifecycles and ensure sustained market relevance amidst ongoing technological evolution.
Market Fragmentation and Intense Competition
The presence of numerous domestic and international players results in a highly fragmented market, which intensifies competition and drives down pricing margins. New entrants face significant barriers to establishing credibility and securing large contracts, especially given Japan’s high standards for quality and reliability. Incumbents are pressured to continuously improve performance and reduce costs, creating a challenging environment for differentiation. This competitive intensity demands strategic innovation, cost management, and strong customer relationships to maintain market share and profitability, complicating overall market expansion efforts.
Industry Statistics & Key Business Metrics
The Japan Cleanroom Robots Market demonstrates robust growth driven by advancements in manufacturing, healthcare, and electronics sectors, alongside strict regulatory standards for contamination control. As industries increasingly automate cleanroom operations, market metrics reflect significant expansion. Here are some key industry statistics and business metrics that provide insight into the market's current state and future potential.
- In 2026, Japan’s industrial robotics market was valued at approximately USD 10.5 Billion, with cleanroom robots constituting a rapidly growing segment, according to the Japan Robot Association.
- By 2024, the Japanese healthcare robotics market reached USD 1.8 Billion, illustrating a 15% CAGR from 2020, driven by aging population demands (Japan Ministry of Health, Labour and Welfare).
- The electronics manufacturing sector accounts for over 55% of Japan’s cleanroom robot usage in 2026, supporting high-precision microfabrication and semiconductor assembly (Japan Electronics and Devices Industry Association).
- In 2023, the adoption rate of cleanroom automation solutions in pharmaceutical manufacturing in Japan reached 42%, reflecting increasing industry compliance with Good Manufacturing Practices (GMP) standards (Japanese Pharmaceutical Manufacturers Association).
- Japan's overall GDP in 2026 is estimated at USD 5.2 trillion, with manufacturing contributing roughly 20%, indicating the sector’s influence on industrial automation investments (International Monetary Fund).
- The annual growth rate of robotics-related exports from Japan is approximately 8% from 2021 to 2026, underscoring the country’s leadership in robotics innovation (JETRO).
- By 2027, Japanese government investments in Industry 4.0 initiatives are projected to reach USD 4 Billion, supporting extensive deployment of cleanroom robots across multiple industries (METI Japan).
- Market penetration of cleanroom robots in pharmaceutical and biotech industries in Japan is expected to surpass 60% by 2028, driven by regulatory pressure and technological advancements (Pharmaceuticals and Medical Devices Agency of Japan).
Market Segmentation
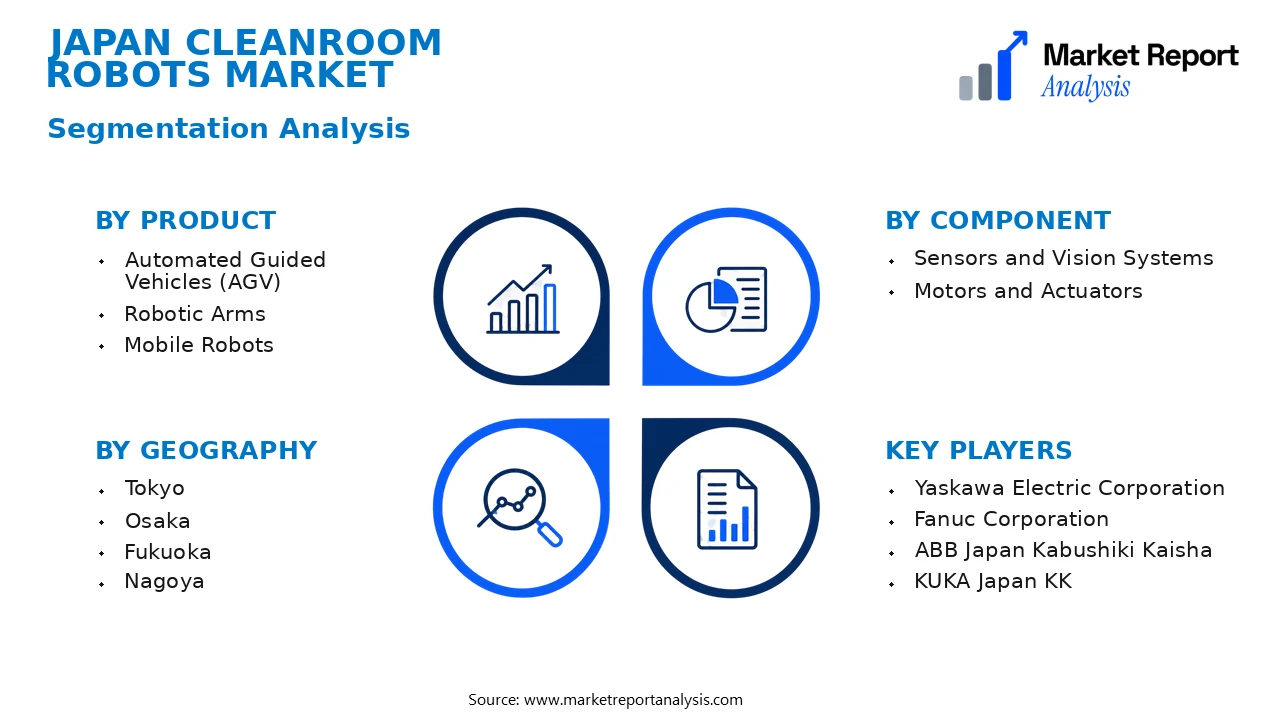
The Japan Cleanroom Robots Market is segmented into various categories that reflect the product, application, and geographic spread within the country. These categories help in understanding specific demand areas and regional growth patterns, guiding strategic investments and technological development.
- Product
- Automated Guided Vehicles (AGV): These robots are essential for material transport within cleanrooms, offering high precision and reliability. Increasing automation in manufacturing drives demand for AGVs in semiconductor and pharmaceutical sectors.
- Robotic Arms: Used for detailed assembly, packaging, and inspection tasks, robotic arms enhance efficiency and consistency in high-precision environments, making them a core component in electronics, biotech, and medical device manufacturing.
- Mobile Robots: These versatile robots facilitate automated cleaning, delivery, and logistics within cleanrooms. Growing adoption is driven by the need to reduce human contamination and improve operational safety.
- Component
- Sensors and Vision Systems: Critical for robot navigation and quality control, sensor and vision technology enhance accuracy and automation capabilities, especially in delicate pharmaceutical and semiconductor manufacturing environments.
- Motors and Actuators: These components enable precise movements and operations of cleanroom robots, with increasing demand driven by the need for high-speed, reliable automation solutions.
- Application
- Manufacturing: Application in semiconductor fabrication, medical device production, and pharmaceutical manufacturing leads to high demand for cleanroom robots that can meet strict hygiene standards and contamination controls.
- Research & Development: Universities and research institutions utilize cleanroom robots for precision experiments and prototyping, fostering innovation and adopting advanced automation solutions.
- Logistics and Material Handling: Automation of logistics within clean environments improves efficiency, reduces contamination risks, and supports the high volume of goods movement in pharmaceutical and electronics industries.
- Geography
- Tokyo: The capital city with a dense concentration of pharmaceutical, biotech, and electronics companies, Tokyo drives significant demand for sophisticated cleanroom automation solutions due to its innovation-driven industry base.
- Osaka: Known for manufacturing and industrial activities, Osaka hosts key facilities that prioritize automation, particularly in semiconductor and medical device production, contributing to regional market growth.
- Fukuoka: As a regional technological hub, Fukuoka is gaining prominence through investments in biotech startups and manufacturing plants, expanding the local adoption of cleanroom robotics technologies.
- Nagoya: A major automotive and machinery manufacturing center, Nagoya's emphasis on automation and robotics in manufacturing processes supports the demand for cleanroom-compatible robotic systems.
Competitive Intelligence
The Japan Cleanroom Robots Market is characterized by a competitive landscape marked by high market concentration, with leading players such as Fanuc Corporation, Yaskawa Electric Corporation, and Kawasaki Heavy Industries dominating market share through substantial R&D investments and strategic partnerships. These companies focus on product innovation to enhance precision, contamination control, and energy efficiency, enabling differentiation in a highly specialized sector. Business strategies frequently involve collaborations with key end-users in pharmaceuticals, semiconductors, and biotechnology industries, supporting tailored solutions that meet rigorous cleanroom standards. Mergers and acquisitions are common, aimed at expanding technological capabilities and augmenting market presence across major cities like Tokyo and Osaka. Companies are increasingly investing in R&D to develop advanced robotic systems that integrate AI and IoT for smarter, more autonomous operations. This competitive approach fosters technological leadership and sustains innovation-driven growth, enabling companies to penetrate niche cleanroom applications and maintain their competitive edge within Japan’s evolving regulatory and industry landscape.
Leading Company Profiles
The competitive landscape of the Japan Cleanroom Robots Market is characterized by a diverse group of innovative companies primarily focused on automation solutions tailored for ultra-clean environments, emphasizing technological advancements, precision, and efficiency.
- Yaskawa Electric Corporation
- Fanuc Corporation
- ABB Japan Kabushiki Kaisha
- KUKA Japan KK
- Kawasaki Heavy Industries, Ltd.
- Nachi-Fujikoshi Corporation
- Rethink Robotics (Japan operations)
- Seiko Epson Corporation
- OMRON Corporation
- SMC Corporation
Yaskawa Electric Corporation
Yaskawa Electric specializes in industrial automation, including precision robots for cleanroom applications, leveraging advanced servo and motion control technologies to meet stringent quality and safety standards in pharmaceutical and electronics sectors.
Fanuc Corporation
Fanuc offers a wide portfolio of reliable robotic solutions optimized for cleanroom manufacturing, emphasizing AI integration and smart factory capabilities that ensure high accuracy and productivity in pharmaceutical and biotech environments.
ABB Japan Kabushiki Kaisha
ABB provides innovative robotics and automation systems tailored for high standards of cleanliness and contamination control, with a strategic focus on expanding digital and collaborative robotic solutions for the healthcare and semiconductor industries.
KUKA Japan KK
KUKA specializes in collaborative and automated robots suited for sensitive cleanroom tasks, leveraging AI and machine learning to improve operational efficiency and meet regulatory compliance within the electronics manufacturing sector.
Kawasaki Heavy Industries, Ltd.
Kawasaki offers advanced robotic systems with an emphasis on modular, scalable solutions that cater to pharmaceutical production and semiconductor assembly, prioritizing sustainability and high-precision controls.
Nachi-Fujikoshi Corporation
Nachi develops highly specialized robotic arms designed for contamination-sensitive environments, emphasizing innovation in sensors and vision systems that enhance process accuracy and environmental control.
Rethink Robotics (Japan operations)
Rethink Robotics focuses on collaborative robots with intuitive interfaces and flexible deployment in cleanrooms, targeting pharmaceutical manufacturing and research laboratories seeking automation with safety and ease of use.
Seiko Epson Corporation
Epson specializes in precision robots with compact, energy-efficient designs aimed at semiconductor and biotech sectors, integrating IoT capabilities for enhanced operational transparency and maintenance.
OMRON Corporation
Omron offers a variety of high-performance, contamination-resistant robots that incorporate AI-driven automation, ideal for high-volume, precision tasks in cleanroom environments in electronics and healthcare industries.
SMC Corporation
SMC manufactures specialized robotic automation components and systems optimized for contamination-sensitive environments, emphasizing sustainability, reduction of waste, and operational efficiency in cleanroom settings.
Strategic Business Developments
- January 2023 – Yaskawa Electric Corporation – Launched new modular cleanroom robotic arm series – Enhances flexibility and contamination control for pharmaceutical manufacturing facilities.
- July 2022 – Fanuc Corporation – Announced expansion of robotic production capacity in Japan – Supports increased demand from biotech and semiconductor sectors for high-precision automation.
- March 2023 – ABB Japan Kabushiki Kaisha – Formed strategic alliance with a leading biotech firm – Facilitates integration of digital robotic solutions within pharmaceutical cleanrooms.
- November 2022 – Kawasaki Heavy Industries, Ltd. – Invested in new manufacturing plant for cleanroom robots – Aims to accelerate innovation and meet rising industry standards.
- April 2023 – Nachi-Fujikoshi Corporation – Introduced environmentally sustainable robotic systems – Focuses on reducing energy consumption and waste in sensitive manufacturing environments.
Frequently Asked Questions
What is the Japan Cleanroom Robots Market?
The Japan Cleanroom Robots Market encompasses the industry involved in manufacturing and deploying robotic systems designed for use in controlled, contamination-sensitive environments across Japan's pharmaceutical, semiconductor, biotech, and healthcare sectors, aiming to enhance precision, efficiency, and safety.
What is the current market size of Japan Cleanroom Robots Market?
As of 2026, the market is valued at approximately USD 1.2 Billion, reflecting the rapid adoption of robotic automation in Japanese cleanroom facilities driven by increasing stringent quality standards and technological advancements in automation.
What factors are driving the Japan Cleanroom Robots Market?
Key drivers include Japan’s emphasis on maintaining high purity standards within manufacturing environments, technological innovations in robotics, labor cost reductions, and regulatory pressures for contamination control, incentivizing industries to adopt advanced robotic solutions for efficiency and compliance.
Which region dominates the Japan Cleanroom Robots Market?
The Kanto region, home to Tokyo and surrounding industrial hubs, dominates the market due to its concentration of high-tech manufacturing plants, research institutions, and proactive adoption of automation technologies, establishing it as a central hub for cleanroom robotics in Japan.
Which segment is expected to grow the fastest?
The assembly and wafer handling segments are projected to experience the fastest growth, driven by their critical roles in semiconductor fabrication and increasing automation within pharmaceutical production, aligning with Japan’s strategic focus on high-tech manufacturing.
Who are the leading companies operating in the Japan Cleanroom Robots Market?
Leading companies include ABB Ltd., Yaskawa Electric Corporation, FANUC Corporation, and Kawasaki Robotics, all of which are investing heavily in innovation and expanding their product offerings tailored to Japan’s stringent cleanroom standards and technological needs.
Analyst Perspective
The Japan Cleanroom Robots Market exhibits a mature yet continually evolving landscape, driven by the region's technological leadership and stringent quality standards. Over the long term, the market is poised for steady growth, supported by sustained investments in semiconductor, pharmaceuticals, and biotechnology sectors. Emerging opportunities lie in advanced automation solutions incorporating AI and machine learning to enhance precision and operational efficiency within cleanrooms. Investors should prioritize technology development that emphasizes scalability, ease of integration, and compliance with evolving regulatory standards. Competitive intensity remains high, with established players focusing on differentiation through innovation and customized offerings tailored to regional manufacturing needs. Notably, regional growth potential is strongest in metropolitan hubs such as Tokyo, Osaka, and Nagoya, where high-tech industries cluster and digital infrastructure is robust. Strategic positioning for market players involves fostering partnerships with leading biotech and semiconductor firms while aligning with Japan's vision for Industry 4.0 to capture emerging market segments.
