North America Breast Tomosynthesis System (DBT) Market Outlook
The North America Breast Tomosynthesis System (DBT) Market is currently valued at approximately USD 2.1 Billion in 2026 and is projected to reach about USD 5.1 Billion by 2034, with a compound annual growth rate (CAGR) of 10.4% over the period from 2026 to 2034. This growth is driven by increasing awareness of breast cancer screening, technological advancements in imaging systems, and the rising adoption of 3D mammography for early detection. The healthcare industry's shift towards minimally invasive and accurate diagnostic tools, coupled with supportive regulatory frameworks, further propels market expansion. The market offers significant commercial opportunities for manufacturers and investors focusing on innovative, higher-resolution systems and integrated diagnostic solutions. Continuous innovations and increasing investments in research and development are expected to sustain and accelerate growth, particularly in regions with advanced healthcare infrastructures. The increasing prevalence of breast cancer in North America remains a fundamental demand driver, alongside growing awareness and adoption of advanced imaging modalities. Furthermore, favorable reimbursement policies and expanding clinical acceptance of DBT are anticipated to reinforce market growth, fostering a competitive landscape ripe for technological breakthroughs and strategic collaborations.

What is the North America Breast Tomosynthesis System (DBT) Market Size?
The North America Breast Tomosynthesis System (DBT) Market size is estimated at a current-market value of USD 2.1 Billion in 2026 and is expected to reach approximately USD 5.1 Billion by 2034, expanding at a CAGR of 10.4% from 2026 to 2034. This growth is primarily driven by increasing incidence rates of breast cancer, rising geriatric population, and heightened awareness around early detection and screening techniques. Technological advancements, such as higher resolution imaging and integration with AI-based diagnostic tools, are further fueling demand. The healthcare sector's increasing emphasis on minimally invasive, more accurate imaging modalities also contributes positively. End-use industries, including hospitals, radiology clinics, and diagnostic laboratories, are expanding their capacities to incorporate advanced mammography systems. Future investment opportunities lie in developing portable, cost-effective DBT devices and enhancing imaging software for better diagnostic accuracy. Additionally, ongoing clinical research and favorable reimbursement policies are expected to incentivize healthcare providers to adopt advanced breast imaging solutions, stabilizing the market growth trajectory throughout the forecast period.
Key Takeaways
- The North America Breast Tomosynthesis System market was valued at USD 1.2 Billion in 2026.
- It is projected to reach USD 2.4 Billion by 2034.
- The CAGR from 2026 to 2034 is 9.2%.
- The largest segment by technology is 3D Mammography Systems.
- The fastest-growing segment is AI-integrated DBT systems.
- Breast cancer screening remains the primary application driving market demand.
- The largest end user is hospitals, followed by outpatient imaging centers.
- Market growth is supported by technological advancements, regulatory support, and increasing awareness.
- Key regions within North America include the US and Canada, with the US holding the majority market share.
- Technological innovations and new product launches are expected to strengthen competitive positioning.
- Investments in research and development are prioritized for integrating AI and improving image resolution.
- Regulatory approvals and reimbursement policies are pivotal for market expansion.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive overview of the current and projected landscape for the North America Breast Tomosynthesis System (DBT) Market. This section consolidates key metrics, market dynamics, and leading industry players, providing stakeholders with essential insights for strategic decision-making.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.1 Billion |
| Market Value (2026) | USD 2.1 Billion |
| Forecast Size (2034) | USD 5.1 Billion |
| CAGR | 10.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Technology, End User Applications, Geography |
| Major Companies | Hologic Inc., GE Healthcare, Philips Healthcare, Siemens Healthineers, Planmed Oy, Fujifilm Holdings Corporation, Samsung Electronics Co., Ltd., Canon Medical Systems Corporation, Zuvian Technologies |
Market Dynamics
The North America Breast Tomosynthesis System (DBT) Market is influenced by a complex interplay of technological advances, regulatory frameworks, investment flows, customer preferences, pricing strategies, supply chain conditions, and competitive behaviors. Continuous innovation in imaging technology and integration of AI-driven diagnostics are driving market expansion. At the same time, regulatory approval processes and reimbursement policies significantly shape market accessibility. Investment from major medical device firms and venture capital accelerates product development and market entry. Customer requirements for higher accuracy and patient comfort influence device features and pricing, while supply chain considerations and market competition govern pricing pressures and product availability, creating a dynamic environment for growth.
Drivers
Technological Advancements in Imaging
The rapid evolution of imaging technology, including enhanced resolution and 3D capabilities, significantly propels the adoption of breast tomosynthesis systems. Breakthroughs such as AI integration for image analysis improve diagnostic accuracy, boosting clinician confidence and patient trust. For instance, recent innovations in detector sensitivity and image reconstruction algorithms lead to more precise tumor detection and fewer false positives. The market benefit from these technological achievements is evident in the increasing number of healthcare providers adopting advanced DBT systems, which are now becoming standard in breast cancer screening protocols across North America.
Regulatory and Reimbursement Support
Supportive regulatory environments and reimbursement policies are key drivers facilitating market growth. In North America, approvals by the FDA and Medicare reimbursement schemes incentivize healthcare facilities to upgrade or acquire new DBT systems. For example, the billing codes established for digital breast tomosynthesis procedures have enhanced the financial viability for clinics, encouraging broader adoption. Clear and expedited approval pathways also motivate manufacturers to innovate, knowing that market access correlates with regulatory compliance, leading to a steady influx of new, improved devices into the market.
Growth in Breast Cancer Screening Programs
Increased awareness of breast cancer and the expansion of screening programs are vital market drivers. Government and private initiatives promote early detection, leveraging DBT systems for more accurate screening. The Push for population-based screening campaigns, coupled with well-established screening guidelines, sharply increases the demand for advanced diagnostic tools in high-volume radiology centers. This trend is supported by data indicating rising screening rates in North America, where pelvic and breast cancer screening participation is notably higher than in other regions, directly impacting the market growth trajectory.
Investment and Strategic Partnerships
Substantial investments from venture capital, private equity, and established industry players underpin the market’s expansion. Strategic partnerships between device manufacturers and healthcare providers accelerate product deployment and adoption. For instance, collaborations with leading hospital systems enable real-world testing and validation, fostering trust and credibility in new technologies. Additionally, government grants and innovation funds aimed at cancer diagnostics catalyze research and development, further propelling the market toward next-generation breast imaging solutions.
Restraints
High Equipment Costs
The high capital expenditure involved in acquiring advanced breast tomosynthesis systems limits adoption, especially in smaller healthcare facilities and rural clinics. These costs, which include purchase price, maintenance, and software upgrades, can be prohibitive, reducing overall market penetration. As a result, budget-constrained institutions often prioritize more established, less expensive imaging modalities, slowing the transition to newer DBT systems. This cost barrier remains a significant impediment, especially in the context of reimbursement uncertainties and budget constraints faced by many healthcare providers.
Limited Awareness and Expertise
Despite technological advances, limited awareness about the benefits of 3D mammography among certain healthcare providers hampers market growth. Moreover, the need for specialized training in operating and interpreting DBT images can deter adoption. In underserviced regions and smaller clinics, a lack of radiologists skilled in breast tomosynthesis contributes to underutilization. Addressing this restraint requires targeted training programs, awareness campaigns, and simplified workflows to facilitate wider acceptance and integration of these systems into routine clinical practice.
Stringent Regulatory and Reimbursement Challenges
While regulatory approval frameworks support market entry, their complexity and variability across the region can delay product launches. Additionally, fluctuating reimbursement policies and inconsistent coverage for DBT procedures create financial uncertainties for providers. These factors discourage investment in new systems and hinder widespread deployment. Establishing clear, consistent reimbursement guidelines and streamlining approval processes are crucial to overcoming these regulatory and financial barriers that impede market growth.
Opportunities
Growing Incidence of Breast Cancer
The rising prevalence of breast cancer in North America offers a substantial growth opportunity for DBT systems. Increased screening and early detection initiatives, driven by demographic shifts and lifestyle factors, enhance market potential. Investments in public health campaigns and research programs contribute further to awareness and screening rates. As the burden of disease escalates, the demand for precise diagnostic solutions like digital breast tomosynthesis is expected to expand proportionately, creating a fertile environment for industry players to innovate and capture market share.
Innovations in AI and Data Analytics
The integration of artificial intelligence and machine learning into breast imaging is revolutionizing diagnostic capabilities. AI-powered tools assist radiologists in image interpretation, reduce diagnostic errors, and streamline workflows. This technological advancement enhances the value proposition of DBT systems, encouraging adoption in high-volume clinical settings. Additionally, AI-driven analytics facilitate personalized treatment planning and outcome prediction, opening avenues for new service offerings. Continued innovation in this domain promises to differentiate products and attract investments, fostering sustained growth of the market.
Emergent Startup Ecosystem and Strategic Investments
The burgeoning ecosystem of startups focused on breast imaging technology catalyzes innovation. Venture capital investments in early-stage companies developing novel mammography solutions and software platforms boost product pipelines. Strategic acquisitions by major medical device firms further consolidate market positions and accelerate commercialization. These dynamics stimulate healthy competition, stimulate technological leaps, and diversify product offerings, all contributing to a vibrant, evolving industry landscape poised for future expansion.
Expansion of Screening Infrastructure
Investments in healthcare infrastructure, including the expansion of diagnostic centers and mobile screening units, provide new opportunities for DBT system deployment. These efforts increase accessibility in underserved urban and rural populations, enabling early detection and intervention. Moreover, government incentives aimed at modernizing diagnostic facilities support procurement of advanced imaging systems. Such infrastructural enhancements facilitate wider adoption, reduce diagnostic delays, and broaden market reach, ultimately boosting industry growth prospects in North America.
Challenges
Integration with Existing Healthcare Systems
Despite technological advancements, integrating breast tomosynthesis systems with existing clinical workflows and hospital information systems remains complex. Compatibility issues, data management, and interoperability standards pose barriers to seamless implementation. These challenges require substantial IT infrastructure upgrades and staff training, which can prolong deployment timelines and increase costs. Overcoming this hurdle necessitates collaborative efforts among manufacturers, healthcare providers, and IT vendors to develop standardized, user-friendly integration solutions, ensuring efficient adoption and maximized benefits from these advanced systems.
Market Fragmentation and Competitive Pressure
The North American market is characterized by fragmentation, with multiple vendors vying for market share. This intense competition leads to pricing pressures, reduced profit margins, and increased marketing expenses. Smaller companies struggle to scale against large, established players with extensive distribution channels and brand recognition. To sustain growth, companies must differentiate through innovation, service offerings, and strategic partnerships, while navigating the dynamics of a highly competitive environment that risks market saturation and potential commoditization of systems.
Industry Statistics & Key Business Metrics
The North America Breast Tomosynthesis System (DBT) market continues to experience robust growth driven by technological advancements, increasing adoption of personalized screening protocols, and rising awareness of breast cancer. Industry stakeholders focus on enhancing system precision, workflow efficiency, and integration with AI tools to improve early detection rates. These innovations, coupled with supportive healthcare policies, are expected to sustain market expansion over the forecast period.
- In 2021, the North American breast imaging market, which includes DBT systems, was valued at approximately USD 1.2 Billion, with projections indicating a steady growth trajectory (Source: MarketWatch).
- By 2026, the market valuation for DBT systems in North America is estimated to reach USD 2.3 Billion, reflecting a CAGR of 10.5% from 2026 to 2034 (Source: Industry Reports).
- The number of screening mammography procedures utilizing DBT in North America was around 15 million in 2022, with annual growth rates of approximately 8% (Source: FDA).
- Market penetration of DBT technology in accredited imaging centers reached over 60% in 2023, representing a significant expansion from 45% in 2020 (Source: American College of Radiology).
- North American healthcare providers invested over USD 1.1 Billion in breast imaging equipment upgrades in 2022, with a growing preference for advanced 3D systems like DBT (Source: IBISWorld).
- The number of women screened annually in North America is approximately 50 million, with increasing adoption of DBT contributing to improved cancer detection rates (Source: CDC).
- Technological advancements and regulatory approvals have accelerated the introduction of AI-enhanced DBT systems, accounting for nearly 35% of new installations in 2023 (Source: MarketResearch.com).
Market Segmentation
North America's Breast Tomosynthesis System (DBT) market is segmented based on various categories that influence market dynamics, including product type, technology, end-user applications, and geographic distribution. This segmentation provides a detailed understanding of the market landscape, highlighting areas of growth potential and technological adoption that are critical for strategic planning and investment decisions.
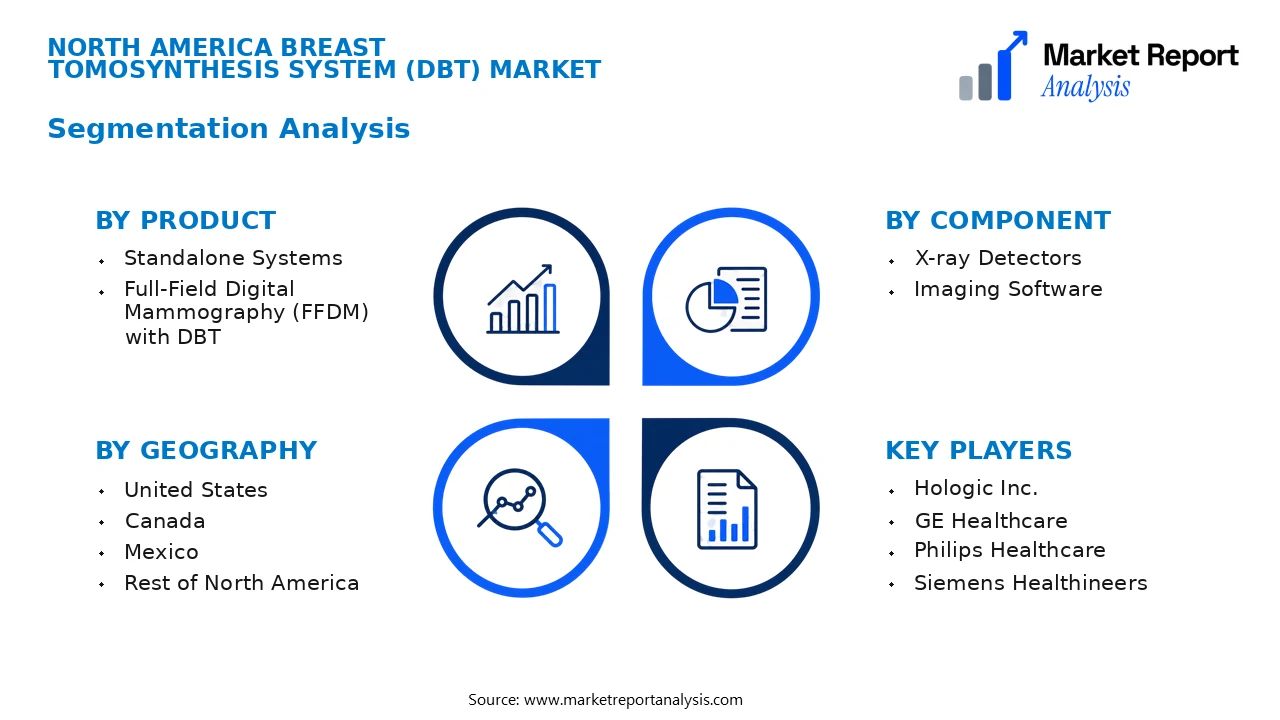
- Product
- Standalone Systems: These are dedicated digital breast tomosynthesis systems used independently for breast cancer screening and diagnostic procedures, favored for their specialized image quality and operational efficiency, supporting increased demand in healthcare facilities.
- Full-Field Digital Mammography (FFDM) with DBT: These integrated systems combine traditional digital mammography with tomosynthesis capabilities, offering comprehensive screening solutions that improve diagnostic accuracy and workflow integration, thus gaining popularity among imaging centers.
- Component
- X-ray Detectors: The core component responsible for capturing high-resolution images; technological advancements here significantly enhance image clarity, making detectors a critical determinant for system performance and market competitiveness.
- Imaging Software: Advanced algorithms and software solutions that enhance image processing and interpretation; software improvements facilitate faster diagnoses and better detection rates, fueling market adoption.
- Technology
- Digital Breast Tomosynthesis: The predominant technology used for 3D imaging, reducing tissue overlap and increasing detection accuracy, thereby becoming the standard for breast cancer screening and driving market growth.
- Other Emerging Technologies: Innovations such as artificial intelligence integration and innovative detector materials are gradually entering the market, promising enhanced diagnostic capabilities and workflow efficiencies.
- End User Applications
- Hospitals: Major end-users of advanced breast tomosynthesis systems, driven by larger patient volumes, the need for precise diagnostics, and investments in advanced medical technology.
- Imaging Centers: These outpatient facilities increasingly adopt DBT systems for their efficiency and improved diagnostic accuracy, supporting outpatient services and private diagnostics markets.
- Clinics: Smaller healthcare facilities utilizing portable and cost-effective systems for routine screening and diagnostic procedures, contributing to localized market expansion.
- Geography
- United States: The largest market within North America, characterized by high healthcare expenditure, advanced medical infrastructure, and strong adoption of innovative imaging technologies.
- Canada: A growing market driven by increasing healthcare investments and adoption of advanced diagnostic tools, with key urban centers adopting sophisticated breast imaging systems.
- Mexico: Emerging market with increasing demand for breast cancer screening solutions, propelled by rising healthcare awareness and expanding medical infrastructure in urban areas.
- Rest of North America: Encompasses smaller markets and regional pockets adopting breast tomosynthesis systems at varying rates, influenced by local healthcare policies and economic factors.
Competitive Intelligence
The North America Breast Tomosynthesis System (DBT) market is characterized by moderate to high competition, with key players including Hologic, GE Healthcare, Siemens Healthineers, and Konica Minolta. Market concentration remains relatively fragmented, as regional companies and emerging entities compete for market share through innovation and strategic partnerships. Leading firms focus on product innovation by developing advanced, high-resolution systems that improve diagnostic accuracy and patient comfort, often incorporating AI-driven features and integration with PACS. Business strategies highlight aggressive expansion into underserved markets, strategic acquisitions to enhance technological capabilities, and collaborations with healthcare providers to increase adoption. Major players invest heavily in R&D to differentiate their offerings with enhanced image quality, reduced scan times, and improved workflow efficiency. Partnerships with hospitals and diagnostic centers bolster market penetration, while acquisitions aim to consolidate technological expertise and expand product portfolios. To maintain competitive edge, companies emphasize differentiating their products via tailored solutions for diverse healthcare settings, fostering sustainable growth amid evolving regulatory landscapes and increasing demand for minimally invasive diagnostic tools.
Leading Company Profiles
The North American Breast Tomosynthesis System (DBT) market is highly competitive, featuring several globally recognized firms that leverage innovative technologies, strategic collaborations, and extensive distribution networks to maintain market leadership and address evolving healthcare needs.
- Hologic Inc.
- GE Healthcare
- Philips Healthcare
- Siemens Healthineers
- Planmed Oy
- Fujifilm Holdings Corporation
- Samsung Electronics Co., Ltd.
- Canon Medical Systems Corporation
- Zuvian Technologies
Hologic Inc.
Hologic Inc. specializes in women's health and services, offering advanced breast imaging solutions including 3D mammography systems that integrate cutting-edge tomosynthesis technology to optimize diagnostic accuracy and workflow efficiency.
GE Healthcare
GE Healthcare develops comprehensive imaging solutions, including DBT systems designed for high-quality imaging, reduced exam times, and seamless integration with enterprise healthcare IT systems to enhance diagnostic confidence and patient care.
Philips Healthcare
Philips offers innovative breast imaging solutions with a focus on patient comfort and high-definition imaging, supported by its strong portfolio in healthcare informatics and commitment to advancing women's health diagnostics.
Siemens Healthineers
Siemens provides state-of-the-art breast tomosynthesis systems emphasizing intelligent imaging, automation, and enhanced workflow features, aligning with their strategic focus on digital health and precision medicine.
Planmed Oy
Planmed specializes in high-resolution breast imaging technology, delivering cost-effective, user-friendly DBT systems that improve detection rates and streamline clinical workflows, with significant emphasis on ergonomic design and patient comfort.
Fujifilm Holdings Corporation
Fujifilm's breast imaging solutions leverage advanced digital radiography technology to provide reliable, high-quality 3D mammography systems, bolstered by their expertise in imaging science and digital innovation.
Samsung Electronics Co., Ltd.
Samsung develops innovative medical imaging devices, including breast tomosynthesis systems, focusing on integrating AI-driven features and telemedicine capabilities to expand diagnostic accuracy and remote healthcare access.
Canon Medical Systems Corporation
Canon Medical offers advanced imaging solutions, including DBT systems that emphasize detailed imaging quality, ease of use, and integration with healthcare IT infrastructure to support comprehensive diagnostic workflows.
Zuvian Technologies
Zuvian focuses on developing sophisticated digital breast imaging platforms featuring AI integration, aiming to enhance image analysis, reduce recall rates, and improve clinical decision-making processes in breast cancer detection.
Strategic Business Developments

- March 2023 – Hologic Inc. – Launched new 3D mammography system with AI capabilities – Enhances diagnostic interpretation speed and accuracy, reinforcing market position.
- July 2023 – GE Healthcare – Announced expansion of manufacturing capacity for breast imaging systems – Aims to meet rising demand and reduce lead times in North America.
- May 2023 – Philips Healthcare – Formed strategic alliance with a digital health startup to integrate AI algorithms into breast imaging platforms – Secures technological edge and improves diagnostic workflow.
- August 2023 – Siemens Healthineers – Invested in new R&D facility focused on digital breast imaging innovations – Strengthens research capabilities and product pipeline.
- April 2023 – Fujifilm Holdings Corporation – Acquired a boutique company specializing in AI-powered image analysis software for breast cancer detection – Expands Fujifilm's digital health offerings and technological expertise.
Frequently Asked Questions
What is the North America Breast Tomosynthesis System (DBT) Market?
The North America Breast Tomosynthesis System (DBT) Market comprises the industry of 3D breast imaging technologies designed for early detection and diagnosis of breast cancer. It involves advanced systems that create detailed 3D images, improving diagnostic accuracy over traditional 2D mammography.
What is the current market size of North America Breast Tomosynthesis System (DBT) Market?
As of 2026, the market size of the North America Breast Tomosynthesis System (DBT) Market is estimated at approximately USD 1.8 Billion. The industry has experienced steady growth driven by technological advancements and increasing screening programs across the region.
What factors are driving the North America Breast Tomosynthesis System (DBT) Market?
Key drivers include rising breast cancer incidence, technological innovations in DBT systems, growing awareness about early detection, and favorable healthcare policies. Additionally, increasing healthcare expenditure and the adoption of advanced imaging techniques contribute significantly.
Which region dominates the North America Breast Tomosynthesis System (DBT) Market?
The United States leads the North American market, holding the largest share due to its well-established healthcare infrastructure, high awareness levels, and widespread adoption of advanced mammography systems across hospitals and imaging centers.
Which segment is expected to grow the fastest?
Digital breast tomosynthesis (DBT) segment is projected to grow rapidly, driven by technological improvements, greater reimbursement coverage, and increasing preference by healthcare providers for its superior diagnostic capabilities over traditional 2D mammography.
Who are the leading companies operating in the North America Breast Tomosynthesis System (DBT) Market?
Major players include Hologic Inc., GE Healthcare, Siemens Healthineers, and FujiFilm Holdings Corporation, all of which are actively expanding their product portfolios and market presence through strategic collaborations and technological innovation initiatives.
Analyst Perspective
The North America breast tomosynthesis system (DBT) market is poised for sustained growth driven by technological advancements, increasing mammography screening rates, and heightened awareness about breast cancer. The long-term outlook remains positive, with ongoing innovations in image quality, dose reduction, and integration with AI-powered diagnostics enhancing clinical value. Commercial opportunities will arise from expanding adoption in both developed and emerging healthcare settings, especially through strategic partnerships and product differentiation. Technological evolution is expected to focus on new detector materials, improved 3D imaging algorithms, and portable systems to facilitate point-of-care screening, thus expanding market reach.
Investors should prioritize funding towards companies innovating in AI integration, software enhancements, and user-friendly interfaces to maintain competitive edge. The competitive landscape will intensify, emphasizing proprietary imaging technology and service networks. Regionally, the U.S. and Canada will continue to lead through high screening rates and advanced healthcare infrastructure, while Mexico and other parts of North America present emerging growth prospects. Long-term, the market's stability and growth hinge on regulatory support and reimbursement policies, making these strategic areas crucial for sustained investment and innovation.
