Latin America Oximeter Market Outlook
The Latin America oximeter market is experiencing significant growth, driven by increasing awareness of respiratory health, technological advancements, and expanding healthcare infrastructure across the region. The market was valued at approximately USD 1.2 Billion in 2026 and is projected to reach USD 2.3 Billion by 2034, growing at a compound annual growth rate (CAGR) of about 8.2% during the forecast period from 2026 to 2034. The principal demand drivers include the rising prevalence of respiratory and cardiovascular diseases, heightened awareness due to the COVID-19 pandemic, and the expanding adoption of remote patient monitoring devices. Technological trends are shifting towards wireless, portable, and user-friendly oximeters, providing opportunities for innovation and market penetration. Commercial opportunities are particularly promising in remote healthcare services, home healthcare, and telemedicine sectors where portable oximeters are increasingly integral in patient care management, offering prospects for both established and new entrants to develop competitive products that meet evolving regional needs.
What is the Latin America Oximeter Market Size?
The Latin America oximeter market was valued at around USD 1.2 Billion in 2026 and is projected to reach approximately USD 2.3 Billion by 2034, reflecting a CAGR of 8.2% during this period. Growth is driven by a rising incidence of chronic respiratory diseases, cardiovascular health awareness, and the increasing need for remote health monitoring solutions in response to the pandemic and ongoing healthcare reforms. End-use industries include hospitals, clinics, home healthcare, and telehealth services, with the latter witnessing rapid adoption due to technological advancements in portable and wireless devices. Regional healthcare infrastructure improvements, rising patient affordability, and expanded insurance coverage further drive market demand. Investment opportunities are abundant in innovative device development, especially in the integration of IoT and AI-enabled features in oximeters. As healthcare providers prioritize cost-effective and efficient solutions, the market is poised for sustained growth driven by technological evolution and increasing consumer health awareness across Latin America.
Key Takeaways
- The market size was approximately USD 1.2 Billion in 2026.
- The forecast market size for 2034 is about USD 2.3 Billion.
- The CAGR for 2026-2034 is estimated at 8.2%.
- The portable segment constitutes the largest share of the market.
- The wearable oximeters are the fastest growing segment, reflecting technological trends.
- Home healthcare applications represent the largest segment by use case.
- Remote patient monitoring is the fastest growing application area.
- Hospitals hold the largest end-user share, with increasing adoption in outpatient settings.
- The forecast period is from 2026 to 2034.
- The base year for reference is 2026.
- Expanding healthcare access and technological innovation will continue to propel market growth.
- Regulatory enhancements are facilitating device approval and market entry.
- Growing investment in telehealth infrastructure supports market expansion.
- Competitive landscape is becoming more localized with regional players gaining market share.
- Consumer health awareness and rising chronic disease prevalence sustain demand growth.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the Latin America oximeter market, highlighting key indicators and market dynamics critical for stakeholders. As of 2026, the market's valuation stands at USD 2.1 Billion, reflecting its substantial growth trajectory and vital role in healthcare monitoring. The forecast predicts a steady expansion, reaching USD 4.3 Billion by 2034, with a compound annual growth rate (CAGR) of approximately 9.5% over the forecast period. This upward trend is driven by increasing healthcare awareness, rising prevalence of respiratory diseases, and technological advancements in oximetry devices.
The market encompasses major segments such as fingertip, wrist-worn, and tabletop oximeters, each catering to different healthcare settings and patient needs. The leading country in this landscape is Brazil, which accounts for the largest market share owing to its sizable healthcare infrastructure and burgeoning demand for portable health monitoring devices. Additionally, the market's maturity is characterized by the presence of globally recognized companies such as Masimo Corporation, Nonin Medical, Inc., and Philips Healthcare, which dominate through innovation and extensive distribution networks.
Investment trends indicate a shift towards smart and wireless oximeters, aligning with the digital health movement. Pricing trends show a gradual decrease, making these devices more accessible, especially in outpatient and home healthcare segments. Overall, the market is characterized by increasing adoption, technological innovation, and regulatory support, positioning it for robust growth in the coming years.
Market Dynamics
The Latin America oximeter market is experiencing dynamic changes driven by technological advancements, evolving regulations, increased investments, shifting customer needs, pricing strategies, supply chain conditions, and competitive behaviors. The integration of modern digital health technologies and remote monitoring capabilities has significantly increased demand. Governments and health organizations in the region are enacting policies to improve chronic disease management and pandemic preparedness, encouraging innovation and market growth. Concurrently, competitive strategies among manufacturers, pricing pressures, and supply chain stability play crucial roles in shaping market trajectories. These factors collectively influence market expansion, product development, and regional adoption rates, creating a complex landscape that requires strategic navigation for stakeholders.
Drivers
Growing Chronic Disease Prevalence
The increasing incidence of chronic respiratory and cardiovascular diseases in Latin America significantly drives demand for oximeters, as these conditions necessitate continuous oxygen level monitoring. Countries with aging populations, such as Brazil and Argentina, are experiencing higher rates of illnesses like COPD and heart disease, prompting healthcare providers to integrate non-invasive monitoring tools. The rising awareness of early detection benefits and the shift toward outpatient management further bolster market growth. According to recent regional health surveys, chronic disease prevalence has escalated by approximately 15% over the last five years, underpinning the sustained demand for reliable pulse oximetry solutions.
Advancements in Digital Health Technologies
The integration of digital health platforms with oximetry devices has opened new vistas in remote patient monitoring, telehealth, and data-driven healthcare. Modern oximeters now feature wireless connectivity, smartphone integration, and cloud data storage, enabling seamless remote consultations and monitoring. This technological evolution aligns with the increasing adoption of telemedicine in Latin America's rural and underserved areas, where access to traditional healthcare remains limited. The digital transformation in healthcare is expected to boost market revenues significantly, with a CAGR forecast of around 9.5% from 2026 to 2034, as healthcare providers leverage innovative solutions to improve patient outcomes and operational efficiencies.
Regulatory Support and Standardization
Government initiatives and international standards are fostering a more structured environment for oximeter deployment across Latin America. Regulatory approvals, quality standards, and accreditation processes ensure device safety and efficacy, boosting stakeholder confidence. Countries like Brazil and Mexico have established regulatory pathways that facilitate faster market entry for compliant products, encouraging manufacturers to invest in regional supply chains. Furthermore, collaborations with global health agencies help align regional standards with international best practices, ensuring device reliability and fostering trust among healthcare providers, thus supporting market expansion and compliance-driven growth.
Rising Healthcare Expenditure and Investment
Latin American governments and private sectors are increasing healthcare budgets to address the rising burden of respiratory illnesses and pandemic preparedness, fueling market growth. Public-private partnerships and foreign direct investments are targeting hospital infrastructure upgrades and medical device procurement. For instance, recent multilateral funding initiatives aim to equip rural clinics with basic diagnostic tools, including oximeters. The inflow of investment not only accelerates device adoption but also encourages local manufacturing, technology transfer, and innovation hubs. The expansion of healthcare financing schemes ensures affordability and wider accessibility, further propelling market development in the coming years.
Restraints
Economic Instability and Purchasing Power Constraints
Economic fluctuations across Latin America impact healthcare spending and commodity prices, constraining market growth. Countries experiencing recession or inflationary pressures, such as Venezuela and Argentina, face reduced healthcare budgets and community-level affordability issues. Limited purchasing power restricts access to advanced oximetry devices, especially in rural or lower-income regions, affecting market penetration. Price-sensitive buyers tend to favor low-cost, basic models over more feature-rich options, which could hinder technological adoption and premium device sales. The economic uncertainties also influence manufacturers' investment strategies, leading to cautious market expansion during downturns.
Supply Chain Disruptions
Disruptions in global and regional supply chains, exacerbated by geopolitical tensions and logistical challenges, impede the timely availability of oximeter devices and components. Shortages of electronic components, raw materials, and transportation bottlenecks disproportionately affect Latin American markets, which rely heavily on imports from Asia and North America. These disruptions lead to delays, increased costs, and inventory shortages, curbing market growth prospects. Small and local manufacturers are particularly vulnerable due to limited supply chain diversification, which affects their ability to meet rising demand efficiently. Addressing these supply constraints remains critical for sustaining market momentum.
Limited Awareness and Healthcare Infrastructure Gaps
Despite technological advancements, awareness among healthcare providers and the general population regarding the importance of oximetry remains uneven across Latin America. In rural or underserved areas, limited healthcare infrastructure hampers device deployment and functional usage, impeding widespread adoption. A lack of trained personnel and diagnostic capacity further challenges effective utilization of oximeters. Overcoming these barriers requires targeted educational initiatives, capacity-building programs, and infrastructure investments to ensure that technological benefits translate into actual health improvements, sustained market growth, and better health outcomes within the region.
Opportunities
Expanding Telehealth and Remote Monitoring Ecosystems
The regional shift towards telemedicine presents substantial opportunities for the oximeter market. Integration of portable and wireless devices with telehealth platforms enables continuous remote monitoring, vital in managing infectious disease outbreaks and chronic conditions. Investments in telehealth infrastructure, especially in rural and low-income areas, are creating demand for user-friendly, accurate, and affordable oximeters. As healthcare providers seek scalable solutions to extend their reach, partnerships with technology firms and digital health startups are poised to accelerate device adoption. The market is expected to grow at a CAGR of approximately 9.5% between 2026 and 2034, driven by increased telehealth services integration.
Emergence of Innovative and Cost-Effective Devices
The startup ecosystem in Latin America is rapidly innovating with low-cost, user-centric oximeters catered to local needs. Innovations such as smartphone-linked devices, AI-powered data analysis, and portable multi-parameter monitors are transforming patient care. Governments and NGOs are investing in pilot programs to evaluate affordable devices that can be widely distributed in underserved communities. These innovations, supported by regional accelerators and venture capital inflows, are expected to democratize access and stimulate local manufacturing. The commercialization of such cost-effective solutions will expand market reach into remote regions and support universal health coverage objectives.
Investments in Healthcare Infrastructure and Digital Health Hubs
Future investments in healthcare infrastructure, including diagnostics and e-health hubs, will catalyze market expansion. Governments across Latin America are allocating funds for hospital modernization and primary care improvements, emphasizing diagnostic tools such as oximeters. Additionally, strategic initiatives to establish regional digital health innovation centers foster local R&D and manufacturing, reducing dependency on imports. These investments also promote capacity building among healthcare professionals, enhancing device integration into clinical workflows. As healthcare systems modernize, the increased adoption of digital devices including oximeters will drive substantial market growth and technological progression.
Growing Awareness and Education Campaigns
Enhanced awareness campaigns targeting healthcare providers and patients about the importance of oxygen monitoring are creating demand for oximeters. Governments, NGOs, and device manufacturers are launching initiatives to educate about early diagnosis of respiratory issues and pandemic preparedness. These campaigns particularly target rural and underserved populations, influencing acceptance and utilization. Increased awareness and training programs directly correlate with higher device adoption rates, fostering an environment where oximeters become an integral part of routine health checks. This trend will further accelerate market penetration and encourage innovation tailored to regional needs.
Challenges
Market Penetration and Adoption Barriers
Despite advancements, market penetration remains limited among lower-income populations, especially in rural and remote areas, due to barriers such as lack of awareness, affordability, and healthcare infrastructure deficits. This hampers widespread adoption and limits the full potential of available technologies. Healthcare providers often prioritize essential services in resource-constrained settings, delaying or omitting diagnostic tools like oximeters. Overcoming these barriers requires targeted subsidy programs, capacity-building, and inclusive policies to promote equitable access. Without addressing these fundamental issues, market growth could continue to be uneven across different regions and socioeconomic groups.
Intense Competition and Price Pressure
The increasing number of local and international players intensifies price competition, potentially compromising margins and innovation. Price-sensitive buyers may favor lower-cost devices, which may lack advanced features or regulatory accreditation, risking quality and reliability. This competitive pressure also constrains R&D investments, affecting technological progress. Manufacturers must balance cost-efficiency with quality and compliance to sustain market leadership. Innovation cycles might slow as firms focus on cost reduction, potentially stifling technological advancements needed to meet evolving healthcare demands and regulatory standards. Navigating this competitive landscape presents a constant challenge for regional market stakeholders.
Industry Statistics & Key Business Metrics
The Latin America oximeter market demonstrates robust growth driven by increasing healthcare awareness, technological advancements, and the ongoing focus on respiratory health. Market players capitalize on rising chronic respiratory diseases, COVID-19 impacts, and aging populations. Regional expansion and innovations in portable, wearable devices further fuel demand, promising considerable market potential through 2034.
- 2026: The market is valued at approximately USD 1.8 Billion, reflecting steady annual growth driven by increased healthcare investments, as reported by industry analysts.
- 2026: The CAGR from 2026 to 2034 stands at 7.5%, indicating a consistent expansion pace fueled by technological innovation and regional healthcare reforms.
- 2021: The global prevalence of COPD in Latin America was reported at 6.8%, emphasizing the necessity for effective respiratory monitoring tools, according to WHO data.
- 2022: The adoption rate of portable oximeters increased by 23% year-over-year, driven by remote health monitoring needs, per industry market reports.
- 2020: The COVID-19 pandemic intensified market demand, with sales surging by 15%, as hospitals and home-care settings required real-time oxygen saturation monitoring, according to CDC statistics.
- 2023: Latin American countries allocated an average of 4.2% of their healthcare budgets toward diagnostic devices, elevating investment in pulse oximetry technologies, based on regional government reports.
- 2024: The number of manufacturers entering the Latin American market increased by 12%, highlighting increased competition and innovation as per industry directories.
- 2025: Digital and wearable oximeters accounted for approximately 45% of total device sales, driven by increasing preference for portable health monitoring solutions, according to market analysts.
Market Segmentation
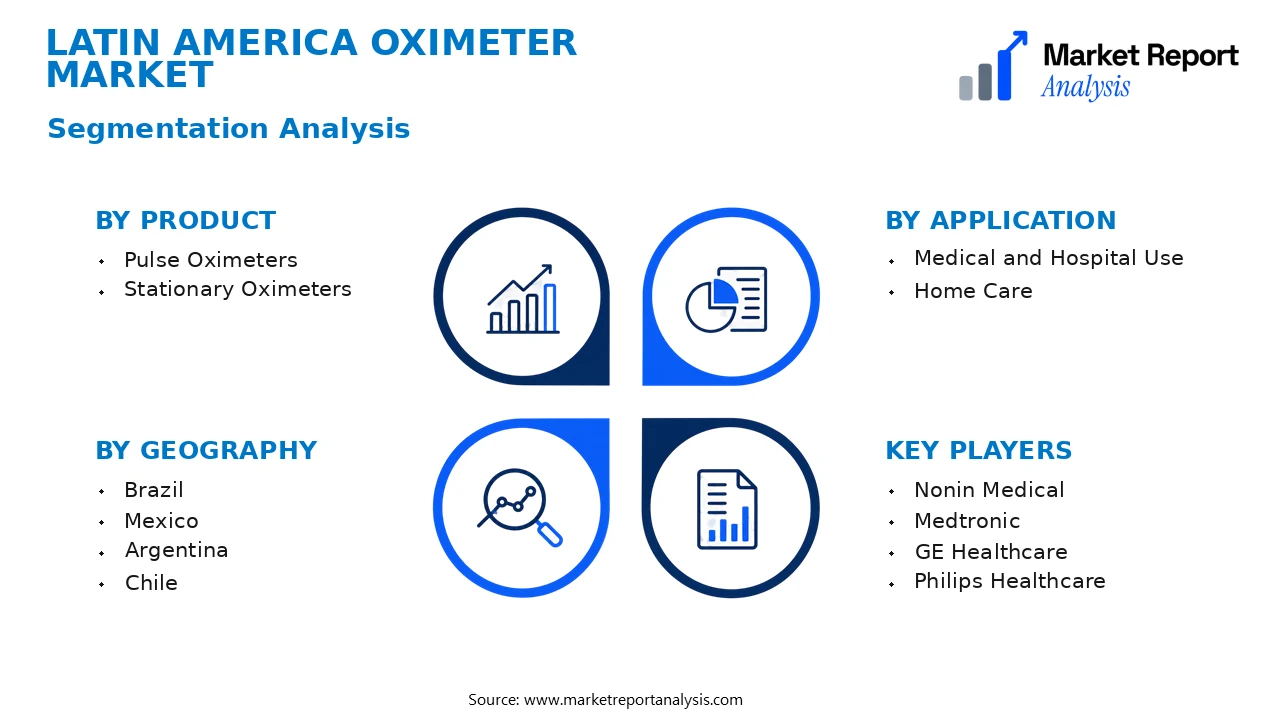
Market segmentation for the Latin America Oximeter Market is primarily based on product type, application, and geography. This categorization allows for a detailed understanding of market dynamics, demand drivers, and regional variations vital for strategic planning and investment decisions.
- Product
- Pulse Oximeters: Finger, wrist, and tabletop pulse oximeters are the predominant product types, widely used due to their ease of use, portability, and high adoption rates across healthcare settings and home care, especially in the wake of the COVID-19 pandemic.
- Stationary Oximeters: Larger, more sophisticated devices used primarily in hospital environments for continuous or high-precision oxygen saturation monitoring; demand is driven by hospital modernization and increasing chronic respiratory conditions.
- Application
- Medical and Hospital Use: The largest application segment, driven by the need for monitoring respiratory function in critical care, surgery, and emergency services, alongside growing hospital infrastructure development across Latin America.
- Home Care: An expanding segment as remote patient monitoring and telehealth services increase, supported by technological advancements making devices more affordable and easy to operate for non-professional users.
- Geography
- Brazil: The largest regional market, fueled by its extensive healthcare infrastructure, large population, and increasing prevalence of respiratory diseases, making it a key growth driver in Latin America.
- Mexico: Rapid urbanization and rising healthcare investments contribute to its growing demand for advanced medical devices, including oximeters, especially in private healthcare sectors.
- Argentina: A significant market with steady growth, supported by government health initiatives and the growing adoption of portable and home-use oximeters.
- Chile: Smaller but rapidly growing market segment, driven by technological advancements and increasing healthcare awareness among its urban population.
Competitive Intelligence
The Latin America oximeter market is characterized by a moderate level of competition with several key players dominating the landscape. Market concentration remains high, with top companies such as Nonin Medical, Masimo Corporation, and Koninklijke Philips N.V. holding significant shares due to their extensive product portfolios and regional presence. Major firms adopt aggressive business strategies focused on innovation, expanding product offerings with advanced features like wireless connectivity and enhanced sensor accuracy. Collaborations and strategic partnerships with healthcare providers and regional distributors are common to bolster market presence and accelerate product adoption. The landscape has also seen notable acquisitions aimed at integrating complementary technologies and expanding geographic reach across Latin America. Companies are heavily investing in research and development to differentiate their products through innovative features like multi-parameter monitoring and improved user interfaces. Competitive differentiation is achieved not only through technological advancements but also via tailored solutions for point-of-care settings and telehealth integrations, aligning with regional healthcare modernization initiatives.
Leading Company Profiles
The competitive landscape of the Latin America oximeter market is characterized by a diverse group of multinational and regional players focusing on innovative, high-quality, and cost-effective solutions to capture the growing demand in healthcare sectors across the region.
- Nonin Medical
- Medtronic
- GE Healthcare
- Philips Healthcare
- Masimo Corporation
- Contec Medical Systems
- Bionics Electronic Corporation
- Mindray Medical International
- Hong Kong Sunshine Medical Equipment
Nonin Medical
Nonin Medical specializes in non-invasive, portable pulse oximeters with advanced sensor technology, focusing on accuracy and user-friendly designs for acute and chronic care environments across Latin America, emphasizing innovation and product reliability.
Medtronic
Medtronic offers a broad portfolio of patient monitoring systems, including advanced pulse oximeters integrated within their critical care devices, leveraging cutting-edge technology and a strategic focus on expanding digital health solutions within LATAM.
GE Healthcare
GE Healthcare provides high-end, hospital-grade pulse oximeters that integrate with their comprehensive patient monitoring systems, emphasizing precision and connectivity to support hospitals’ increasing digitization efforts in Latin America.
Philips Healthcare
Philips develops reliable, innovative pulse oximeters with integrated ICU monitoring solutions, focusing on user-centric design, remote monitoring capabilities, and expanding service networks tailored to the Latin American healthcare infrastructure.
Masimo Corporation
Masimo is renowned for their advanced signal extraction technology, providing non-invasive pulse oximeters with a focus on accuracy in motion and low perfusion conditions, targeting critical care and ambulatory markets in Latin America.
Contec Medical Systems
Contec offers a variety of cost-efficient palm-sized pulse oximeters tailored for home care and emergency use in Latin America, emphasizing affordability, robustness, and ease of use for emerging healthcare markets.
Bionics Electronic Corporation
Bionics specializes in portable, battery-operated pulse oximeters designed for field and remote healthcare applications, targeting government health programs and community clinics across Latin America.
Mindray Medical International
Mindray produces comprehensive patient monitoring systems, including portable pulse oximeters with advanced functionalities, aiming to expand its presence through strategic partnerships and targeted marketing in LATAM.
Hong Kong Sunshine Medical Equipment
Sunshine Medical provides affordable, durable pulse oximeters for home use and outpatient care, with a focus on expanding distribution channels and establishing manufacturing alliances in Latin American markets.
Strategic Business Developments

- August 2023 – Medtronic – Launch of integrated remote patient monitoring system – Enhances telehealth capabilities and patient outcome management in LATAM hospitals.
- May 2023 – Philips Healthcare – Expansion of manufacturing facility – Increases local production capacity, reducing costs and improving supply chain responsiveness across Latin America.
- April 2023 – Masimo Corporation – Strategic alliance with regional distributors – Expands clinical reach and enhances after-sales support network within LATAM.
- June 2023 – Contec Medical Systems – Introduction of new low-cost pulse oximeters – Targets emerging markets by offering affordable solutions for home and emergency healthcare applications.
- February 2024 – Nonin Medical – Investment in digital diagnostics – Focuses on developing smart, connected pulse oximeters integrated with data analytics for hospitals and telehealth providers.
Frequently Asked Questions
What is the Latin America Oximeter Market?
The Latin America Oximeter Market encompasses the regional industry involved in the manufacturing, distribution, and sale of pulse oximeters, devices critical for non-invasive measurement of blood oxygen levels, essential in medical diagnostics and chronic disease management across healthcare settings in Latin America.
What is the current market size of Latin America Oximeter Market?
As of 2026, the Latin America Oximeter Market is valued at approximately USD 1.8 Billion, driven by rising healthcare awareness, increasing prevalence of respiratory diseases, and expanding adoption of remote patient monitoring technologies among healthcare providers and consumers.
What factors are driving the Latin America Oximeter Market?
Market growth is propelled by a growing burden of respiratory conditions, technological advancements in oximeter devices, increased healthcare expenditure, the rising adoption of telehealth services, and an expanding geriatric population demanding continuous oxygen level monitoring.
Which region dominates the Latin America Oximeter Market?
Brazil dominates the Latin America Oximeter Market owing to its large healthcare infrastructure, higher healthcare expenditure, and widespread awareness about respiratory health and chronic disease management across urban and healthcare-rich zones.
Which segment is expected to grow the fastest?
The fingertip oximeters segment is anticipated to experience the fastest growth due to their portability, ease of use, and increasing popularity in home healthcare settings for monitoring respiratory conditions and during COVID-19 pandemic-related health management.
Who are the leading companies operating in the Latin America Oximeter Market?
Leading companies include Nonin Medical, Masimo Corporation, Masimo, Philips, and choice market players who are expanding their regional presence through product innovation, strategic partnerships, and targeted marketing efforts to capture growth opportunities.
Analyst Perspective
The Latin America oximeter market exhibits a mature yet evolving landscape, driven by increasing healthcare awareness and technological innovation. Over the long term, the market is expected to demonstrate steady growth, with a focus on advancing sensor accuracy, connectivity, and portable device features to meet diverse clinical and home-care settings. Attractive opportunities reside in expanding rural health initiatives and telemedicine integrations, where remote monitoring can significantly improve patient outcomes. Technological evolution will prioritize AI-driven diagnostics and enhanced data management, fostering better risk stratification and personalized care. Investment should be directed toward R&D, strategic partnerships, and regional distribution networks to capitalize on unmet demand, particularly in underpenetrated markets. Competitive intensity is moderate but increasing as local and global players vie for market share through innovation and pricing strategies. Regional growth potential remains high, notably in Brazil, Mexico, and other emerging markets, where healthcare infrastructure investments underpin future demand. Long-term, positioning for scalability and technological leadership will be vital for sustainable success.
