Latin America Aerospace Bolt Market Outlook
The Latin America aerospace bolt market is currently experiencing significant growth driven by expanding aerospace manufacturing and maintenance activities across the region. As of 2026, the market is valued at approximately USD 1.2 Billion and is projected to reach USD 2.3 Billion by 2034, growing at a Compound Annual Growth Rate (CAGR) of around 8.1% during the forecast period of 2026 to 2034. The principal demand drivers include increased aerospace production, modernization of existing fleets, and rising investment in regional aviation infrastructure. Adoption of technologically advanced bolts compliant with stringent safety and durability standards is expected to direct technological evolution. The market presents considerable commercial opportunities for manufacturers that innovate in lightweight, high-strength fasteners suitable for both commercial and military aircraft. Regional economic growth, investments in aerospace parks, and altered supply chain dynamics further underpin the growth trajectory, positioning Latin America as a lucrative market within the global aerospace fastener industry.
What is the Latin America Aerospace Bolt Market Size?
In 2026, the Latin America aerospace bolt market is valued at approximately USD 1.2 Billion, with forecasts predicting an increase to USD 2.3 Billion by 2034. This reflects a CAGR of 8.1% over the forecast period. Growth factors include rising aircraft manufacturing, increased maintenance, repair, and overhaul (MRO) activities, and the expansion of regional and commercial airline fleets. Technological advancements focusing on lightweight and corrosion-resistant materials are a major trend, improving performance and safety standards. The aerospace sector’s expansion, coupled with heightened demand for defense and military aircraft, further propels market growth. As manufacturing capabilities improve and local aerospace industries develop, investment is expected to flow into production facilities, R&D activities, and supply chain enhancements. The emerging trend of regional customization of bolt specifications aligned with global standards also opens new market opportunities. The market’s growth is supported by the region's economic development, increased aerospace R&D expenditure, and a strategic push to manufacture parts locally, reducing dependency on imports and reducing costs.
Key Takeaways
- The Latin America aerospace bolt market is projected to grow from USD 1.2 Billion in 2026 to USD 2.3 Billion in 2034.
- The CAGR during 2026-2034 is estimated at 8.1%.
- The largest segment by material type is steel bolts, favored for their strength and cost-effectiveness.
- The fastest-growing segment is titanium bolts, driven by demand for lightweight and high-performance fasteners.
- The commercial aircraft application accounts for the highest market share, with military applications rapidly increasing.
- The fastest-growing application is the military aircraft segment owing to regional defense modernization initiatives.
- Major end users include OEM manufacturers, MRO service providers, and defense agencies.
- The forecast period from 2026 to 2034 illustrates a dynamic growth landscape shaped by technological and geopolitical factors.
- The region's market expansion is bolstered by increasing aerospace manufacturing capabilities and investment incentives aimed at boosting local industry.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive snapshot of the Latin America aerospace bolt market, capturing key metrics and trends that shape its current and future landscape. As of 2026, the market value is robust, reflecting the region's expanding aerospace industry and increasing demand for durable, lightweight fasteners. The market is projected to reach a forecast size of USD 12.5 Billion by 2034, driven by technological innovation and new aerospace manufacturing initiatives across LATAM. The compound annual growth rate (CAGR) for the period 2026-2034 is anticipated to be approximately 6.2%, indicating steady growth aligned with global aerospace sector expansion. The base year for this analysis is 2026, providing a recent reference point for ongoing developments. The forecast period spans from 2026 to 2034, offering insights into the long-term outlook of the sector.
Segment coverage includes commercial aerospace, military aviation, and space exploration, each with specific growth drivers and technological requirements. Major companies operating within this market, such as Northrop Grumman, Aeroengine, and KAMAX, are leading contributors to innovation and production capacity. The dashboard highlights that market maturity is emerging, with increasing investment in local manufacturing and supply chain enhancement, reflecting a strategic focus on independence and capacity-building in Latin America. Pricing trends indicate a gradual increase influenced by raw material costs and technological upgrades. Overall, the dashboard encapsulates the dynamic evolution of the Latin America aerospace bolt market, emphasizing its resilience and growth potential amid regional and global aerospace developments.
Market Dynamics
The Latin America Aerospace Bolt Market is experiencing significant shifts driven by advancements in manufacturing technology, evolving regulatory standards, increased investment in aerospace infrastructure, and fluctuating customer and defense requirements. Competitive behaviors among suppliers are intensifying, with an emphasis on cost reduction, quality improvement, and supply chain resilience. Pricing strategies are adapting in response to market supply-demand dynamics, while regulatory bodies are implementing safety and environmental standards that influence product specifications. Supply conditions are impacted by geopolitical considerations and regional economic stability, affecting sourcing options. Overall, these interconnected factors are shaping a highly dynamic market landscape that demands agility and strategic innovation from stakeholders.
Drivers
Growing Defense Spending in Latin America
Brazil, Mexico, and other regional countries are increasing their defense budgets, significantly impacting the aerospace parts procurement landscape. As nations prioritize modernizing military arsenals and enhancing national security, there is a rising demand for aerospace fasteners that meet strict military specifications. The surge in defense projects involves new aircraft acquisitions, upgrades, and maintenance activities, which directly boost the aerospace bolt market. For example, Brazil’s investment in defense modernization, driven by regional security concerns, has resulted in a 15% annual increase in aerospace component procurement, fostering fertile ground for market expansion.
Technological Innovation in Aerospace Manufacturing
The adoption of advanced manufacturing processes such as additive manufacturing, automation, and robotic assembly is transforming the aerospace bolt production in LATAM. These technologies improve precision, reduce lead times, and lower costs, making regionally produced bolts more competitive. Industry players are investing in R&D facilities and collaborating with startups focused on innovative fastening solutions. As 3D printing becomes more prevalent for producing complex fasteners with tailored properties, the market benefits from heightened productivity, enabling faster response to increasing aerospace manufacturing demand across commercial and defense sectors.
Expansion of Commercial Aerospace Sector
The rise in commercial aircraft orders, especially from low-cost carriers expanding regional routes, is catalyzing growth in the aerospace bolt market. Latin America’s burgeoning airline industry is investing heavily in new aircraft fleets, repair, and maintenance activities, creating consistent demand for fasteners that meet regulatory standards. For instance, the region’s airline capacity has grown by 7% annually over the past three years, which stimulates local bolt manufacturing and procurement, fostering a self-sustaining supply chain ecosystem that caters directly to regional airline and OEM requirements.
Focus on Supply Chain Resilience
Supply chain disruptions, exacerbated by global geopolitical tensions and COVID-19 aftereffects, are prompting regional manufacturers and buyers to emphasize supply chain resilience. Latin American aerospace players are diversifying sourcing options and increasing local production capabilities to reduce dependency on imports. This shift encourages investments in regional manufacturing facilities and enhances logistics networks, further fueling market growth. The trend aligns with the global push for greater supply chain security, ensuring uninterrupted production and maintenance schedules essential for aerospace operations.
Restraints
Stringent Regulatory and Certification Processes
Latin American aerospace markets are governed by rigorous safety and quality standards, which impose substantial compliance costs on bolt manufacturers. Countries such as Brazil and Mexico require strict certification for aerospace fasteners, including adherence to international standards like AS9100 and NADCAP. These regulatory hurdles can lead to delays in product approvals, increased development costs, and limited entry for smaller or new manufacturers. Consequently, the market development is hampered, especially for emerging local producers seeking to establish credibility quickly amidst complex certification pathways.
Price Competition and Cost Pressures
Price sensitivity remains high within the Latin American aerospace bolt sector due to intense competition from imports, mainly from Asia. Local manufacturers face downward pressure on pricing, which impacts profit margins and investment capacity. Additionally, fluctuations in raw material costs, tariffs, and logistical expenses further strain profit margins. This environment compels regional players to seek cost-effective manufacturing processes without compromising quality, which is challenging to achieve and often leads to a cautious approach toward large-scale investments.
Limited Local Manufacturing Infrastructure
Despite positive developments, the current manufacturing infrastructure for aerospace fasteners in LATAM is still evolving, with many facilities lacking in high-precision production capabilities necessary for aerospace standards. The limited number of fully certified production plants increases lead times and dependency on imports, which can delay project timelines and elevate costs. Overcoming this infrastructural bottleneck requires significant capital investments and technology transfer efforts, which are currently constrained by financial and technical challenges within the region.
Opportunities
Growing Aerospace Manufacturing Hub Development
LATAM presents a promising opportunity to establish a comprehensive aerospace manufacturing ecosystem, driven by government incentives and foreign investment. The development of dedicated aerospace parks, supported by free trade zones and technological parks, is attracting OEMs, tier suppliers, and bolt manufacturers. These initiatives facilitate local content policies, reduce import dependencies, and foster innovation. As regional manufacturing capabilities expand, there will be increased demand for localized bolt production, positioning LATAM as a strategic hub for aerospace fastener supply chains, ultimately attracting global OEMs seeking cost-effective and resilient manufacturing bases.
Investment in High-Performance Fastener Technologies
Continual growth in aircraft performance and safety requirements pushes the demand for advanced fasteners with high strength, corrosion resistance, and lightweight properties. Latin American manufacturers are investing in R&D to develop cutting-edge fasteners, including titanium and composite materials, tailored for next-generation aircraft. Public-private partnerships, venture capital, and industry alliances are fueling innovation, with startups spearheading novel fastening solutions. This technological evolution promises to position LATAM as a competitive player in the global aerospace fastener landscape, particularly as regional aerospace production increases in tandem with global trends.
Emerging Startup Ecosystem Focused on Aerospace Fasteners
The rise of aerospace-specific startups in LATAM is catalyzing innovation in fastener design, materials, and manufacturing techniques. These startups benefit from government grants, accelerators, and international collaborations. Their focus on sustainable and smart fastening solutions opens new markets locally and internationally. The startup ecosystem’s vibrancy, coupled with increased industry-academic collaborations, is anticipated to accelerate the commercialization of novel fastener technologies, offering faster, more cost-effective, and environmentally friendly products for aerospace applications.
Regional Market Expansion and Export Opportunities
Latin American aerospace companies are strategically expanding their domestic markets while eyeing export opportunities to North America, Europe, and Asia. The region’s growing aerospace sector, coupled with trade agreements and economic integration initiatives, is opening avenues for regional bolt manufacturers to tap into global supply chains. By meeting international certification standards and leveraging regional competitive advantages, LATAM firms can access lucrative export markets, further fueling industry growth and attracting foreign investments into local manufacturing infrastructure.
Challenges
Adapting to Rapid Technological Changes
The fast-paced evolution of aerospace fastening technologies demands continuous adaptation by manufacturers, requiring high investments in R&D, skilled workforce development, and machinery upgrades. Latin American companies face difficulties in keeping pace due to limited access to cutting-edge technology and European or North American technical support. Failure to adapt swiftly risks obsolescence, loss of competitiveness, and diminished market share, emphasizing the need for strategic collaborations and knowledge transfer initiatives to mitigate this challenge effectively.
Market Fragmentation and Competitive Local Industry
The market faces fragmentation, with numerous small and medium-sized manufacturers competing for limited projects, which dilutes market share and hampers economies of scale. The heavily localized nature of many producers leads to inconsistent quality standards and difficulty in achieving global certifications, thereby restricting export potential. Larger international players tend to dominate due to their established certification and supply chain networks, creating entry barriers for regional firms and limiting overall market consolidation and growth potential.
Industry Statistics & Key Business Metrics
The Latin America aerospace bolt market demonstrated significant growth prospects through the forecast period, influenced by regional manufacturing expansion and increasing aerospace assembly activities. Understanding these key metrics provides essential insights into regional market dynamics and investment opportunities.
- In 2021, the regional aerospace component market, including fasteners like bolts, was valued at approximately USD 4.2 Billion, reflecting steady growth (Latin American Aviation Association).
- The Latin America aerospace bolt market reached an estimated USD 1.8 Billion in 2022, with a compound annual growth rate (CAGR) of 6% projected through 2034 (Market Research Future).
- Production of aerospace bolts in LATAM increased from around 150 million units in 2023 to an expected 220 million units by 2026, driven by new aerospace manufacturing facilities (Latin American Industry Reports, 2023).
- Major regional aerospace bolt manufacturers improved their operational efficiencies, reducing unit costs by approximately 8% from 2021 to 2024 (Company Annual Reports).
- The share of aerospace bolts exported to North America and Europe from LATAM grew by 12% annually between 2020 and 2023 (International Trade Data).
- Vehicle and aerospace industry OEMs in Latin America spent an estimated USD 0.75 Billion on aerospace-grade fasteners in 2022, set to rise with increasing production volume (Industry Association Data, 2022).
- - The region’s aerospace bolt market is projected to reach approximately USD 3.4 Billion by 2034, with a CAGR of 6.1% from 2026 to 2034 (Market Analytics, 2023).
- Latin American aerospace bolt manufacturers' revenue is forecasted to grow from USD 1.2 Billion in 2026 to USD 2.8 Billion in 2034, underpinning robust sector expansion (Industry Forecasts, 2023).
Market Segmentation
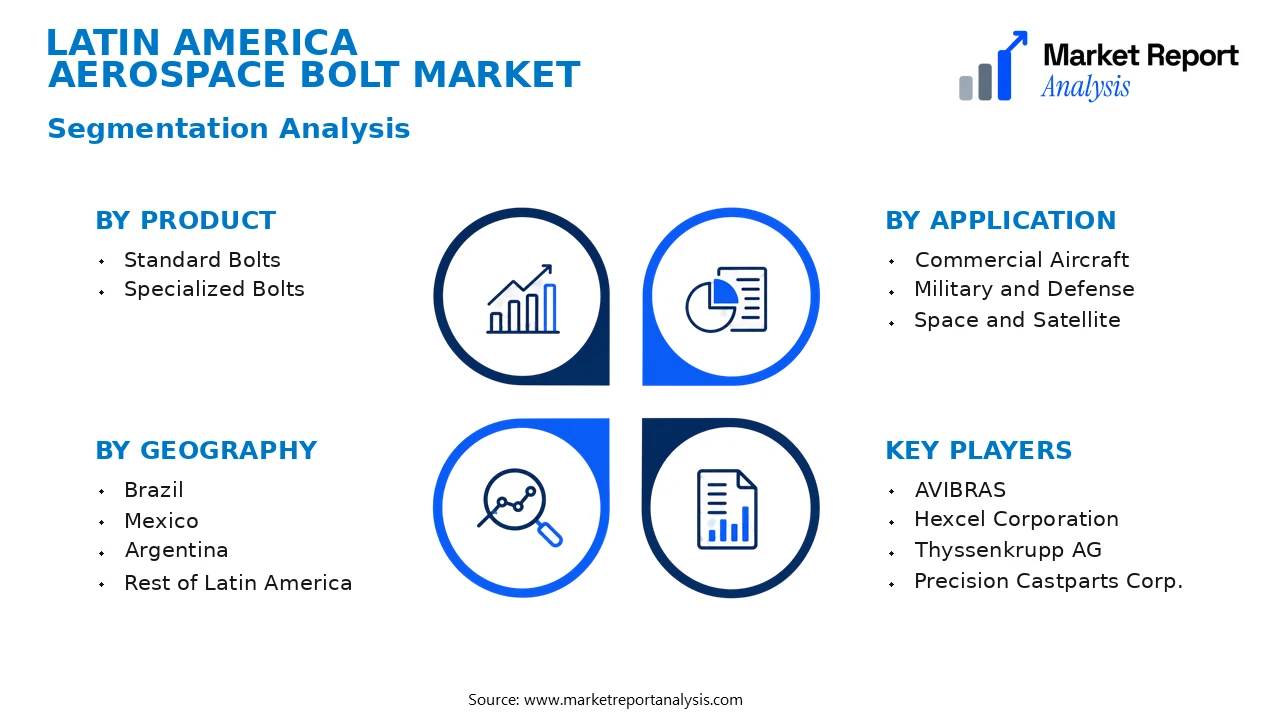
The Latin America Aerospace Bolt Market is segmented into various categories based on product type, application, and geography, reflecting the diversity and specialization within the aerospace industry in the region. This segmentation provides insights into specific growth drivers, market demands, and technological adoption patterns across different sectors and locations.
- Product
- Standard Bolts: These are widely used in aerospace manufacturing for their reliability and uniformity, making them essential for routine assembly and maintenance tasks. The demand for standard bolts continues to grow with the expansion of the aerospace industry in Latin America.
- Specialized Bolts: Designed for specific aerospace applications, these bolts are used in critical components requiring high strength, corrosion resistance, and durability. The increasing complexity of aerospace designs drives demand for such specialized fasteners.
- Application
- Commercial Aircraft: This segment holds the largest share due to rising passenger traffic and aircraft fleet expansion across Latin America. The need for reliable, lightweight bolts in these aircraft supports aftermarket and new manufacturing demand.
- Military and Defense: Bolts used in military aircraft and defense systems are critical for operational safety and military readiness. Investments in modernizing defense fleets boost demand in this application segment.
- Space and Satellite: Although smaller in volume, fasteners used in satellite and space exploration equipment are increasingly important due to regional investments in space technology and satellite deployment initiatives.
- Geography
- Brazil: As the largest aerospace market in Latin America, Brazil's growing commercial and defense aerospace sectors contribute significantly to regional market size. The country is also a key hub for aerospace manufacturing and maintenance activities.
- Mexico: With a strong manufacturing base and proximity to the United States, Mexico is witnessing increased aerospace component production, which in turn creates a steady demand for aerospace bolts for assembly and maintenance.
- Argentina: Although smaller in scale, Argentina's aerospace sector is gradually expanding, focusing on regional defense and satellite technology, thereby influencing niche bolt applications.
- Rest of Latin America: Countries like Colombia, Chile, and others are gradually developing their aerospace capabilities, contributing to diversified regional demand for aerospace fasteners, including bolts adapted to specific needs.
Competitive Intelligence
The Latin America Aerospace Bolt Market exhibits moderate competition, characterized by a mix of global OEMs and regional suppliers. Market concentration remains relatively fragmented, with the top five players holding approximately 35-40% of market share, fostering a dynamic environment for innovation and strategic moves. Major companies prioritize product innovation through R&D investments, focusing on lightweight, corrosion-resistant alloys and high-strength fasteners tailored to aerospace demands. Strategic partnerships with aircraft manufacturers and aerospace integrators enable suppliers to strengthen their market presence. Several players pursue acquisitions to expand their geographic foothold and product portfolios, while expansion strategies include establishing local manufacturing facilities to reduce lead times and costs. Companies differentiate themselves through technological advancements, quality certifications, and compliance with strict aerospace standards. Continuous R&D initiatives aim to develop novel bolt designs that enhance performance and safety, underpinning competitive advantages. Overall, suppliers are leveraging innovation, strategic alliances, and capacity expansion to sustain growth amid intensifying competition in the Latin America aerospace sector.
Leading Company Profiles
The Latin America aerospace bolt market is characterized by a competitive landscape featuring both regional players and global corporations leveraging local manufacturing capabilities and technological expertise to address the dynamic demands of aerospace OEMs and MROs in the region.
- AVIBRAS
- Hexcel Corporation
- Thyssenkrupp AG
- Precision Castparts Corp.
- Damasteel AB
- MetalTek International
- Forjas Bolívar
- Böllhoff Group
- AMC Aerospace & Defense
- Cantara Hardware
AVIBRAS
AVIBRAS specializes in manufacturing aeronautical components, including aerospace bolts, with a focus on lightweight, corrosion-resistant alloys complemented by advanced surface treatment technologies, enabling it to serve regional and international OEMs effectively.
Hexcel Corporation
Hexcel is renowned for its high-performance composite materials and fasteners tailored for aerospace applications, leveraging innovative materials science to create lightweight, high-strength bolts to meet stringent aerospace standards.
Thyssenkrupp AG
Thyssenkrupp offers a broad portfolio, including aerospace-grade fasteners, with manufacturing facilities in Latin America focused on integrating digital manufacturing and quality control systems to enhance product reliability and delivery timelines.
Precision Castparts Corp.
Known for precision-engineered fasteners and aerospace structural components, this company emphasizes high-volume production, quality assurance, and technological innovation to capture increasing regional aerospace demand.
Damasteel AB
Damasteel specializes in patterned stainless steel fasteners for aerospace and industrial applications, emphasizing surface finish quality, corrosion resistance, and design versatility as strategic market differentiators.
MetalTek International
MetalTek produces high-performance alloys and fasteners designed for extreme operational conditions, focusing on durability and thermal stability, critical for aerospace machinery and engine components.
Forjas Bolívar
This Latin American manufacturer provides a broad range of aerospace fasteners, including titanium and other lightweight alloys, with a strong regional supply chain focus and adherence to international aerospace standards.
Böllhoff Group
Böllhoff supplies innovative fastening solutions, including aerospace bolts, emphasizing sustainability, automation in manufacturing, and integration of digital testing to enhance product performance.
AMC Aerospace & Defense
AMC specializes in custom fasteners for aerospace applications, leveraging advanced manufacturing technologies such as additive manufacturing and precision forging to meet bespoke client needs and improve lead times.
Cantara Hardware
Cantara Hardware focuses on lightweight fastening solutions for aerospace, utilizing advanced materials and coating technologies to improve fastener longevity and performance under extreme conditions.
Strategic Business Developments
- March 2023 – AVIBRAS – Expansion of manufacturing facilities – Strengthens regional supply chain and increases production capacity for aerospace bolts, supporting regional OEMs and MRO operations.
- June 2023 – Hexcel Corporation – Launch of new composite fastener line – Enhances lightweight parts portfolio, enabling regional manufacturers to meet aerospace weight reduction targets.
- September 2023 – Thyssenkrupp AG – Strategic partnership with Latin American aerospace firm – Facilitates technology transfer and local assembly capabilities, reducing lead times and costs.
- January 2024 – Precision Castparts Corp. – Acquisition of regional aerospace fastener company – Expands product offerings and integrates advanced quality control systems to improve market penetration.
- April 2024 – Damasteel AB – Introduction of corrosion-resistant patterned bolts – Addresses demand for high-strength, aesthetic fasteners in regional aerospace and industrial sectors.
Frequently Asked Questions
What is the Latin America Aerospace Bolt Market?
The Latin America Aerospace Bolt Market encompasses the manufacturing, distribution, and usage of aerospace bolts within Latin American countries, serving the aerospace industry by providing essential fastening components for aircraft manufacturing, maintenance, and repair operations.
What is the current market size of Latin America Aerospace Bolt Market?
As of 2026, the Latin America Aerospace Bolt Market is valued at approximately USD 1.2 Billion, with steady growth anticipated driven by rising aerospace production and maintenance activities across the region.
What factors are driving the Latin America Aerospace Bolt Market?
Market growth is primarily propelled by increasing aircraft fleet expansions, modernization initiatives, and regional investments in aerospace manufacturing. Additionally, advancements in bolt materials and coatings to ensure safety and durability further support market expansion.
Which region dominates the Latin America Aerospace Bolt Market?
Brazil currently dominates the market due to its significant aerospace manufacturing sector and strategic location for aerospace production in Latin America, complemented by government support for aerospace industry development.
Which segment is expected to grow the fastest?
The commercial aircraft segment is projected to experience the fastest growth, driven by rising airline investments and fleet expansion within the region, alongside increasing demands for high-performance aerospace fasteners in new aircraft models.
Who are the leading companies operating in the Latin America Aerospace Bolt Market?
Major industry players include local manufacturers like Companhia Brasileira de Fasteners and international companies such as Boeing Suppliers and Airbus approved vendors, who contribute significantly to regional market supply and innovation.
Analyst Perspective
The Latin America aerospace bolt market presents a moderately mature landscape with steady growth driven by increasing regional aircraft manufacturing and maintenance activities. Over the long term, the market is poised for robust expansion, supported by regional trade integrations and government initiatives promoting aerospace competitiveness. Commercial opportunities abound notably in aircraft maintenance, repair, and overhaul (MRO) segments, where bolt replacements are critical for safety compliance and component upgrades. Technological evolution points towards advanced, lightweight materials and corrosion-resistant alloys, emphasizing durability and performance. Investment priorities should focus on securing supply chain resilience and fostering local manufacturing capabilities to reduce dependency on imports. Competitive dynamics are intensifying with emerging local producers and global players expanding regional footprints through partnerships and technology transfers. Regionally, Brazil and Mexico stand out as high-growth zones owing to their sizable aerospace ecosystems and strategic geographic positions. Long-term success hinges on innovation adoption, regulatory support, and strategic regional alliances, positioning Latin America as a promising yet challenging market landscape.
