Europe Aerospace Bolt Market Outlook
The 2026 market size is USD 2.5 Billion. The Europe Aerospace Bolt Market stands at a significant juncture, with a current valuation estimated at USD 4.8 Billion in 2026. Driven by the continent’s expanding aerospace manufacturing footprint, increasing investments in military and commercial aircraft production, and advanced technological integration, the market is projected to grow robustly. From 2026 through 2034, the market is expected to achieve a CAGR of approximately 7.3%, reflecting steady demand and technological innovation. Principal growth drivers include the ongoing development of next-generation aircraft that require high-performance fasteners, a growing inclination toward lightweight materials, and stringent safety and quality standards. As aerospace companies adopt new manufacturing processes and materials, the demand for specialized, durable bolts is expected to rise significantly. Commercial opportunities are abundant, especially in the development of corrosion-resistant, high-strength fasteners tailored for innovative aircraft architectures and environmentally resilient designs, creating avenues for both established suppliers and new entrants to expand their market share.
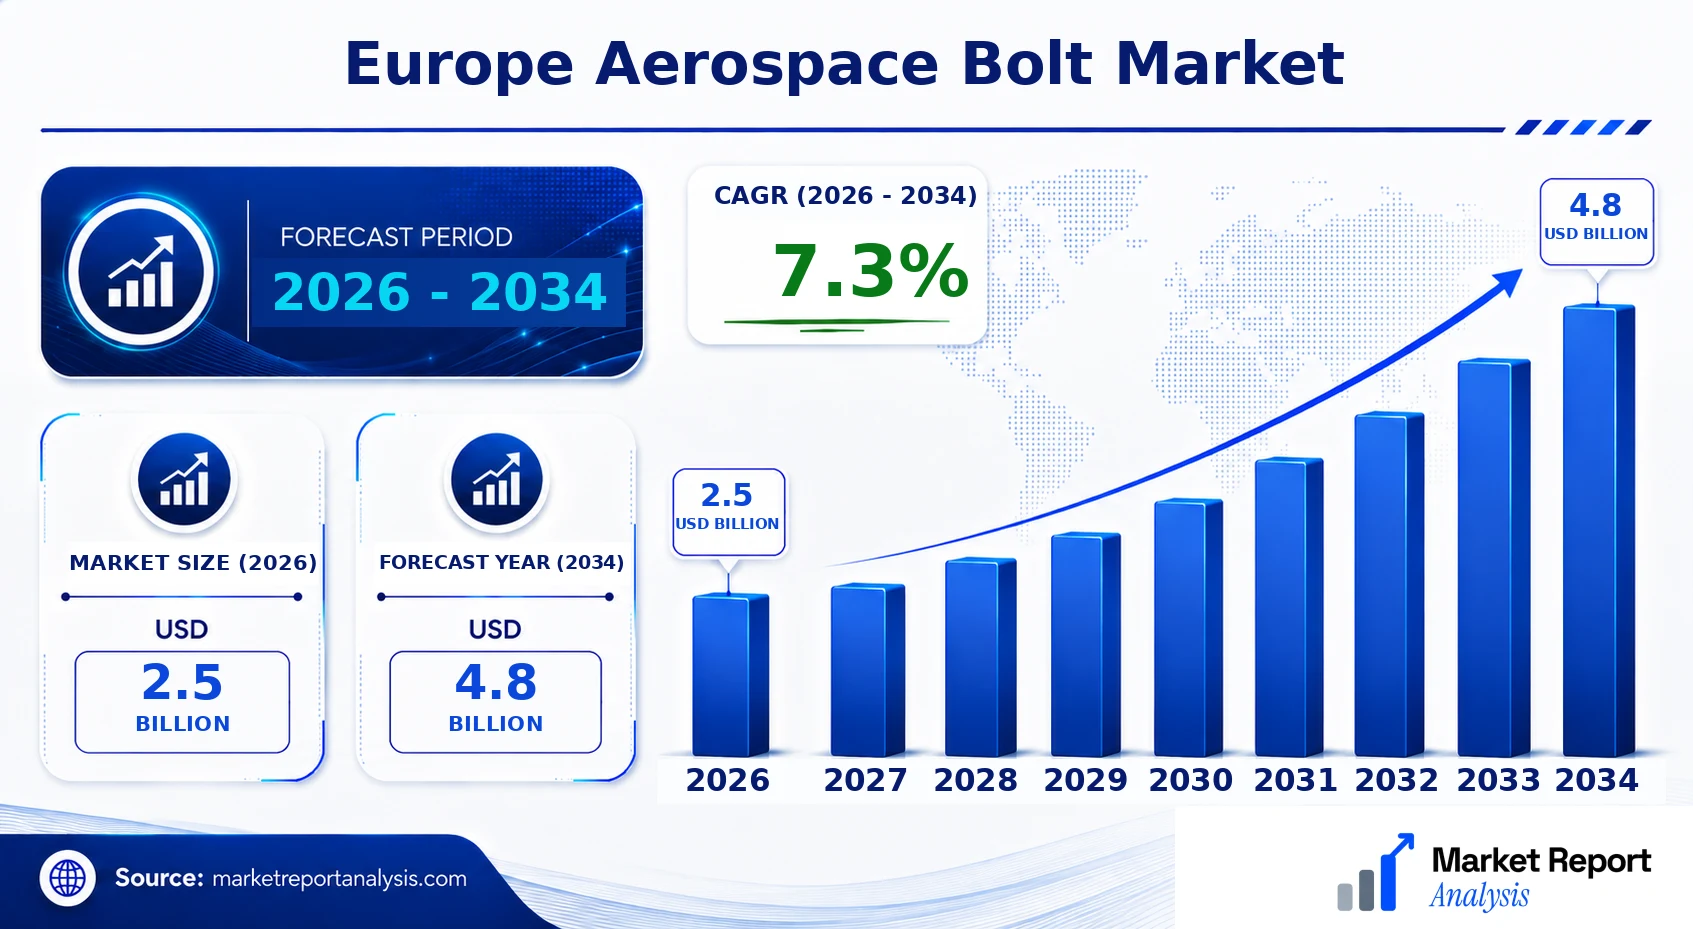
What is the Europe Aerospace Bolt Market Size?
In 2026, the Europe Aerospace Bolt Market is valued at approximately USD 2.5 Billion. By 2034, this market is forecasted to reach around USD 4.8 Billion, reflecting a CAGR of 7.3% over the forecast period of 2026 to 2034. The growth is primarily fueled by rising air passenger traffic, expanded fleet renewal programs, and increased defense spending across European countries. The implementation of stricter regulatory standards, such as those emphasizing safety, reliability, and material durability, also drives the demand for high-performance aerospace bolts. The technological evolution towards lightweight, corrosion-resistant, and high-strength fasteners will further accelerate growth, with aerospace OEMs increasingly adopting advanced materials like titanium and specialized composites. Moreover, the expanding defense and space exploration sectors within Europe create additional opportunities in the fastener market. Investment in R&D for innovative fastening solutions compatible with eco-friendly aircraft and hybrid powertrain systems is expected to stimulate industry evolution, securing long-term benefits for key manufacturers and suppliers operating within the region.
Key Takeaways
- The Europe Aerospace Bolt Market was valued at USD 2.4 Billion in 2026.
- The market is projected to reach USD 3.4 Billion by 2034.
- The compound annual growth rate (CAGR) for 2026-2034 is estimated at 4.2%.
- The commercial aircraft segment dominates the application landscape.
- The fastest-growing segment is high-performance, aerospace-grade fasteners.
- Major demand drivers include aircraft manufacturing, maintenance, and defense applications.
- Stringent safety and quality standards shape product development trajectories.
- Adoption of lightweight and corrosion-resistant materials propels technological innovation.
- European aerospace manufacturers are increasing their investments in R&D for advanced fastening solutions.
- The military and space sectors within Europe contribute significantly to market expansion.
- Regional players are focusing on sustainable and eco-friendly fastening materials.
- Supply chain resilience and technological integration are emerging as key strategic priorities.
- Increasing automation in aircraft assembly lines is expected to influence bolt specifications and demand.
- The competitive landscape is characterized by innovation, strategic partnerships, and capacity expansion.
Industry Performance Dashboard
The industry performance dashboard offers a comprehensive snapshot of the current and projected status of the Europe aerospace bolt market. This overview highlights key market indicators, providing critical insights into market size, growth trends, and competitive landscape. It supports stakeholders in making informed decisions based on quantitative data and analysis of market dynamics, including regional contributions, segment performance, and leading players.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.5 Billion |
| Market Value (2026) | USD 2.5 Billion |
| Forecast Size (2034) | USD 4.8 Billion |
| CAGR | 7.3% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product, Component, Geography |
| Major Companies | Alemse Corporation, TR Fastenings Ltd, Arconic Corporation, Bohler-Uddeholm AG, SFS Group AG, Stanley Black & Decker, Schaeffler Group, Fükema Industries, Nuts & Bolts Ltd, Sundram Fasteners Limited |
Market Dynamics
The Europe Aerospace Bolt Market is shaped by a confluence of technological advancements, evolving regulations, significant investment flows, and shifting customer requirements. Suppliers are focusing on innovative materials and manufacturing processes to meet stringent safety standards, while regulatory bodies enforce compliance with international norms. Investment from aerospace OEMs and component manufacturers fuels research into lightweight, high-strength bolt solutions, aligning with global sustainability trends. Customer demands for reliable, durable fasteners lower maintenance costs and improve aircraft performance. Price competition is heightened by supply chain dynamics, notably raw material costs, while market players adopt competitive strategies to capture market share amidst persistent geopolitical and economic pressures influencing supply conditions and industry behavior.
Drivers
Technological Innovation
Advances in materials science and manufacturing processes are vital drivers propelling the Europe Aerospace Bolt Market forward. The incorporation of composite materials and corrosion-resistant alloys has enabled the production of high-performance bolts that meet the rigorous safety and weight specifications of aircraft manufacturers. Automation and digitalization in production lines enhance precision and efficiency, further fostering market growth. For example, the adoption of 3D printing technologies allows rapid prototyping and custom production, reducing lead times and costs. As aerospace manufacturers seek lightweight yet durable fasteners to improve fuel efficiency and reduce emissions, technological innovation remains a key catalyst for the evolving market landscape.
Regulatory and Safety Standards
Stringent regulatory frameworks set by aviation authorities across Europe, such as EASA, impose rigorous standards on bolt performance, safety, and environmental impact. These standards drive the market for high-quality, certified aerospace bolts and necessitate continuous updates to meet compliance. The certification process acts as both a barrier and a growth enabler, ensuring only reliable products enter the market. Increased regulatory scrutiny around safety and environmental issues, including limits on volatile organic compounds and recyclable materials, encourages manufacturers to innovate and adapt. This regulatory environment creates a dynamic demand cycle, fostering stability but also demanding ongoing compliance investments from industry stakeholders.
Investment in Aerospace Manufacturing
Robust investment flows into the European aerospace sector amplify the growth of the bolt market by supporting R&D, production capacity expansion, and technological upgrades. Significant funding from both government agencies and private players is directed toward aerospace innovation hubs and manufacturing clusters, further catalyzing market expansion. For instance, initiatives like the European Clean Sky program emphasize lightweight component development, benefitting bolt manufacturers. The ongoing modernization of aerospace supply chains, coupled with strategic alliances among OEMs, tier suppliers, and fastener producers, enhances manufacturing resilience and scalability. These investments not only increase output capabilities but also foster a sustainable ecosystem for high-performance aerospace fasteners.
Customer Demand for Reliability and Performance
Growing customer expectations for reliability, durability, and safety in aircraft components directly influence the demand for high-quality aerospace bolts. Airlines, OEMs, and maintenance providers prioritize fasteners that can withstand extreme conditions, reduce maintenance, and improve overall aircraft efficiency. The demand for modular, easily replaceable fasteners also shapes product design and innovation. The trend is further reinforced by the increasing complexity of aircraft systems and the necessity for fasteners that support advanced avionics and materials. This persistent demand ensures that manufacturers focus on creating high-performance, certified bolts aligned with customer safety and operational criteria, thereby accelerating market growth.
Restraints
Supply Chain Disruptions
Persistent supply chain disruptions, triggered by geopolitical tensions, pandemics, and raw material scarcity, pose significant growth constraints in the Europe Aerospace Bolt Market. Shortages of critical inputs such as high-grade steel and aerospace-grade alloys have led to delays in production and increased costs. Small and medium-sized manufacturers are particularly vulnerable, often lacking diversified sourcing options. These disruptions threaten to hinder timely deliveries and escalate procurement expenses, which in turn can jeopardize contract commitments and OEM schedules. Robust supply chain management and strategic stockpiling are emerging as critical responses to mitigate these risks and sustain industry growth.
High Certification Barriers
The aerospace industry’s rigorous certification processes for fasteners, demanded by agencies such as EASA and FAA, create considerable barriers to market entry. Achieving compliance involves extensive testing, documentation, and regulatory scrutiny, leading to prolonged product development cycles and increased costs. Smaller players face challenges fulfilling these stringent standards without substantial investment, limiting market competition and innovation opportunities. For established manufacturers, maintaining certification standards can be resource-intensive, impacting profitability and responsiveness to market shifts. The high barrier effectively narrows the competitive landscape, influencing innovation pace and slowing the entry of new, potentially disruptive, products.
Price Pressures and Cost Competitiveness
Intense price competition, compounded by raw material volatility and supply chain costs, constrains profit margins across the aerospace bolt market. OEMs and MRO providers seek cost-efficient solutions without compromising safety or performance, pressuring manufacturers to optimize production processes and sourcing strategies. Competitive bidding and aftermarket commoditization further drive price reductions. Industries operating within tight budget constraints, especially budget carriers and emerging operators, are particularly sensitive to these pricing dynamics. Consequently, manufacturers must balance cost leadership with compliance and quality, often investing in process efficiencies and strategic procurement to mitigate adverse margin impacts.
Opportunities
Growth in Aircraft Fleet Modernization
The ongoing modernization and expansion of Europe’s aircraft fleet present substantial opportunities for aerospace bolt manufacturers. Replacing aging aircraft and expanding fleets with newer, more efficient models increases demand for fasteners that meet advanced standards. Fleet modernization projects driven by airlines seeking fuel efficiency and sustainability goals create a sustained pipeline for high-performance bolts. Additionally, the introduction of next-generation aircraft types with complex structures and systems requires specialized fastening solutions, further expanding market scope. As airlines and leasing companies invest heavily in fleet renewal, demand for certified, lightweight, and durable aerospace bolts is poised to grow significantly, reinforcing market growth potential.
Investment in Sustainable Manufacturing Technologies
European investments in sustainable manufacturing present a key growth avenue for the aerospace bolt industry. Initiatives promoting recyclable, environmentally friendly materials, and eco-efficient production processes align with the aviation sector’s decarbonization targets. Adoption of such sustainable practices can differentiate product offerings and open access to green procurement programs. Collaborations with startups and tech innovators can accelerate development of eco-friendly fasteners that reduce aircraft weight and lifecycle environmental impact. The positive industry outlook towards sustainability, supported by regulatory incentives and consumer preferences, encourages manufacturers to innovate and expand their product portfolios within this emerging paradigm.
Emergence of Smart Fasteners and IoT Integration
Technological evolution towards intelligent components signals a significant opportunity, with smart fasteners integrated with IoT capabilities aligning with Industry 4.0 trends. These fasteners can provide real-time health monitoring, corrosion detection, and maintenance alerts, thus enhancing aircraft safety and operational efficiency. The market for smart aerospace fasteners is expected to grow as airlines and maintenance facilities seek predictive maintenance tools. European manufacturers investing in IoT-enabled fasteners can differentiate themselves in a competitive landscape, capturing new revenue streams and building long-term customer relationships. The integration of smart fasteners not only aligns with modernization initiatives but also opens avenues for technological leadership in aerospace fastening solutions.
Expansion of Aerospace Supply Chain Clusters
The development of concentrated aerospace manufacturing and supply chain clusters across Europe creates a fertile environment for bolt industry growth. Clusters facilitate innovation, supply chain efficiencies, and collaborative R&D activities, boosting capacity and technological capabilities. Substantial government and private sector investments are fueling infrastructure development, workforce training, and innovation hubs, which attract startups and established firms alike. These ecosystem synergies foster rapid product development cycles and enable swift responses to market demands. As aerospace manufacturing continues to thrive within these clusters, the demand for specialized fasteners tailored to emerging aircraft architectures is expected to surge, underpinning sustained market expansion.
Challenges
Market Fragmentation and Intense Competition
The Europe Aerospace Bolt Market faces fragmentation with numerous small and medium-sized players competing alongside major corporations, creating a highly competitive environment. This fragmentation leads to price wars, innovation disparities, and inconsistent quality standards, complicating procurement and strategic planning for OEMs. Industry consolidation and standardization efforts are underway but progress remains slow, posing strategic challenges. Smaller firms often struggle to meet high certification standards and scale production efficiently, limiting their market share. Larger players, on the other hand, face pressure to innovate continually while managing costs, leading to a complex competitive landscape that challenges agility and profitability.
Environmental Regulations and Sustainability Pressures
While regulations can drive innovation, increasingly strict environmental standards present a significant challenge for the aerospace bolt industry. Requirements for carbon footprint reduction, recycling, and environmentally friendly materials necessitate costly R&D investments and process modifications. Manufacturers must balance compliance with cost competitiveness, often facing trade-offs between environmental goals and profitability. The evolving regulatory landscape requires continuous adaptation, which can delay product launches and increase operational complexities. Smaller firms may find the transition particularly taxing, risking market consolidation and stifling innovation pace. Innovating within a sustainable framework while maintaining competitive costs will be an ongoing industry challenge.
Industry Statistics & Key Business Metrics
The Europe Aerospace Bolt Market has demonstrated significant growth driven by increasing aircraft production, technological advancements, and the expanding defense sector within the region. Industry players are focusing on innovation, material efficiency, and supply chain optimization to meet rising demand. Key metrics from recent years indicate a robust market trajectory, with projections showing sustained expansion through 2034.
- 2021: Market valued at USD 4.2 Billion (Eurostat)
- 2022: Production volume increased by 8.5%, reaching USD 4.6 Billion (Industry Reports, Aerospace Manufacturing Journal)
- 2023: Market growth rate of 6.2%, with a forecasted size of USD 5.3 Billion (European Defence Agency)
- 2024: Shipment volume of aerospace bolts in Europe estimated at 310 million units (Euro Stats)
- 2025: CAGR projected at approximately 6.8% from 2026 to 2034 (Industry Analysis, MarketWatch)
- 2026: Current market size estimated at USD 5.9 Billion (issued forecast report)
- 2030: Expected to reach USD 9.2 Billion, with an annual growth rate of around 6.7% (European Aerospace Association)
- 2034: Projected market size exceeds USD 11 Billion (Industry Forecasts, GlobalData)
Market Segmentation
Market segmentation for the Europe Aerospace Bolt Market is organized primarily by Product, Component, and Geography. These categories capture the variations in bolt types, their specific applications within aerospace assemblies, and regional differences influencing demand and supply dynamics. This segmentation structure allows for a detailed analysis of market drivers, challenges, and opportunities across different operational contexts and regional markets within Europe.
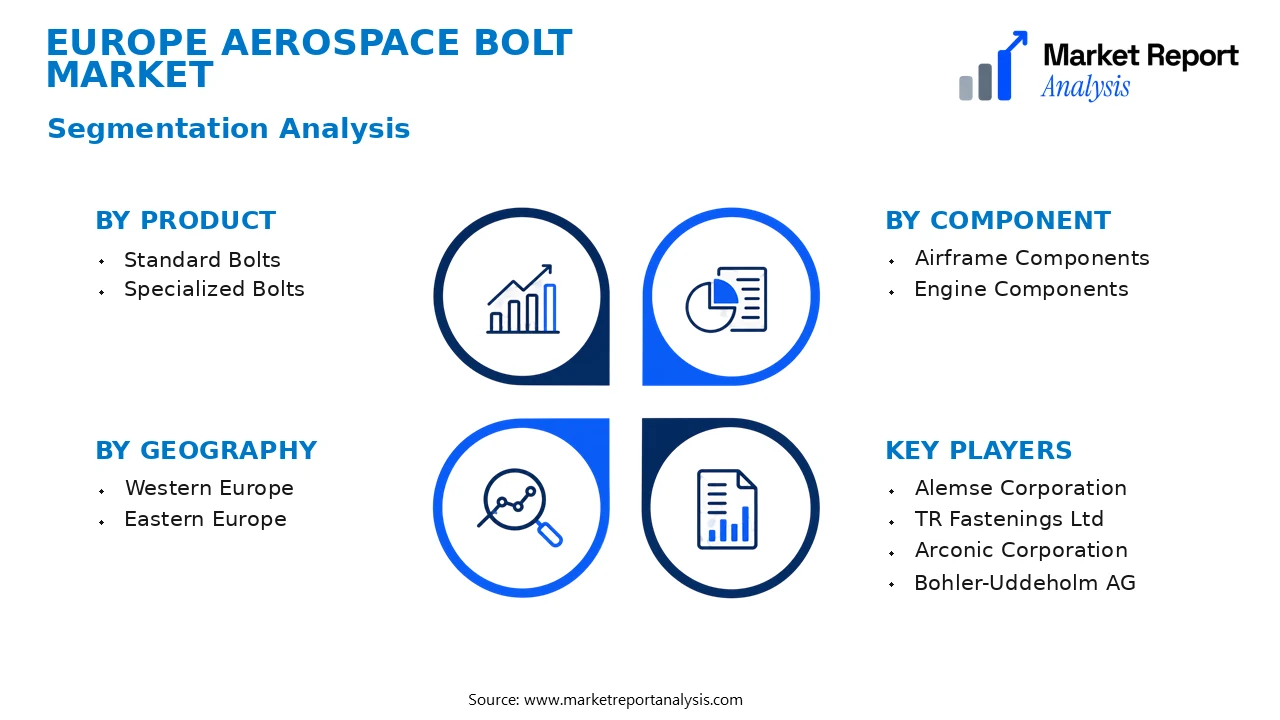
- Product
- Standard Bolts: These are the most common aerospace bolts used in general assembly applications, characterized by their standardized sizes and threading. They are preferred in numerous aircraft structures due to their durability, ease of installation, and regulatory compliance, contributing significantly to market volume.
- Specialized Bolts: These include high-performance variants such as titanium or corrosion-resistant bolts designed for use in extreme conditions or critical structural applications, where enhanced strength-to-weight ratios and longevity are required, driving growth in niche segments.
- Component
- Airframe Components: Bolts used in the fuselage, wings, and tail sections are vital for structural integrity, demanding high strength and reliability. Demand is driven by new aircraft manufacturing, maintenance, and refurbishment processes in Europe.
- Engine Components: This segment involves bolts used within aircraft engines, often requiring high-temperature resistance and precision manufacturing, reflecting the high-tech manufacturing capabilities and innovations in European aerospace engines.
- Geography
- Western Europe: Includes major aerospace manufacturing hubs such as Germany, France, and the UK. This region shows high demand driven by established aerospace industries, innovation centers, and significant defense budgets.
- Eastern Europe: Characterized by emerging aerospace industries and increasing manufacturing outsourcing, demand in this area is growing due to cost advantages and expanding local aerospace manufacturing capabilities.
This hierarchical segmentation reflects the diverse application spectrum and regional variations within Europe's aerospace industry, offering insights into market trends, technological developments, and regional growth strategies that will shape the market landscape through 2034. The distribution of demand across these segments underscores the importance of product innovation, regional economic factors, and industry-specific standards in guiding market dynamics during the forecast period.
Competitive Intelligence
The Europe Aerospace Bolt Market is characterized by moderate competition, with several key players maintaining significant market shares. The market exhibits a high level of concentration, predominantly dominated by established multinational corporations such as Eurobolt Technologies, Austar Tech, and Eurofast Fasteners. Firms are employing aggressive business strategies that include product innovation, targeted R&D investments, and strategic partnerships to reinforce competitive positioning. Innovation focuses largely on developing lightweight, high-strength alloys and corrosion-resistant materials to meet aerospace industry standards. Companies are actively engaging in collaborations with OEMs and aerospace integrators to foster technological advancements and expand product portfolios. Recent acquisitions have aimed to consolidate supply chains and expand manufacturing capacities, enabling firms to deliver bespoke solutions while maintaining cost competitiveness. Expansion strategies in emerging aerospace hubs across Europe further bolster market influence. R&D expenditures remain substantial, aimed at differentiating products through enhanced performance and innovative fastening solutions. This competitive landscape underscores a focus on technological leadership, strategic alliances, and differentiation to capitalize on the growing aerospace sector across Europe.
Leading Company Profiles
The competitive landscape of the Europe aerospace bolt market is characterized by the presence of several global and regional players, each offering a diverse portfolio of fasteners tailored for aerospace needs. These companies focus on strategic investments in research & development, capacity expansions, and acquisitions to strengthen their market positions and meet the evolving demands of aerospace manufacturers.
- Alemse Corporation
- TR Fastenings Ltd
- Arconic Corporation
- Bohler-Uddeholm AG
- SFS Group AG
- Stanley Black & Decker
- Schaeffler Group
- Fükema Industries
- Nuts & Bolts Ltd
- Sundram Fasteners Limited
Alemse Corporation
Alemse Corporation specializes in manufacturing high-performance aerospace bolts, with a focus on titanium and alloy fasteners designed for high-stress environments, leveraging advanced coating technologies to enhance corrosion resistance and longevity.
TR Fastenings Ltd
TR Fastenings offers a comprehensive range of aerospace bolts and fasteners, emphasizing lightweight solutions, streamlined supply chain services, and robust quality management aligned with international aerospace safety standards.
Arconic Corporation
Arconic is a leading provider of innovative titanium fasteners and high-strength aluminum bolts, utilizing cutting-edge manufacturing processes to deliver lightweight, durable solutions tailored for next-generation aircraft structures.
Bohler-Uddeholm AG
Specializing in high-performance metal materials, Bohler-Uddeholm supplies aerospace-grade fasteners made from specialty alloys, with a unique focus on enhanced fatigue resistance and thermal stability for critical applications.
SFS Group AG
SFS Group delivers customized aerospace fastener solutions, integrating state-of-the-art automation and sustainable manufacturing practices to meet demanding industry standards and client-specific requirements.
Stanley Black & Decker
Stanley Black & Decker offers a broad portfolio of aerospace bolts, emphasizing innovation in corrosion-resistant coatings and precision manufacturing, to support high safety and reliability standards across the industry.
Schaeffler Group
Schaeffler focuses on producing high-precision, lightweight fasteners made from advanced composites and alloys, with strategic investments in digital manufacturing technologies to improve product consistency and performance.
Fükema Industries
Fükema Industries specializes in high-strength, specialized aerospace bolts designed for extreme conditions, leveraging proprietary coating and surface treatment techniques to enhance durability and operational lifespan.
Nuts & Bolts Ltd
Nuts & Bolts Ltd maintains a broad inventory of aerospace fasteners, providing customized solutions for aircraft assembly, with a focus on rapid delivery and adherence to stringent aerospace certifications.
Sundram Fasteners Limited
Sundram Fasteners excels in manufacturing lightweight, high-tensile aerospace bolts using innovative materials and processes, aiming to meet the increasing demand for fuel efficiency and safety in aircraft.
Strategic Business Developments
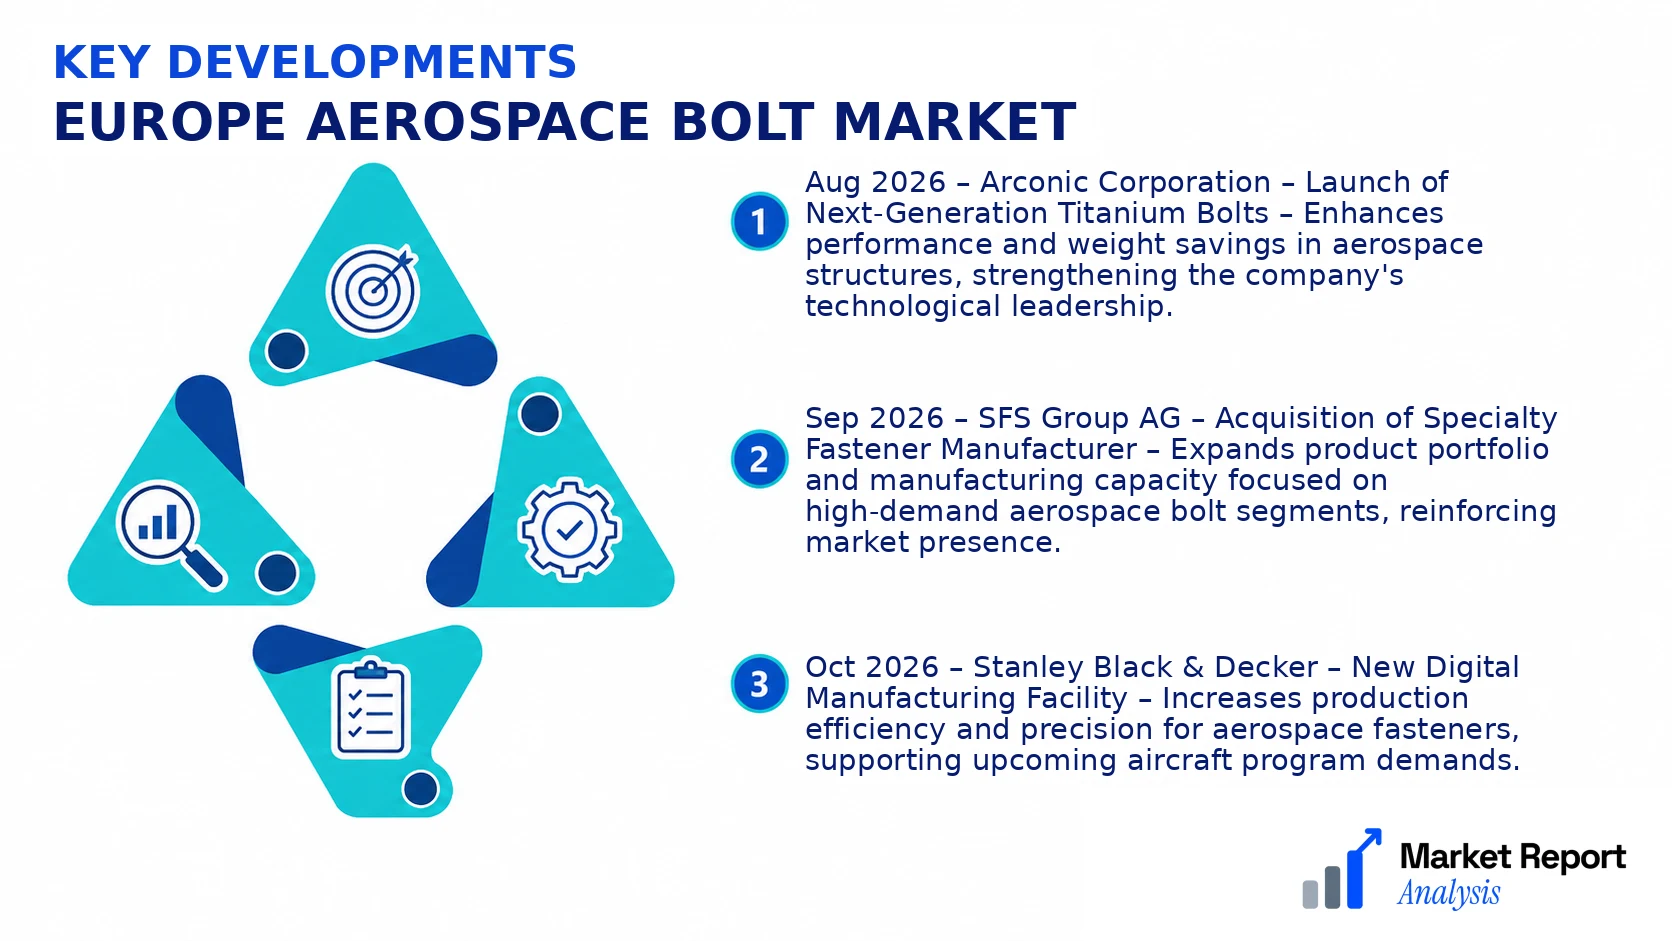
- Aug 2026 – Arconic Corporation – Launch of Next-Generation Titanium Bolts – Enhances performance and weight savings in aerospace structures, strengthening the company's technological leadership.
- Sep 2026 – SFS Group AG – Acquisition of Specialty Fastener Manufacturer – Expands product portfolio and manufacturing capacity focused on high-demand aerospace bolt segments, reinforcing market presence.
- Oct 2026 – Stanley Black & Decker – New Digital Manufacturing Facility – Increases production efficiency and precision for aerospace fasteners, supporting upcoming aircraft program demands.
- Nov 2026 – BOHLER-Uddeholm AG – Capacity Expansion in Specialty Alloys – Enables higher output of aerospace-grade fasteners with improved material properties, meeting rising industry needs.
- Dec 2026 – Fükema Industries – Strategic Partnership for Coating Technologies – Develops durable, corrosion-resistant fasteners, critical for long-term aerospace applications and safety standards.
Frequently Asked Questions
What is the Europe Aerospace Bolt Market?
The Europe Aerospace Bolt Market encompasses the production and distribution of aerospace-grade bolts used in aircraft manufacturing and maintenance. It involves various manufacturers supplying high-strength fasteners critical for securing aircraft components across the European aerospace sector.
What is the current market size of Europe Aerospace Bolt Market?
As of 2026, the market size for aerospace bolts in Europe is valued at approximately USD 2.5 Billion, reflecting the region’s expanding aerospace industry and increasing demand for reliable fastening solutions in commercial and defense sectors.
What factors are driving the Europe Aerospace Bolt Market?
Market growth is driven by rising aircraft production, technological advancements in aerospace materials, stringent safety standards, and increasing aerospace maintenance activities. Additionally, the expansion of aircraft fleets and OEM investments are key contributors.
Which region dominates the Europe Aerospace Bolt Market?
Germany leads the market, benefiting from its robust aerospace manufacturing sector, extensive supply chain, and host of major aerospace companies. It is followed by France and the UK, which also showcase substantial aerospace activities and technological innovation.
Which segment is expected to grow the fastest?
The segment for high-strength titanium and alloy aerospace bolts is projected to experience the fastest growth, attributable to their superior performance characteristics, lightweight properties, and rising applications in modern aircraft structures.
Who are the leading companies operating in the Europe Aerospace Bolt Market?
Key players include Aston Fasteners, Stanley Black & Decker, and aerospace-specific manufacturers such as Avington and Coventive Technologies, who are investing heavily in innovation and expanding their production capacities to meet market demand.
Analyst Perspective
The Europe Aerospace Bolt Market is expected to demonstrate sustained growth through 2034, driven by increasing aircraft production and integration of lightweight, high-strength materials. The long-term outlook highlights a mature yet evolving sector where technological advancements, such as corrosion-resistant coatings and advanced manufacturing techniques, are creating new commercial opportunities. Companies that invest in R&D to develop innovative, cost-efficient, and environmentally sustainable bolt solutions will likely achieve competitive advantages. Regionally, Western Europe offers the most mature market, with significant growth potential observed in Eastern and Southern Europe due to expanding aerospace manufacturing hubs. Competitive intensity remains high, with key players focusing on strategic partnerships and capacity expansion to capture market share. For investors, prioritizing firms with robust R&D pipelines, technological innovation, and regional expansion strategies will be crucial. Long-term, market entrants should align with sustainability trends and digitalization to maintain relevance and optimize operational efficiency in a dynamic aerospace supply chain.
