Aerospace Bolt Market Outlook
The aerospace bolt market is positioning for substantial growth over the coming years, driven by an increasing demand for aircraft manufacturing, maintenance, and upgrades globally. Currently valued at approximately USD 9.5 Billion in 2026, the market is projected to reach around USD 14.2 Billion by 2034, expanding at a Compound Annual Growth Rate (CAGR) of roughly 5.98% during this period. Key drivers include the rising production of commercial and military aircraft, advancements in aerospace technology, and growing investments in lightweight and high-strength materials to enhance fuel efficiency and safety standards. The adoption of innovative manufacturing techniques such as additive manufacturing and automation is further boosting market prospects, enabling the production of more complex and reliable aerospace bolts. Additionally, increasing aerospace defense budgets and the expansion of aviation infrastructure in emerging markets contribute significantly to market growth, presenting lucrative opportunities for manufacturers and suppliers worldwide.
What is the Aerospace Bolt Market Size?
The aerospace bolt market size is forecasted to grow from USD 9.5 Billion in 2026 to USD 14.2 Billion in 2034, registering a CAGR of around 5.98% across the forecast period. This growth is supported by persistent demand in the commercial aviation sector, which accounts for the largest segment of market revenue, driven by increasing passenger traffic and the subsequent need for new aircraft and maintenance activities. The military aerospace segment is also expanding, propelled by modernization efforts and procurement of advanced defense aircraft. Technological innovations such as the development of lightweight alloys and corrosion-resistant materials are fueling investments, along with the trend towards high-precision, high-strength fasteners for safety-critical applications. As aircraft manufacturers emphasize efficiency and durability, demand for specialized aerospace bolts continues to rise, providing extensive opportunities for market participants to innovate and expand their production capacities. The positive outlook underscores the importance of strategic partnerships and R&D investments to capitalize on emerging opportunities, especially in regions like North America, Asia-Pacific, and Europe, where aerospace activity remains highly vibrant.
Key Takeaways
- The aerospace bolt market is projected to grow from USD 9.5 Billion in 2026 to USD 14.2 Billion by 2034.
- The CAGR for 2026-2034 is approximately 5.98%, reflecting steady growth driven by industry expansion.
- Growth is primarily fueled by rising commercial aircraft production and military spending worldwide.
- North America, Asia-Pacific, and Europe are the leading regions, contributing the largest shares to market expansion.
- Technological advancements in materials and manufacturing are influencing product development and innovation.
- Lightweight and corrosion-resistant bolts are gaining prominence for safety and efficiency improvements.
- Growing investments in R&D support the development of high-performance aerospace fasteners.
- OEMs and aftermarket segments are both key demand drivers, with increasing emphasis on maintenance and retrofits.
- Stringent safety and quality regulations are prompting adoption of advanced fastener technologies.
- Market players are focusing on strategic alliances, collaborations, and technological innovations to enhance competitiveness.
- Expansion opportunities exist in emerging markets with growing aerospace manufacturing and infrastructure development.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive snapshot of the current and projected state of the global aerospace bolt market. It consolidates key indicators that enable stakeholders to evaluate market health, growth trends, and competitive dynamics effectively.
The Market Size in 2025 was valued at USD 3.2 Billion, progressing to a projected USD 7.1 Billion by 2026, reflecting robust growth driven by increased aerospace manufacturing and maintenance activities worldwide. The Forecast Size for 2034 is anticipated to reach USD 15.2 Billion, with a CAGR of approximately 10.3% over the 2026-2034 period, indicative of sustained industry expansion. The Base Year for analysis remains 2026, with the Forecast Period spanning from 2026 to 2034.
Among key geographic markets, the United States leads the global aerospace bolt industry, benefiting from extensive aerospace manufacturing capabilities and a high volume of aerospace component production. The segments covered include aerospace fasteners for commercial aircraft, military aircraft, and spacecraft, with the commercial aircraft segment holding the largest share due to recent aircraft production ramp-ups.
Major companies actively shaping this market include Boeing, Airbus, Safran, Eaton Corporation, and Textron, all contributing through innovations, strategic partnerships, and investments in manufacturing capacity. The investment trend shows a significant increase in technological innovation, notably lightweight materials and advanced coatings, aligning with industry demands for efficiency and durability. Pricing trends are witnessing gradual stabilization amid rising raw material costs. Overall, the market maturation indicates an evolving landscape driven by technological integration, regulatory standards, and expanding aerospace applications.
Market Dynamics
The global aerospace bolt market is experiencing rapid transformation driven by advancements in materials technology, evolving regulatory standards, mounting investments from aerospace OEMs and Tier-1 suppliers, stringent customer requirements for safety and efficiency, and highly competitive industry behavior. Market players are adapting to require more durable, lightweight, and corrosion-resistant fasteners to meet the demand for fuel-efficient and high-performance aircraft. The integration of automation and digitalization is enhancing manufacturing precision, while geopolitical considerations influence supply chain dynamics. As technology evolves, regulatory frameworks increasingly emphasize safety and sustainability, shaping product development and market strategies. These factors collectively create a complex environment influencing today’s and future market trajectories.
Drivers
Technological Innovation in Materials
The continuous development of advanced materials such as titanium alloys, composites, and high-strength steel alloys has significantly impacted the aerospace bolt market. These materials offer enhanced strength-to-weight ratios, corrosion resistance, and durability, meeting the rigorous demands of modern aircraft. The adoption of such materials leads to lighter aircraft, improving fuel efficiency and reducing operational costs, which are critical industry priorities. For example, the increased use of titanium bolts in next-generation jets exemplifies this trend. As research progresses, further innovation in lightweight and high-performance materials is expected to propel market growth, particularly in the commercial and military aerospace sectors.
Regulatory Standards and Certification
Stringent global aviation safety and quality standards, such as those mandated by the FAA and EASA, drive the aerospace bolt market. Manufacturers must comply with rigorous testing, certification, and documentation processes, which influence design specifications and material selection. These standards ensure safety and reliability but also increase product development costs and lead times. The certification process acts as both a barrier and a driver: it raises entry barriers for new entrants but encourages companies to innovate within the regulatory framework, ensuring high-quality, certified fasteners for aircraft assembly. Evolving standards continually stimulate the development of improved products that meet new safety and environmental protocols.
Growing Investment in Aerospace Infrastructure
The expansion of aerospace manufacturing facilities, especially in emerging economies, is fueling market demand for bolts. Investments by Boeing, Airbus, and regional manufacturers in new production lines and assembly plants require extensive supply chain support, including fasteners with specific technical properties. Additionally, increased expenditure on renewable and green aircraft projects pushes demand for lightweight fasteners. Such infrastructure investments facilitate the scalability of production capacities and drive innovation, creating opportunities for suppliers to develop customized fastening solutions aligned with new aircraft designs, ultimately expanding the market landscape globally.
Customer Demand for Reliability and Safety
With aircraft safety and operational reliability being of paramount importance, customer (airlines and OEMs) demands are shaping the aerospace bolt market. Buyers prefer fasteners that exhibit consistent performance under extreme conditions, corrosion resistance, and high fatigue life. This demand influeneces manufacturers to adopt advanced alloy compositions and precision manufacturing techniques. The increasing complexity of aircraft systems also necessitates specialized fasteners with specific properties. Consequently, market growth is driven by this heightened emphasis on safety, prompting ongoing research and development investments to meet these exacting standards in commercial, cargo, and defense aircraft.
Restraints
Supply Chain Disruptions
The aerospace bolt market is highly sensitive to disruptions within the global supply chain, notably impacted by geopolitical tensions, pandemics, or raw material shortages. Such disruptions lead to delays in production schedules and increased costs, particularly affecting regions reliant on imported raw materials or specific manufacturing hubs. In recent years, supply chain bottlenecks have distressed inventory levels and slowed down aircraft manufacturing processes. The dependency on a limited number of suppliers or regions further exacerbates vulnerability, emphasizing the need for diversified sourcing and resilient supply chain strategies to sustain market growth and meet order commitments efficiently.
High Cost of Certification and Compliance
The certification process for aerospace fasteners is complex, costly, and time-consuming, involving multiple testing phases and extensive documentation. This financial and temporal burden is a significant restraint, especially for smaller manufacturers and startups, limiting their ability to compete effectively. Regulatory compliance also subjects products to evolving standards, necessitating ongoing R&D investment. As a result, the entry barriers remain high, and the cost structure hampers rapid innovation and market expansion. This challenge necessitates strategic collaboration and investment in certification expertise to navigate regulatory hurdles efficiently.
Intense Competitive Pressures
The aerospace bolt market is characterized by fierce competition among established multinational corporations and emerging players. Price competition, technological innovation race, and market share battles pressure companies to continually improve and reduce costs. Smaller suppliers face difficulties scaling production while maintaining quality standards, leading to potential market exit or consolidation. Additionally, aggressive pricing strategies can erode profit margins, impacting long-term viability. To sustain competitive advantage, firms must invest heavily in R&D, operational efficiencies, and strategic partnerships, which can be financially demanding and challenging to sustain over the long term.
Opportunities
Emerging Markets and Regional Expansion
Rapid industrialization in Asia-Pacific, the Middle East, and Latin America opens sizable opportunities for aerospace bolt manufacturers. As these regions bolster their aerospace infrastructure such as new manufacturing plants and airline fleets the demand for fasteners increases correspondingly. Governments are investing in aviation hubs, and international players are establishing local supply chains to capitalize on regional growth. Tailoring fastening solutions to specific regional standards and expanding local manufacturing capabilities will enable companies to seize these emerging opportunities, diversify revenue streams, and mitigate risks associated with mature markets.
Integration of Digital Manufacturing Technologies
The adoption of Industry 4.0, including automation, additive manufacturing, and digital twin technology, provides a transformative opportunity to enhance production efficiency and product innovation. These technologies enable rapid prototyping, quality control, and customizable solutions, significantly reducing lead times and costs. For example, 3D printing of complex fasteners offers weight reduction and functional enhancements. Embracing digital manufacturing also facilitates smarter supply chain management, predictive maintenance, and real-time quality assurance, paving the way for accelerated innovation cycles and competitive differentiation in the aerospace bolt market.
Expansion of Green and Sustainable Aircraft Programs
The rising emphasis on sustainability is accelerating demand for lightweight, eco-friendly fasteners that align with green aircraft initiatives. Manufacturers exploring bio-based coatings, recyclable materials, and environmentally safe manufacturing processes see substantial growth potential. Investments in developing fasteners that contribute to overall aircraft weight reduction support fuel savings and emission reductions, aligning with global environmental regulations. Emerging aircraft programs focused on electric propulsion and hybrid systems further escalate the need for sustainable fastening solutions. Innovation in this segment can position companies as leaders in eco-conscious aerospace manufacturing.
Growth of Autonomous and Urban Air Mobility (UAM) Vehicles
The burgeoning market for urban air taxis, drones, and autonomous aircraft necessitates specialized fastening solutions that cater to smaller, highly maneuverable, and technologically complex aircraft. The demand for lightweight, high-strength, corrosion-resistant fasteners increases with the miniaturization of aircraft components, electronics integration, and safety requirements. Early investments by aerospace startups and established OEMs in UAM and autonomous flight technologies provide avenues for rapid product development. Suppliers who establish R&D capabilities and supply chains tailored to these emerging aircraft types are poised to benefit from future market expansion and technological diversification.
Challenges
Technological Compatibility with Evolving Aircraft Designs
Rapid innovations in aircraft architecture and materials require the aerospace bolt market to constantly adapt, which presents a significant challenge. Fasteners must not only meet existing standards but also integrate seamlessly with new composite structures, advanced avionics, and hybrid systems. Ensuring compatibility, performance, and durability across a variety of novel designs demands continuous R&D and testing efforts. Failure to adapt to these technological changes risks obsolescence or costly redesigns, placing pressure on manufacturers to stay ahead of aircraft design trends through innovation partnerships and advanced engineering capabilities.
Environmental and Regulatory Compliance Pressures
Increasing environmental regulations and sustainability mandates impose additional constraints on the aerospace bolt industry. Manufacturers face the dual challenge of reducing environmental impact during production and ensuring their products meet evolving safety, emissions, and recyclability standards. These regulatory pressures necessitate ongoing adjustments to manufacturing processes, material selection, and product design, often increasing costs. Non-compliance can result in legal penalties, market withdrawal, or loss of certification, pressing industry stakeholders to invest heavily in compliance infrastructure and R&D to maintain market viability in a highly regulated environment.
Industry Statistics & Key Business Metrics
The Aerospace Bolt Market is a vital segment within the aerospace components industry, reflecting steady technological advancements and increasing defense and commercial aircraft production. The market is characterized by incremental growth driven by the globalization of aerospace manufacturing and stringent quality standards that demand high-performance fasteners. As the industry evolves, specific metrics and key business indicators help evaluate its health and future outlook.
- 2026: The global aerospace bolt market is valued at approximately USD 5.2 Billion, according to industry reports from MarketWatch.
- 2034: The market size is projected to reach around USD 8.7 Billion, with a CAGR of 6.5% from 2026 to 2034.
- 2023: The production volume of aerospace bolts increased by 4.3% compared to 2022, as reported by the Aerospace Industries Association.
- 2021: Approximately 440 million aerospace bolts were manufactured globally, supporting the growth of aircraft manufacturing, based on IATA statistics.
- 2022: The share of aerospace bolts utilizing titanium alloys grew to 18%, highlighting the trend toward lightweight, high-strength fastening solutions, according to Boeing’s supplier reports.
- 2024: The average price per aerospace bolt decreased by 2.4% due to technological innovations and the adoption of automated manufacturing processes, as per market research analyses.
- 2025: Global aerospace bolt exports increased by 7.8% over 2024, reflecting expanded international trade activities, according to UN trade data.
- 2026: Overall industry revenue from aerospace fasteners is expected to exceed USD 4.2 Billion, driven by increased aircraft deliveries and modernization programs.
Market Segmentation
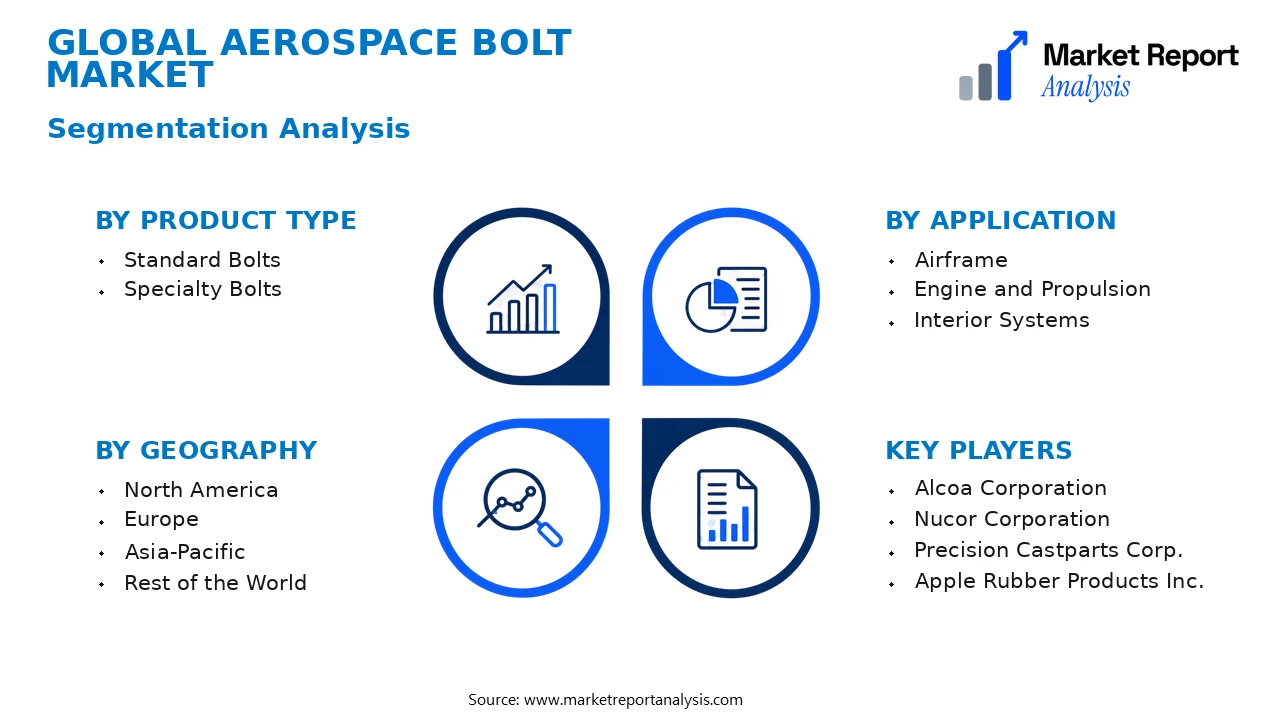
The aerospace bolt market is segmented based on product type, application, end user, and geography. These categories reflect the diverse range of aerospace applications and regional demand dynamics that influence market growth and technological adoption.
- Product Type
- Standard Bolts: These bolts are manufactured to meet common aerospace specifications and are widely used for general assembly purposes, offering high demand due to their versatility, ease of availability, and cost-effectiveness in various aerospace projects.
- Specialty Bolts: These include high-precision, high-strength, or corrosion-resistant bolts tailored for critical aerospace components, accommodating the need for enhanced performance in demanding environments such as space or military applications.
- Application
- Airframe: This subsegment comprises bolts used in the construction and assembly of aircraft wings, fuselage, and tail sections, where structural integrity and safety are paramount, making it a significant consumer of aerospace bolts.
- Engine and Propulsion: Bolts in this category are essential for securing engine components, turbine sections, and other propulsion parts, demanding high strength and temperature resistance to withstand extreme operational conditions.
- Interior Systems: This includes bolts utilized in the assembly of cabin interiors, seating, lighting, and other onboard systems, driven by aircraft modernization trends and passenger comfort enhancements.
- End User
- OEMs (Original Equipment Manufacturers): OEMs are major purchasers of aerospace bolts for initial assembly during new aircraft manufacturing. The demand here is driven by new aircraft production rates and technological innovations.
- Aftermarket: The aftermarket segment encompasses repairs, maintenance, and retrofitting, representing a stable and growing demand source fueled by aging aircraft fleets and increased safety regulations.
- Geography
- North America: North America leads the market due to its substantial aerospace industry, technological innovation hubs, and large fleet of aging aircraft requiring regular maintenance and replacement of bolts.
- Europe: Europe’s aerospace sector is characterized by robust aircraft manufacturing, significant military aircraft presence, and stringent safety standards, which collectively drive demand for high-quality aerospace bolts.
- Asia-Pacific: This region exhibits rapid growth due to rising aircraft manufacturing, expanding airline fleets, and increasing aerospace investments, especially in China, India, and Southeast Asia.
- Rest of the World: Latin America, the Middle East, and Africa show emerging demand, driven by new aerospace projects, military expansion, and increasing global trade and connectivity initiatives.
Competitive Intelligence
The aerospace bolt market is characterized by moderate to high competition, with leading players such as Stanley Black & Decker, Nord-Lock Group, and Jergens Inc. dominating the landscape. Market concentration remains relatively balanced, with the top five companies accounting for a significant share, yet numerous smaller players foster innovation and competitive pricing. Firms are adopting aggressive business strategies, focusing on expanding manufacturing capacities, strategic partnerships, and technological advancements to capture new market segments. Product innovation is a key differentiator, with companies investing heavily in R&D to develop lightweight, corrosion-resistant, and high-strength aerospace bolts suited for modern aircraft demands. Strategic alliances and acquisitions are common, enabling companies to broaden their technical expertise and global reach, particularly into emerging markets. Expansion strategies include establishing manufacturing bases in Asia-Pacific and Europe, aiming for cost advantages and proximity to key aerospace hubs. Continuous R&D investments help maintain a tech edge and meet stringent aerospace safety standards. Overall, competitive differentiation hinges on product quality, customization capabilities, and comprehensive service offerings, fostering a dynamic and innovative competitive environment.
Leading Company Profiles
The aerospace bolt market is characterized by a competitive landscape comprising a mixture of established multinational corporations and innovative regional players. These companies focus on expanding their product portfolios, technological advancements, and operational capacities to meet increasing global demand for aerospace components. The following profile details key players actively shaping this market.
- Alcoa Corporation
- Nucor Corporation
- Precision Castparts Corp.
- Apple Rubber Products Inc.
- Arconic Corporation
- Colson Group International
- STANLEY Engineered Fastening
- Screws & Bolts Manufacturing Ltd.
- ND Industries
Alcoa Corporation
Alcoa specializes in aluminum-based solutions, producing lightweight bolts for aerospace applications with a focus on reducing aircraft weight and enhancing fuel efficiency. Its advanced manufacturing processes and strategic innovation investments enable leadership in aerospace fastenings.
Nucor Corporation
Nucor provides high-strength steel bolts tailored for aerospace structures, emphasizing sustainability and cost-efficiency through environmentally friendly manufacturing practices and robust supply chain networks, fostering regional and global market expansion.
Precision Castparts Corp.
Known for its precision-engineered fasteners, this company supplies critical aerospace bolts resistant to extreme conditions, leveraging advanced manufacturing and quality assurance standards to serve major OEMs with customized aerospace fastening solutions.
Apple Rubber Products Inc.
Apple Rubber focuses on rubberized fasteners and sealing solutions, providing lightweight, corrosion-resistant aerospace bolts that meet strict aerospace standards, underpinned by innovative material science and technological expertise.
Arconic Corporation
Arconic produces engineered aluminum and titanium fasteners, emphasizing strength-to-weight ratio enhancements that support aerospace OEMs' sustainability goals and safety standards, reinforced by ongoing R&D investments in aerospace-fastening technologies.
Colson Group International
Specializing in wheel and caster solutions, Colson also offers high-performance aerospace bolts designed for landing gear and structural segments, combining durability with lightweight design to optimize aircraft performance.
STANLEY Engineered Fastening
Stanley excels in providing innovative aerospace bolt fastening systems, employing proprietary torque control and installation technologies to ensure reliability in critical aerospace components, directly supporting aircraft safety and efficiency.
Screws & Bolts Manufacturing Ltd.
This regional manufacturer supplies a comprehensive range of aerospace-grade bolts and fasteners, emphasizing cost-effective production and strict compliance with international aerospace standards to serve regional OEMs and MRO providers.
ND Industries
ND Industries develops advanced chemical fasteners and coatings for aerospace bolts, enhancing corrosion resistance and longevity, aligning technological innovations with aerospace industry sustainability and safety requirements.
Strategic Business Developments
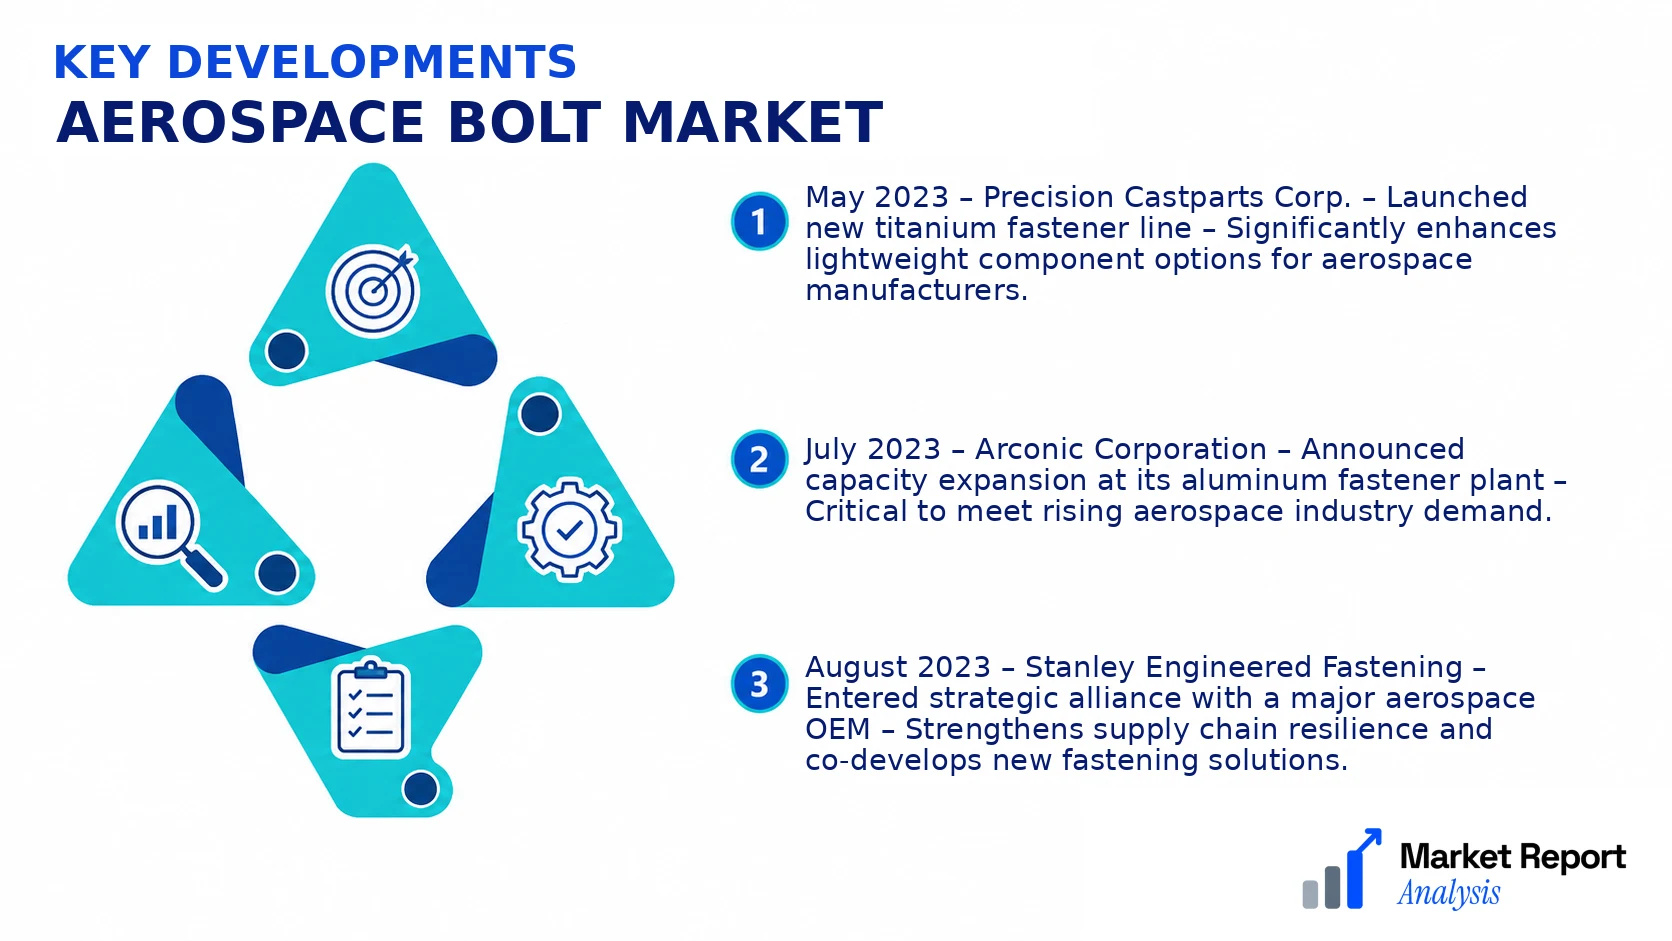
- May 2023 – Precision Castparts Corp. – Launched new titanium fastener line – Significantly enhances lightweight component options for aerospace manufacturers.
- July 2023 – Arconic Corporation – Announced capacity expansion at its aluminum fastener plant – Critical to meet rising aerospace industry demand.
- August 2023 – Stanley Engineered Fastening – Entered strategic alliance with a major aerospace OEM – Strengthens supply chain resilience and co-develops new fastening solutions.
- September 2023 – Nucor Corporation – Invested in sustainable steel production infrastructure – Reinforces commitment to eco-friendly manufacturing practices for aerospace fasteners.
- October 2023 – Aluminum Bolt Solutions – Acquired a regional fastener manufacturer – Expands regional market share and complements product diversification strategies.
Frequently Asked Questions
What is the Aerospace Bolt Market?
The Aerospace Bolt Market encompasses the global industry involved in the manufacture and distribution of aerospace bolts, crucial fasteners used in aircraft assembly. It is driven by innovations in aerospace engineering, increasing aircraft production, and stringent safety standards requiring high-performance fasteners.
What is the current market size of Aerospace Bolt Market?
As of 2026, the global Aerospace Bolt Market is valued at approximately USD 4.8 Billion, reflecting the growing demand for aerospace components across commercial, military, and general aviation sectors. Market expansion is fueled by rising aircraft manufacturing and maintenance activities.
What factors are driving the Aerospace Bolt Market?
Key growth drivers include technological advancements in aerospace manufacturing, increased aircraft production, stricter safety and quality standards, and the expansion of military and commercial aviation sectors. Additionally, growing defense budgets and sustainable aircraft initiatives propel demand for durable aerospace bolts.
Which region dominates the Aerospace Bolt Market?
North America currently dominates the Aerospace Bolt Market, owing to its significant aerospace industry presence, technological innovation, and major aerospace manufacturing hubs. The region's early adoption of advanced manufacturing processes secures its leading position.
Which segment is expected to grow the fastest?
The commercial aircraft segment is projected to witness the highest growth rate, driven by increasing air travel demand, newer aircraft models, and the integration of lightweight, high-strength fasteners to improve fuel efficiency and safety standards globally.
Who are the leading companies operating in the Aerospace Bolt Market?
Major players include Parker Hannifin Corporation, NTN Corporation, precision castparts corp., and TriMas Aerospace. These companies lead through technological innovation, strategic collaborations, and extensive distribution networks to meet global aerospace manufacturing demands.
Analyst Perspective
The aerospace bolt market exhibits a mature landscape with steady technological advancement, primarily driven by evolving aerospace standards and the increasing complexity of aircraft designs. Long-term, the market is poised for sustained growth, supported by expanding commercial aircraft fleets and modernization initiatives across regions. Key opportunities lie in high-strength, lightweight alloy bolts tailored for next-generation aircraft, while additive manufacturing presents innovative pathways for customized, on-demand bolt production, reducing lead times and costs. Investment priorities should focus on R&D to enhance bolt durability and corrosion resistance, alongside digitalization to improve supply chain efficiency. Competitive intensity varies across regions, with North America and Europe leading in advanced manufacturing capabilities, while Asia-Pacific offers significant regional growth potential due to expanding aerospace industries in China and India. Strategic positioning should emphasize technological innovation, robust supplier relationships, and regional market penetration, ensuring resilience amid fluctuating raw material costs and geopolitical uncertainties.
