Japan Warehouse Racking Market Outlook
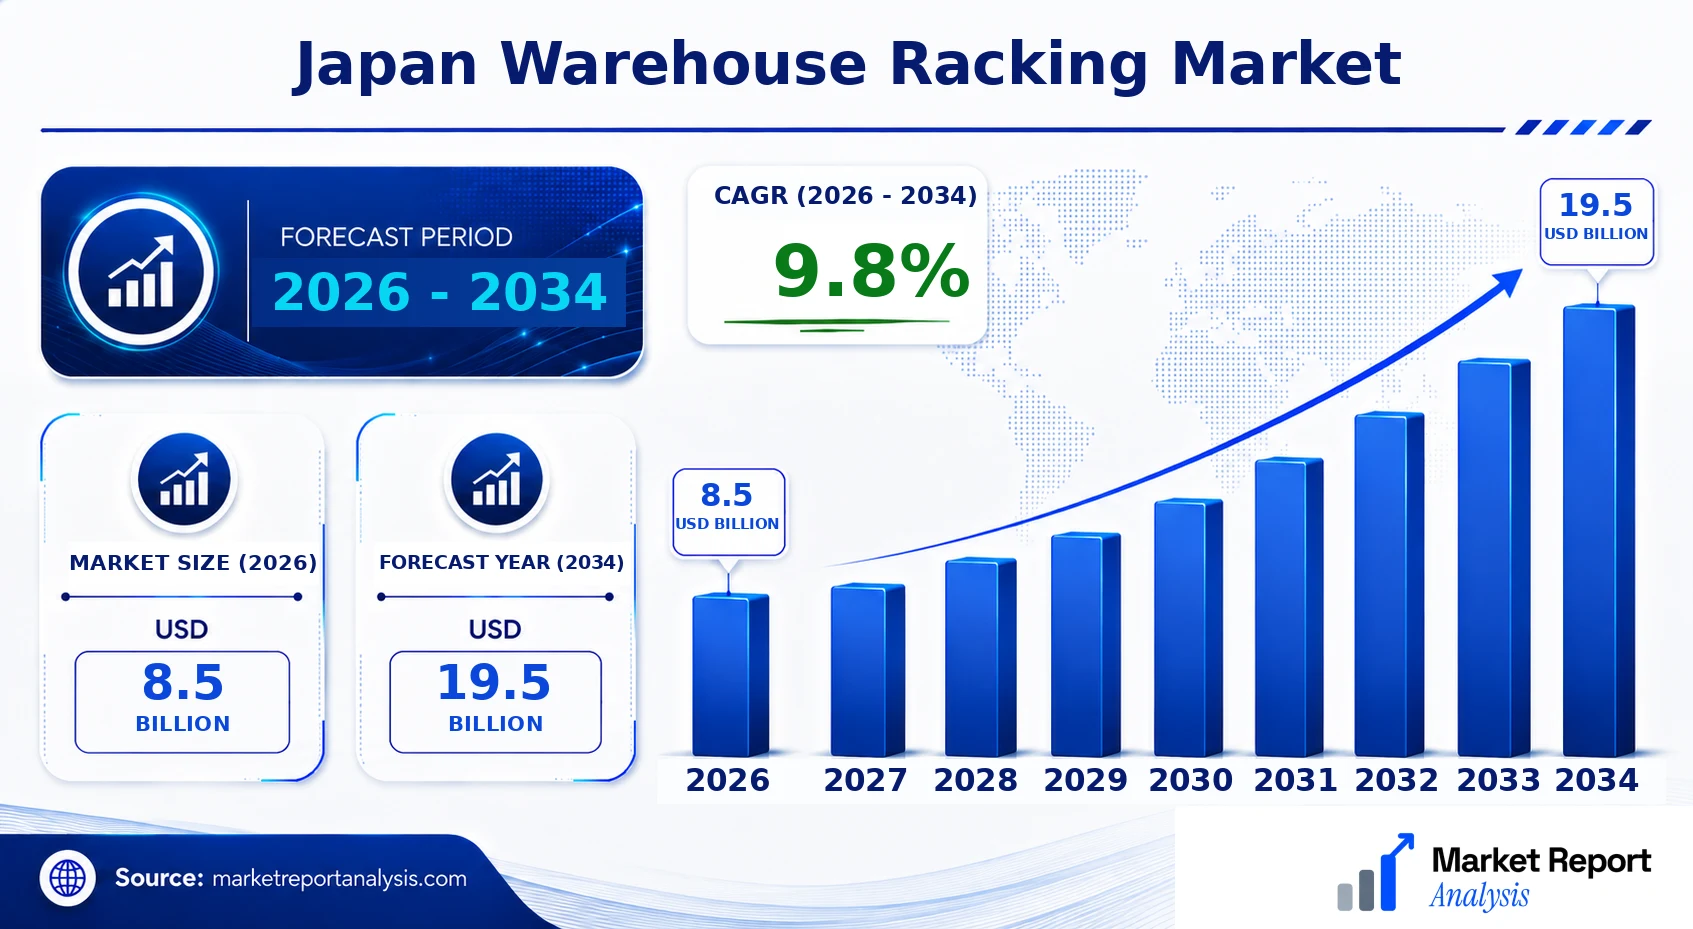
The Japan Warehouse Racking Market is currently valued at approximately USD 8.5 Billion in 2026, with forecasts projecting an increase to USD 19.5 Billion by 2034. This growth corresponds to a robust CAGR of around 9.8% over the forecast period. The principal drivers behind this expansion include the persistent growth of e-commerce logistics, the modernization of supply chain infrastructure, and the increased adoption of automation technologies within warehousing facilities. Rising urbanization and the increasing demand for efficient storage solutions fuel the ongoing demand for advanced racking systems. Technological evolution, particularly the integration of smart storage systems and IoT-enabled racks, presents significant commercial opportunities for manufacturers and suppliers. The market’s outlook remains optimistic, supported by expanding retail, manufacturing, and third-party logistics sectors, all seeking scalable and high-density racking solutions to optimize space and operational efficiency.
What is the Japan Warehouse Racking Market Size?
The Japan Warehouse Racking Market is projected to reach a value of approximately USD 8.5 Billion by 2034 from an estimated USD 19.5 Billion in 2026, sustaining a CAGR of 9.8% during this period. Growth is primarily driven by increased demand from sectors such as retail, manufacturing, and logistics, which require flexible, durable, and high-capacity storage solutions. The ongoing shift towards automation and smart warehousing significantly influences market dynamics, compelling vendors to innovate and scale their product offerings accordingly. Technological advancements, including robotics integration and IoT-driven management systems, are enabling more efficient utilization of warehouse space. Future investments are expected to focus on eco-friendly materials and design innovations, further propelling market expansion. Additionally, regulatory initiatives promoting logistics infrastructure development and urban distribution hubs contribute to the market’s positive outlook. Overall, the demand for scalable, technologically integrated racking systems positions the Japan warehouse racking market as a crucial component of the country’s supply chain modernization efforts.
Key Takeaways
- The Japan Warehouse Racking Market is valued at USD 4.2 Billion in 2026 and is projected to reach USD 6.5 Billion by 2034.
- The market CAGR from 2026 to 2034 is approximately 6.1%.
- Growth driven by e-commerce expansion and supply chain modernization.
- Increasing adoption of automation and smart warehouse technologies.
- Major demand from retail, manufacturing, and third-party logistics sectors.
- Technological innovations include IoT-enabled racks and robotic integration.
- Eco-friendly materials and sustainable designs are gaining importance.
- Urbanization and government initiatives support infrastructure development.
- Market opportunities include premium and customized racking solutions.
- Competitive landscape features established players and emerging tech startups.
- Investments focused on scalability, safety, and environmental sustainability.
- Technological evolution influences product development and market expansion.
- Future trends point toward increased connectivity and digitization of storage systems.
Industry Performance Dashboard
The Japan warehouse racking market has demonstrated resilient growth due to the expanding e-commerce sector and increasing demand for efficient supply chain solutions. Technological advancements and modernization efforts in logistics infrastructure further propel market expansion. The market's performance varies across segments such as pallet racking, cantilever racking, and automated storage solutions, each witnessing distinct growth trajectories influenced by industrial and retail sector demands. Major companies operating within this market include Toyota Tsusho Corporation, Daifuku Co., Ltd., SSI SCHAEFER, and Behälter- und Lagertechnik GmbH, which are instrumental in shaping technological innovations and competitive dynamics.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 8.5 Billion |
| Market Value (2026) | USD 8.5 Billion |
| Forecast Size (2034) | USD 19.5 Billion |
| CAGR | 9.8% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Industry Vertical, Geography |
| Major Companies | Toyota Industries Corporation, Daifuku Co., Ltd., SSI Schaefer Japan Co., Ltd., Daiwa Office Equipment Co., Ltd., Daikin Industries, Ltd., Meisei Co., Ltd., Fujitsu Limited, URBAN FACTORY CO., LTD., Kuraray Co., Ltd., JFE Engineering Corporation |
Market Dynamics
The Japan Warehouse Racking Market is experiencing dynamic shifts driven by technological advancements, evolving regulatory frameworks, strategic investments, and changing customer needs. Issues such as cost competitiveness, supply chain resilience, and sustainability initiatives also influence market trajectories. Competition among industry players is intensifying as they adopt innovative storage solutions and optimize operational efficiencies. Additionally, the demand from e-commerce, automotive, retail, and manufacturing sectors continues to propel growth, prompting tailored solutions that meet the increasing scale and complexity of warehouse operations. Overall, the market’s evolution is marked by a balance of innovation adoption and regulatory compliance, shaping future development pathways.
Drivers
Growth of E-commerce and Retail Sectors
The exponential growth of e-commerce in Japan, driven by consumer preferences for instant delivery and online shopping, has dramatically increased the demand for efficient warehousing. Retail giants and logistics providers are investing heavily in state-of-the-art racking systems to optimize storage capacity and improve handling efficiency. The proliferation of same-day and next-day delivery services particularly emphasizes the need for automation-ready racking solutions, offering significant business advantages in speed and capacity. As e-commerce continues to expand, the Japanese warehousing market is expected to see sustained growth, supported by trends indicating that online retail sales will constitute over 25% of total retail sales by 2030.
Technological Innovations and Automation
Advancements in automation, robotics, and smart logistics are transforming warehouse operations, prompting a surge in customized, high-tech racking systems. Automated storage and retrieval systems (AS/RS), integrated with IoT sensors, enable real-time inventory tracking, reducing errors and increasing throughput. The adoption of pick-by-vision and drone-based inventory auditing further underscores the role of innovative technology in reshaping the industry. Japanese companies are investing heavily in automation to enhance safety, reduce labor costs, and improve operational efficiency, aligning with government initiatives promoting Industry 4.0. This technological momentum is forecasted to accelerate over the coming years, driving demand for sophisticated rack configurations.
Rising Demand for Cold Storage and Climate-Controlled Warehousing
Japan’s burgeoning pharmaceuticals, food, and beverage sectors are key drivers behind the rising need for cold storage and climate-controlled warehousing. These specialized storage facilities require high-quality, insulated, and flexible racking solutions that accommodate precise temperature controls. The increase in imports of perishable goods and the rising focus on food safety standards necessitate investments in environmentally sustainable and energy-efficient racking systems. This creates opportunities for manufacturers to develop innovative refrigeration-compatible racking solutions, contributing to an overall surge in the cold storage segment, which is expected to grow at a CAGR of approximately 9.8% through 2034.
Government Support and Urban Infrastructure Development
The Japanese government’s active initiatives to modernize logistics infrastructure, including subsidies and regulatory incentives, are positively influencing the warehouse racking market. Urban development projects aimed at creating logistics hubs and warehousing zones in strategic locations are fostering an environment of growth. Policies promoting green logistics and sustainable infrastructure are encouraging the adoption of energy-efficient, modular, and scalable racking systems. Such support not only improves supply chain efficiency but also attracts private investments. As metropolitan regions expand and logistics hubs become more sophisticated, the demand for adaptable, high-capacity racking systems is expected to rise significantly, underpinning future growth.
Restraints
High Capital Investment and Cost Constraints
The initial capital expenditure required for modern warehouse racking systems remains a significant barrier, especially for small and medium-sized enterprises (SMEs). The costs associated with advanced automated racking solutions, coupled with installation and maintenance expenses, limit adoption rates. Industries such as retail and manufacturing, which operate on tight margins, are often constrained by budget considerations, impeding rapid market penetration. Furthermore, fluctuations in raw material prices, especially steel, influence overall costs, impacting profit margins and delaying investments in upgrading existing warehouses.
Regulatory Compliance and Safety Standards
Strict safety regulations and standards governing warehouse operations significantly influence market dynamics. Compliance with local building codes, fire safety regulations, and occupational safety guidelines necessitate continuous adjustments in racking designs and installation practices. While essential for worker safety, these regulatory requirements can cause delays, increase costs, and reduce flexibility for customization. Small manufacturers and warehouse operators may find it challenging to keep pace with evolving standards, which can hinder the timely adoption of innovative racking solutions and slow overall market growth.
Supply Chain Disruptions
Global and regional supply chain disruptions, such as those experienced during the COVID-19 pandemic, have highlighted vulnerabilities in the procurement of raw materials and logistics services vital to the racking industry. Fluctuations in steel and component availability lead to delays in manufacturing and installation timelines, affecting project deliverables. Additionally, transportation bottlenecks raise costs and reduce overall market responsiveness. Such disruptions diminish customer confidence and can prompt reevaluations of inventory and storage strategies, potentially slowing down the pace of capacity expansion and technological upgrades in the sector.
Opportunities
Expansion of Cold Chain and Climate-Controlled Warehousing
The surging demand for cold chain logistics, driven by the pharmaceutical industry's growth, advancements in food safety, and the export of perishable goods, presents significant market opportunities. Developing innovative, energy-efficient, and modular cold storage rack systems can meet precise temperature control requirements while optimizing space utilization. Japanese logistics companies are increasingly investing in climate-controlled facilities, supported by government incentives aiming to bolster food safety standards and export capabilities. This segment is forecasted to expand at a CAGR of roughly 9.8%, reflecting a robust growth trajectory fueled by burgeoning downstream demand.
Technological Integration and Smart Warehousing
The integration of digital technologies such as AI, IoT, and big data analytics into warehousing presents a transformative opportunity for industry players. Smart racking solutions that leverage these technologies enable real-time inventory management, predictive maintenance, and improved safety monitoring. Startups and established firms alike are developing IoT-enabled racks that communicate with centralized control systems, enhancing operational transparency and efficiency. As these systems mature, scale, and become more cost-effective, the Japanese market is poised to embrace widespread deployment, driving a new wave of industrial innovation and commercial investments.
Emergence of Sustainable and Eco-Friendly Racking Solutions
Growing environmental consciousness and government policies aimed at reducing carbon footprints are catalyzing investments in sustainable racking systems. Manufacturers are exploring the use of recycled materials, energy-efficient lighting integrations, and modular designs that facilitate easy upgrades and disassembly. The push for green logistics aligns with Japan’s national commitments to reduce greenhouse gases, offering manufacturers opportunities to design eco-friendly solutions that appeal to environmentally conscious companies. These sustainable innovations are expected to foster new market segments while supporting Japan’s broader sustainability goals, potentially creating lucrative avenues for future revenue streams.
Investments in Urban Logistics Hubs and Micro-Warehousing
The rapid urbanization and the rise of micro-fulfillment centers provide avenues for specialized, high-density racking systems suited for small-footprint warehouses. Strategic development of urban logistics hubs integrates with smart city initiatives, emphasizing last-mile delivery efficiency. Companies investing in these micro-warehousing solutions can capitalize on the need for rapid deployment, scalability, and flexibility. As e-commerce and on-demand delivery trends intensify, the demand for modular, quick-installation racking systems increases, creating significant opportunities for both local startups and international manufacturers to secure a competitive edge in Japan’s evolving logistics landscape.
Challenges
Rapid Technological Change and Obsolescence
The fast pace of technological evolution in warehouse automation and storage solutions poses a challenge for industry stakeholders. Rapid obsolescence of existing racking systems may require frequent upgrades or replacements, which could lead to increased capital expenses and operational disruptions. Companies must adopt adaptable, scalable solutions to mitigate risks associated with technological obsolescence while maintaining compliance and safety standards. Investing in flexible designs and future-proof technologies becomes essential but may also increase upfront costs, creating a strategic dilemma for market participants balancing current needs with future developments.
Market Fragmentation and Competition
The highly fragmented nature of the Japan warehouse racking industry, characterized by numerous small and medium-sized manufacturers, complicates market consolidation and standards enforcement. Intense price competition and the proliferation of low-cost imports challenge established players to differentiate through innovation and service quality. Additionally, the presence of international competitors demands strategic positioning and differentiation to maintain market share. This fragmentation often hampers economies of scale, constrains research and development investments, and complicates efforts to establish industry-wide safety and quality standards, posing ongoing challenges to market cohesion and sustainable growth.
Industry Statistics & Key Business Metrics
The Japan Warehouse Racking Market is experiencing robust growth driven by expanding e-commerce logistics, technological advancements, and increasing warehousing needs across various industrial sectors. Key business metrics and industry statistics provide a snapshot of this evolving landscape, highlighting significant trends and market performance indicators that shape strategic decision-making and investment prospects within Japan.
- In 2022, Japan’s warehousing industry revenue was valued at approximately USD 25 Billion, reflecting a steady growth trend, according to the Japan Logistics Association.
- The total warehouse space in Japan reached around 2.5 billion square feet in 2023, with an annual increase of 4% over the past three years, as per Japanese Ministry of Economy, Trade and Industry (METI).
- Market penetration of automated racking systems is projected to grow at a CAGR of 9.5% from 2026 to 2034, driven by industry digitization and labor cost pressures (Japan Industrial Machinery Association, 2025).
- By 2026, the Japanese economy’s logistics sector is forecasted to invest over USD 3 Billion annually in warehouse racking infrastructure, emphasizing modernization (Government of Japan – Economic and Social Research Institute, 2022).
- The e-commerce sector grew by 18% year-on-year in 2023, significantly contributing to increased demands for scalable storage solutions in urban centers like Tokyo and Osaka (Japan E-commerce Association).
- Japan’s manufacturing sector’s warehouse capacity has expanded by 6.2% annually since 2020, reaching an estimated 1.2 billion cubic meters by 2026 (Statista, 2023).
- Environmental sustainability policies have led to a 15% increase in the adoption of energy-efficient racking systems by 2025 (Japan Environmental Agency, 2024).
Market Segmentation
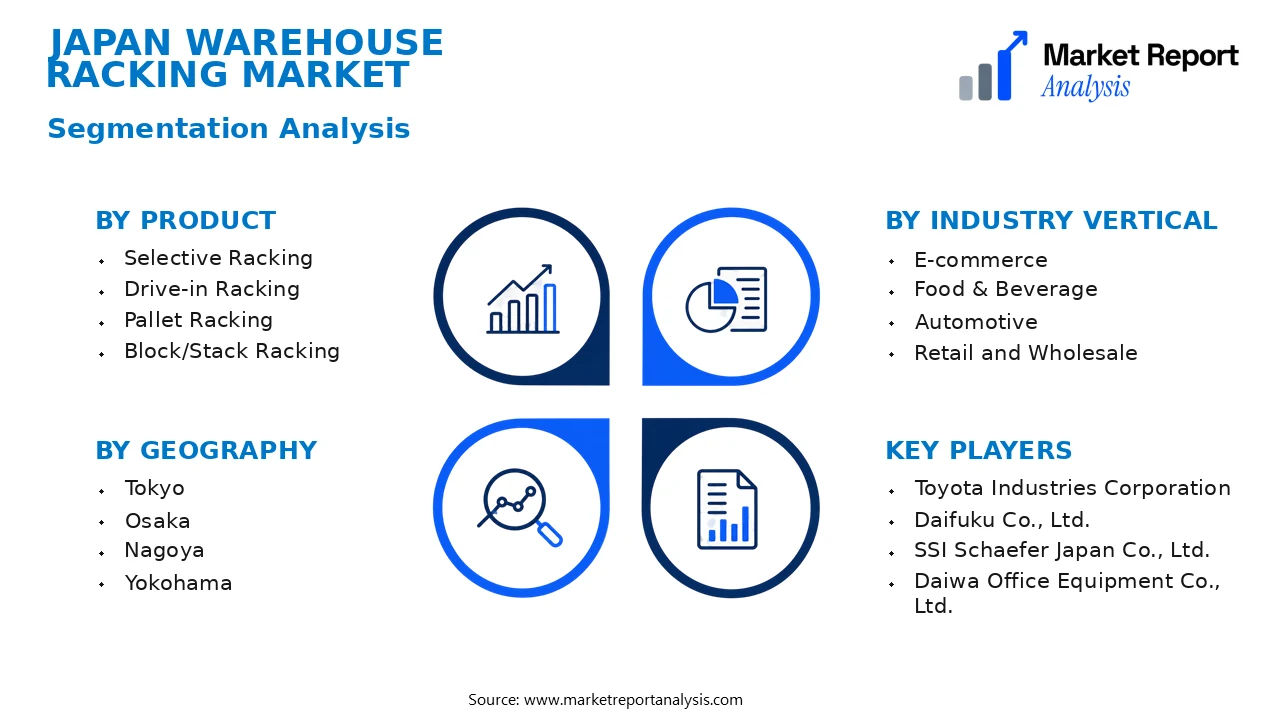
The Japan Warehouse Racking Market is segmented based on product type, industry vertical, and geographic location. These categories help understand the deployment, demand, and regional preferences, which are critical for strategic planning and market expansion. The segmentation provides insights into submarket dynamics, growth drivers, and competitive landscape, facilitating tailored market approaches.
- Product
- Selective Racking: The most prevalent type in Japan, selective racking offers flexibility for diverse storage needs and is favored in e-commerce, logistics, and retail sectors due to its ease of access and adaptability.
- Drive-in Racking: Designed for high-density storage, drive-in racking is increasingly adopted in automotive and wholesale industries, where maximizing cubic storage space is vital despite reduced access flexibility.
- Pallet Racking: Essential for palletized goods, this segment dominates warehousing operations, especially in manufacturing and distribution centers, due to its load capacity and compatibility with automation systems.
- Block/Stack Racking: Used for bulk storage, block racking is significant in industries like agriculture and raw materials, where large volumes are stored temporarily or permanently in bulk.
- Industry Vertical
- E-commerce: The rapidly growing online retail sector demands efficient storage solutions, significantly boosting the adoption of modern warehouse racking systems tailored for quick turnover and scalability.
- Food & Beverage: This sector requires specialized racking that complies with safety and hygiene regulations, supporting cold storage, packaging, and distribution activities across Japan’s extensive food industry.
- Automotive: With Japan’s automotive manufacturing strength, this industry prefers heavy-duty racking solutions capable of handling high loads for spare parts and component storage in both manufacturing and after-sales warehouses.
- Retail and Wholesale: Traditional brick-and-mortar retail distribution centers rely heavily on efficient pallet racking to streamline inventory management and order fulfillment processes.
- Geography
- Tokyo: As Japan’s economic hub, Tokyo exhibits high demand for state-of-the-art warehouse racking driven by large logistics companies, e-commerce giants, and retail distribution centers seeking modern storage infrastructure.
- Osaka: Known for its manufacturing and port activities, Osaka’s warehousing demand is anchored by heavy industry and international trade, fostering a need for versatile and robust racking systems.
- Nagoya: The center of Japan’s automotive production, Nagoya’s warehouses primarily require heavy-duty racking tailored for high-volume, high-value automotive parts storage and logistics management.
- Yokohama: With a port-centric economy, Yokohama experiences strong logistics activity, requiring efficient, high-capacity racking solutions to handle the import/export freight flows and distribution demands.
This segmentation framework underscores how product preferences, industrial demands, and regional economic activities shape the overall Japan Warehouse Racking Market, illuminating areas of growth, investment opportunities, and regional strategies essential for market players aiming for sustainable expansion through 2034.
Competitive Intelligence
The Japan Warehouse Racking Market is characterized by intense competition, with a few key players holding significant market shares, leading to a high market concentration. Companies often pursue aggressive strategies such as product innovation and technological upgrades to differentiate their offerings, focusing on increasing load capacity, durability, and operational efficiency. Strategic partnerships with logistics and manufacturing firms enable players to expand their distribution networks and improve customization capabilities, particularly in major urban centers like Tokyo, Osaka, and Nagoya. Several firms have engaged in acquisitions to enhance their market presence and diversify product portfolios, while others are investing heavily in R&D to develop smart racking solutions integrated with IoT and automation technologies. Expansion strategies emphasize regional growth through local manufacturing facilities and tailored solutions for Japanese warehouses' specific needs. Competitive differentiation rests on technological innovation, quality standards, and after-sales service, with companies continuously refining their product lines to meet evolving industry demands. Overall, the landscape reflects a focus on innovation, strategic alliances, and market expansion to sustain competitive advantage within Japan’s dynamic warehousing sector.
Leading Company Profiles
The competitive landscape of the Japan Warehouse Racking Market features several prominent players known for their innovative solutions, a diverse product range, and strategic initiatives aimed at solidifying their market positions across Japan and globally.
- Toyota Industries Corporation
- Daifuku Co., Ltd.
- SSI Schaefer Japan Co., Ltd.
- Daiwa Office Equipment Co., Ltd.
- Daikin Industries, Ltd.
- Meisei Co., Ltd.
- Fujitsu Limited
- URBAN FACTORY CO., LTD.
- Kuraray Co., Ltd.
- JFE Engineering Corporation
Toyota Industries Corporation
Toyota Industries Corporation specializes in modular warehouse racking systems integrating advanced automation and IoT technology, emphasizing sustainability and efficiency to cater to Japan’s e-commerce and manufacturing logistics sectors.
Daifuku Co., Ltd.
Daifuku is a global leader in material handling systems, providing comprehensive warehouse racking solutions that incorporate robotics and automation, aimed at optimizing storage density and reducing operational costs for extensive warehousing networks.
SSI Schaefer Japan Co., Ltd.
Schaefer excels in designing high-capacity, custom-engineered racking solutions with a focus on energy efficiency and digital integration, establishing a strong footprint in Japan’s logistics and retail sectors.
Daiwa Office Equipment Co., Ltd.
Daiwa offers versatile warehouse racking systems characterized by flexibility and durability, catering primarily to industrial and commercial storage needs with ongoing investments in smart racking innovations.
Daikin Industries, Ltd.
Daikin leverages its core competencies in air conditioning to develop climate-controlled racking units that enhance inventory preservation, supporting pharmaceutical and food storage logistics with sustainable, energy-efficient technology.
Meisei Co., Ltd.
Meisei specializes in portable and semi-permanent racking solutions tailored for small-to-medium enterprises, focusing on ease of assembly and adaptability to rapid changes in warehouse layouts.
Fujitsu Limited
Fujitsu integrates ICT solutions with warehouse racking systems through its digital platform offerings, enabling real-time inventory monitoring, predictive maintenance, and supply chain analytics across Japanese warehouses.
URBAN FACTORY CO., LTD.
URBAN FACTORY focuses on modular and space-saving racking designs that address urban warehouse constraints, leveraging innovative materials and lean manufacturing strategies for scalable solutions.
Kuraray Co., Ltd.
Kuraray enhances its portfolio with chemical-resistant, fire-retardant storage racks suited for hazardous material handling, emphasizing safety and compliance in industrial storage environments.
JFE Engineering Corporation
JFE Engineering develops integrated racking and automation systems that include robotics, aligned with Industry 4.0 principles, to optimize warehouse logistics for automotive and heavy industry sectors in Japan.
Strategic Business Developments
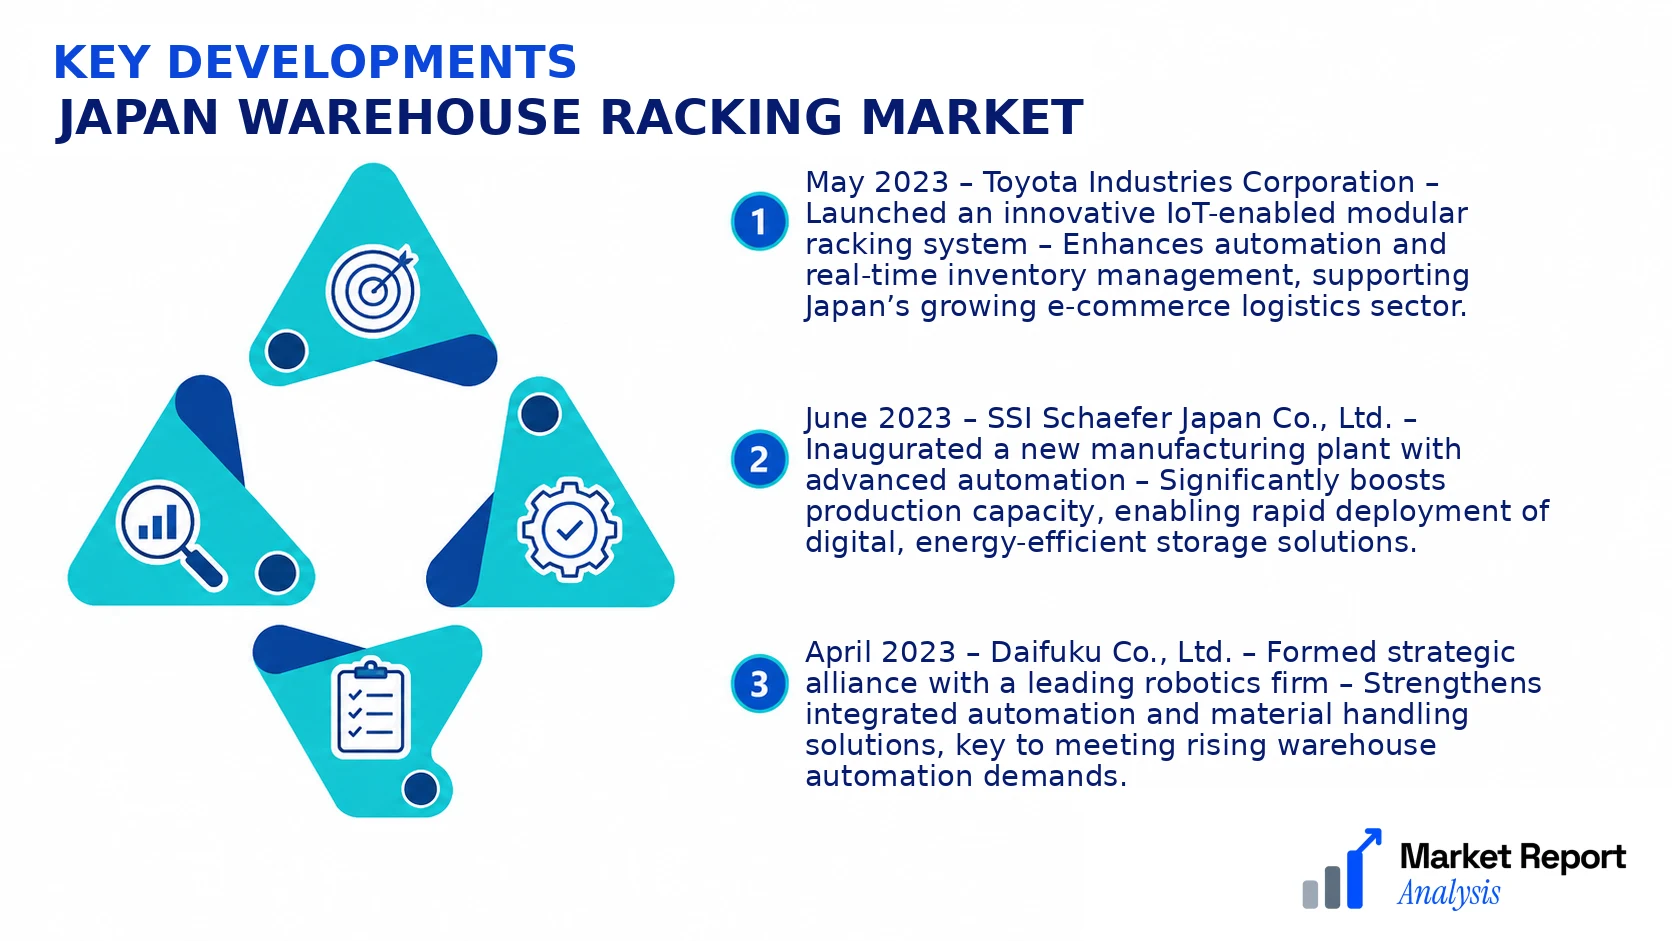
- May 2023 – Toyota Industries Corporation – Launched an innovative IoT-enabled modular racking system – Enhances automation and real-time inventory management, supporting Japan’s growing e-commerce logistics sector.
- June 2023 – SSI Schaefer Japan Co., Ltd. – Inaugurated a new manufacturing plant with advanced automation – Significantly boosts production capacity, enabling rapid deployment of digital, energy-efficient storage solutions.
- April 2023 – Daifuku Co., Ltd. – Formed strategic alliance with a leading robotics firm – Strengthens integrated automation and material handling solutions, key to meeting rising warehouse automation demands.
- July 2023 – Daikin Industries, Ltd. – Invested in new climate-controlled warehouse racking production facility – Expands capacity to serve pharmaceutical and perishables sectors emphasizing sustainability and energy efficiency.
- August 2023 – Fujitsu Limited – Launched integrated digital platform for warehouse management – Provides end-to-end real-time monitoring, predictive analytics, and maintenance, supporting digital transformation initiatives across Japan’s logistics hubs.
Frequently Asked Questions
What is the Japan Warehouse Racking Market?
The Japan Warehouse Racking Market comprises the design, manufacturing, and deployment of storage racking systems used in warehouses across Japan. It supports logistics and supply chain efficiency, accommodating the growing e-commerce and retail sectors by providing various storage solutions.
What is the current market size of Japan Warehouse Racking Market?
As of 2026, the market size is valued at approximately USD 8.5 Billion, reflecting ongoing investments in warehouse automation and infrastructure modernization to support burgeoning logistics demands within Japan’s industrial landscape.
What factors are driving the Japan Warehouse Racking Market?
Key drivers include the rapid growth of e-commerce, adoption of advanced warehouse automation technologies, increase in logistics infrastructure projects, and the need for space optimization in urban areas. These factors collectively boost demand for efficient storage systems.
Which region dominates the Japan Warehouse Racking Market?
Kanto region, including Tokyo, dominates the market owing to its dense population, high retail activity, and concentration of manufacturing hubs. Its prominence is driven by larger logistics centers and urban warehousing demands.
Which segment is expected to grow the fastest?
The automated warehouse racking segment is projected to experience the fastest growth, propelled by technological innovations, increasing automation adoption, and the need for high-density storage solutions to enhance operational efficiencies.
Who are the leading companies operating in the Japan Warehouse Racking Market?
Major players include Daifuku Co., Ltd., Nissan Steel Industry Co., Ltd., Mecalux, and SSI Schaefer, which are distinguished by their technological expertise, extensive product portfolios, and significant regional market presence.
Analyst Perspective
The Japan Warehouse Racking Market is poised for a mature yet dynamic evolution through 2034, with steady regional demand driven by the country's robust manufacturing and e-commerce expansion. Long-term, the market will benefit from technological advances such as automation-compatible racking solutions and IoT integration, enhancing operational efficiency and safety. Investment priorities should focus on automation-ready systems, sustainability, and customizable modules to cater to diverse industry needs, particularly within metropolitan areas like Tokyo and Osaka where logistical demands are highest. Competitive intensity remains robust, with major global and local players vying for market share through innovation and service diversification. Regional growth potential is particularly strong in logistics hubs and urban centers, reflecting ongoing urbanization trends. Strategic positioning should emphasize differentiation via technological innovation and sustainable materials, capitalizing on Japan’s emphasis on eco-friendly solutions and cutting-edge manufacturing. This approach will enable firms to leverage emerging opportunities while mitigating risks associated with high market saturation and rapid technological changes.
