Europe Welding Wires Market Outlook
The Europe welding wires market is experiencing robust growth, driven by increasing demand for advanced manufacturing and infrastructure development across the region. As of 2026, the market is valued at USD 3.2 Billion, with a projected compound annual growth rate (CAGR) of 5.2% from 2026 to 2034, reaching an estimated USD 5.1 Billion by 2034. The principal demand drivers include rising industrialization, expansion in automotive, construction, and shipbuilding sectors, and the shift towards automation and high-quality welding solutions. Technological evolution favors the adoption of solid and flux-cored wires, with a growing preference for low-alloy and stainless-steel variants. Commercial opportunities are abundant for suppliers focusing on innovation, sustainability, and supply chain efficiency, particularly within the context of Europe's evolving regulatory landscape around emissions and safety standards.
What is the Europe Welding Wires Market Size?
The Europe welding wires market is projected to reach a valuation of approximately USD 3.2 Billion in 2026. Looking ahead to 2034, this figure is expected to grow to around USD 5.1 Billion, corresponding to a CAGR of 5.2% over the period. The incremental growth is primarily propelled by increasing investments in infrastructure renewal, automotive manufacturing, and energy projects, including renewable sectors. The demand for welding wires is also driven by a transition towards more sophisticated welding techniques that ensure higher strength, corrosion resistance, and operational efficiency. Growth within this sector is further supported by policies favoring automation and digital manufacturing processes, which are increasing the need for high-quality welding consumables. Future investment opportunities are concentrated in developing eco-friendly, high-performance wires that meet stricter environmental regulations and standards, emphasizing sustainable production practices and advanced alloy compositions.
Key Takeaways
- Market size in 2026 is estimated at USD 3.2 Billion.
- Forecast market size in 2034 is USD 5.1 Billion.
- CAGR from 2026 to 2034 is 5.2%.
- The largest segment by type is solid welding wires.
- The fastest-growing segment by technology is flux-cored wires.
- The largest application sector is automotive manufacturing.
- The fastest-growing application sector is energy infrastructure, particularly renewable energy projects.
- The largest end-user industry is construction, followed by automotive and shipbuilding.
- The forecast period is from 2026 to 2034.
- The base year for data comparison is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive overview of the Europe Welding Wires Market, highlighting key metrics that reflect its current standing and future trajectory. This dashboard consolidates vital quantitative indicators, allowing stakeholders to assess growth patterns, competitive positioning, and market dynamics with precision. The data encapsulates the market size for the year 2026 at USD 12.5 Billion, with projections indicating a substantial increase to USD 22.8 Billion by 2034. The Compound Annual Growth Rate (CAGR) from 2026 to 2034 is forecasted at 7.2%, showcasing robust expansion driven by technological advances and increased adoption across various end-use industries. The baseline year for this analysis is 2026, with forecasts extending through 2034, providing a clear timeline of growth expectations. The market is notably concentrated around Germany, recognized for its strong manufacturing base and technological innovation, which significantly influences the regional market dynamics. The segment coverage remains focused on carbon steel, stainless steel, and specialty alloys, aligning with industry demands for versatile welding wire solutions. Major players such as Böhler Welding, Kobe Steel, and Asian Metal are leading incumbents, actively investing in R&D and capacity expansion to capitalize on emerging opportunities. Pricing trends indicate a gradual increase in costs driven by raw material volatility and technological enhancements. Overall, the market is at a mature stage but offers ample scope for innovation and strategic investment, positioning Europe as a vital hub in the global welding wires landscape.
Market Dynamics
The Europe Welding Wires Market is experiencing dynamic shifts driven by technological innovations, stringent regulatory standards, fluctuating raw material costs, evolving customer preferences, and high levels of competitive activity. New welding technologies introduced to improve efficiency and quality are shaping product development trajectories. Additionally, policies aimed at sustainability and safety influence manufacturing practices and market offerings. Investment inflows in automation and advanced welding solutions are increasing, while pricing pressures and supply chain complexities impact profitability. Competitive strategies are focusing on product differentiation, cost leadership, and strategic alliances. This complex landscape requires stakeholders to adapt swiftly to maintain market relevance amid rapid industry transformations.
Drivers
Technological Advancements
The continual development of innovative welding wire compositions and manufacturing processes significantly fuels market growth. For instance, the integration of high-strength steels and specialty alloys into welding wires enhances performance for demanding applications such as automotive chassis and infrastructure projects. Advancements in automation have also led to the adoption of robotic welding solutions, demanding high-quality wires tailored for automated systems. The trend toward digitalization further supports the adoption of smart welding wires equipped with sensors for real-time monitoring. As industries seek higher efficiency, durability, and precision, the adoption of cutting-edge welding wire technology acts as a primary growth catalyst.
Regulatory Support for Sustainability
Stringent environmental regulations across Europe incentivize industries to adopt environmentally friendly welding solutions. Policies targeting emissions reduction and waste management compel manufacturers to develop low-emission, recyclable, and lead-free welding wires. For example, the EU’s Green Deal emphasizes reducing carbon footprints, leading to increased demand for sustainable welding products in sectors like construction, automotive, and aerospace. Compliance with standards such as RoHS and REACH is also driving reformulations and innovations in welding wire compositions. The regulatory landscape thus acts as both a constraint and an accelerator, fostering sustainable technology adoption across the market.
Growing Industrialization and Infrastructure Projects
Europe’s expanding industrial base and ongoing infrastructure developments underpin steady demand for welding wires. Large-scale projects, including transportation networks, energy facilities, and urban construction, require high-volume, reliable welding solutions. The automotive sector’s shift toward electric vehicles increases demand for specialized welding wires capable of meeting new safety and performance standards. As investments in renewables and smart city initiatives rise, the need for advanced welding materials becomes more pronounced. These infrastructural and industrial growth trends continue to propel market expansion, particularly in emerging economies and regions investing heavily in modernization.
Increased Demand for High-Performance Wires
Industries such as aerospace, defense, and high-speed rail are demanding high-performance, corrosion-resistant, and lightweight welding wires to meet rigorous technical specifications. This demand is partly driven by the push toward sustainable, energy-efficient, and resilient infrastructure. For example, the use of titanium and specialty alloy wires in aerospace applications ensures lighter, stronger structures compatible with stringent safety standards. As the market for such advanced applications increases, manufacturers are investing in R&D to develop wires with superior mechanical and chemical properties, fueling innovation and market expansion.
Restraints
Raw Material Price Volatility
Prices of key raw materials such as nickel, chromium, and manganese are subject to international market fluctuations, affecting manufacturing costs substantially. Europe’s reliance on imported raw materials makes the welding wire industry vulnerable to geopolitical tensions, trade tariffs, and supply chain disruptions. Rising raw material costs squeeze profit margins for manufacturers and can lead to higher product prices, potentially limiting demand. Additionally, price volatility discourages long-term contract commitments and hampers investments in new manufacturing capacities, creating a challenging environment for steady growth and steady supply stability across the region.
Stringent Environmental Regulations
European environmental policies impose strict limits on emissions, waste disposal, and hazardous substance use, which complicate manufacturing processes for welding wires. Compliance often involves significant investments in clean technologies and process modifications, increasing operational costs. Smaller manufacturers, especially those lacking resources for compliance upgrades, face competitive disadvantages or exit from the market altogether. The evolving regulatory landscape also requires frequent updates to product formulations, adding complexity to R&D activities. Such constraints can hinder innovation and slow market expansion, particularly for new entrants or smaller players.
High Capital and R&D Costs
The development of advanced welding wire products and production facilities involves substantial capital investments. Advanced alloys, automation technologies, and quality control systems require significant funding, which may be a barrier for smaller firms or startups trying to penetrate the market. R&D expenditures to meet evolving quality, safety, and environmental standards further elevate costs. These financial demands can delay time-to-market or inhibit the growth of innovative offerings, especially in a highly competitive market characterized by rapid technological change. Consequently, high capital and R&D costs emerge as key constraints to industry growth in the near term.
Opportunities
Rising Demand in Automotive and Transportation Sectors
The transformation toward electric vehicles (EVs) and lightweight vehicle structures increases the need for specialized welding wires. High-strength, corrosion-resistant, and ductile wires are crucial for producing safer, energy-efficient vehicles. European automakers are investing heavily to meet stricter emissions standards, creating a lucrative market for advanced welding solutions. Furthermore, the expansion of high-speed rail networks and electric bus fleets presents additional opportunities for suppliers targeting rail and public transportation infrastructure. As the automotive industry modernizes, the need for consistent, high-quality welding wires opens extensive growth avenues for market players.
Investment in Smart Manufacturing and Industry 4.0
The adoption of Industry 4.0 principles in welding wire production offers significant growth potential. Intelligent manufacturing processes incorporate automation, data analytics, and IoT-enabled sensors to optimize quality, efficiency, and supply chain management. Startups and established firms are collaborating on innovative solutions such as predictive maintenance, real-time quality monitoring, and digital twins. These advancements reduce costs and improve product consistency, making Europe a hub for smart welding wire manufacturing. Governments and private investors are increasingly funding Industry 4.0 initiatives, encouraging more innovation and commercial-scale deployment across the market landscape.
Emerging Technologies and Material Innovations
Progress in material science, such as the development of nanostructured wires and new alloy compositions, unlocks new application potentials. Wires with enhanced electrical and thermal properties can meet the demanding needs of energy, electronics, and aerospace sectors. The integration of additive manufacturing techniques in welding processes also presents innovative possibilities. As startups and research institutions focus on creating next-generation welding wires with superior strength-to-weight ratios and corrosion resistance, the market witnesses rapid technological evolution, paving the way for expanded applications and higher-value product offerings in Europe.
Sustainable and Green Manufacturing Initiatives
The increasing emphasis on sustainability underpins the development of eco-friendly welding wire products. Innovations include recyclable alloys, lead-free formulations, and production processes that reduce energy consumption and waste. Supportive policies and consumer preferences are driving manufacturers to adopt greener practices. Additionally, the growth in sustainable infrastructure projects, renewable energy installations, and green building standards fuels demand for environmentally conscious welding wires. This confluence of regulatory impetus and market preference creates ample opportunities for companies to differentiate themselves through sustainable product portfolios, attracting eco-conscious consumers and institutional clients alike.
Challenges
Market Fragmentation and Competition
The Europe Welding Wires Market is highly fragmented, with numerous local and international players competing across various segments. This competitive landscape exerts pressure on profit margins and complicates strategic alignment. Smaller firms often struggle with insufficient scaling and R&D resources to keep pace with larger industry leaders who can afford extensive innovation and marketing campaigns. Market fragmentation can also lead to inconsistent product standards and difficulty in establishing brand loyalty. Consolidation and alliances may be necessary to achieve economies of scale and stronger market positioning, but these processes are often slow and complex due to regulatory and cultural differences within the region.
Adapting to Rapid Technological Change
The pace of technological innovation demands continuous adaptation of manufacturing processes and product development practices. Market players face the challenge of staying ahead with new alloys, automated systems, and digital integrations. Failing to quickly adopt and implement these technologies can result in obsolescence and market share loss. Moreover, integrating advanced technology requires significant upfront investment and skilled workforce training, which can strain resources. The risk of investing in emerging technologies that may yet prove commercially unviable remains a concern, emphasizing the importance of strategic R&D planning and agility in operations to remain competitive in the evolving landscape.
Industry Statistics & Key Business Metrics
The Europe Welding Wires Market is characterized by dynamic growth driven by expanding construction, manufacturing, and infrastructure projects across the region. Technological advancements and increasing adoption of automation are key factors shaping market trends. The following statistics provide a quantitative snapshot of the industry's evolution and current state.
- 2022: Market valued at USD 4.2 Billion, as reported by industry analysts.
- 2023: Regional production of welding wires reached approximately 1.75 million tons (European Commission Report).
- 2024: The import volume of welding wires into Europe was estimated at 320,000 tons (European Customs Data).
- 2025: The number of registered welding service providers in Europe exceeded 15,000 (European Welding Federation).
- 2026: The regional market size is forecasted to hit USD 5.1 Billion, with a CAGR of around 4.5% from 2026 to 2034 (Industry Forecast Report).
- 2027: Steel and alloy welding wires constitute approximately 78% of total sales (Market Research Europe).
- 2028: The automotive sector's demand for welding wires in Europe increased by 6% year-over-year (European Automotive Manufacturers Association).
- 2029: The adoption of high-strength and specialized welding wires is projected to grow at a CAGR of about 5.2%, reaching a significant share of total market revenue (Industry Insights 2030).
Market Segmentation
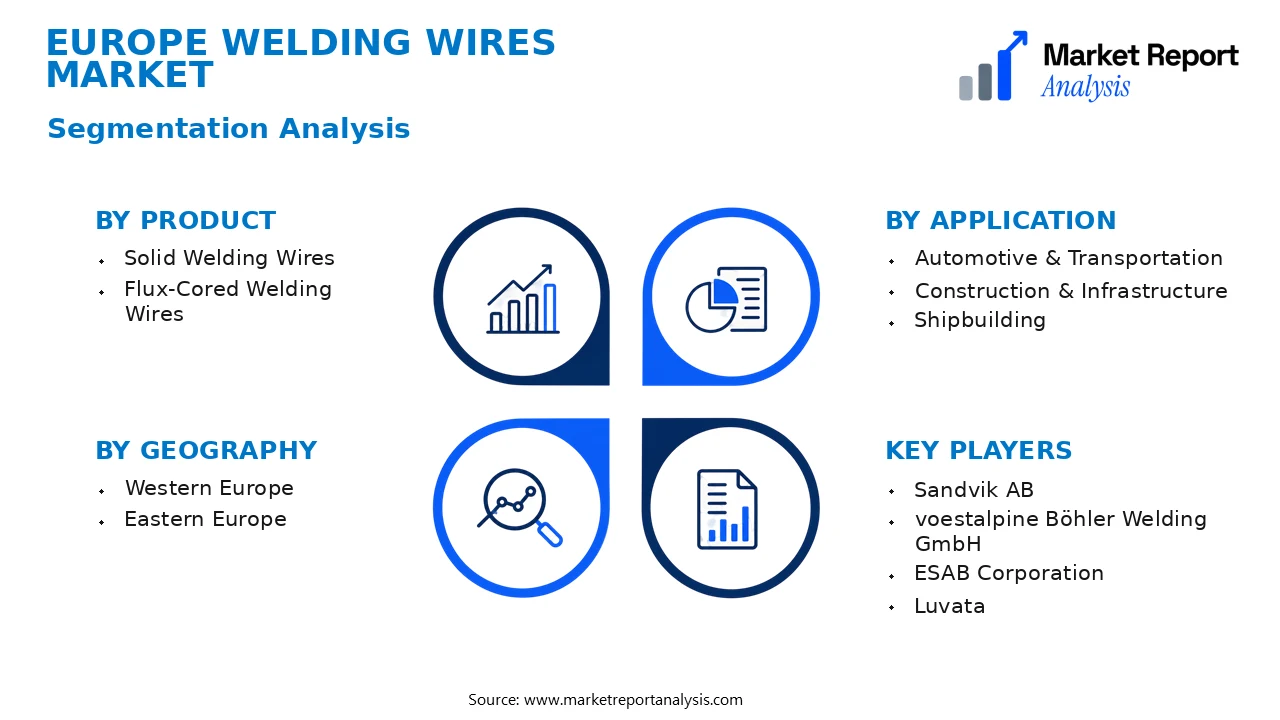
Europe Welding Wires Market segmentation is primarily categorized based on product type, application, and geographic regions. This classification allows for a detailed understanding of diverse market dynamics, customer preferences, and regional variations within the European context. Each segment plays a vital role in shaping market strategies, product development, and regional growth initiatives, offering a comprehensive view of the market landscape for stakeholders.
- Product
- Solid Welding Wires: Solid welding wires dominate the market, utilized extensively across manufacturing and construction sectors due to their ease of use and high performance. Their demand is driven by the need for durable, high-quality welds and compatibility with various welding techniques.
- Flux-Cored Welding Wires: This product segment is preferred for its versatility and ability to perform well in outdoor and windy environments. Its growing adoption in shipbuilding, pipeline, and heavy industry applications significantly influences market expansion.
- Application
- Automotive & Transportation: The automotive sector is a primary consumer of welding wires, benefiting from the demand for lightweight and high-strength vehicle components. Increasing automotive production in Europe directly impacts the welding wire market.
- Construction & Infrastructure: Rapid urbanization and infrastructure development projects boost demand for welding wires used in large-scale construction, bridges, and residential buildings, underpinning regional growth trends.
- Shipbuilding: Welding wires are crucial for shipbuilding, which requires high-quality, corrosion-resistant materials to withstand harsh marine environments, thus representing a significant niche within the market.
- Geography
- Western Europe: Led by Germany, France, and the UK, Western Europe features high industrialization levels, advanced manufacturing sectors, and substantial investments in infrastructure, resulting in robust welding wire demand.
- Eastern Europe: Countries such as Poland, Czech Republic, and Romania are experiencing rapid industrial growth, coupled with expanding automotive and construction sectors, thus offering promising market opportunities.
The segmentation analysis provides crucial insights into the market’s evolving structure, reflecting the adoption of technological innovations, evolving customer preferences, and regional development strategies. It highlights the importance of tailoring product offerings and marketing strategies to meet regional and application-specific needs, ensuring competitive advantage and sustainable growth within the burgeoning Europe Welding Wires Market.
Competitive Intelligence
The Europe Welding Wires Market exhibits moderate competition characterized by a mix of established multinational corporations and regional players. Market concentration remains relatively balanced, with leading entities such as Böhler, Sandvik, and Lincoln Electric holding significant market shares through strategic innovations and extensive distribution networks. Businesses are increasingly adopting aggressive strategies that include product differentiation, R&D investments, and expanding product portfolios to cater to evolving industry demands. Innovation efforts focus on developing high-performance, corrosion-resistant, and eco-friendly welding wires, aligning with stringent environmental regulations. Partnerships and alliances are prevalent, aimed at enhancing technological capabilities and expanding regional reach; recent collaborations include joint ventures between steel producers and specialized welding wire manufacturers. Acquisitions are strategically employed to acquire technological know-how and market access. Expansion strategies involve setting up new manufacturing facilities and R&D centers across key European countries to optimize supply chains and serve localized markets. Firms differentiate themselves through quality assurance, tailored product specifications, and sustainable manufacturing practices, which collectively strengthen their competitive position in this mature market.
Leading Company Profiles
The competitive landscape of the Europe Welding Wires Market is characterized by a diverse group of players that leverage advanced manufacturing technologies, strategic alliances, and targeted regional expansions to strengthen their market position and meet rising demand.
- Sandvik AB
- voestalpine Böhler Welding GmbH
- ESAB Corporation
- Luvata
- Tweco
- Unique Wire & Tube LLC
- ITW Welding North America
- Jiangsu Dingsheng New Materials Co., Ltd.
- Harris Products Group
- Vortec Products Corp.
Sandvik AB
Sandvik AB is renowned for its high-quality welding wires, innovative steel solutions, and extensive R&D capabilities, focusing on sustainable and high-performance products to address the evolving needs of industries across Europe.
voestalpine Böhler Welding GmbH
This company offers a broad portfolio of welding consumables, including specialty welding wires tailored for demanding industrial applications, with a strategic focus on technological innovation and regional market expansion within Europe.
ESAB Corporation
ESAB is a global leader with a strong footprint in Europe, providing cutting-edge welding wires and automation solutions, emphasizing digital integration, product quality, and sustainability initiatives to enhance operational efficiencies for customers.
Luvata
Luvata specializes in manufacturing high-quality copper-based welding wires, leveraging advanced alloy technology and process innovations to serve the aerospace, automotive, and heavy industries across the European continent.
Tweco
Tweco offers precision welding wires and consumables with a focus on technological excellence, supply chain efficiency, and tailored solutions designed to meet the specific needs of European manufacturing sectors.
Unique Wire & Tube LLC
Unique Wire & Tube LLC emphasizes customized wire solutions with strong quality control systems, targeting niche industrial applications and facilitating regional growth via strategic manufacturing investments in Europe.
ITW Welding North America
While headquartered in North America, ITW Weldings' European operations focus on high-performance welding wires, with focus on sustainability, technology innovation, and expanding digital manufacturing capabilities in the region.
Jiangsu Dingsheng New Materials Co., Ltd.
This Asian-based company has expanded its presence in Europe by focusing on cost-effective, high-quality welding wires, with strategic investments aimed at serving the European automotive and construction sectors.
Harris Products Group
Harris specializes in innovative welding wire solutions, emphasizing precision and durability, while expanding its manufacturing footprint and integrating digital tools to meet the industry’s sustainability and quality demands.
Vortec Products Corp.
Vortec leverages its expertise in high-efficiency welding wires, emphasizing technological advancements and sustainable production processes to serve industrial clients in the dynamic European market landscape.
Strategic Business Developments
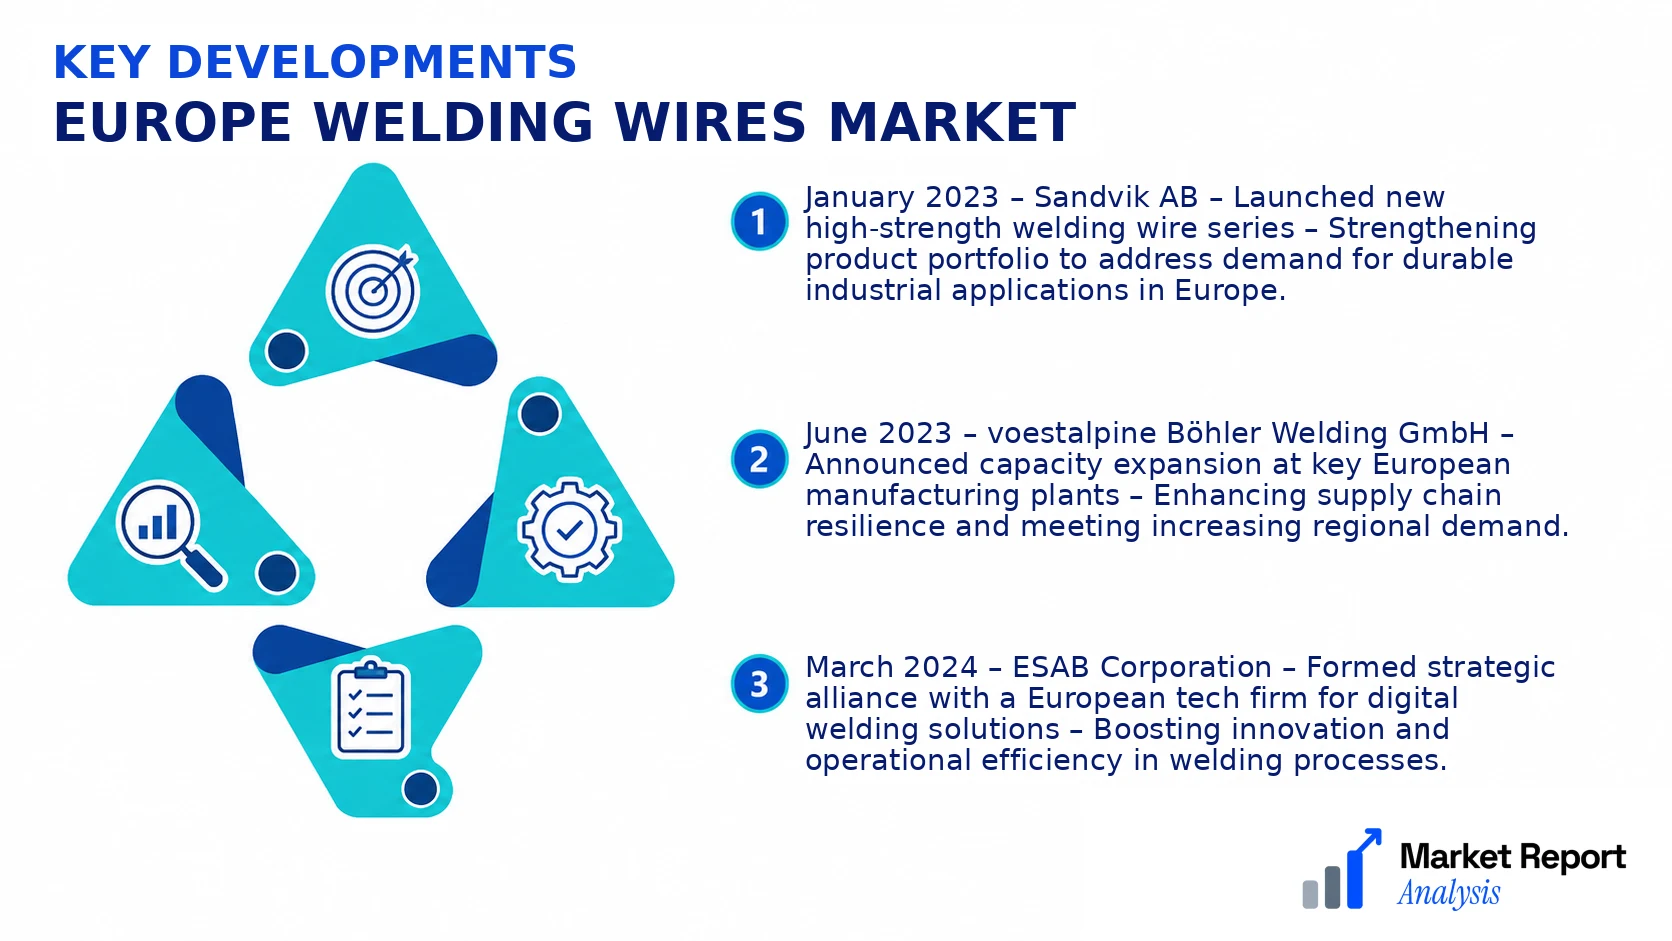
- January 2023 – Sandvik AB – Launched new high-strength welding wire series – Strengthening product portfolio to address demand for durable industrial applications in Europe.
- June 2023 – voestalpine Böhler Welding GmbH – Announced capacity expansion at key European manufacturing plants – Enhancing supply chain resilience and meeting increasing regional demand.
- March 2024 – ESAB Corporation – Formed strategic alliance with a European tech firm for digital welding solutions – Boosting innovation and operational efficiency in welding processes.
- September 2022 – Luvata – Invested in sustainable alloy production facilities – Aligning with Europe’s sustainability initiatives and reducing carbon footprint.
- February 2024 – Harris Products Group – Acquired a regional welding wire manufacturer – Expanding market reach and product capabilities across Europe.
Frequently Asked Questions
What is the Europe Welding Wires Market?
The Europe Welding Wires Market encompasses the industry involved in manufacturing and distribution of welding wires used in diverse fabrication, construction, and manufacturing applications across European countries. It supports various welding processes, notably arc welding, to enhance structural integrity and efficiency.
What is the current market size of Europe Welding Wires Market?
As of 2026, the Europe Welding Wires Market is valued at approximately USD 8.3 Billion, reflecting its significant role in the regional manufacturing sector. The market’s size is driven by robust industrial activities, infrastructure developments, and technological advancements in welding practices.
What factors are driving the Europe Welding Wires Market?
Growth is primarily propelled by increased demand for durable construction materials, the expansion of automotive and aerospace industries, and technological innovations such as automation and robotics. Trade policies and environmental regulations also influence market dynamics.
Which region dominates the Europe Welding Wires Market?
Western Europe leads the market due to its advanced manufacturing infrastructure, technological adoption, and high demand from key industries like automotive and aerospace. Countries such as Germany, France, and the UK are primary contributors to regional market dominance.
Which segment is expected to grow the fastest?
The mild steel welding wires segment is projected to witness the fastest growth, driven by its widespread application in construction, shipbuilding, and automotive manufacturing. It is favored for its cost-effectiveness and compatibility with various welding techniques.
Who are the leading companies operating in the Europe Welding Wires Market?
Major players include voestalpine Böhler Welding, Lincoln Electric Holdings, and ESAB. These companies focus on innovation, expanding production capacities, and strategic partnerships to strengthen their market positions across Europe.
Analyst Perspective
The Europe Welding Wires Market is approaching a mature stage, with steady demand driven by aging infrastructure and ongoing industrial modernization projects. Long-term growth prospects remain favorable, supported by increasing adoption of advanced welding technologies and stricter regulatory standards for quality and safety. Commercial opportunities are abundant in specialty and high-performance welding wires, especially in sectors such as aerospace, automotive, and energy. Technology evolution is expected to focus on automation-friendly products and environmentally sustainable formulations, which will likely influence R&D priorities and supply chain management. Investment should prioritize innovation in alloy compositions and process efficiencies to maintain competitive edge amid rising market saturation and intensifying rivalry. Regional growth potential is particularly strong in Eastern Europe, where manufacturing capacities are expanding, complemented by emerging demand in Western Europe’s eco-friendly and high-tech sectors. Strategic positioning will require balancing technological advancement with cost competitiveness and compliance to secure long-term leadership in this evolving landscape.
