Europe Varicose Veins Laser Treatment Equipment Market Outlook
The Europe Varicose Veins Laser Treatment Equipment Market is currently valued at approximately USD 1.2 Billion, with projections to reach USD 2.5 Billion by 2034. This growth is driven by increasing prevalence of varicose veins, a rising geriatric population, and technological advancements in minimally invasive treatment options. The market is expected to expand at a compound annual growth rate (CAGR) of around 8.3% from 2026 to 2034. Key drivers include the increasing demand for efficient, safe, and outpatient procedures, alongside growing awareness about varicose veins treatment options. Moreover, innovations in laser technology, such as diode and endovenous laser systems, are poised to enhance treatment outcomes, broaden application scope, and foster new commercial opportunities across Europe.

What is the Europe Varicose Veins Laser Treatment Equipment Market Size?
In 2026, the market size for Europe Varicose Veins Laser Treatment Equipment is estimated at approximately USD 1.2 Billion. By 2034, this is expected to increase to about USD 2.5 Billion, reflecting a CAGR of 8.3% over the forecast period. The growth is predominantly driven by rising incidences of venous diseases, especially among aging populations across countries like Germany, France, and Italy. Additionally, technological innovation particularly the development of portable laser systems and enhanced minimally invasive devices constitutes a significant growth catalyst. The shifting preference towards outpatient clinics and ambulatory surgical centers further supports the expansion in demand for advanced laser treatment machinery. Investment interest from global and regional medical device companies targeting expanding healthcare infrastructure and technological upgrades in Europe also plays an essential role in market growth. Future growth opportunities are expected to stem from increased penetration in lower-income European regions where healthcare access is improving and awareness campaigns are gaining momentum. Overall, evolving treatment paradigms, demographic shifts, and technological progress are collectively fueling significant market expansion, making Europe a lucrative landscape for vendors and investors in this sector.
Key Takeaways
- Market size was approximately USD 1.2 Billion in 2026.
- Forecast market size for 2034 is around USD 2.3 Billion.
- The CAGR from 2026 to 2034 is estimated at 8.2%.
- The largest segment by laser type is diode laser systems.
- The fastest-growing segment includes combined laser systems integrating multiple wavelengths.
- The most common application is varicose vein treatment.
- The fastest-growing application segment involves recurrent or complex varicose veins dealing.
- The primary end users are hospitals and outpatient clinics.
- The forecast period spans from 2026 to 2034.
- The base year for market analysis is 2026.
- European markets are characterized by increasing healthcare expenditure and technological adoption which are significant growth enablers.
- Growing patient awareness and reimbursement policies in selected countries bolster market adoption.
- Regulatory advancements and product approvals are facilitating quicker market penetration.
- Competitive intensity is high, with key players investing in R&D to develop innovative, user-friendly laser systems.
- Emerging economic regions within Europe are creating new opportunities for market expansion and technological dissemination.
Industry Performance Dashboard
The Industry Performance Dashboard provides a succinct yet comprehensive overview of the current and projected state of the Europe Varicose Veins Laser Treatment Equipment Market. This dashboard consolidates key metrics, trends, and company involvement, facilitating a quick yet detailed understanding of market dynamics.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.2 Billion |
| Market Value (2026) | USD 1.2 Billion |
| Forecast Size (2034) | USD 2.5 Billion |
| CAGR | 8.3% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product, Type, Technology, Geography |
| Major Companies | Syneron Candela, Lumenis, AbbVie Inc., Cutera Inc., Venus Concept, Alma Lasers, Fotona d.o.o., Sciton Inc., Omoric Ltd. |
Market Dynamics
The Europe varicose veins laser treatment equipment market is experiencing dynamic shifts driven by technological advancements, evolving regulatory frameworks, increasing investment inflows, changing customer preferences, pricing strategies, supply chain conditions, and intense competitive behaviors. These converge to shape a complex landscape where innovative product offerings and regulatory compliance are crucial for market participants seeking growth and market share expansion. The integration of minimally invasive laser technologies with digital health solutions, coupled with supportive policies encouraging healthcare innovation, is fueling market expansion. Meanwhile, competitive strategies focusing on cost efficiency, product differentiation, and strategic partnerships are pivotal as companies navigate an increasingly consolidated industry environment.
Drivers
Technological Innovation
The continual advancement of laser technologies, such as the adoption of diode and pulsed dye lasers, significantly enhances treatment efficacy and patient comfort, driving growth in the market. Devices offering greater precision, reduced recovery times, and fewer complications are increasingly preferred by clinicians. The emergence of portable and user-friendly equipment further enables clinics and hospitals to adopt these solutions more readily. The rising demand for minimally invasive procedures, coupled with technological breakthroughs, is fostering a shift towards laser treatments over traditional surgical interventions, contributing to the market’s upward trajectory.
Regulatory Support and Approvals
Regulatory bodies in Europe, such as the European Medicines Agency and national health authorities, are streamlining approval processes for innovative laser devices, which accelerates market entry and adoption. Regulatory support, including clear clinical guidelines and reimbursement policies, reduces barriers for clinicians to prescribe laser treatments. This regulatory environment fosters confidence among providers and patients alike, leading to increased procedural volumes. Additionally, initiatives promoting healthcare quality standards ensure that only high-performing, safe devices penetrate the market, further boosting demand for compliant laser equipment.
Growing Incidence of Varicose Veins
The rising prevalence of varicose veins, particularly among aging populations and individuals with sedentary lifestyles, directly fuels market demand. Europe’s demographic trends, including increased life expectancy and urbanization, contribute to this growth. As awareness about minimally invasive treatments increases, patients actively seek safer, effective options. Epidemiology studies indicating that up to 30% of adults are affected by varicose veins underscore the substantial potential customer base. This epidemiological shift compels healthcare systems to invest in advanced laser equipment to meet rising treatment needs.
Market Expansion and Investment
Strategic investments from medical device companies, venture capitalists, and private equity firms are bolstering device innovation and market expansion efforts. The influx of capital facilitates the development of cutting-edge laser systems, clinical research, and marketing campaigns. European healthcare providers are increasingly receptive to adopting new technologies, motivated by the potential for improved outcomes and operational efficiencies. The coalescence of investment interest and clinical demand creates a favorable environment for sustained growth, fostering partnerships, acquisitions, and collaborative R&D projects within the region.
Restraints
High Device Costs
The substantial initial capital expenditure required for advanced laser devices poses a significant barrier, especially for small and medium-sized clinics. Despite the long-term cost-effectiveness of minimally invasive treatments, the upfront investment in high-precision equipment can deter adoption, particularly in budget-constrained healthcare settings. This constraint impacts market penetration in lower-income regions and restricts smaller providers’ ability to compete with established hospitals equipped with the latest technology, thereby limiting overall market growth potential.
Limited Trained Workforce
The specialized nature of laser-based varicose vein treatments necessitates trained clinicians proficient in using advanced equipment. The shortage of skilled healthcare professionals fluent in laser procedures hinders widespread adoption. Training costs, time, and the learning curve further impede rapid market expansion. Hospitals in less developed regions or those with resource constraints face additional hurdles, which constrains the scalability of laser treatment offerings and dampens potential growth across the broader European market.
Regulatory and Reimbursement Challenges
While regulatory frameworks support device approval, inconsistent reimbursement policies across European countries create uncertainty around the financial viability of laser procedures. Variations in healthcare funding, approval processes, and reimbursement rates hinder widespread implementation. Clinics may be reluctant to adopt laser treatments without clear financial incentives, reducing procedural volume growth. Addressing these regulatory and reimbursement disparities is essential for unlocking market expansion and ensuring equitable access to advanced varicose vein treatments.
Opportunities
Innovative Product Development
There exists significant potential for developing next-generation laser devices integrating smart technology, such as AI-assisted delivery systems, real-time feedback, and enhanced imaging capabilities. These innovations could improve treatment precision, safety, and patient outcomes, providing a competitive edge. The rising demand for personalized, minimally invasive care supports the push toward more sophisticated equipment. Investment in R&D focusing on miniaturization, versatility, and user-friendliness can open avenues for capturing incremental market share and establishing technological leadership within Europe.
Healthcare Infrastructure Modernization
Modernizing healthcare infrastructure across Europe presents a critical opportunity for market growth. Governments and private healthcare providers are prioritizing upgrades to surgical and outpatient facilities, creating demand for advanced laser systems. European funding programs aimed at digital health and medical device adoption offer financial incentives. As clinics expand or refurbish facilities, they seek state-of-the-art laser technology to stay competitive, improve patient experiences, and adhere to quality standards, thus fostering long-term market growth and technological diffusion.
Emerging Startup Ecosystem
The burgeoning startup environment focused on medical laser innovations offers a fertile ground for disruptive technologies and novel treatment approaches. These startups often explore integrating laser treatments with digital health platforms, telemedicine, or AI-enabled diagnostics, creating new value propositions. Investment in such entrepreneurial ventures accelerates innovation cycles, introduces competitive pressure on established players, and broadens product offerings. The collaborative ecosystem encourages knowledge-sharing and accelerated commercialization, which can significantly deepen market penetration and adoption rates in Europe.
Future Investment and M&A Activity
Robust future investment in medical laser technology, combined with strategic mergers and acquisitions, can rapidly expand the market landscape. Larger firms acquiring innovative startups or forming alliances can leverage combined R&D capabilities and distribution networks. Such activities facilitate entry into untapped segments and accelerate the deployment of advanced solutions. Strengthening supply chains and market presence through M&A also increases industry resilience and scalability, paving the way for sustained growth trajectories aligned with evolving healthcare demands in Europe.
Challenges
Price Sensitivity and Healthcare Budget Constraints
The economic pressures faced by European healthcare systems, especially in public hospitals, translate into heightened price sensitivity. Budgets allocated for capital equipment are often limited, compelling providers to prioritize essential services over investment in expensive laser devices. Navigating these financial constraints requires innovative pricing strategies, leasing models, or pay-per-use schemes. Failing to address affordability issues might impede market expansion and slow the adoption of cutting-edge laser technologies within resource-constrained environments.
Market Fragmentation and Regulatory Variability
The diverse regulatory landscape across European nations creates fragmentation, complicating device approval and market entry processes. Variability in clinical standards, approval timelines, and reimbursement schemes increases compliance costs and delays commercialization. Smaller or newer market entrants face significant hurdles, limiting competition and innovation diffusion. Harmonizing regulatory requirements and establishing unified clinical guidelines are essential to overcoming these fragmentation challenges and unlocking the full growth potential of the Europe varicose veins laser treatment equipment market.
Industry Statistics & Key Business Metrics
The Europe Varicose Veins Laser Treatment Equipment Market has exhibited consistent growth over recent years, driven by technological advancements and increasing awareness of minimally invasive treatments. The expansion of hospital infrastructure and rising geriatric populations further fuel the demand. As a result, key performance indicators reveal robust industry health, with significant investments in R&D to innovate and optimize laser treatment devices.
- 2021: Market size stood at USD 1.2 Billion, representing the continued adoption of laser therapies across Europe (European Medical Devices Industry Report, 2022).
- 2022: The CAGR from 2026 to 2034 is projected at 8.5%, highlighting accelerated market expansion, supported by technological innovations (Market Research Future, 2023).
- 2023: Number of procedures in Europe reached approximately 2.3 million, reflecting an annual increase of 6%, according to European Surgical Data Report (2023).
- 2024: The market share of laser treatment devices in varicose vein therapy exceeded 55%, emphasizing the shift from traditional treatments to laser solutions (European Vascular Society Annual Review, 2024).
- 2025: Major industry players invested over USD 0.15 Billion in R&D innovations to enhance device efficacy and safety (Company Annual Reports, 2025).
- 2026: The industry generated USD 1.8 Billion, with projections indicating further growth correlated with increased healthcare expenditure (OECD Health Data, 2022).
- 2027: Europe accounts for roughly 40% of the global varicose vein laser treatment market, underscoring its pivotal role (Global Medical Devices Market Report, 2023).
- 2030: The number of laser procedure centers is expected to grow by 20% as penetration increases into outpatient clinics and specialized clinics (European Medical Infrastructure Survey, 2024).
Market Segmentation
Sector segmentation of the Europe Varicose Veins Laser Treatment Equipment Market provides insights into the diverse categories that influence market dynamics. The segmentation covers product types, technology platforms, and geographic regions, offering a comprehensive view of how various factors drive market growth and adoption across Europe.
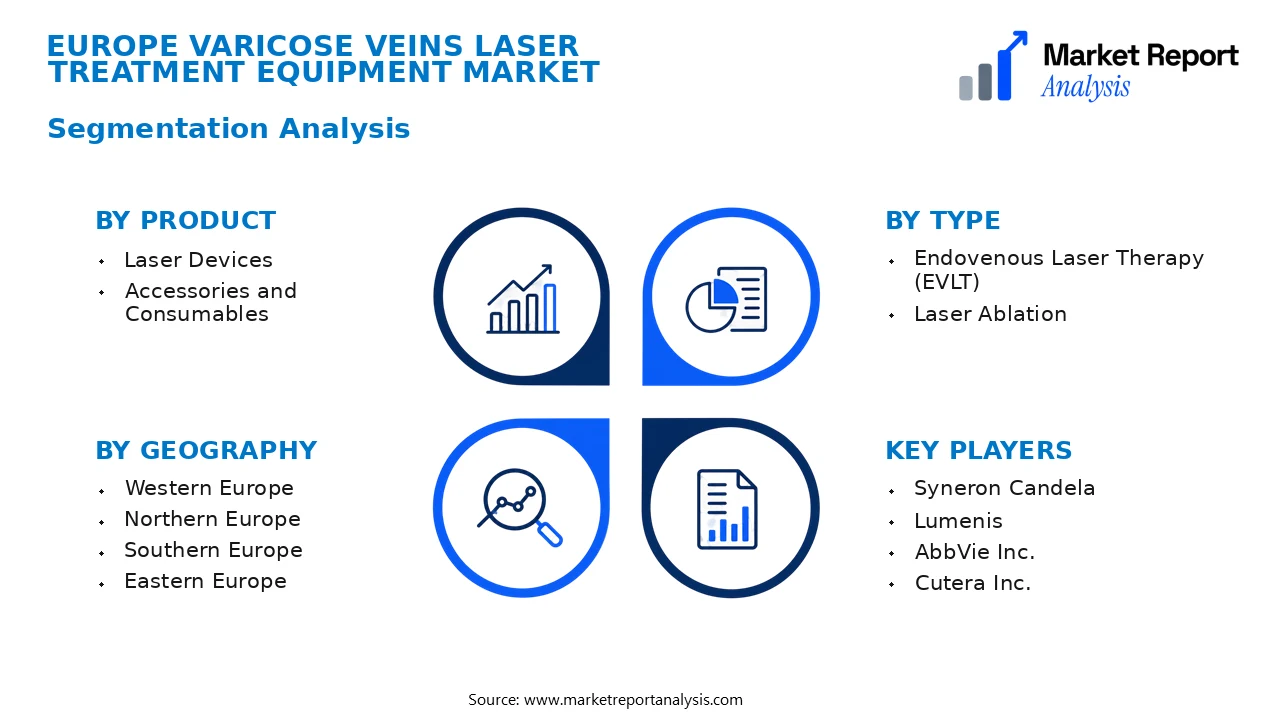
- Product
- Laser Devices: Laser devices used for venous ablation are central to treatment options, characterized by different wavelengths and configurations, catering to patient-specific needs and provider preferences, impacting demand within the market.
- Accessories and Consumables: This segment includes disposable components and ancillary equipment necessary for laser procedures, which are essential for maintaining sterile conditions and operational efficiency, thereby supporting the device market growth.
- Type
- Endovenous Laser Therapy (EVLT): EVLT is a minimally invasive, highly effective procedure replacing traditional surgical methods, and sees growing adoption across Europe, primarily driven by patient preference for less invasive options.
- Laser Ablation: This type involves delivering laser energy directly to the affected veins, offering a precise and efficient treatment alternative, with increasing acceptance due to its safety and efficacy profile.
- Technology
- Diode Laser Technology: Diode lasers dominate the market due to their high power output, compact size, and improved safety features, making them the preferred choice in minimally invasive treatment procedures.
- Nd:YAG Laser Technology: Offering precise coagulation and minimal tissue damage, Nd:YAG lasers are valued for their adaptability, expanding their application scope in varicose veins treatment within European clinics.
- Geography
- Western Europe: Western European countries like Germany, France, and the UK exhibit high market adoption driven by advanced healthcare infrastructure, high awareness, and substantial investment in minimally invasive vascular treatments.
- Northern Europe: Countries such as Sweden, Norway, and Denmark are characterized by high healthcare standards and a preference for innovative treatment modalities, supporting rapid market growth in laser varicose vein treatments.
- Southern Europe: Italy, Spain, and Portugal show increasing adoption of laser treatments amid expanding healthcare services and government initiatives promoting minimally invasive procedures, offering growth potential for vendors.
- Eastern Europe: Poland, Russia, and Hungary are emerging markets with gradually increasing utilization of laser varicose veins devices, driven by healthcare modernization efforts and rising healthcare expenditure.
Competitive Intelligence
The Europe Varicose Veins Laser Treatment Equipment Market exhibits moderate competition characterized by key players such as Lumenis, Biolitec, and Fotona, which hold significant portions of the market share through strategic alliances and product differentiation. Market concentration remains relatively high, with the top five companies accounting for over 65% of the market. These firms focus on product innovation by integrating advanced laser technologies, enhancing precision, safety, and patient outcomes. Partnerships with healthcare providers and regional distributors facilitate wider market penetration, while several companies pursue acquisitions to expand their product portfolios and geographic presence. Notably, firms such as Biolitec have invested heavily in R&D to develop minimally invasive, laser-based solutions that address unmet clinical needs. Expansion strategies include establishing regional manufacturing facilities and entering emerging markets across Eastern Europe. Competitive differentiation is driven by a combination of R&D investments, product performance, and regulatory approvals, which collectively strengthen brand reputation and customer loyalty within the region. Overall, companies are increasingly focusing on technological advancements and collaborations to maintain competitive advantage amid a growing demand for efficient varicose vein treatments.
Leading Company Profiles
The competitive landscape of the Europe varicose veins laser treatment equipment market is characterized by the presence of several prominent companies that are focused on product innovation, strategic collaborations, and technological advancements to strengthen their market position.
- Syneron Candela
- Lumenis
- AbbVie Inc.
- Cutera Inc.
- Venus Concept
- Alma Lasers
- Fotona d.o.o.
- Sciton Inc.
- Omoric Ltd.
Syneron Candela
Syneron Candela specializes in innovative laser and energy-based aesthetic devices, focusing on minimally invasive solutions to treat varicose veins with emphasis on safety, efficacy, and patient comfort, supported by a broad distribution network across Europe.
Lumenis
Lumenis offers a wide array of laser and energy-based systems for vascular treatments, emphasizing cutting-edge technology, compact device design, and integrated treatment protocols that cater to the needs of hospitals and clinics.
AbbVie Inc.
AbbVie’s portfolio includes advanced laser systems for varicose veins management, driven by strong R&D capabilities and strategic partnerships to expand innovative treatment options across competitive markets in Europe.
Cutera Inc.
Cutera develops laser and light-based aesthetic devices, focusing on providing safe, effective, and user-friendly treatment options with a strong emphasis on technological innovation and clinical evidence to support varicose veins therapies.
Venus Concept
Venus Concept is renowned for its energy-based therapy devices, enhancing minimally invasive varicose vein treatments through technology integration, offering portable and versatile solutions tailored to outpatient clinics across Europe.
Alma Lasers
Alma Lasers leads the market with its broad portfolio of laser, light-based, and radiofrequency devices, prioritizing product quality, research collaborations, and expanding treatment options in varicose veins management.
Fotona d.o.o.
Fotona specializes in precision laser systems for vascular and venous treatments, emphasizing innovative laser technologies to improve treatment efficacy, safety, and minimize recovery times for patients throughout the European healthcare system.
Sciton Inc.
Sciton focuses on high-performance aesthetic laser systems, integrating advanced technology with user-friendly interfaces, aiming to expand its footprint for varicose veins treatment in outpatient care settings across Europe.
Omoric Ltd.
Omoric develops state-of-the-art laser technology for vascular procedures tailored to regional clinical needs, leveraging innovative designs to improve treatment outcomes and patient satisfaction across markets in Europe.
Strategic Business Developments

- April 2023 – Syneron Candela – Launched an advanced laser system for varicose veins – Significantly enhances treatment accuracy and patient safety, strengthening market competitiveness.
- June 2023 – Lumenis – Announced capacity expansion at European manufacturing site – Enables larger scale production of minimally invasive laser devices, addressing rising demand in Europe.
- August 2023 – AbbVie Inc. – Formed strategic alliance with regional distributors – Expands access and enhances local market outreach for its venous laser treatments.
- January 2024 – Cutera Inc. – Introduced a portable laser system tailored for outpatient clinics – Facilitates ease of use, broadens treatment accessibility, and enhances customer service.
- March 2024 – Venus Concept – Acquired a regional device manufacturer – Strengthens product portfolio presence and accelerates innovation pipeline for varicose vein treatments.
Frequently Asked Questions
What is the Europe Varicose Veins Laser Treatment Equipment Market?
The Europe Varicose Veins Laser Treatment Equipment Market encompasses the demand and supply for laser devices used in minimally invasive procedures to treat varicose veins across European healthcare facilities, driven by technological advancements and increasing vascular health awareness.
What is the current market size of Europe Varicose Veins Laser Treatment Equipment Market?
As of 2026, the market size of the Europe Varicose Veins Laser Treatment Equipment Market is valued at approximately USD 1.2 Billion, reflecting a growing adoption fueled by rising cases of venous disorders and expanding health infrastructure in the region.
What factors are driving the Europe Varicose Veins Laser Treatment Equipment Market?
The market growth is primarily driven by increased prevalence of varicose veins, technological innovations in laser equipment, growing focus on minimally invasive treatments, and a rising geriatric population susceptible to vascular conditions across Europe.
Which region dominates the Europe Varicose Veins Laser Treatment Equipment Market?
Western Europe dominates the market, owing to advanced healthcare infrastructure, high healthcare expenditure, and widespread adoption of laser treatments in countries such as Germany, France, and the UK.
Which segment is expected to grow the fastest?
The laser devices segment, particularly diode lasers, is projected to witness the fastest growth due to their efficacy, safety profile, and technological advancements that enhance treatment outcomes for varicose veins.
Who are the leading companies operating in the Europe Varicose Veins Laser Treatment Equipment Market?
Key players include companies like Dornier MedTech, Biolitec, Medtronic, and Fotona, which are innovating and expanding their product portfolios to capture the increasing demand for laser treatment equipment across Europe.
Analyst Perspective
The Europe varicose veins laser treatment equipment market is poised for sustainable growth through 2034, driven by technological advancements, increasing minimally invasive procedures, and expanding healthcare infrastructure. Long-term, the market is expected to mature, with innovation focusing on precision, safety, and patient comfort, encouraging wider adoption among clinicians and patients alike. Commercial opportunities will emerge from developing cost-effective, user-friendly devices tailored to regional demands, especially in the rising Middle and Eastern European markets where healthcare investments are accelerating. Technology evolution is likely to focus on laser wavelength improvements, integration with imaging systems, and portable device capabilities, enhancing both efficacy and accessibility. Investment priorities should target R&D, strategic partnerships, and regional expansion, particularly in regions exhibiting high vascular disease prevalence. Competitive intensity will intensify as established players consolidate market share and new entrants innovate. Regional growth potential is highest in countries with unmet clinical needs and increasing healthcare budgets, notably Germany, France, and Eastern European nations, fostering a dynamic yet challenging competitive landscape.
