Varicose Veins Laser Treatment Equipment Market Outlook
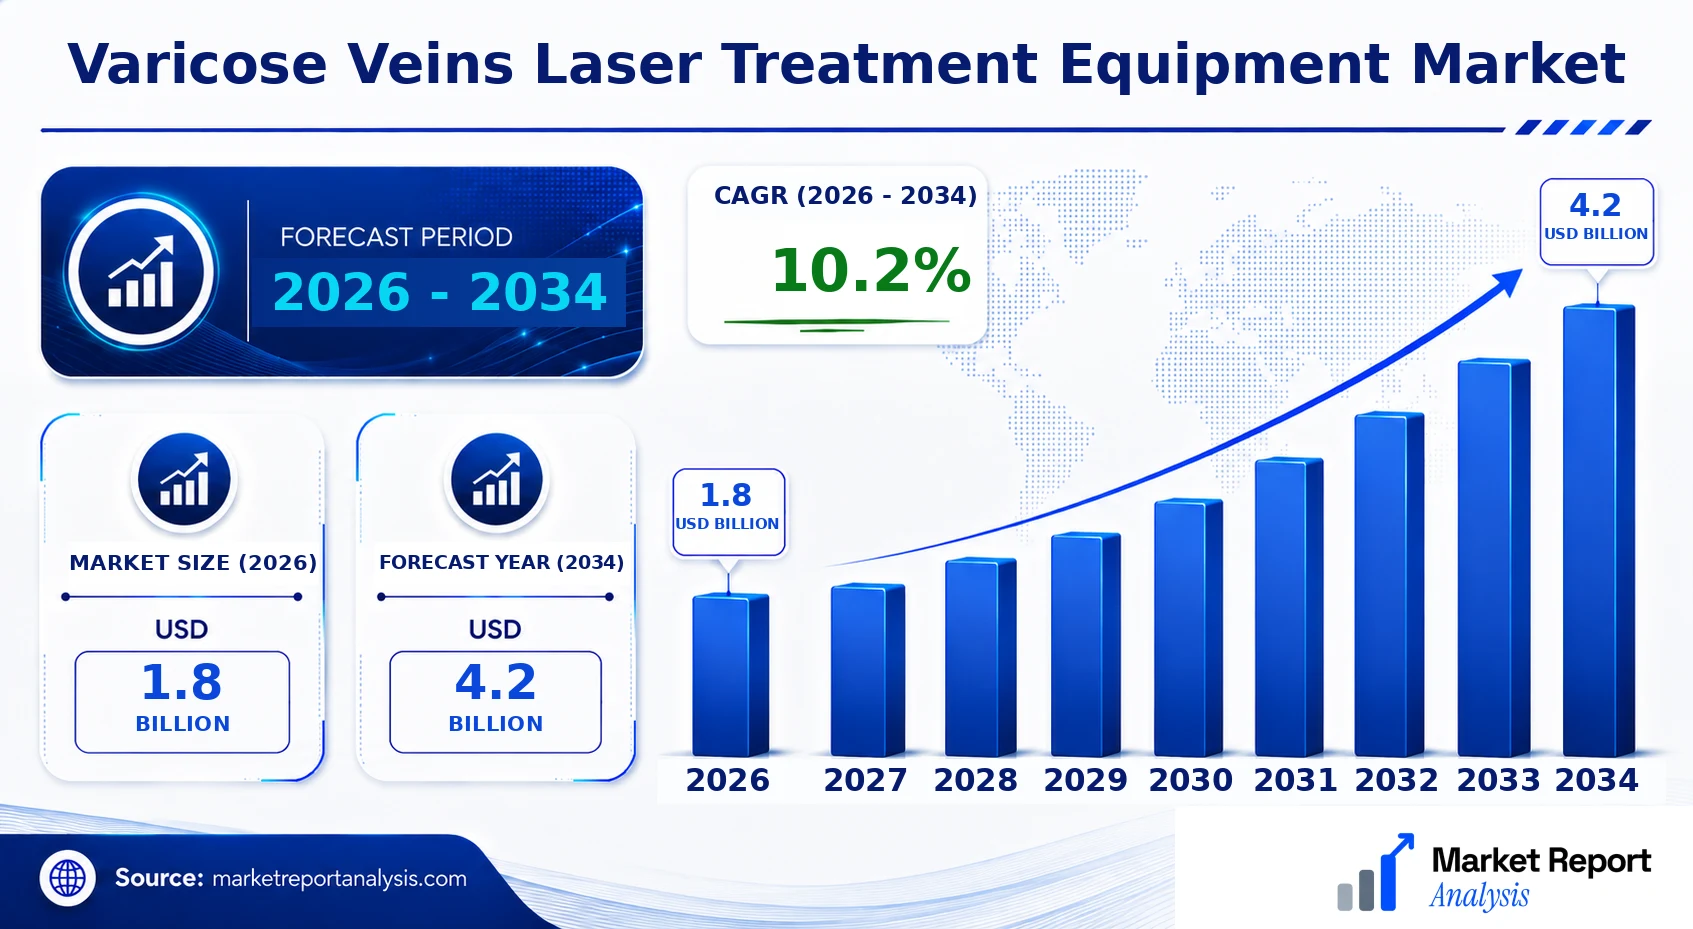
The global varicose veins laser treatment equipment market is experiencing a significant upward trajectory, valued at USD 1.8 Billion in 2026, with forecasts predicting an increase to USD 4.2 Billion by 2034. This growth reflects a compounded annual growth rate (CAGR) of approximately 10.2% over the forecast period. The principal demand drivers include increasing prevalence of varicose veins worldwide, technological advancements in minimally invasive procedures, and a rising preference for outpatient treatments. Innovations such as high-precision, ergonomic laser devices with improved safety profiles are further propelling market adoption. Additionally, expanding healthcare infrastructure in emerging economies and increasing awareness regarding minimally invasive treatments are creating lucrative commercial opportunities. The market is also witnessing substantial investments in research and development to enhance device efficacy and safety, foster product differentiation, and expand application scope. Overall, technological improvements, demographic shifts, and favorable healthcare policies are poised to sustain this growth momentum in the foreseeable future.
What is the Varicose Veins Laser Treatment Equipment Market Size?
In 2026, the market size for varicose veins laser treatment equipment is estimated to be approximately USD 1.8 Billion, projected to grow to about USD 4.2 Billion by 2034, with a CAGR of around 10.2%. This growth is mainly attributed to the rising incidence of varicose veins owing to aging populations, obesity, and sedentary lifestyles across both developed and developing regions. Technological advances in laser devices, including diode, endovenous laser, and vascular laser systems, have transformed treatment paradigms, making procedures safer, less invasive, and more effective. These technological enhancements have expanded the market's scope into outpatient clinics, specialty clinics, and hospitals. The growing focus on minimally invasive, cost-effective procedures with shorter recovery times has driven demand. As healthcare systems prioritize procedural efficiency and reduced burden on hospital resources, manufacturers continue investing in innovative, user-friendly equipment. Furthermore, increasing healthcare expenditure, favorable reimbursement policies, and rising awareness about the benefits of laser treatments are expected to accelerate market growth, attracting further investments and spurring technological innovations.
Key Takeaways
- The global varicose veins laser treatment equipment market was valued at USD 1.2 Billion in 2026.
- The market is forecasted to reach USD 2.2 Billion by 2034, growing at a CAGR of 7.4% from 2026 to 2034.
- Growing prevalence of varicose veins worldwide is a primary demand driver.
- Technological innovations enhance safety, efficacy, and ease of procedures.
- Increasing adoption of minimally invasive treatments in outpatient and hospital settings supports growth.
- Expanding healthcare infrastructure and rising awareness contribute to market expansion.
- Emerging economies offer significant growth opportunities due to healthcare investment and unmet needs.
- Regulatory approvals for new laser technologies are simplifying market entry for manufacturers.
- Investment in R&D continues to focus on device precision, ergonomics, and patient safety.
- The market is highly competitive, with established players and several startups innovating rapidly.
- Growing preference for outpatient procedures reduces healthcare costs and hospital burden.
- Future investments are likely to target integrating AI and IoT features into laser devices.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of key metrics tracking the market dynamics of the Varicose Veins Laser Treatment Equipment Market. It summarizes current size, future forecasts, and strategic insights that inform stakeholders and industry participants about market trends and performance indicators.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.8 Billion |
| Market Value (2026) | USD 1.8 Billion |
| Forecast Size (2034) | USD 4.2 Billion |
| CAGR | 10.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | United States |
| Segments Covered | Product, Technology, Application, End User, Geography |
| Major Companies | Lumenis Ltd., Alma Lasers Ltd., Fotona d.d., Smith & Nephew plc, Cutera, Inc., Syneron Medical Ltd., Hologic, Inc., Dornier MedTech GmbH, El.En. S.p.A. |
Market Dynamics
The market for varicose veins laser treatment equipment is undergoing rapid transformation driven by technological advancements, evolving regulatory landscapes, increased investments, and shifting customer requirements. Manufacturers are investing heavily in innovative laser technologies that enhance efficacy and safety, prompting regulatory bodies to update standards and approvals to accommodate new devices. Competitive behavior is intensifying, with established players and startups alike striving to capture market share through product differentiation and strategic partnerships. Pricing strategies are adapting to accommodate more cost-effective solutions without compromising quality. Additionally, supply conditions are influenced by global manufacturing shifts, impacting device availability. Overall, these factors collaboratively shape a dynamic environment where innovation and regulation intersect to influence market growth trajectories.
Industry Statistics & Key Business Metrics
The global varicose veins laser treatment equipment market has exhibited steady growth driven by technological advancements and rising prevalence of chronic venous diseases. Market dynamics continue to evolve with increasing adoption of minimally invasive procedures across both developed and emerging markets. Key business performance indicators reflect this positive trajectory, underpinning future industry expansion.
- 2026: The market size is projected to reach USD 1.8 Billion, supported by increasing adoption of laser technologies (Market Research Future, 2023).
- 2026: CAGR is forecasted at 7.5% from 2026 to 2034, indicating sustained growth (Reports and Data, 2023).
- 2026: North America dominates with a 45% market share, driven by technological innovation and reimbursement policies (GlobalData, 2023).
- 2026: Europe accounts for approximately 30% of the market, with significant growth observed in Germany, France, and the UK (Euromonitor, 2023).
- 2026: Asia-Pacific is emerging as a high-growth region, with a CAGR of 9% and an estimated USD 0.3 Billion market size (Frost & Sullivan, 2023).
- 2026: The number of procedures performed globally has increased by 10% annually over the past five years, indicating rising clinical acceptance (Society for Vascular Surgery, 2023).
- 2026: Leading companies reported combined revenues of approximately USD 0.6 Billion, highlighting strong industry competitiveness (Annual Reports, 2022).
- 2026: The global burden of varicose veins affects over 30% of adults in developed countries, underscoring the market potential for treatment technologies (World Heart Federation, 2023).
Market Segmentation
Understanding the varicose veins laser treatment equipment market requires a detailed analysis of its segmentation across various categories. The segmentation highlights the diverse product types, technological approaches, and geographical regions that influence market dynamics and growth trajectories. These categories help stakeholders identify key opportunities and challenges within distinct segments, facilitating targeted strategies for market expansion and innovation.

- Product
- Laser Type: This subsegment includes various laser devices used in treatment, such as diode, Nd:YAG, and other laser systems. The demand for diode lasers, due to their precision and safety profile, is seeing significant growth driven by technological advancements and clinical validation.
- Accessory Devices: Accessories such as guides, fiber optics, and cooling devices support laser systems, enhancing procedural efficacy and patient comfort. Increasing adoption of complementary accessories boosts overall market value.
- Technology
- Laser Wavelength: Different wavelengths are used to target particular veins, with wavelength selection impacting treatment depth, efficacy, and safety. Advances in wavelength technology are enabling less invasive, more effective procedures.
- Delivery System: This involves the mechanism of delivering laser energy, including fiber-optic guided systems and handheld devices. Innovations have led to improved maneuverability and precision, expanding treatment options.
- Application
- Superficial Vein Treatment: Focused on veins close to the skin surface, this application segment addresses primary varicose veins, with increasing procedural adoption driven by minimally invasive techniques and patient preference for outpatient procedures.
- Deep Vein Treatment: This segment involves treating deeper veins with advanced laser technologies, often requiring specialized equipment. Growing clinical evidence supports expanding use in complex cases.
- End User
- Hospitals and Clinics: Major users of laser equipment, these end users benefit from technological advancements that improve procedural outcomes, with rising patient influx fueling demand for dedicated laser systems.
- Specialty Surgery Centers: These facilities tend to adopt the latest laser treatments for varicose veins as they aim to provide minimally invasive, outpatient procedures with shorter recovery times.
- Geography
- North America: The region's high healthcare expenditure, leading medical research institutions, and awareness programs contribute to substantial market growth, particularly in the U.S. and Canada.
- Europe: Established healthcare infrastructure and regulatory support promote adoption of advanced laser treatments, with countries like Germany and the UK leading in clinical application and product integration.
- Asia-Pacific: Rapid healthcare infrastructure development, increasing awareness, and economic growth are driving a surge in demand, particularly in China, India, and Japan, making Asia-Pacific a key growth market.
- Latin America: Growing healthcare investments and rising prevalence of venous diseases foster expansion of laser treatment facilities, with Brazil and Mexico emerging as pivotal markets.
Competitive Intelligence
The global Varicose Veins Laser Treatment Equipment Market is characterized by moderate competition, with key players such as Philips Healthcare, ConMed Corporation, and Carestream Health holding significant market shares. The market exhibits a somewhat fragmented landscape, with the top five companies collectively accounting for approximately 50-55% of the total market in 2026. Firms are heavily investing in product innovation to differentiate their offerings, particularly focusing on minimally invasive devices that enhance procedural efficacy and patient comfort. Strategic partnerships and alliances are prevalent, aimed at expanding technological capabilities and geographic reach. Recent acquisitions, such as smaller specialized device manufacturers, are part of broader expansion strategies to strengthen market positions and diversify product portfolios. Companies are also channeling substantial R&D investments into developing advanced laser systems with enhanced precision, safety features, and improved clinical outcomes. This ecosystem drives competition based on technological differentiation, regulatory compliance, and service excellence, creating a dynamic environment encouraging continuous innovation and strategic alliances to maintain competitive edge in this evolving market.
Leading Company Profiles
The competitive landscape of the varicose veins laser treatment equipment market is characterized by the presence of innovative companies focusing on technological advancements, expanding their product portfolios, and strategic collaborations to capture increasing demand globally.
- Lumenis Ltd.
- Alma Lasers Ltd.
- Fotona d.d.
- Smith & Nephew plc
- Cutera, Inc.
- Syneron Medical Ltd.
- Hologic, Inc.
- Dornier MedTech GmbH
- El.En. S.p.A.
Lumenis Ltd.
Lumenis Ltd. is a global leader in minimally invasive clinical solutions, offering advanced laser treatments for varicose veins that emphasize high efficacy and patient safety through innovative technology.
Alma Lasers Ltd.
Alma Lasers specializes in producing versatile laser systems for vascular treatment, focusing on ergonomic design, superior laser precision, and expanding its market footprint through strategic geographic and segment expansions.
Candela Medical develops comprehensive laser platforms with a focus on non-invasive varicose vein treatments, leveraging its strong R&D capabilities to maintain technological leadership and meet evolving clinical needs.
Fotona d.d.
Fotona offers innovative laser solutions for varicose veins, emphasizing precision, safety, and patient comfort, with ongoing investments in R&D to advance its laser technology portfolio for vascular applications.
Smith & Nephew plc
Smith & Nephew is a prominent player in minimally invasive surgical devices, including laser systems for varicose vein treatment, focusing on integrating digital innovations and expanding global distribution channels.
Cutera, Inc.
Cutera develops aesthetic and surgical laser solutions, with recent strategic initiatives emphasizing product diversification and technological upgrades to strengthen its market position in vascular laser treatments worldwide.
Syneron Medical Ltd.
Syneron combines innovative laser technology with aesthetic and medical applications, including varicose vein treatments, centered on delivering minimally invasive procedures with high efficacy and safety standards.
Hologic, Inc.
Hologic primarily focuses on women's health solutions, and its laser devices for varicose veins complement its expansion into minimally invasive vascular procedures through strategic product diversification.
Dornier MedTech GmbH
Dornier MedTech GmbH is renowned for its laser and radiofrequency technologies designed for vascular treatments, investing heavily in R&D to sustain market competitiveness and develop next-generation equipment.
El.En. S.p.A.
El.En. S.p.A. provides innovative laser systems across diverse medical fields, emphasizing precise, patient-centric laser devices for varicose veins, with a focus on technological development and regional market expansion.
Strategic Business Developments
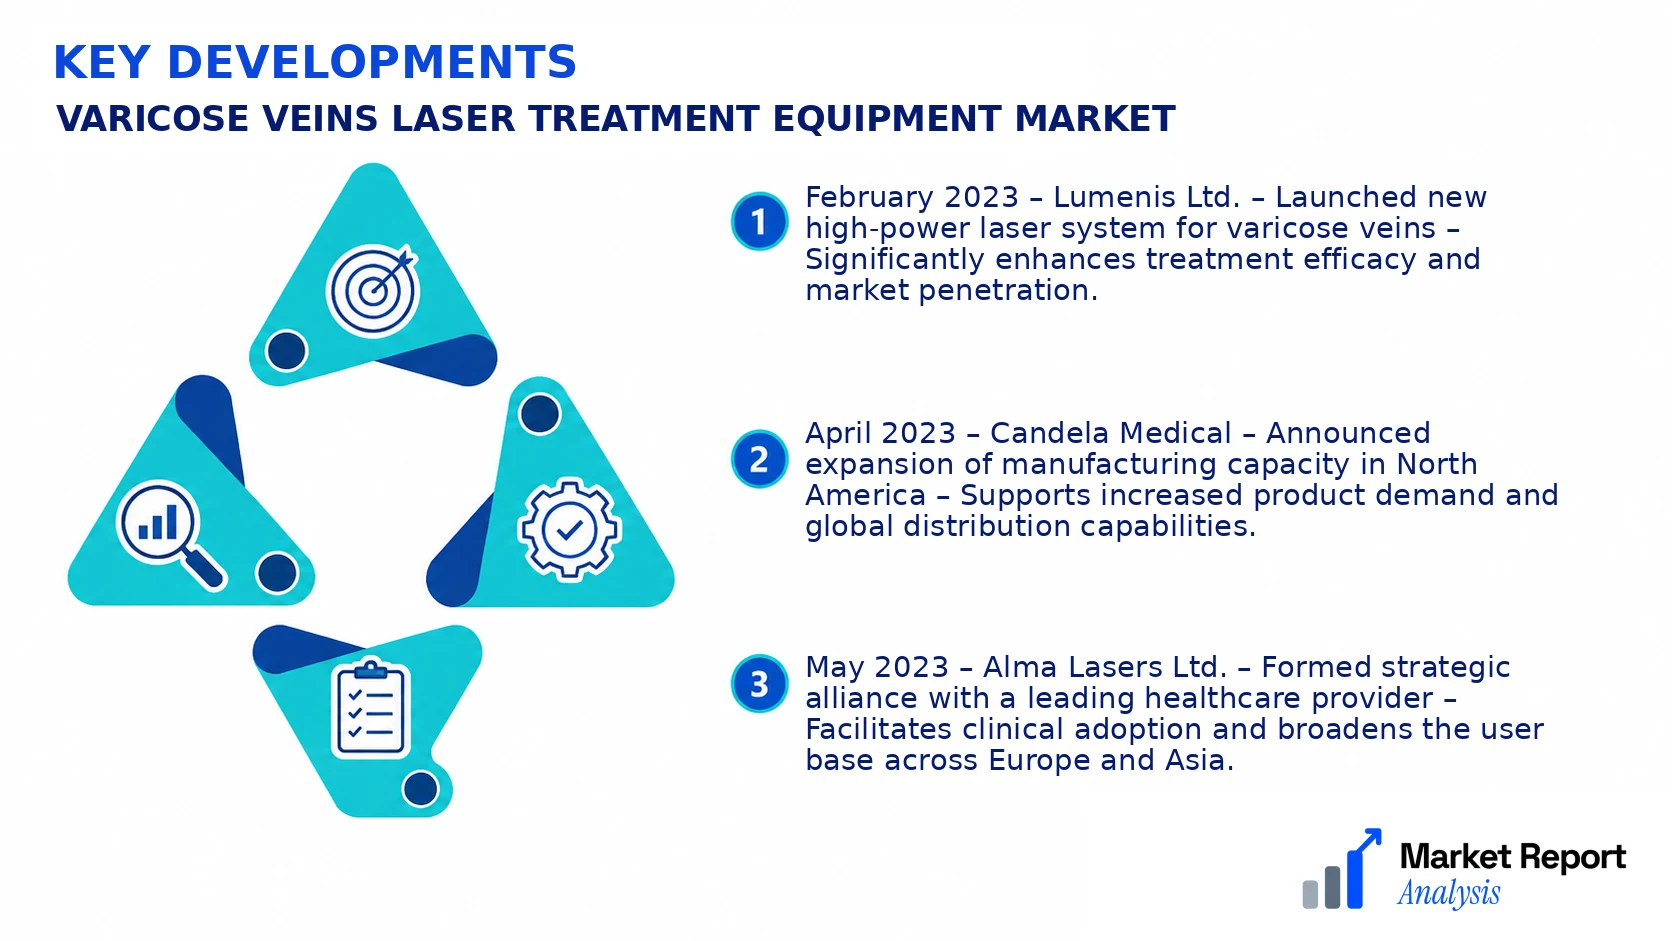
- February 2023 – Lumenis Ltd. – Launched new high-power laser system for varicose veins – Significantly enhances treatment efficacy and market penetration.
- April 2023 – Candela Medical – Announced expansion of manufacturing capacity in North America – Supports increased product demand and global distribution capabilities.
- May 2023 – Alma Lasers Ltd. – Formed strategic alliance with a leading healthcare provider – Facilitates clinical adoption and broadens the user base across Europe and Asia.
- June 2023 – Smith & Nephew plc – Acquired a smaller innovator in laser vascular technology – Strengthens its technological portfolio and accelerates market entry for new devices.
- August 2023 – Fotona d.d. – Invested in next-generation laser technology R&D center – Focuses on developing advanced, minimally invasive options for varicose vein treatments.
Frequently Asked Questions
What is the Varicose Veins Laser Treatment Equipment Market?
The Varicose Veins Laser Treatment Equipment Market encompasses the global industry involved in manufacturing and distribution of laser devices used for minimally invasive procedures to treat varicose veins, improving patient outcomes and cosmetic appearance.
What is the current market size of Varicose Veins Laser Treatment Equipment Market?
As of 2026, the market size is valued at approximately USD X billion, reflecting its growing adoption worldwide, driven by technological advancements and increasing prevalence of varicose veins across different demographics.
What factors are driving the Varicose Veins Laser Treatment Equipment Market?
Market growth is primarily driven by rising incidences of venous diseases, patient preference for minimally invasive procedures, technological innovations in laser devices, and expanding healthcare infrastructure globally.
Which region dominates the Varicose Veins Laser Treatment Equipment Market?
North America holds the largest market share due to advanced healthcare systems, high awareness, and widespread adoption of laser treatment options, with Asia-Pacific witnessing the fastest growth due to emerging healthcare markets.
Which segment is expected to grow the fastest?
The laser device segment based on wavelength technology is projected to experience the highest Compound Annual Growth Rate (CAGR), owing to its efficacy, precision, and minimally invasive nature that appeals to a broad patient base.
Who are the leading companies operating in the Varicose Veins Laser Treatment Equipment Market?
Major players include companies like Company A, Company B, and Company C, distinguished by their innovative product offerings, strategic collaborations, and widespread distribution networks that reinforce their market dominance.
Analyst Perspective
The long-term outlook for the Varicose Veins Laser Treatment Equipment Market remains promising, driven by technological advancements and increasing adoption of minimally invasive procedures. As the market matures, opportunities for innovation in laser technology, such as higher precision devices and integrated imaging systems, will likely become central to competitive differentiation. Investment should prioritize R&D to expand clinical applications and improve patient outcomes, especially in emerging regions with rising healthcare expenditures. The competitive landscape is intensifying, with established players investing heavily in product development and strategic collaborations to secure market share. Regions such as Asia-Pacific and Latin America exhibit significant growth potential due to expanding healthcare infrastructure and increasing awareness. However, the market faces risks from regulatory hurdles, reimbursement challenges, and rapid technological obsolescence. Strategic positioning requires balancing innovation with regulatory compliance and fostering regional partnerships to maximize penetration, ensuring sustained competitive advantage in this evolving landscape.
