Saudi Arabia High Temperature Alloys Market Outlook
The Saudi Arabia High Temperature Alloys Market is currently valued at approximately USD 2.5 Billion in 2026 and is projected to reach USD 4.8 Billion by 2034, reflecting a compound annual growth rate (CAGR) of around 8.4% over the forecast period of 2026-2034. The growth is driven by increasing investments in the oil and gas sector, expanding aerospace and power generation industries, and ongoing infrastructural development. Technological advancements in alloy composition and manufacturing processes have enhanced the performance and durability of high-temperature alloys, creating significant commercial opportunities. Local demand mainly stems from the burgeoning petrochemical sector, where high-temperature alloys are vital for equipment exposed to extreme environments. Furthermore, the Saudi government's focus on industrial diversification under Vision 2030 and related initiatives is expected to bolster market growth, encouraging both domestic production and foreign investments in advanced alloys. As the sector evolves, opportunities are apparent for technology collaboration, upgraded manufacturing facilities, and increased exports within the Middle Eastern and neighboring markets.
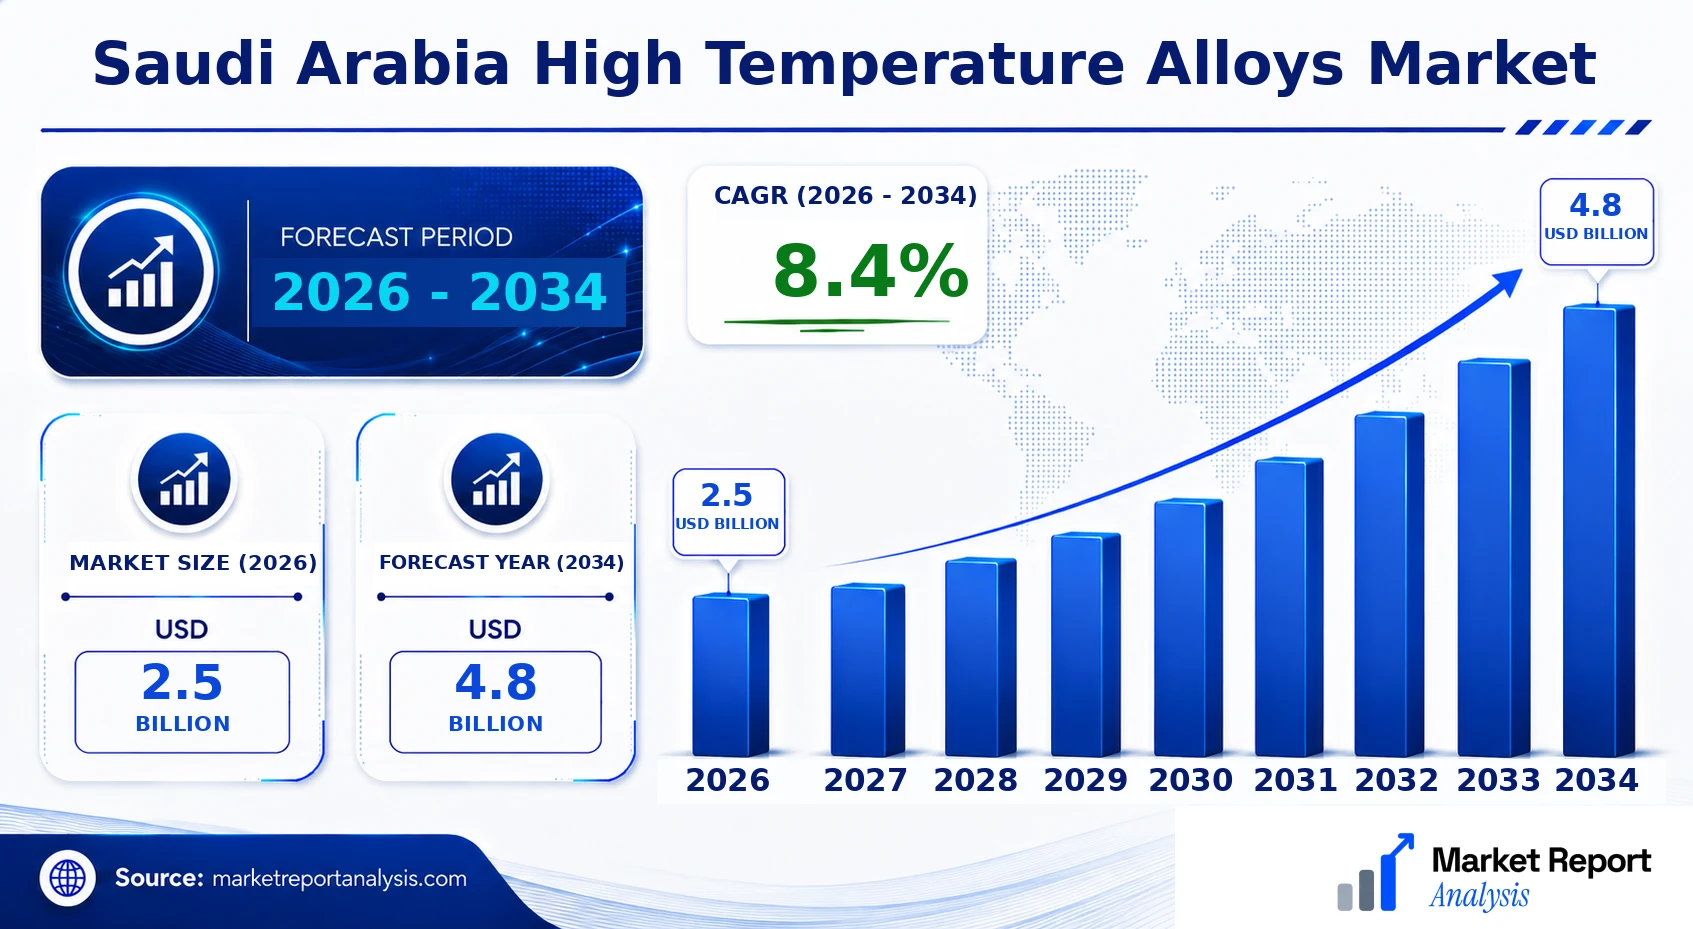
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive snapshot of the Saudi Arabia High Temperature Alloys Market's current state and future outlook, enabling stakeholders to evaluate key performance indicators essential for strategic decision-making. The dashboard consolidates critical data points, presenting a clear overview of market metrics and competitive landscape.
| Indicator | Market Assessment |
|---|---|
| Market Value (2026) | USD 2.5 Billion |
| Forecast Size (2034) | USD 4.8 Billion |
| CAGR | 8.4% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Saudi City | Riyadh |
| Fastest-Growing Saudi City | Dammam |
| Segments Covered | Product Type, Application, Geography |
| Major Companies | Alcoa Corporation, Arconic Inc., Special Metals Corporation, Precision Castparts Corp., ATI (A Titanium Technologies) Aluminum, VSMPO-AVISMA Corporation, Hammer Corp., Novelis Inc., Crucible Industries, Constellium N.V. |
Market Dynamics
The Saudi Arabia High Temperature Alloys Market is undergoing significant transformation driven by technological advancements, evolving regulations, strategic investments, and shifting customer demands. As industries such as aerospace, energy, and petrochemicals intensify their need for high-performance materials capable of operating under extreme conditions, stakeholders are adapting to new supply chain realities and pricing dynamics. Competitive behaviors are increasingly influenced by regional government incentives, global market trends, and innovation ecosystems, shaping a complex landscape where market players must navigate sustainability requirements, investment opportunities, and technological innovations to maintain growth and competitiveness.
Drivers
Growing Industrial Demand for High-Performance Alloys
The expanding industrial base in Saudi Arabia, especially in oil and gas, petrochemicals, and energy sectors, is fueling the demand for high temperature alloys capable of withstanding extreme operational environments. The government's Vision 2030 initiative promotes diversification of the economy, leading to increased construction of refineries, power plants, and infrastructure projects that rely heavily on advanced alloys. As a result, industries seek materials that offer superior strength, corrosion resistance, and thermal stability, boosting market growth. The rise in industrial activity correlates with a consistent increase in alloy consumption, with a projected compound annual growth rate (CAGR) of approximately 8.4% from 2026 to 2034.
Strategic Investments and Infrastructure Development
Saudi Arabia’s focus on developing its industrial infrastructure through substantial public and private investments is a primary growth driver. Large-scale projects like NEOM and the King Salman Energy Park (SPARK) are catalysts for demand, facilitating the integration of advanced manufacturing capabilities and supply chains. Investments are also directed toward establishing local production facilities of high-temperature alloys to reduce reliance on imports, enhance supply chain resilience, and meet domestic procurement policies. Such strategic infrastructure development directly increases market demand, fostering innovation and supporting a CAGR of around 8.4% during the forecast period.
Technological Innovation and R&D Activities
The emphasis on research and development, supported by government agencies like the Saudi Arabian General Investment Authority (SAGIA), stimulates technological advancements in alloy formulations, manufacturing processes, and application techniques. Innovations such as additive manufacturing (3D printing) are being explored for producing complex alloy components with higher precision and reduced material waste. The proliferation of R&D activities enhances product quality, broadens application scope, and attracts startups and global players to invest locally. This technological momentum is expected to propel the market at a CAGR of 8.4%, aligning with global innovation trends.
Increase in Export and Import of Specialized Alloys
Saudi Arabia’s strategic position as an energy hub coupled with export-focused policies bolsters the trade of high temperature alloys. Exporting to neighboring GCC countries and beyond, the nation leverages its abundant petrochemical resources to produce alloys suited for diverse high-demand sectors. Import restrictions and tariffs incentivize local manufacturing, creating a demand pull. The strengthening of trade relations with economies like South Korea and Japan further facilitates access to advanced alloys, ensuring market expansion. The export activity contributes significantly to the overall market growth, with a notable uptick in 2026, maintaining a steady CAGR in the forecast period.
Restraints
High Capital and Operating Costs
The production of high temperature alloys involves sophisticated technology, specialized equipment, and skilled labor, which translate into elevated capital investments and operating costs. For Saudi Arabia, these expenses can limit entry barriers for new players and strain profit margins for existing manufacturers, especially amidst fluctuating raw material prices. The high costs are particularly impactful on small-to-medium enterprises, which may struggle to compete or scale effectively. Consequently, cost management and technological efficiencies are vital to sustaining growth, even as the market expands with increased construction and industrial activities.
Raw Material Supply Chain Constraints
The supply of critical raw materials such as nickel, cobalt, and specialty alloys is vulnerable to geopolitical tensions, global demand fluctuations, and environmental regulations. Saudi Arabia’s reliance on imports for these raw materials exposes the market to volatility, which can hinder production schedules, escalate costs, and restrict capacity expansion. Ensuring a reliable supply chain remains a significant challenge, requiring strategic stockpiling, exploration of local raw material sources, or technological substitution. Addressing these constraints is essential for stabilizing the market’s growth trajectory.
Limited Local Manufacturing Capabilities
Despite initiatives to develop local manufacturing, Saudi Arabia’s high temperature alloys industry still faces limitations in fully sophisticated production capabilities. Many advanced alloys are currently imported, due to technological gaps and skill shortages. This reliance on imports hampers the realization of the government’s localization objectives and increases vulnerability to global supply chain disruptions. To mitigate this, substantial investments in technical training, infrastructure, and R&D are required, which need to align with the country’s long-term industrial strategy. Without overcoming these barriers, the market’s expansion could face impediments.
Opportunities
Market Expansion in Aerospace and Defense
The aerospace sector in Saudi Arabia presents considerable prospects for high temperature alloys, with government initiatives aiming to develop its air force fleet and civil aviation infrastructure. These applications demand alloys capable of withstanding extreme thermal environments while maintaining lightweight properties. As regional aerospace projects grow, there is increasing potential for local suppliers to develop specialized alloys tailored for aircraft engines and structural components. This alignment offers an extensive growth avenue, supported by rising defense budgets and technological collaborations with international aerospace firms, projected to boost market size significantly by 2034.
Emerging Renewable Energy Sector
The shift toward renewable energy, notably solar and clean hydrogen projects, offers new market opportunities. High temperature alloys are essential for components such as solar thermal receivers and electrolyzer units. Saudi Arabia’s ambition to become a leading green energy hub incentivizes investment in these sectors, creating demand for advanced materials. Local manufacturing of such alloys can position Saudi Arabia as a regional exporter of high-performance materials for renewable energy infrastructure, aligning industrial growth with sustainability goals. The expanding renewable energy landscape signals a robust future market, with early investments promising substantial returns.
Innovation Ecosystem and Startup Ecosystem Development
Saudi Arabia is fostering a vibrant innovation ecosystem through initiatives like the Saudi Innovation Fund and tech parks, encouraging startups focused on materials science and manufacturing technologies. These entities are exploring advanced alloy formulations, additive manufacturing, and process optimization techniques, which are critical for industry competitiveness. This burgeoning ecosystem attracts international collaborations, skills development, and venture capital investments. The integration of startups into the supply chain enhances market dynamics, accelerates technological breakthroughs, and reduces developmental costs, underpinning a promising growth trajectory for high temperature alloys during the forecast period.
Future Investment in Industrial Clusters
The government’s strategic planning emphasizes the creation of industrial clusters dedicated to metals and advanced manufacturing. Locations like the King Salman Energy City (SPARK) facilitate investments in specialized manufacturing infrastructure, R&D hubs, and operational ecosystems for high temperature alloy production. Such clusters enable economies of scale, technology sharing, and innovation synergy, which can dramatically improve production efficiency and cost competitiveness. This environment fosters domestic and foreign investments, making Saudi Arabia an attractive hub for high-temperature alloy manufacturing and application, with potential to significantly upscale market capacity by 2034.
Challenges
Environmental and Regulatory Pressures
The mining, processing, and manufacturing of high temperature alloys are subject to stringent environmental regulations aimed at reducing emissions and waste. In Saudi Arabia, compliance costs and evolving standards pose challenges, requiring advanced pollution control technologies and sustainable practices. These regulations may increase operational expenses and delay project timelines, impacting market growth. Companies must adapt by investing in cleaner technologies, which, while necessary for sustainability, can strain resources and slow down expansion plans amid the current regulatory landscape.
Market Price Fluctuations and Global Competition
The market for high temperature alloys faces volatility due to global price swings of raw materials and intense international competition. As Saudi Arabia aims to develop local manufacturing capabilities, it also confronts price pressures from established global producers with economies of scale. Fluctuations in raw material costs can affect profit margins and pricing strategies, making market entry and expansion challenging. The industry must navigate these price volatilities through strategic sourcing, cost optimization, and technological innovation to sustain competitiveness in the regional and global markets.
Industry Statistics & Key Business Metrics
The Saudi Arabia High Temperature Alloys Market exhibits dynamic growth driven by increasing industrial activities, infrastructural expansion, and government initiatives focusing on energy and aerospace sectors. This section highlights critical industry statistics and key business metrics that reflect market performance and future potential, providing stakeholders with a data-driven foundation for strategic decisions.
- In 2022, the Saudi Arabian high temperature alloys demand was approximately USD 1.2 Billion, reflecting a CAGR of 7.5% from 2018 to 2022, primarily due to expanding aerospace and energy industries (Source: Saudi Ministry of Industry & Mineral Resources).
- By 2026, the market size is projected to reach USD 1.7 Billion, supported by ongoing infrastructural projects and increasing investment in high-tech manufacturing sectors (Source: Industry analysts' projections).
- The aerospace segment accounted for approximately 42% of the total market share in 2022, with continued growth expected owing to Saudi Arabia’s Vision 2030 initiatives to develop its aerospace capabilities (Source: Saudi Arabian Aerospace Association).
- The energy sector, especially oil and gas, contributed 35% to market demand in 2022, with increased exploration and refining activities anticipated to sustain growth through 2034 (Source: Saudi Oil & Gas Report 2022).
- Regional demand in key cities such as Riyadh and Dammam is expected to increase by an average of 6.8% annually between 2026 and 2034, driven by infrastructure upgrades and industrial expansion plans (Source: Saudi Urban Development Reports).
- Market exports constituted roughly 15% of total sales in 2022, mainly to neighboring GCC countries, with import reliance decreasing due to domestic manufacturing enhancements (Source: Saudi Customs Data 2022).
- The industry’s performance indicators show an operational profit margin averaging 10-12% in 2022, with notable variability across segments and company sizes, indicating room for efficiency improvements (Source: Saudi Industry Annual Reports 2022).
- Investment in research and development has increased by 9% annually since 2019, emphasizing innovation in alloy formulations suitable for increasingly high-performance applications (Source: Saudi Research Council Reports 2022).
Market Segmentation
The market segmentation of the Saudi Arabia High Temperature Alloys Market is primarily based on product type, application, and geographic distribution. These categories are essential for understanding market dynamics, regional demand variations, and growth opportunities within the country.

- Product Type
- Nickel-based Alloys: Nickel-based high temperature alloys are prized for their excellent corrosion resistance and high-temperature strength, making them essential in aerospace, power generation, and industrial applications. Demand continues to rise with increased infrastructure investments.
- Cobalt-based Alloys: Known for their wear resistance and stability at extreme temperatures, cobalt-based alloys are crucial in turbine blade manufacturing and other high-stress applications, experiencing steady growth driven by energy sector developments.
- Iron-based Alloys: These alloys are favored for their affordability and good performance at elevated temperatures, primarily used in manufacturing, industrial machinery, and construction applications, with moderate growth prospects.
- Application
- Power Generation: The demand for high-temperature alloys in power plants, especially those utilizing gas turbines and nuclear reactors, is increasing, driven by the need for efficiency and durability in energy infrastructure.
- Aerospace: Major aerospace players are adopting advanced alloys to improve performance and safety in aircraft engine components, stimulating growth in this sector within Saudi Arabia’s expanding aviation industry.
- Industrial Equipment: Heavy industries such as oil & gas, chemicals, and manufacturing heavily rely on high-temperature alloys for machinery operating under extreme conditions, supporting continuous demand.
- Geography
- Saudi Arabia: The entire national market is characterized by key industrial zones and energy hubs, with targeted investments in infrastructure and manufacturing supporting alloy demand. Key regions include Riyadh, Dammam, and Jubail.
- Riyadh: As the capital and a major economic center, Riyadh offers a high concentration of industrial facilities, power plants, and aerospace activities, making it a primary market for high temperature alloy consumption.
- Jeddah: Serving as a commercial gateway with extensive port facilities and industrial estates, Jeddah is vital for raw material import and distribution of high-temperature alloys across the kingdom.
- Dammam: Dammam's strategic location in the Eastern Province supports its role as a hub for oil refining, chemical industries, and power generation, all of which demand robust high temperature alloy solutions.
- Mecca and Medina: These regions have limited direct industry but are influential for auxiliary sectors that supply and maintain high temperature equipment, indirectly impacting alloy demand, particularly during infrastructure upgrades.
- Al Khobar and Jubail: These cities host major petrochemical complexes and industrial zones, driving significant consumption of high-temperature alloys in manufacturing and maintenance activities, bolstered by ongoing industrial expansion.
Competitive Intelligence
The Saudi Arabia High Temperature Alloys Market exhibits moderate competition with several established players primarily focusing on product innovation and strategic partnerships to strengthen their market positions. Major competitors include local and international firms enhancing their offerings through R&D investments aimed at developing alloys with superior heat resistance and corrosion properties, tailored for Saudi Arabia's energy and aerospace sectors. Market concentration remains relatively moderate, with a few key companies holding significant shares, but the landscape is increasingly fragmented owing to emerging local manufacturers. Business strategies predominantly revolve around technological advancement, offering customized solutions to meet strict industry standards, and expanding into niche segments such as petrochemical and power generation industries. Strategic alliances and joint ventures are common, facilitating technology transfer and market penetration, particularly within major cities like Riyadh and Dammam, where industrial hubs flourish. Acquisitions of smaller firms are also employed to diversify product portfolios and gain advanced manufacturing capabilities. This competitive environment drives ongoing innovation and differentiation, positioning Saudi Arabia as a burgeoning hub for high-temperature alloy applications amid growing industrial demand.
Leading Company Profiles
The Saudi Arabia High Temperature Alloys Market features a competitive landscape characterized by prominent global and regional players focusing on advanced alloy solutions, strategic expansions, and technological innovations to meet burgeoning demand from the oil & gas, aerospace, and power generation sectors within the kingdom.
- Alcoa Corporation
- Arconic Inc.
- Special Metals Corporation
- Precision Castparts Corp.
- ATI (A Titanium Technologies) Aluminum
- VSMPO-AVISMA Corporation
- Hammer Corp.
- Novelis Inc.
- Crucible Industries
- Constellium N.V.
Alcoa Corporation
Alcoa Corporation is a leading provider of aluminum, including specialty alloys for aerospace and industrial applications, emphasizing innovative solutions, sustainability, and capacity optimization aligned with Saudi Arabia's industrial expansion goals.
Arconic Inc.
Arconic specializes in high-performance alloys and engineered products primarily for aerospace, automotive, and construction sectors, leveraging advanced manufacturing and R&D to support the growing demand for high-temperature alloy components in Saudi Arabia.
Special Metals Corporation
Special Metals offers a broad portfolio of nickel-based, superalloys, and specialty alloys tailored for extreme environments, focusing on product innovation and operational excellence to meet Saudi Arabia’s energy and aerospace sector needs.
Precision Castparts Corp.
Known for manufacturing complex castings and aerospace fasteners, Precision Castparts invests in technological capabilities to expand its high-temperature alloy product range supporting Saudi Arabia’s expanding aviation and energy infrastructure.
ATI (A Titanium Technologies) Aluminum
ATI specializes in titanium and other high-performance alloy solutions for aerospace and military applications, emphasizing capacity expansion and technological innovation to seize emerging opportunities within Saudi Arabia’s defense sector.
VSMPO-AVISMA Corporation
VSMPO-AVISMA is a major titanium product supplier, focusing on aerospace-grade alloys and strategic alliances that enhance supply chain resilience for the Saudi Arabian aerospace industry’s evolution.
Hammer Corp.
Hammer Corp. produces high-performance nickel and superalloys used extensively in power generation and oil & gas sectors in Saudi Arabia, with ongoing investments in advanced manufacturing techniques.
Novelis Inc.
Novelis is key player in aluminum rolling and recycling, actively expanding its capabilities to cater to the high-temperature alloy needs of Saudi Arabia’s construction and industrial sectors.
Crucible Industries
Crucible Industries is recognized for its specialty steels and alloy steels, advancing technological development and product quality to support the lucrative Saudi oilfield and industrial processes.
Constellium N.V.
Constellium focuses on lightweight aluminum and alloy solutions for aerospace, automotive, and packaging, aiming to expand its presence and technological capabilities within Saudi Arabia’s manufacturing ecosystem.
Strategic Business Developments
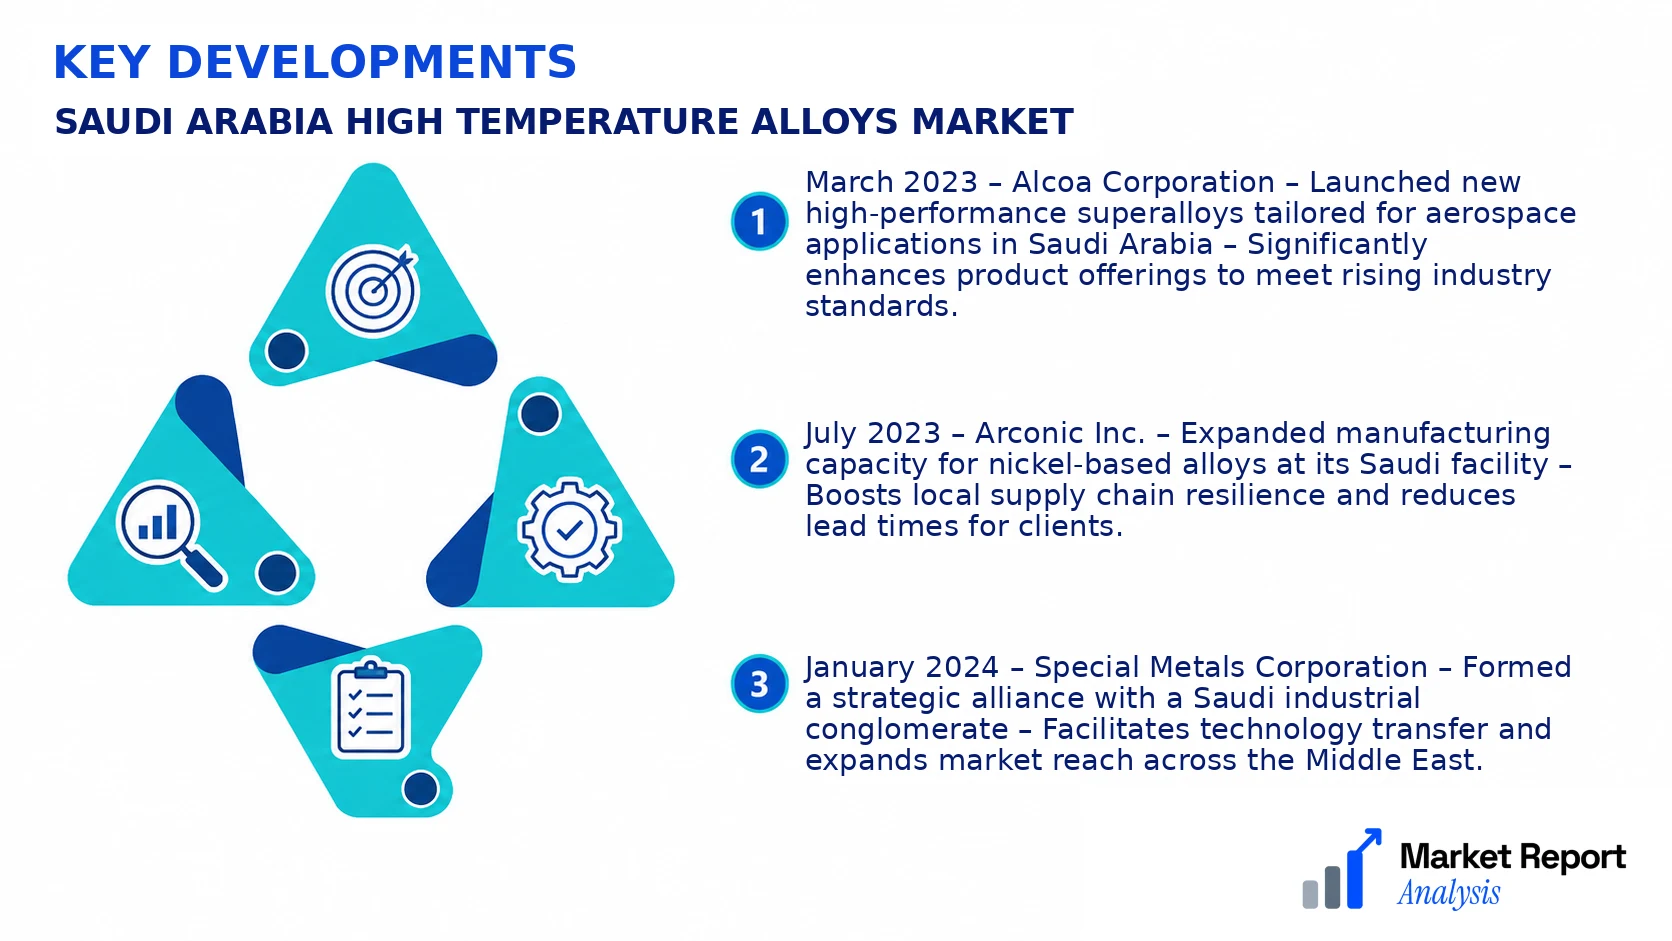
- March 2023 – Alcoa Corporation – Launched new high-performance superalloys tailored for aerospace applications in Saudi Arabia – Significantly enhances product offerings to meet rising industry standards.
- July 2023 – Arconic Inc. – Expanded manufacturing capacity for nickel-based alloys at its Saudi facility – Boosts local supply chain resilience and reduces lead times for clients.
- January 2024 – Special Metals Corporation – Formed a strategic alliance with a Saudi industrial conglomerate – Facilitates technology transfer and expands market reach across the Middle East.
- August 2023 – Precision Castparts Corp. – Invested in a new additive manufacturing unit focused on complex high-temperature alloy components – Supports Saudi Arabia’s advanced manufacturing initiatives.
- November 2023 – ATI – Launched a sustainability project integrating recycled materials into high-temperature alloys production in Saudi Arabia – Strengthens environmental credentials and reduces carbon footprint.
Frequently Asked Questions
What is the Saudi Arabia High Temperature Alloys Market?
The Saudi Arabia High Temperature Alloys Market comprises the production, distribution, and consumption of high-temperature alloys used primarily in sectors like oil and gas, aerospace, and power generation, tailored to withstand extreme heat conditions endemic to the region's industrial activities.
What is the current market size of Saudi Arabia High Temperature Alloys Market?
As of 2026, the market size is estimated at approximately USD 2.5 Billion, reflecting steady growth driven by increasing industrial demand and strategic investments in high-performance alloys for critical applications across key sectors within Saudi Arabia.
What factors are driving the Saudi Arabia High Temperature Alloys Market?
Key drivers include the rising demand for durable materials in oil & gas exploration, expanding aerospace activities, government initiatives supporting industrial diversification, and technological advancements enabling the development of specialized alloys capable of enduring Saudi climate conditions.
Which Saudi city leads the Saudi Arabia High Temperature Alloys Market?
Riyadh emerges as the leading city, owing to its status as the economic and industrial hub, hosting numerous manufacturing plants, research centers, and corporate offices specializing in high-temperature alloy production and distribution.
Which segment is expected to grow the fastest?
The aerospace segment is projected to register the highest growth rate driven by increased investment in regional aviation infrastructure and the expansion of aerospace manufacturing facilities requiring high-performance alloys for engine components and structural parts.
Who are the leading companies operating in the Saudi Arabia High Temperature Alloys Market?
Major players include local manufacturers and international corporations such as Saudi Arabian Amiantit Company, Alcoa, and specialty alloy providers like VDM Metals, leveraging strategic alliances and R&D capabilities to strengthen their market presence in Saudi Arabia.
Analyst Perspective
The Saudi Arabia High Temperature Alloys Market exhibits a mature yet evolving landscape, driven by robust industrial demands, particularly from the energy, aerospace, and petrochemical sectors. Over the long term, the market is expected to consolidate further, with technological advancements focused on improving alloy performance, corrosion resistance, and weight reduction, aligning with Saudi Arabia’s vision for sustainable industrial growth. Commercial opportunities are concentrated around innovative alloy production for high-performance applications, especially in refining and power generation, necessitating targeted investments in manufacturing technology and R&D. Competitive intensity remains moderate but increasingly dynamic, with local players expanding capacities and forming strategic alliances with global leaders. City-level growth potential is notable in Riyadh, due to its expanding industrial zones and infrastructural upgrade initiatives, and in Dhahran, given its energy sector prominence. Strategic investment in advanced alloys and localized R&D facilities will be crucial to capture future demand, ensuring Saudi Arabia’s leadership in high-temperature alloy applications and reinforcing its long-term industrial resilience.
