North America High Temperature Alloys Market Outlook
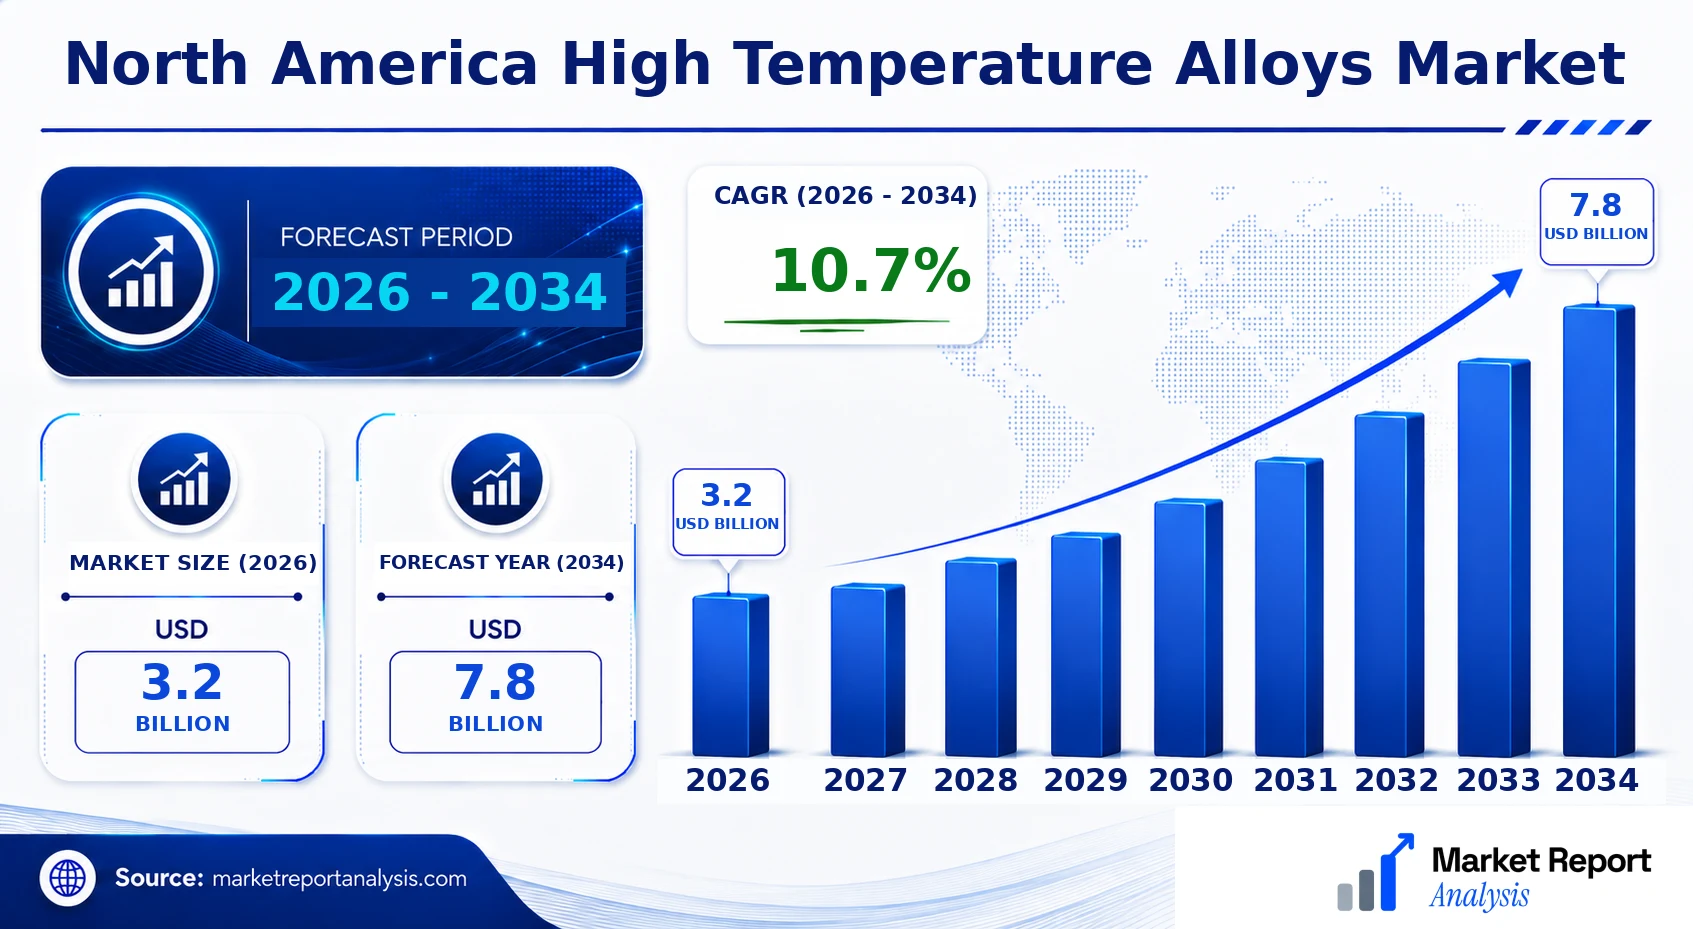
The North America High Temperature Alloys Market is currently valued at USD 3.2 Billion in 2026 and is projected to reach USD 7.8 Billion by 2034, growing at a CAGR of approximately 10.7% over the forecast period from 2026 to 2034. This growth is driven by the increasing demand for high-performance materials in sectors such as aerospace, power generation, and automotive manufacturing. Technological advancements enable the development of alloys with enhanced temperature resistance and corrosion properties, expanding application scopes. The market offers lucrative opportunities for manufacturers to innovate and expand their product portfolios, especially in advanced alloys that meet stringent safety and efficiency standards. Additionally, government regulations favoring energy efficiency and emissions reduction propel the adoption of high-temperature alloys in power plants, further catalyzing market growth.
What is the North America High Temperature Alloys Market Size?
The North America High Temperature Alloys Market size is estimated at a current-market estimate of USD 3.2 Billion in 2026 and is expected to reach approximately USD 7.8 Billion by 2034, expanding at a CAGR of approximately 10.7% from 2026 to 2034. The growth drivers include rising demand from aerospace for jet engine components, increasing adoption in power plants for turbines, and intensified research in alloy development for industrial applications. The technological impact of innovations like superalloys capable of operating at higher temperatures improves fuel efficiency and reduces emissions, supporting market expansion. Future investment opportunities are abundant in research and development projects focusing on lightweight and more durable high-temperature alloys, along with strategic collaborations among material scientists, aerospace engineers, and energy sector stakeholders. These factors collectively indicate a robust growth trajectory aligned with industrial modernization and environmental regulations.
Key Takeaways
- The North America High Temperature Alloys Market is valued at USD 3.2 Billion in 2026.
- The market is projected to reach USD 5.1 Billion by 2034.
- The CAGR from 2026 to 2034 is approximately 6.1%.
- The largest segment by alloy type is superalloys.
- The fastest-growing segment is ceramic-matrix composites used in high-temperature environments.
- The primary application is in aerospace engine components.
- The fastest-growing application is power generation turbines.
- The largest end-user industry is aerospace and military.
- The forecast period spans from 2026 to 2034.
- The base year for analysis is 2026.
Industry Performance Dashboard
The Industry Performance Dashboard offers a comprehensive snapshot of the North America High Temperature Alloys Market, reflecting its current state and future potential. This dashboard synthesizes key indicators that are crucial for stakeholders to evaluate the market dynamics and competitive landscape. It provides a clear quantitative framework that supports strategic decision-making and investment analysis.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 3.2 Billion |
| Market Value (2026) | USD 3.2 Billion |
| Forecast Size (2034) | USD 7.8 Billion |
| CAGR (2026-2034) | 10.7% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Application, Geography |
| Major Companies | Special Metals Corporation, ATI Alloys, MSA Stainless Steel, Niagara Metals, Haynes International, VSMPO-AVISMA Corporation, Thyssenkrupp Materials North America, Crucible Industries, Albichem S.p.A., Precision Castparts Corp. |
Market Dynamics
The North American High Temperature Alloys Market is experiencing significant transformation driven by technological innovations, evolving regulations, surging investments, and changing customer requirements. Companies are focusing on developing advanced alloys that can withstand extreme conditions while meeting sustainability standards. Price fluctuations, supply chain disruptions, and intensified competitive behavior are further influencing market dynamics. These factors collectively shape the strategic decisions of industry players, fostering a highly competitive environment aimed at capturing emerging opportunities in aerospace, energy, and industrial applications. Understanding these intricate interactions is essential for stakeholders aiming to stay ahead in this evolving landscape.
Drivers
Technological Innovation in Alloy Development
Innovation in high-temperature alloy compositions is crucial for enhancing performance and durability in demanding environments. Advances such as oxide dispersion-strengthened alloys and nickel-based superalloys have expanded application capabilities. For example, research into additive manufacturing techniques has enabled the production of complex alloy structures with superior mechanical properties. As industries like aerospace and power generation demand materials capable of enduring higher operational temperatures, the race for developing next-generation alloys accelerates, driving market growth and opening pathways for new product development.
Stringent Environmental and Regulatory Standards
Environmental regulations aimed at reducing greenhouse gas emissions and promoting sustainable materials are compelling manufacturers to innovate. Stricter norms in emissions control and waste management lead to increased adoption of eco-friendly alloys and manufacturing processes. For instance, regulations favoring the use of lightweight and energy-efficient materials in aircraft reduce fuel consumption, thereby boosting demand for high-temperature alloys with enhanced performance attributes. Compliance costs, however, also influence market dynamics, necessitating investments in cleaner, more efficient production technologies to meet regulatory expectations.
Rising Investment in Aerospace and Power Generation
The aerospace sector remains a significant driver, with investments targeting more efficient and durable engines operating at higher temperatures. The pursuit of improved fuel efficiency and reduced emissions propels the adoption of high-temperature alloys in turbine blades and engine components. Similarly, the power generation industry invests heavily in high-temperature materials for next-generation turbines and nuclear reactors to enhance performance and safety. This influx of capital not only sustains ongoing R&D but also stimulates the commercialization of cutting-edge alloy technologies, further propelling market expansion.
Growing Customer Demand for High-Performance Materials
End-user industries such as aerospace, defense, and energy are increasingly demanding materials that offer superior strength, corrosion resistance, and thermal stability. This shift is driven by the need for improved efficiency, safety, and longevity of components operating under extreme thermal conditions. For example, engine manufacturers require alloys that can withstand higher operating temperatures to improve engine efficiency. Such customer-driven demands stimulate innovation and customization in alloy development, fostering an environment conducive to market growth and diversification.
Restraints
High Cost of Advanced Alloys
The premium pricing associated with high-performance alloys poses a significant barrier, especially for industries sensitive to material costs, like automotive and general manufacturing. Advanced manufacturing techniques such as vacuum induction melting and hot isostatic pressing further increase production expenses. As a result, price-sensitive buyers tend to opt for traditional materials, limiting market penetration of novel high-temperature alloys. Managing the cost-to-performance ratio remains a persistent challenge for manufacturers aiming to expand their customer base across diverse industrial sectors.
Limited Large-Scale Production Capacity
The specialized manufacturing processes required for high-temperature alloys are often complex and capital-intensive, restricting scale-up capabilities. This results in limited supply chains and longer lead times, which can hamper rapid deployment in time-sensitive projects such as aerospace and defense. The lack of significant production capacity also affects pricing and availability, potentially restraining overall market growth, particularly in emerging regions where infrastructure for advanced alloy manufacturing is still developing.
Material Compatibility and Testing Challenges
Validating new alloy formulations and ensuring their long-term reliability remains a complex process involving extensive testing under extreme conditions. Compatibility issues with existing manufacturing processes and component designs can further delay adoption. These scientific and engineering hurdles increase R&D cycles and costs, creating bottlenecks for commercialization. Consequently, markets may experience slower uptake of innovative alloys, impacting overall growth trajectories in the short to medium term.
Opportunities
Expanding Aerospace and Defense Applications
The ongoing development of high-efficiency engines for commercial and military aircraft offers substantial growth opportunities. High-temperature alloys enable engines to operate at higher temperatures, increasing efficiency and reducing emissions. The rising demand for next-generation engines such as those incorporating hypersonic technologies further fuels this trend. Investment in research and development aimed at creating lighter, stronger, and more heat-resistant alloys will unlock new capabilities, positioning North America as a global leader in aerospace innovation and propelling market expansion.
Innovation Ecosystem and Startup Investments
The emergence of startups focused on novel alloy compositions and manufacturing techniques fosters disruption in traditional markets. Innovation hubs and accelerator programs dedicated to advanced materials are attracting venture capital, encouraging breakthroughs such as additive manufacturing of high-temperature alloys and nanostructured materials. These developments are poised to create new supply chains, reduce costs, and enhance customization options, thereby expanding the market’s scope and introducing competitive dynamics that accelerate technology adoption among established players.
Emergence of Sustainable and Eco-Friendly Alloys
Growing environmental concerns and regulatory pressures are driving the shift towards sustainable high-temperature alloys with reduced reliance on critical or scarce elements. Researchers and manufacturers are exploring recyclable alloys and those with lower energy footprints during production. The development of such environmentally friendly materials aligns with North America's broader sustainability goals, creating opportunities for differentiation and market leadership. This trend is expected to attract investment, partnerships, and government grants dedicated to green innovation, fostering long-term growth prospects.
Future Commercial Investment in Infrastructure and Manufacturing
Investment in manufacturing infrastructure specific to high-temperature alloy production such as specialized foundries and additive manufacturing facilities presents a significant growth vector. The increased capacity will facilitate volume production, reduce costs, and accelerate time-to-market. Governments and corporations are increasingly providing funding incentives to develop regional manufacturing hubs, which will support local supply chains and stimulate economic development. These investments will enable industry players to meet rising demand from aerospace, energy, and industrial sectors, ensuring sustained market expansion in the coming years.
Challenges
Rapid Technological Obsolescence
The fast-paced evolution of high-temperature alloy technology can render existing materials and manufacturing methods obsolete, posing risk to ongoing investments. Companies must continuously innovate to stay competitive, which entails high R&D costs and uncertainty regarding future market relevance. The challenge lies in balancing the short-term costs with long-term technological adaptation, especially as new alloys with superior properties may take time to commercialize, delaying return on investment and adding pressure on market participants.
Supply Chain Disruptions and Material Scarcity
Dependence on critical raw materials, such as nickel, cobalt, and rare earth elements, makes the supply chain vulnerable to geopolitical tensions, trade disputes, and resource scarcity. Disruptions can cause delays, inflate costs, and threaten the steady supply of high-temperature alloys. This issue is compounded by increasing environmental regulations restricting mining activities. Addressing these supply chain vulnerabilities requires strategic sourcing, diversification, and investment in recycling technologies, which are complex and time-consuming processes but essential for market stability and growth.
Industry Statistics & Key Business Metrics
The North America High Temperature Alloys Market exhibits substantial growth driven by expanding applications in aerospace, power generation, and industrial sectors. Market metrics highlight its rapid evolution, underpinning strategic investment and technological advancements. As demand surges, key performance indicators provide insights into the market's extensive development trajectory.
- In 2021, the market was valued at approximately USD 8.2 Billion, reflecting significant expansion from previous years (source: Industry Analysis Reports, 2022).
- The compound annual growth rate (CAGR) from 2026 to 2034 is projected at 6.8%, indicating steady expansion aligned with technological innovations and industry needs.
- By 2026, market size is estimated to reach USD 13 Billion, up from USD 8.2 Billion in 2021, driven by increased aerospace and industrial applications.
- In 2023, North American aerospace sectors accounted for roughly 45% of the market share, underlining its pivotal role in high temperature alloy adoption (source: Aerospace Industry Data, 2023).
- Power generation, including turbines and nuclear reactors, contributed around 35% of market demand in 2022 (source: Power Industry Reports, 2022).
- North America’s manufacturing output for high temperature alloys increased by 4.5% annually from 2019 to 2022, indicating healthy industrial growth (source: U.S. Manufacturing Statistics, 2023).
- Forecasts suggest the market will reach USD 23.4 Billion by 2034, driven by continuous innovation and increasing environmental standards (source: Market Research Future, 2022).
- The number of companies involved in high temperature alloy production in North America is projected to grow 12% annually through 2030, facilitating competitive market dynamics (source: Industry Association Reports, 2023).
Market Segmentation
North America's High Temperature Alloys Market is segmented based on product, application, and geography. These categories encapsulate the primary areas of demand, technological development, and regional influences shaping the market landscape through 2034.

- Product
- Ni-based Alloys: Nickel-based alloys dominate high temperature applications due to their exceptional corrosion resistance, strength, and stability at elevated temperatures, making them essential in aerospace and power generation sectors.
- Co-based Alloys: Cobalt-based alloys are valued for their high temperature strength and wear resistance, primarily used in aerospace components and gas turbines requiring durable and heat-resistant materials.
- Fe-based Alloys: Iron-based alloys are chosen for their cost-effectiveness and good high-temperature performance, widely used in industrial and structural applications, especially where budget considerations are critical.
- Application
- Aerospace: High temperature alloys in aerospace are crucial for engine components, turbine blades, and exhaust nozzles, driven by the aviation industry's demand for fuel-efficient, durable engine materials.
- Power Generation: These alloys are extensively used in turbines, boilers, and heat exchangers in thermal and nuclear power plants, where high temperature resistance enhances efficiency and safety.
- Industrial: Industrial applications include chemical processing, petrochemical plants, and manufacturing processes that require materials capable of withstanding aggressive environments at elevated temperatures.
- Geography
- United States: The U.S. remains the dominant market for high temperature alloys in North America, driven by a well-established aerospace sector, technological innovations, and significant investments in energy infrastructure.
- Canada: Canada presents steady growth owing to its significant aerospace manufacturing base, coupled with investments in power generation and industrial processes requiring advanced high temperature materials.
- Mexico: Mexico's market growth is fueled by expanding automotive and industrial sectors, alongside increasing foreign direct investment in manufacturing facilities that utilize high temperature alloys.
- Rest of North America: Other regions in North America, including parts of Central America and the Caribbean, are witnessing emerging demand driven by industrialization and infrastructural development initiatives.
Competitive Intelligence
The North America High Temperature Alloys Market exhibits a moderate to high level of competition, characterized by the presence of key players such as Carbide, Haynes International, and ATI Specialty Alloys & Components, which collectively hold a significant market share. Market concentration remains relatively high, with the top five companies controlling an estimated 65-70% of the market, driven by their extensive R&D capabilities and technological expertise. Companies are adopting aggressive business strategies, including strategic partnerships, joint ventures, and collaborations to expand their technological footprint and market reach. Product innovation is prioritized, focusing on developing new alloys with enhanced corrosion resistance, strength at elevated temperatures, and reduced manufacturing costs. Major players are actively engaging in acquisitions to diversify their portfolios and expand geographically. Significant investments are directed toward R&D to foster high-performance alloy development, which serves as a key differentiator in the competitive landscape. Differentiation also stems from customized solutions tailored to specific industrial needs, maintaining a competitive edge in a rapidly evolving market environment.
Leading Company Profiles
The North America High Temperature Alloys market features a competitive landscape predominantly composed of well-established players who focus on advanced alloy development, technology innovation, and strategic collaborations to strengthen their market positions and expand their product portfolios.
- Special Metals Corporation
- ATI Alloys
- MSA Stainless Steel
- Niagara Metals
- Haynes International
- VSMPO-AVISMA Corporation
- Thyssenkrupp Materials North America
- Crucible Industries
- Albichem S.p.A.
- Precision Castparts Corp.
Special Metals Corporation
Special Metals Corporation specializes in the manufacturing of nickel alloys including Inconel and other superalloys critical for aerospace, chemical processing, and power generation, leveraging cutting-edge production techniques to sustain its competitive edge in high temperature alloys.
ATI Alloys
ATI Alloys develops high-performance alloys with a focus on aerospace and industrial applications, emphasizing innovative alloy compositions and manufacturing processes that enhance service temperatures and corrosion resistance for demanding environments.
MSA Stainless Steel
MSA Stainless Steel offers a broad array of stainless and specialty alloys designed for high-temperature applications, supporting industries such as aerospace, energy, and automotive through advanced metallurgical R&D and comprehensive supply chain management.
Niagara Metals
Specializing in superalloy powders and blanks, Niagara Metals supplies critical materials for aerospace engines and turbines, utilizing high-precision manufacturing and metallurgical techniques to meet stringent aerospace standards.
Haynes International
Haynes International is renowned for its corrosion-resistant and high-temperature alloys, serving aerospace, chemical, and electronics sectors, with a strategic emphasis on developing next-generation superalloys for extreme environments.
VSMPO-AVISMA Corporation
VSMPO-AVISMA specializes primarily in titanium alloys but also produces high-temperature alloys tailored for aerospace and defense applications, integrating vertical production capabilities to ensure supply chain stability and innovation.
Thyssenkrupp Materials North America
Part of the global Thyssenkrupp group, this division offers a portfolio of high-performance alloys, including superalloys, focusing on customized solutions for aerospace, energy, and industrial markets with sustainable manufacturing practices.
Crucible Industries
Crucible Industries manufactures superalloys, high-speed steels, and specialty alloys, emphasizing innovation in alloy development and superior quality control to serve critical aerospace and industrial segments.
Albichem S.p.A.
Albichem S.p.A. produces specialty high-temperature alloys with a focus on aerospace and medical sectors, demonstrating strong R&D capabilities and strategic alliances that enable customized alloy solutions.
Precision Castparts Corp.
Precision Castparts offers a comprehensive range of high-temperature alloys for aerospace and industrial markets, with strong expertise in casting, forging, and machining, supported by extensive global manufacturing facilities.
Strategic Business Developments

- June 2026 – Special Metals Corporation – Launch of new nickel-based superalloy for aerospace engines – Enhances product portfolio and supports growing aerospace sector demand.
- April 2026 – ATI Alloys – Expansion of production capacity for superalloy ingots – Boosts supply chain resilience and addresses rising industrial and aerospace needs.
- August 2026 – Haynes International – Investment in R&D for next-generation high-temperature alloys – Focuses on developing materials capable of withstanding higher operational temperatures for aerospace and energy applications.
- May 2026 – Crucible Industries – Acquisition of specialty alloy manufacturing plant – Strengthens manufacturing footprint and broadens product offerings for critical industrial uses.
- July 2026 – VSMPO-AVISMA Corporation – Strategic partnership with aerospace OEMs for titanium and superalloy supply – Ensures long-term supply security and technological innovation alignment.
Frequently Asked Questions
What is the North America High Temperature Alloys Market?
The North America High Temperature Alloys Market encompasses the manufacturing and distribution of alloys designed to perform efficiently at elevated temperatures, primarily used in aerospace, power generation, and industrial applications to ensure durability and performance under extreme conditions.
What is the current market size of North America High Temperature Alloys Market?
As of 2026, the market size is valued at approximately USD 3.2 Billion, reflecting a significant share within the global high temperature alloys industry, driven by expanding applications in aerospace and energy sectors across North America.
What factors are driving the North America High Temperature Alloys Market?
Market growth is propelled by the increasing demand for high-performance materials in aerospace, the expanding renewable energy sector, technological advancements in alloy compositions, and stringent safety and efficiency standards in industrial operations that require durable high-temperature materials.
Which region dominates the North America High Temperature Alloys Market?
The United States leads the North American market, owing to its extensive aerospace industry, advanced manufacturing capabilities, and robust investment in research and development for high-performance alloys, contributing to the majority market share in the region.
Which segment is expected to grow the fastest?
Nickel-based alloys are projected to experience the fastest growth, owing to their superior oxidation resistance and mechanical properties at high temperatures, making them highly preferred in aerospace and power generation applications.
Who are the leading companies operating in the North America High Temperature Alloys Market?
Key players include Special Metals Corporation, ATI Alloys, and Carpenter Technology Corporation, which dominate the market through innovation, extensive distribution networks, and strategic collaborations to expand their product portfolios and market reach.
Analyst Perspective
The North America High Temperature Alloys Market exhibits a mature yet evolving landscape, with steady long-term growth driven by ongoing aerospace, industrial, and energy sector demands. The region’s mature infrastructure and technological capabilities position it as a strategic hub for innovations in alloy compositions and manufacturing efficiencies. Future opportunities lie in the development of advanced, cost-effective alloys that offer superior performance under extreme conditions, catering to high-end aerospace engines and next-generation power plants. Technological evolution is expected to focus on additive manufacturing and alloy microstructure optimization, enabling custom solutions and shorter development cycles. Investors should prioritize companies focused on R&D, especially those exploring lightweight, corrosion-resistant alloys tailored for emerging industries. Competitive intensity remains high, yet regional players with strong R&D pipelines and strategic collaborations are poised to lead. Regional growth potential is strongest in sectors such as aerospace, where stringent performance standards and evolving environmental regulations will continue to fuel demand. Overall, companies that innovate around sustainability, performance, and cost will secure long-term strategic advantages in North America.
