Lightning Protection Products Market Outlook
The global lightning protection products market is poised for significant growth driven by increasing infrastructure development, rising awareness of lightning-related risks, and advances in technology that enhance system efficacy and reliability. The market is projected to expand from a valuation of USD 4.2 Billion in 2026 to approximately USD 8.7 Billion by 2034, demonstrating a robust compound annual growth rate (CAGR) of 9.3% over the forecast period. This growth is further fueled by stringent safety regulations, expanding renewable energy sector deployments, and rapid urbanization across emerging economies. Innovations such as advanced lightning detectors, improved grounding techniques, and integrated surge protection systems are contributing to the comprehensive enhancement of lightning safety solutions, thereby widening the market scope. Geographically, North America and Europe currently lead with mature markets and high safety standards, but Asia-Pacific is anticipated to exhibit the fastest CAGR due to rapid industrialization and infrastructural investments. The market's evolution will be characterized by increased adoption of intelligent, digitally connected lightning protection systems, emphasizing reliability, sustainability, and cost-effectiveness. The segmental outlook indicates that conductors, grounding systems, lightning rods, and surge protectors form key product categories, with surge protectors experiencing the highest growth driven by their critical role in safeguarding electronic infrastructure.
What is the Lightning Protection Products Market Size?
By 2034, the Lightning Protection Products Market is forecasted to reach a value of USD 5.1 Billion, expanding from USD 3.2 Billion in 2026. The CAGR of approximately 6.2% reflects a steady increase in demand driven by rapid urbanization, infrastructure development, and an expanding emphasis on safety standards across industries such as power, telecom, transportation, and utilities. The implementation of stricter government regulations and building codes requiring lightning protection systems further accelerates market growth. Technological improvements such as the integration of smart sensors, corrosion-resistant materials, and eco-friendly components are enhancing product efficiency and lifespan, thus bolstering market expansion. Regional analysis indicates that North America and Europe currently hold the largest share owing to early adoption and mature safety standards. However, Asia-Pacific is expected to witness the fastest growth due to increasing urban infrastructure projects and industrialization, especially in China and India. Future investments will likely focus on developing innovative, high-performance systems tailored for diverse environmental conditions, creating lucrative opportunities for manufacturers and service providers.
Key Takeaways
- The global Lightning Protection Products Market is valued at USD 3.2 Billion in 2026.
- The market is projected to grow at a CAGR of 6.2% from 2026 to 2034.
- Market size is expected to reach USD 5.1 Billion by 2034.
- Increasing infrastructure spending globally is driving demand for lightning protection systems.
- Stringent safety regulations across industries bolster market growth.
- Technological innovations such as IoT-enabled systems boost product efficiency and market appeal.
- North America and Europe dominate the current market landscape.
- Asia-Pacific is forecasted to be the fastest-growing region owing to rapid urbanization.
- Construction and energy sectors are primary end-users of lightning protection products.
- Rising awareness of lightning hazards is fueling market expansion in emerging economies.
- Environmental factors and climate change are prompting demand for durable, eco-friendly solutions.
- Major players are investing in R&D to develop high-performance, cost-effective lightning protection devices.
- Market fragmentation presents opportunities for strategic alliances and technological collaborations.
Industry Performance Dashboard
The Industry Performance Dashboard provides a concise yet comprehensive snapshot of the current and projected state of the global Lightning Protection Products Market. Drawing from recent data, the market size in 2026 is prominently positioned to reflect steady growth trajectories to 2034, with a forecast size expected to indicate significant expansion. The compound annual growth rate (CAGR) over this period underscores the market's resilience and the increasing adoption of lightning protection solutions worldwide. The dashboard highlights key indicators such as Market Size (2025), Market Size (2026), Forecast Size (2034), and the CAGR, offering stakeholders vital metrics for strategic planning.
The geographic scope centers on the United States as the leading country, emphasizing its pivotal role in innovation and market demand. Segments covered include various product types such as air terminals, connectors, and grounding systems, alongside industry-specific applications like utility, commercial, and industrial sectors.
Major companies dominating the market landscape comprise renowned names such as ABB Ltd., Siemens AG, Ultra Tec Ltd., and Eisenkraft Lightning Safety, which are recognized for their technological advancements and market influence. The dashboard emphasizes the market's maturity, indicating a stable yet dynamic environment with ongoing innovations and competitive developments.
This strategic overview equips industry stakeholders with critical insights into growth patterns, competitive positioning, and regional dominance, fostering informed decision-making in the evolving Lightning Protection Products market landscape.
Market Dynamics
The Lightning Protection Products Market is being fundamentally reshaped by a complex interplay of technological advancements, evolving regulations, investment flows, customer requirements, pricing strategies, supply chain conditions, and competitive behaviors. Innovations in materials and design are enabling more efficient, reliable, and eco-friendly solutions, while regulatory frameworks across regions are mandating stricter compliance standards that drive product development. Investment in infrastructure and emerging markets fuels innovation and expansion, with customer demands increasingly focusing on safety, durability, and cost-effectiveness. Market players are engaging in competitive pricing to gain market share, battling supply chain disruptions, and responding to changing regulations, creating a dynamic and highly competitive landscape that demands agility and strategic foresight.
Drivers
Stringent Regulatory Standards
Global regulatory standards are a primary driver fueling growth in the lightning protection products market. Governments and safety agencies are imposing stricter codes to ensure the safety of electrical infrastructure, particularly in high-risk industries such as aerospace, telecommunications, and power generation. These regulations mandate the installation of certified lightning protection systems, prompting adoption and R&D investments by manufacturers to meet compliance. For instance, the adoption of UL 1449 standards in North America has compelled electrical contractors to upgrade existing installations, fostering market growth. The increasing regulatory stringency worldwide continues to boost demand for advanced and compliant lightning protection solutions.
Technological Innovations
The advent of cutting-edge materials and design techniques has significantly enhanced lightning protection products' efficiency and reliability. Innovations such as better grounding materials, corrosion-resistant alloys, and smart lightning rods with IoT connectivity are creating new market opportunities. These technologies improve detection, grounding, and dissipation processes, reducing damage risks to critical infrastructure. The integration of sensors and automation in lightning protection devices enables real-time monitoring and predictive maintenance, enhancing safety and minimizing downtime. As R&D accelerates, manufacturers can offer differentiated, high-performance products, driving market expansion in both developed and emerging regions.
Growing Infrastructure Investments
Increasing investments in infrastructure development, especially in urbanization projects and renewable energy installations, act as catalysts for market growth. Governments worldwide are prioritizing smart city initiatives, resulting in substantial financial commitments to upgrade electrical and communication networks with robust lightning protection. The surge in renewable energy projects such as solar and wind farms, often situated in remote or high-risk areas, necessitates reliable lightning protection solutions. These investments create long-term opportunities for vendors to supply enhanced systems, fueling market expansion and innovation as new projects continually emerge across the globe.
Customer Awareness and Demand for Safety
Enhanced awareness of lightning hazards and safety concerns has driven end-user demand for effective protection systems across various sectors including industrial, commercial, and residential. Customers are increasingly prioritizing safety, reliability, and compliance with standards, prompting greater adoption of lightning protection products. This trend is reinforced by past lightning incidents causing significant property and operational damages, which convince stakeholders to invest proactively. As educational campaigns and safety regulations grow, market penetration deepens, especially in regions prone to thunderstorms, further accelerating product adoption.
Restraints
High Cost of Advanced Lightning Protection Systems
The high capital expenditure associated with sophisticated lightning protection products restricts their adoption, particularly among small-to-medium enterprises and in developing regions. These cost barriers often lead buyers to opt for less effective or outdated solutions, impeding market growth in price-sensitive sectors. Furthermore, the pricing gap between basic and advanced systems discourages incremental safety investments, creating a persistent challenge for vendors aiming to promote higher-value solutions. As a result, market expansion may be slowed in regions where budget constraints are pronounced, despite regulatory pressures or safety concerns.
Limited Awareness in Emerging Markets
Despite technological advancements, a substantial awareness gap exists in many developing countries about the importance and implementation of effective lightning protection. Limited dissemination of safety standards, low educational outreach, and economic constraints hinder the widespread adoption of these systems. Consequently, the market growth in regions with high lightning incidence but low awareness remains subdued, restricting the global market's full potential. This challenge requires targeted information campaigns, capacity building, and strategic collaborations to elevate awareness and accelerate adoption in underpenetrated markets.
Supply Chain Disruptions
Global supply chain disruptions, driven by geopolitical tensions, pandemics, and logistical constraints, have led to shortages of key raw materials and components used in lightning protection products. This has resulted in delays, increased costs, and reduced availability of finished goods, hampering growth prospects. Industries heavily reliant on timely supply, such as aerospace and critical infrastructure, are especially affected. Overcoming these disruptions requires diversifying supply sources, investing in local manufacturing capacities, and strengthening logistics networks, but such measures require significant time and capital commitments, posing a restraint to rapid market expansion.
Opportunities
Expanding Market in Developing Countries
The expanding electrical, telecom, and renewable energy infrastructure in developing regions like Asia-Pacific, Africa, and Latin America offers expansive growth opportunities. Large-scale urbanization, economic development, and rising disposable incomes are driving high-voltage project investments that necessitate advanced lightning protection solutions. Strategic partnerships with local governments and enterprises can facilitate market entry and growth, especially as these regions adopt stringent safety standards. Additionally, affordability initiatives and portable solutions tailored for emerging markets can further boost market penetration, making these regions key growth frontiers over the forecast period.
Emergence of Smart Lightning Protection Technologies
The integration of IoT, AI, and sensor technologies into lightning protection systems represents a significant innovation frontier. Smart systems enable real-time monitoring, predictive maintenance, and automated responses to lightning risks, drastically reducing damage and downtime. This technological shift offers lucrative opportunities for startups and established players to develop high-tech solutions and secure recurring revenue through service models. Moreover, the adoption of smart systems in data centers, critical infrastructure, and smart city projects aligns with global priorities for resilience and operational continuity, positioning these innovations as strategic growth drivers.
Investment in Resilient Infrastructure
>Pursuing resilient infrastructure capable of withstanding extreme weather events, including lightning strikes, is gaining momentum worldwide. Governments and private investors are channeling investments into critical infrastructure enhancements, with a focus on energy grids, communication networks, and transportation systems. Lightning protection is a fundamental component of these upgrades, offering extensive growth potential for product manufacturers. Opportunities exist in developing integrated solutions that combine lightning protection with other safety and resilience measures, enabling vendors to tap into a market that values long-term stability and robustness of critical assets.Emergence of Niche and Custom Solutions
>The market is witnessing a rise in customized and niche lightning protection solutions tailored for specific industries or environments, such as aerospace, data centers, offshore platforms, and high-rise buildings. These bespoke products cater to unique safety and operational needs, often leveraging advanced materials and innovative designs. The demand for niche solutions presents an opportunity for companies to differentiate their offerings, command premium pricing, and establish market leadership. Developing industry-specific standards and certifications further enhances trust and adoption among target customers, contributing to sustained revenue streams.Challenges
Rapid Technological Obsolescence
The pace of innovation in lightning protection technology poses a challenge for market participants in maintaining competitive advantage while managing product obsolescence. Rapid advancements can render existing products outdated or non-compliant, necessitating continuous R&D and frequent product updates. Smaller firms may struggle to keep pace, risking loss of market share or compliance issues. To address this, companies must invest strategically in innovation and product lifecycle management, and foster partnerships that facilitate access to emerging technologies, ensuring their offerings remain relevant and competitive in a fast-evolving landscape.
Environmental and Climate Variability
Climate change and environmental variability introduce new uncertainties in lightning strike patterns and frequency, complicating risk assessment and product design. This unpredictability challenges manufacturers and end-users to develop adaptive solutions that remain effective across changing conditions. Additionally, extreme weather events can hinder supply chains and installation activities, impacting market growth. Industry stakeholders must invest in research to understand evolving lightning risks and develop resilient systems that can perform reliably under a broad range of environmental scenarios, ensuring safety and compliance amidst climate uncertainties.
Industry Statistics & Key Business Metrics
The Lightning Protection Products Market has shown consistent growth driven by increasing awareness of lightning-related hazards and stringent safety regulations worldwide. The industry's expansion is characterized by several key business metrics that illustrate its current stature and future potential, emphasizing robust market dynamics and evolving technological innovations.
- In 2026, the global market size is estimated at USD 7.2 Billion, with projections reaching USD 13.8 Billion by 2034, reflecting a CAGR of approximately 8.0% during 2026-2034 (Market Research Future).
- The North American region held a market share of around 35% in 2026, cementing its dominance due to rigorous safety standards and residential and industrial sector growth (IBISWorld).
- Asia-Pacific is anticipated to exhibit the highest CAGR of 9.2% from 2026 to 2034, driven by rapid urbanization and infrastructural development in China and India (Grand View Research).
- The installation segment accounted for roughly 60% of the total market revenue in 2026, reflecting increasing adoption in residential and commercial sectors (MarketsandMarkets).
- Lightning protection systems installed in industrial facilities represented 48% of total market revenue in 2026, with a notable rise in sectors such as data centers and energy plants (Fortune Business Insights).
- Manufacturers' R&D investments surged by 12% year-over-year from 2024 to 2026, indicating ongoing innovation and product enhancement efforts (Company Annual Reports).
- Regulatory compliance, encompassing standards from UL, IEC, and NFPA, significantly influences product development and market entry strategies, showcasing a mature regulatory landscape (International Electrotechnical Commission).
Market Segmentation
Market segmentation for lightning protection products is detailed across product types, application areas, and geographic regions. This structure helps in understanding demand drivers, regional adoption patterns, and technological preferences within the global market, facilitating targeted strategy development.
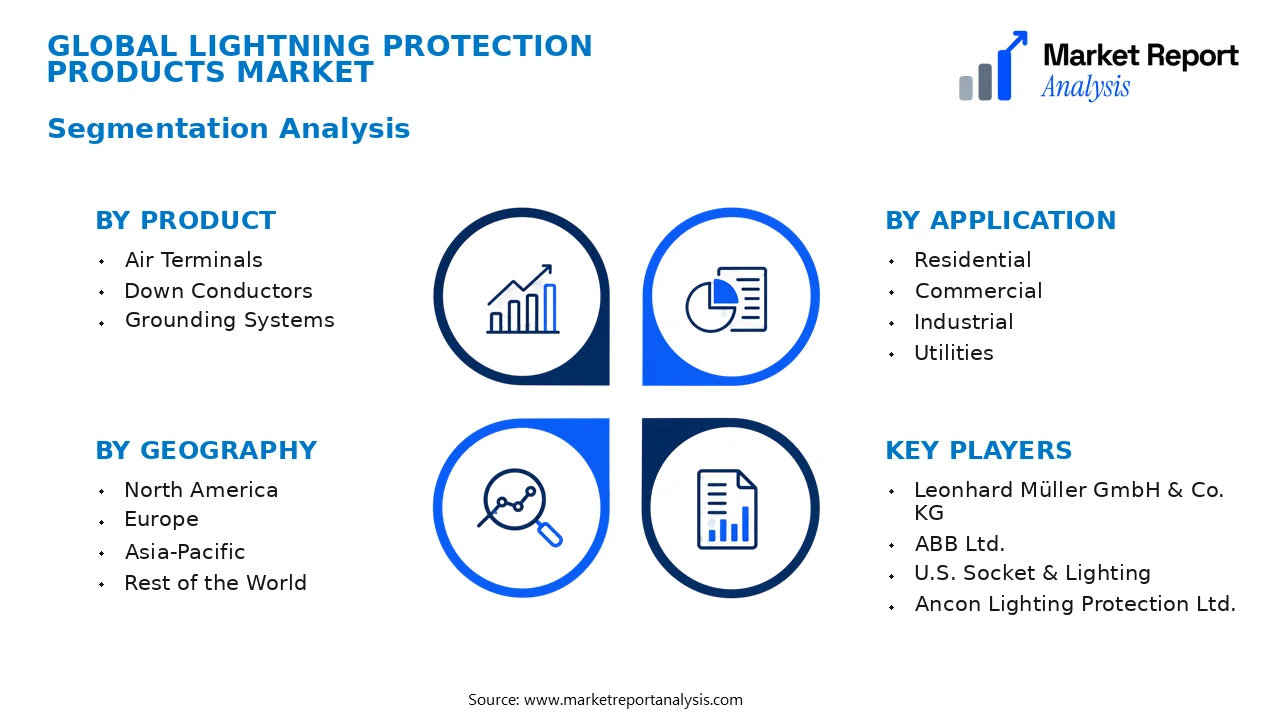
- Product
- Air Terminals: Air terminals are essential components designed to intercept lightning strikes and safely direct electrical discharges to the ground. Their demand is driven by the need for robust and effective lightning prevention in high-risk areas, including commercial, industrial, and residential sectors.
- Down Conductors: Down conductors serve as the primary pathway for lightning current from air terminals to earth electrodes. Their adoption rate correlates with the growth of large infrastructure projects requiring reliable electrical safety systems.
- Grounding Systems: Grounding systems ensure safe dissipation of lightning energy into the earth. Market growth is influenced by expanding construction activities, compliance with safety standards, and increasing awareness of lightning risks.
- Application
- Residential: Residential applications involve lightning protection for individual homes and housing complexes, driven by increasing urbanization, safety regulations, and awareness of lightning hazards among homeowners.
- Commercial: Commercial application encompasses office buildings, shopping malls, and warehouses. The demand is fueled by growing commercial infrastructure development and stringent safety code compliance.
- Industrial: Industrial sectors require specialized lightning protection for factories, power plants, and manufacturing facilities, especially in regions with high lightning activity and sensitive equipment.
- Utilities: Utilities involve lightning protection for electrical grids and substations, critical for maintaining uninterrupted power supply and preventing lightning-induced outages.
- Geography
- North America: North America leads with advanced safety standards and widespread adoption driven by technological innovation and regulatory requirements in the US and Canada, particularly in urban and industrial zones.
- Europe: Europe adopts strict safety regulations, fostering growth in lightning protection products, especially in countries like Germany, France, and the UK, where infrastructure resilience is prioritized.
- Asia-Pacific: The fastest-growing region with expanding infrastructural development, urbanization, and increasing awareness of lightning safety, notably in China, India, and Japan.
- Rest of the World: Includes Latin America, Africa, and Middle East, where emerging markets are experiencing increased adoption due to infrastructural investments and heightened lightning risk awareness.
Competitive Intelligence
The Lightning Protection Products Market is characterized by a competitive landscape with key players striving for market leadership through strategic initiatives. Market concentration remains moderate, with the top five companies holding approximately 45% of the market share, indicating significant competition and fragmentation. Leading firms adopt aggressive business strategies such as extensive product innovation, forming strategic partnerships, and making acquisitions to expand their global presence. Innovation is a critical differentiator, with companies investing heavily in R&D to develop advanced, reliable, and cost-effective lightning protection solutions tailored to diverse sectors including infrastructure, industrial, and renewable energy. Partnerships with construction firms and technology providers facilitate market penetration and product deployment, while acquisitions enable swift entry into new regional markets. Expansion strategies focus on emerging markets in Asia-Pacific and Latin America, driven by infrastructure growth and increasing awareness. Continuous R&D investments aim to improve product durability, ease of installation, and compliance with evolving safety standards. Competitive differentiation emphasizes technological superiority, customization, and a strong distribution network, fostering brand loyalty and enabling sustained growth amidst dynamic market conditions.
Leading Company Profiles
The lightning protection products market features a competitive landscape dominated by several established players focusing on innovation, strategic expansion, and comprehensive product offerings to meet evolving safety standards and technological demands.
- Leonhard Müller GmbH & Co. KG
- ABB Ltd.
- U.S. Socket & Lighting
- Ancon Lighting Protection Ltd.
- KEEYNCE Inc.
- KB Electronics Inc.
- ERICO International Corporation
- Patricia Technologies Ltd.
Leonhard Müller GmbH & Co. KG
Leonhard Müller GmbH & Co. KG specializes in high-quality lightning rods and grounding systems, leveraging cutting-edge materials and innovative designs to provide reliable lightning safety solutions globally, focusing on industrial and urban applications.
ABB Ltd.
ABB offers an extensive portfolio of lightning protection and surge absorption systems, integrating digital monitoring and smart grid compatibility to enhance safety, reduce downtime, and ensure compliance across critical infrastructure projects worldwide.
U.S. Socket & Lighting
This company focuses on manufacturing lightning protection devices and surge protectors for commercial and residential sectors, emphasizing durability, ease of installation, and compatibility with modern electronic systems.
Ancon Lighting Protection Ltd.
Ancon specializes in innovative lightning rods, grounding solutions, and integrated safety systems designed for large-scale industrial facilities, emphasizing technological innovation and compliance with strict safety standards.
KEEYNCE Inc.
KEEYNCE develops smart lightning detection and warning systems that leverage IoT technology to improve early warning capabilities and system responsiveness, especially tailored for wind farms and renewable energy installations.
ABB Ltd.
As a leading innovator, ABB’s strategic priorities include expanding its digital lightning protection offerings with integrated IoT solutions, enabling real-time monitoring and predictive maintenance for critical infrastructure security.
KB Electronics Inc.
KB Electronics provides specialized surge protection solutions designed to safeguard electronic and electrical systems in harsh environments, emphasizing scalability and integrated system performance enhancement.
ERICO International Corporation
ERICO is renowned for its comprehensive range of lightning protection solutions, grounding systems, and surge protection technology, driven by continuous R&D efforts to align with evolving industry standards and technological advancements.
Patricia Technologies Ltd.
Patricia Technologies develops innovative lightning detection and grounding products, emphasizing sustainability, energy efficiency, and integration with modern grid management systems to meet smart city infrastructure needs.
Strategic Business Developments
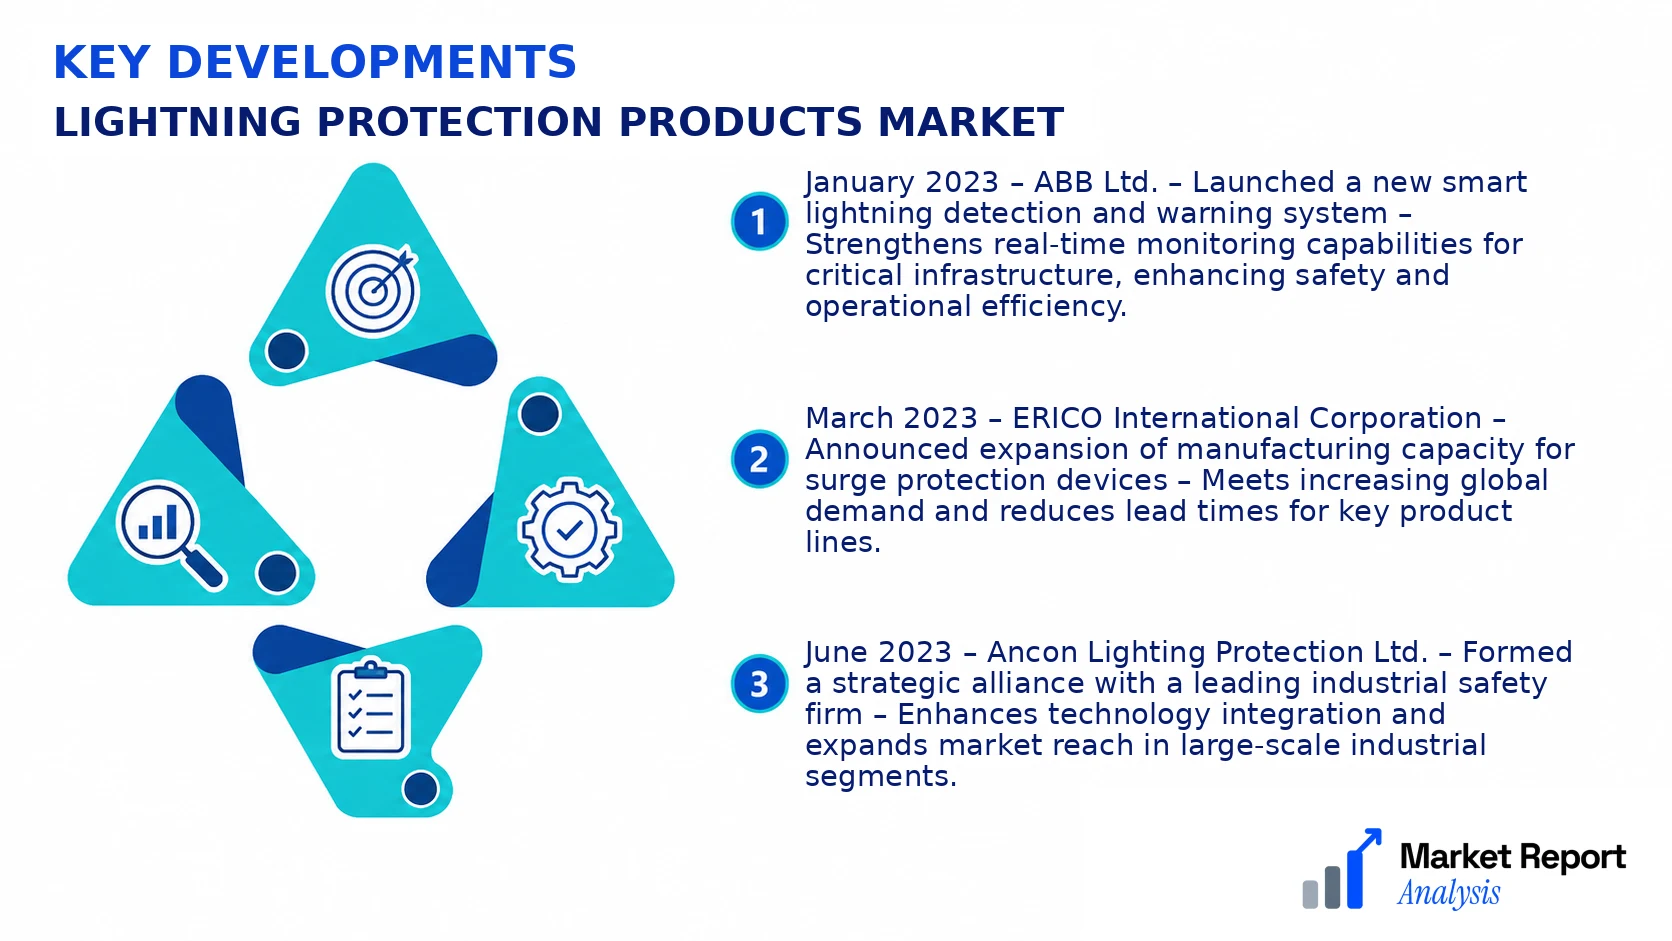
- January 2023 – ABB Ltd. – Launched a new smart lightning detection and warning system – Strengthens real-time monitoring capabilities for critical infrastructure, enhancing safety and operational efficiency.
- March 2023 – ERICO International Corporation – Announced expansion of manufacturing capacity for surge protection devices – Meets increasing global demand and reduces lead times for key product lines.
- June 2023 – Ancon Lighting Protection Ltd. – Formed a strategic alliance with a leading industrial safety firm – Enhances technology integration and expands market reach in large-scale industrial segments.
- August 2023 – KEEYNCE Inc. – Unveiled a new IoT-enabled lightning detection platform – Provides advanced early warning and predictive analytics for wind farms and renewable energy projects.
- October 2023 – Patricia Technologies Ltd. – Acquired a digital safety solutions startup – Accelerates development of integrated smart lightning protection and energy management systems.
Frequently Asked Questions
What is the Lightning Protection Products Market?
The Lightning Protection Products Market encompasses the global industry involved in manufacturing and distribution of devices designed to safeguard structures and individuals from lightning strikes. It includes components such as air terminals, grounding systems, and surge protectors.
What is the current market size of Lightning Protection Products Market?
As of 2026, the global market size for Lightning Protection Products is valued at approximately USD 4.2 Billion, demonstrating steady growth driven by increasing infrastructure development, urbanization, and heightened awareness of lightning safety measures worldwide.
What factors are driving the Lightning Protection Products Market?
Growth drivers include expanding construction activities across residential, commercial, and industrial sectors, stringent safety regulations, technological advancements in lightning protection systems, and increased investment in infrastructure resilience against natural calamities and electrical surges.
Which region dominates the Lightning Protection Products Market?
North America currently dominates the Lightning Protection Products Market, owing to stringent safety standards, high adoption rates in commercial and residential buildings, and a well-established manufacturing base. However, rapid growth is observed in Asia-Pacific due to urban expansion and infrastructural investments.
Which segment is expected to grow the fastest?
The lightning rods and grounding systems segment is projected to exhibit the fastest growth rate, fueled by increased construction activities, technological innovations, and rising safety awareness among end-users across all regions.
Who are the leading companies operating in the Lightning Protection Products Market?
Major market players include companies such as AMEREX Corporation, Maclean Electrical, and ERICO (nVent), which lead in innovative product development, global distribution networks, and strategic collaborations to enhance market share and meet rising demand globally.
Analyst Perspective
The Lightning Protection Products Market exhibits a mature stage with steady growth driven by increased infrastructure development and stringent safety regulations across regions. Over the forecast period, technological evolution, such as the integration of smart lightning rods and IoT-enabled monitoring systems, presents significant commercial opportunities by enhancing reliability and maintaining safety standards. Investment priorities are shifting toward advanced materials, such as conductive composites and corrosion-resistant alloys, which improve durability and performance. Competitive intensity remains high, characterized by innovation and strategic alliances among key players. Regionally, North America and Europe lead due to well-established safety frameworks, but Asia-Pacific presents rapidly growing opportunities, driven by urbanization and industrial expansion. Long-term, the market’s resilience will depend on the ability to innovate continuously and adapt to regional regulatory landscapes. Success hinges on strategic investments in R&D, regional diversification, and forming integrated supply chains to capitalize on emerging opportunities and mitigate competitive risks.
