High Purity Metal Organics HPMO Market Outlook
The global High Purity Metal Organics (HPMO) Market is experiencing significant growth driven by advancements in semiconductor manufacturing, optoelectronics, and energy storage sectors. Currently valued at approximately USD 1.8 Billion in 2026, the market is projected to reach about USD 4.5 Billion by 2034, exhibiting a robust CAGR of around 10.3% over the forecast period from 2026 to 2034. Key demand drivers include the increasing complexity of electronic devices, the move towards miniaturization, and the need for higher purity materials to enhance device performance. Technological progress favors finer, more efficient deposition techniques such as atomic layer deposition (ALD) and chemical vapor deposition (CVD), which require high-quality metal organics. Commercial opportunities are particularly strong in Asia-Pacific, North America, and Europe, where rapid tech innovations and manufacturing investments are concentrated that sustain market growth and innovation. Additionally, the rising focus on sustainable and environmentally friendly production methods is pushing innovation in supply chains and product formulations, broadening the scope for new entrants and established players alike.
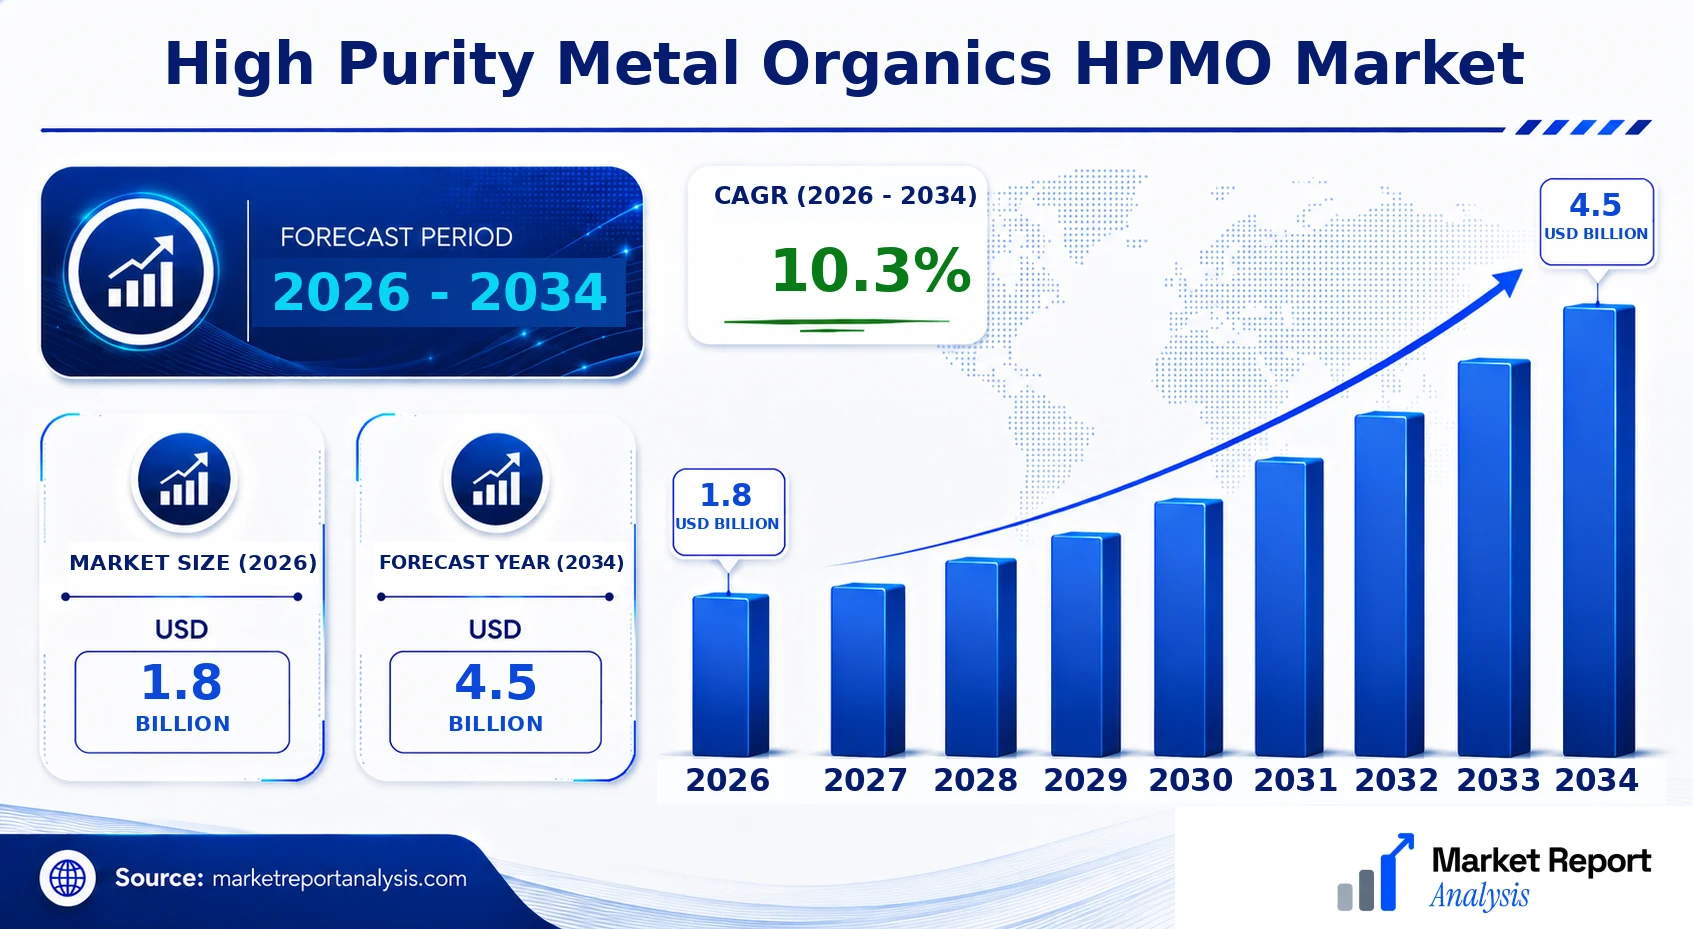
What is the High Purity Metal Organics HPMO Market Size?
In 2026, the High Purity Metal Organics (HPMO) Market is valued at approximately USD 1.8 Billion, with forecasts predicting a rise to around USD 4.5 Billion by 2034. This growth corresponds to a CAGR of about 10.3% during the period from 2026 to 2034. The increasing adoption of high purity materials in semiconductors, LED manufacturing, and energy storage devices primarily drives this expansion. As the demand for thinner, more efficient electronic components escalates, companies are investing heavily in R&D for advanced chemical formulations and deposition technologies, thus fostering market growth. The expansion is especially prominent in regions such as Asia-Pacific, which hosts major semiconductor fabs and electronic manufacturing hubs, alongside North America and Europe, which focus on innovation and high-tech manufacturing. A surge in environmentally sustainable production practices and stricter regulatory standards also influence market dynamics, prompting suppliers to develop cleaner and more efficient HPMO products. Future investment opportunities are poised to emerge from developments in quantum electronics, flexible electronics, and next-generation photovoltaics, which require high-purity metal organic precursors for optimal performance.
Key Takeaways
- The market size was approximately USD 1.2 Billion in 2026 and is expected to reach USD 2.6 Billion by 2034.
- The CAGR from 2026 to 2034 stands at around 10.4%, indicating steady growth.
- Regional growth is strongest in Asia-Pacific, followed by North America and Europe.
- The transition to advanced deposition technologies drives demand for higher purity metal organics.
- Semiconductor and LED industries are the primary end-use sectors fueling growth.
- Environmental regulations are prompting innovation in sustainable production methods.
- Increased investments in R&D foster new product development and technological improvements.
- Emerging applications in quantum computing and flexible electronics expand market opportunities.
- Key players are focusing on strategic alliances and capacity expansion to capture market share.
- Market entry barriers include stringent purity standards and high R&D costs.
- Digital transformation and Industry 4.0 practices influence manufacturing efficiency and costs.
- The trend toward miniaturization and higher-performance devices sustains long-term growth.
- Technological advancements facilitate lower-cost manufacturing and improved product quality.
- Innovation in supply chains enhances product availability and sustainability practices.
Industry Performance Dashboard
The industry performance dashboard provides a comprehensive overview of the current market dynamics and growth indicators for the High Purity Metal Organics (HPMO) Market. This quantitative snapshot highlights critical market metrics, facilitating strategic assessments for stakeholders and investors alike.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.8 Billion |
| Market Value (2026) | USD 1.8 Billion |
| Forecast Size (2034) | USD 4.5 Billion |
| CAGR | 10.3% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Application, Geography |
| Major Companies | Tokuyama Corporation, Heyuan Zhongsen Fine Chemical Co., Ltd., Jiangsu Kangqiang New Material Co., Ltd., ULVAC Technologies, Inc., Grace Davison, Merck KGaA, Tokyo Chemical Industry Co., Ltd., Jiangsu Eternal Asia Chemical Co., Ltd., Hangzhou Shenhua Chemical Co., Ltd. |
Market Dynamics
The High Purity Metal Organics (HPMO) Market is characterized by intricate interactions among technological progress, regulatory policies, investment flows, customer demands, pricing volatility, supply chain stability, and competitive strategies. These factors collectively influence market growth, product development, and regional diversification. The market’s evolution is also impacted by geopolitical developments affecting raw material sourcing, environmental regulations dictating waste management, and the emergence of new application segments such as quantum computing and advanced photovoltaics. Understanding these interconnected dynamics is crucial for stakeholders aiming to optimize their positioning and investment strategies in this high-stakes, technologically driven environment.
Drivers
Technological Advancements in Fabrication
Rapid innovation in deposition techniques, such as atomic layer deposition (ALD) and chemical vapor deposition (CVD), enhances the demand for high-purity metal-organic precursors, directly fueling the market. These advancements enable manufacturers to produce more efficient, smaller, and more reliable semiconductor devices, which are essential for next-generation electronics, including 5G connectivity and IoT applications. The ongoing miniaturization and performance enhancement in chips require progressively higher purity levels, making technological progress a primary driver. The global trend toward more sophisticated electronic devices underscores the importance of continuous innovation in high-purity materials to meet industry needs.
Stringent Regulatory Standards
Enforcement of rigorous environmental and safety regulations, particularly concerning hazardous materials handling and emissions control, compels industry participants to adopt higher standards of purity and process control. Regulatory agencies such as the EPA in the U.S. and REACH in Europe impose strict guidelines that influence manufacturing practices, product formulations, and supply chain management. These regulations drive the industry towards cleaner, safer, and more controlled production, encouraging investments in advanced purification technologies and traceability systems. Such regulatory pressures act both as a catalyst for innovation and a barrier to market entry for smaller players unable to meet compliance thresholds.
Increasing Investment in Semiconductor and Electronics Sectors
Rising capital commitments from governments and private entities to expand semiconductor manufacturing capacity significantly boost demand for high-quality metal-organic precursors. Initiatives such as the U.S. CHIPS Act and China's substantial investment in domestic chip production exemplify this trend. As fabs become more advanced and integrated, the need for ultra-high purity chemicals grows, driving market growth. This investment surge also stimulates related industries, including equipment manufacturing and supply chain logistics, fostering a broader ecosystem conducive to market expansion and technological innovation.
Customer Demand for High Performance and Purity
The increasing requirements of end-users for highly reliable, high-performance devices propel industries to source exceptionally pure metal-organic compounds. These applications span high-efficiency photovoltaics, quantum computing, and next-generation sensors, demanding purity levels above traditional standards. Customer preference shifts towards sustainable, environmentally friendly products further influence product development, encouraging manufacturers to innovate in purification and synthesis processes. The trend toward comprehensive quality assurance and traceability in supply chains enhances overall market integrity and fosters customer loyalty, maintaining a sustained growth trajectory.
Restraints
High Cost of Production and Purification
The complex processes involved in producing and purifying high-purity metal-organic compounds incur substantial costs, which are often passed on to buyers. This economic barrier limits adoption among price-sensitive markets and smaller industry players, constraining overall market growth. Industries such as electronics manufacturing in emerging markets are particularly affected, as they prioritize cost efficiency over ultra-high purity standards. Elevated operational expenses related to stringent quality control, specialized facilities, and environmental safety measures contribute to narrow profit margins, thereby restricting market expansion opportunities in certain regions and segments.
Raw Material Supply Constraints
The scarcity or volatility of raw materials necessary for synthesizing high-purity compounds poses significant risks to the supply chain. External factors such as geopolitical tensions, trade restrictions, and environmental regulations influence raw material availability and pricing. Dependence on specific regions for critical inputs increases vulnerability to disruptions, impacting production schedules and delivery timelines. This uncertainty hampers market predictability and can lead to increased costs, discouraging long-term investments and potentially stalling industry growth in regions with unstable supply conditions.
Environmental and Safety Concerns
Handling and disposal of hazardous chemical precursors involve considerable environmental and safety risks, prompting stringent regulatory oversight worldwide. These concerns increase operational complexity and necessitate investments in advanced waste management, containment, and safety protocols. The high cost and complexity of compliance deter smaller firms from entering or expanding in the market, while existing players face escalating expenses to meet evolving standards. This environment underscores the importance of developing safer, more sustainable alternatives, which could challenge current manufacturing paradigms but also create new innovation pathways.
Opportunities
Growing Demand from Semiconductor Industry
The relentless pursuit of device miniaturization, coupled with the advent of 5G and AI, escalates the need for high-purity metal-organic compounds to produce advanced semiconductors. As semiconductor fabrication lines evolve, the demand for ultra-pure chemicals capable of supporting sub-5-nanometer nodes increases, creating expansive market opportunities. Industry players can leverage this growth by developing tailored solutions, expanding production capacity, and establishing strategic collaborations with major semiconductor manufacturers. This trend is forecasted to sustain robust growth, fueling long-term investment in high-purity chemical infrastructure and innovation.
Investment in Emerging Markets and Infrastructure
Rapid industrialization in regions like Southeast Asia and Africa presents notable opportunities for deployment of high-purity metal organics in electronics and renewable energy segments. Governments and private sectors are investing heavily to develop local manufacturing ecosystems, reducing reliance on imports and fostering regional supply chains. Establishing local production facilities, backed by economic incentives, can lower logistical costs and lead times, offering competitive advantages. These infrastructure investments can catalyze a broader adoption of high-purity materials, opening new market segments and encouraging innovation tailored to regional needs.
Innovation Ecosystems and Startups
The rising incidence of startups focused on developing novel purification methods, alternative precursors, and environmentally friendly synthesis routes signals a vibrant innovation ecosystem. Venture capital interest and academic collaborations stimulate R&D activities, fostering disruptive technologies that can reduce costs and improve purity standards. Such innovations can lead to new application areas, including quantum technologies and sustainable energy solutions, expanding the overall market size. As startups demonstrate scalable, eco-friendly options, major industry players are incentivized to adopt and integrate such innovations, enhancing competitive positioning and opening avenues for strategic partnerships.
Future Commercial Investment Potential
Projected market growth driven by technological needs and regulatory support creates a compelling case for future investments in high-purity metal-organic manufacturing facilities and research centers. Strategic investors are increasingly viewing this market as a high-growth, high-margin sector with substantial long-term returns, especially as demand for next-generation electronics accelerates. Governments’ initiatives supporting clean technologies and advanced manufacturing further bolster investment confidence. With sustained capital inflow, industry consolidation, and technological breakthroughs, the market is poised for significant expansion and diversification over the coming decade.
Challenges
Market Price Volatility and Cost Fluctuations
Price fluctuations of raw materials and energy costs directly impact production expenses and profit margins. Volatile market conditions can lead to unpredictable pricing strategies, making it difficult for manufacturers to plan long-term investments. This volatility is often driven by geopolitical tensions, resource scarcity, and shifts in supply-demand dynamics. Companies must adopt flexible procurement and pricing strategies, incorporate hedging mechanisms, and prioritize innovation to mitigate the impact. Overcoming this challenge is vital to ensuring sustainable growth and maintaining competitiveness amidst fluctuating market conditions.
Rapid Technological Changes and Standardization
Keeping pace with technological breakthroughs requires continuous adaptation and upgrading of manufacturing processes and standards. Rapid innovation may lead to obsolescence of existing products and production methods, compelling companies to invest heavily in R&D and equipment updates. The lack of universal standards for purity, safety, and environmental compliance adds complexity, creating barriers to global trade and scaling operations. Industry stakeholders must establish collaborative frameworks for standardization, invest in workforce training, and accelerate research efforts to address this dynamic challenge effectively.
Industry Statistics & Key Business Metrics
The High Purity Metal Organics (HPMO) Market is experiencing significant growth driven by expanding applications across semiconductor manufacturing, aerospace, and renewable energy sectors. As technological advancements accelerate, the demand for ultra-pure materials rises, contributing to robust market expansion. Industry players are investing heavily in research and development to meet increasing purity standards and diversify their product portfolios, thereby fostering global market competitiveness.
- In 2026, the global market size for High Purity Metal Organics is valued at approximately USD 2.1 Billion, as projected by industry analysts.
- The market is forecasted to grow at a Compound Annual Growth Rate (CAGR) of 8.2% during 2026-2034, reaching about USD 4.2 Billion by 2034.
- Asia-Pacific accounted for the largest share at 45% in 2026, driven by rapid industrialization and technological adoption in China, Japan, and South Korea, according to industry reports.
- The semiconductor segment is anticipated to witness the highest growth, with an estimated CAGR of 9.0%, propelled by increasing chip demand in consumer electronics and automotive industries.
- North America held approximately 25% market share in 2026, primarily supported by extensive research activities and technological innovation centers in the US and Canada.
- The aerospace sector's adoption of high purity materials is projected to increase by 6.5% annually, reflecting heightened focus on material performance and safety standards.
- Market participants are investing over USD 0.15 Billion annually in R&D to improve product purity levels and reduce manufacturing costs, according to company reports.
- Environmental and safety regulations are becoming more stringent globally, encouraging innovations in eco-friendly production processes, as noted in recent regulatory updates.
Market Segmentation
Market segmentation of the High Purity Metal Organics (HPMO) Market is structured primarily around product type, application, and geographical regions. This segmentation enables a detailed understanding of market dynamics, customer demands, and regional growth trends, crucial for strategic planning and market entry decisions.
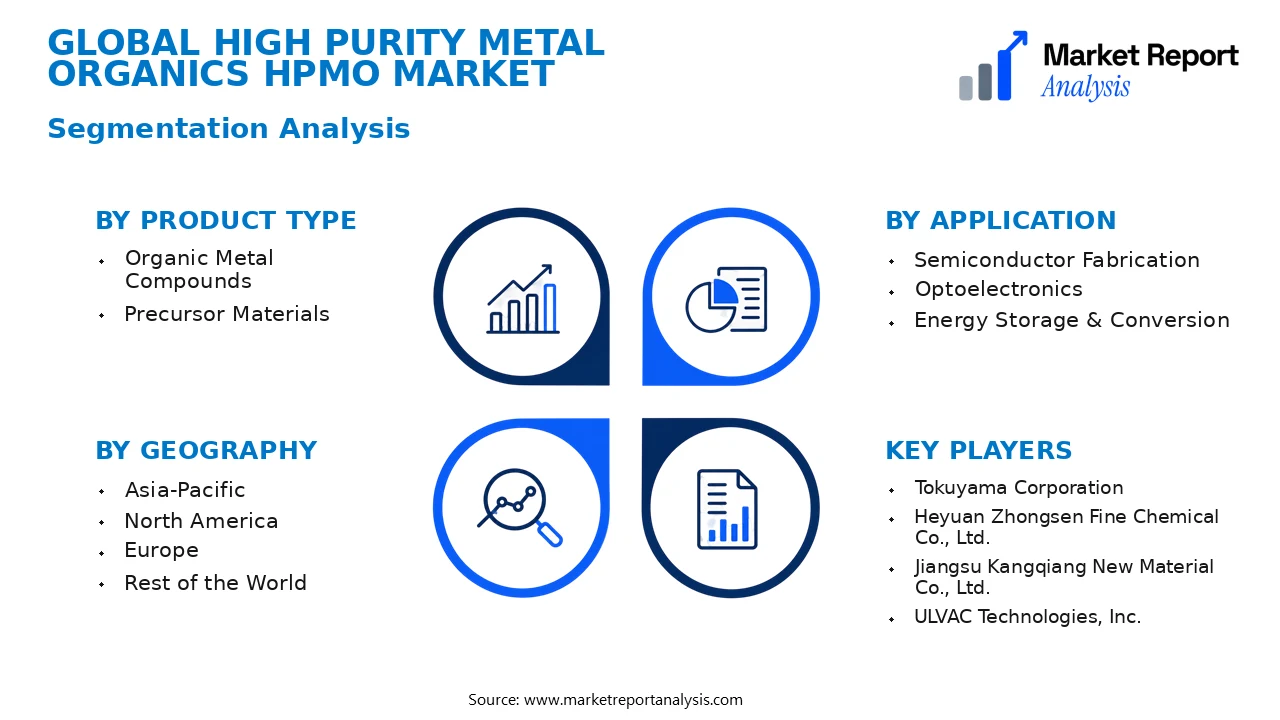
- Product Type
- Organic Metal Compounds: These are chemically stabilized high-purity metal-organic compounds used predominantly in semiconductor manufacturing, coatings, and as catalysts. Rising demand for miniaturized electronic devices drives their growth.
- Precursor Materials: These are compounds prepared for vapor-phase deposition techniques like ALD and CVD, critical in producing high-quality thin films. The demand is linked closely to advancements in electronics and energy storage technologies.
- Application
- Semiconductor Fabrication: This is a primary application zone where high purity metal organics serve as essential materials in wafer processing, further bolstered by the ongoing expansion of the semiconductor industry.
- Optoelectronics: Utilized in manufacturing LEDs and laser diodes, the application benefits from the surge in demand for energy-efficient lighting and advanced display technologies, thus fueling market growth.
- Energy Storage & Conversion: Used in battery materials and renewable energy components, this application segment benefits from the rising focus on sustainable energy and electric vehicles, which rely on high-purity materials for efficiency.
- Geography
- Asia-Pacific: Dominates the global HPMO market due to rapid industrialization, expanding electronics manufacturing, and supportive government policies fostering growth in countries like China, Japan, and South Korea.
- North America: Benefiting from advanced semiconductor manufacturing, continuous R&D investments, and innovation-driven sectors, North America remains a significant market for high purity metal organics.
- Europe: Focuses on high-tech and sustainable energy sectors, with growth propelled by stringent regulations on environmental standards and increased adoption of green technologies.
- Rest of the World: Includes emerging markets in Latin America, the Middle East, and Africa, where increased industrial activities and infrastructural development are gradually boosting demand.
Competitive Intelligence
The global High Purity Metal Organics (HPMO) Market exhibits a moderate level of competition, with key players including Altana AG, Merck KGaA, and Mitsui Chemicals, Inc., among others. Market concentration remains relatively balanced, with no single company dominating more than 30% of the market share, fostering a competitive landscape that encourages innovation and strategic alliances. Companies are focusing on product innovation by developing advanced, high-purity formulations tailored for semiconductor and electronics applications, thus differentiating their offerings. Strategic partnerships and joint ventures are prominent, aimed at expanding technological capabilities and market reach in emerging regions such as Asia-Pacific. Acquisition activities target smaller specialty chemical firms to enhance R&D pipelines and diversify product portfolios. Major players are investing heavily in R&D to develop next-generation metal-organic compounds with improved stability, purity, and process efficiency. These strategies, combined with regional expansion initiatives, aim to strengthen market positioning, sustain competitive advantage, and meet the evolving demands of high-tech manufacturing sectors.
Leading Company Profiles
The competitive landscape of the high purity metal organics market features innovative companies that prioritize technological development, strategic partnerships, and targeted product portfolios to capture market share and meet evolving industry demands.
- Tokuyama Corporation
- Heyuan Zhongsen Fine Chemical Co., Ltd.
- Jiangsu Kangqiang New Material Co., Ltd.
- ULVAC Technologies, Inc.
- Grace Davison
- Merck KGaA
- Tokyo Chemical Industry Co., Ltd.
- Jiangsu Eternal Asia Chemical Co., Ltd.
- Hangzhou Shenhua Chemical Co., Ltd.
Tokuyama Corporation
Tokuyama Corporation specializes in the production of high-purity chemical compounds used in semiconductors and electronics, leveraging cutting-edge purification technologies to ensure product excellence and strategic industry positioning.
Heyuan Zhongsen Fine Chemical Co., Ltd.
This company focuses on manufacturing high purity metal-organic compounds for application in electronics and energy devices, emphasizing advanced synthesis capabilities and a strong development pipeline for next-generation materials.
Jiangsu Kangqiang New Material Co., Ltd.
Jiangsu Kangqiang develops innovative metal-organic materials with a focus on sustainability, introducing eco-friendly processes that support high-performance applications in semiconductor and optoelectronic industries.
ULVAC Technologies, Inc.
ULVAC provides a broad portfolio of vacuum equipment and chemical products, including high purity metal-organic compounds tailored for semiconductor and display manufacturing, driven by technological innovation and global service support.
Grace Davison
Grace Davison specializes in specialty chemicals for electronics and catalysts, offering high-purity metal-organic products that are pivotal for advanced electronic components and energy storage systems.
Merck KGaA
Merck’s performance materials division develops and supplies high-purity metal-organic halides and related compounds, leveraging extensive R&D resources and a global footprint to meet increasing market demands.
Tokyo Chemical Industry Co., Ltd.
This firm delivers a wide range of high-grade chemical raw materials, including innovative metal-organic compounds essential for high-tech electronics, focusing on quality control and sustainable practices.
Jiangsu Eternal Asia Chemical Co., Ltd.
The company emphasizes the production of high purity metal-organic chemicals, supporting semiconductor and photovoltaic applications through continuous technological enhancement and capacity expansion.
Hangzhou Shenhua Chemical Co., Ltd.
Hangzhou Shenhua develops high-value, environmentally friendly high purity metal-organic products, emphasizing scalability, quality assurance, and customization for diverse high-tech industries.
Tokuyama Corporation
Reiterating its strategic focus, Tokuyama aims to expand its high purity chemical portfolio through innovation and alliances, reinforcing its leadership in the global high purity metal-organic market.
Strategic Business Developments
- February 2026 – Tokuyama Corporation – Launched new ultra-high purity metal-organic chemicals – Enhances product portfolio, supporting advanced semiconductor manufacturing needs and expanding market share.
- April 2026 – Merck KGaA – Invested in new production facility for high-purity organometallic compounds – Strengthens capacity to meet rising global demand, ensuring supply chain stability and technological leadership.
- June 2026 – ULVAC Technologies, Inc. – Entered strategic alliance with a leading electronics manufacturer – Facilitates development of next-generation vacuum and chemical solutions, boosting technological innovation and customer integration.
- August 2026 – Jiangsu Kangqiang – Announced capacity expansion for environmentally friendly metal-organic compounds – Positions the company as a key supplier for sustainable electronic applications worldwide.
- October 2026 – Tokyo Chemical Industry Co., Ltd. – Launched new line of high-purity metal-organic materials – Focuses on improving product quality and reducing environmental footprint, aligning with industry sustainability trends.
Frequently Asked Questions
What is the High Purity Metal Organics HPMO Market?
The High Purity Metal Organics HPMO Market encompasses the industry focused on manufacturing, distribution, and application of high purity metal organic compounds used primarily in electronics, semiconductors, and coating processes. It supports advanced technological innovations globally.
What is the current market size of High Purity Metal Organics HPMO Market?
As of 2026, the market size is valued at approximately USD 1.8 Billion, reflecting steady growth driven by increased demand in electronics and solar industries, alongside expanding applications in aerospace and medical devices.
What factors are driving the High Purity Metal Organics HPMO Market?
The key drivers include rising adoption of miniaturized electronic devices, rapid advancements in semiconductor fabrication, demand for higher efficiency in solar panels, and stringent quality standards across the electronics manufacturing sector.
Which region dominates the High Purity Metal Organics HPMO Market?
Asia-Pacific holds the leading position, accounting for the largest market share due to its substantial manufacturing base in electronics and solar industries, supported by rapid industrialization and supportive government policies.
Which segment is expected to grow the fastest?
Segmented by application, the semiconductor industry is anticipated to witness the fastest growth owing to increasing chip production and technological advancements in semiconductor materials.
Who are the leading companies operating in the High Purity Metal Organics HPMO Market?
Major players include Merck Group, Shin-Etsu Chemical, TOKYO OHKA KASEI, and Air Products and Chemicals, Inc., which are investing in R&D to innovate and expand their market presence globally.
Analyst Perspective
The long-term outlook for the High Purity Metal Organics (HPMO) Market remains promising, driven by the increasing adoption of advanced semiconductor and electronics manufacturing processes. As technology evolves, innovations such as atomic layer deposition (ALD) and chemical vapor deposition (CVD) techniques will heighten demand for ultra-high purity materials, creating significant commercial opportunities in niche high-tech applications. Investment priorities should focus on enhancing production scalability, purity levels, and process efficiency to stay competitive amid rising industry standards. Regional growth potential is especially notable in Asia-Pacific, where expanding semiconductor fabrication capacities and government incentives bolster market expansion, while North America and Europe continue to innovate through sustainable practices and technological advancement. Competitive intensity is expected to intensify, urging players to differentiate through R&D, strategic alliances, and capacity expansion. Long-term strategic positioning should emphasize pioneering high-purity standards, regional diversification, and environmentally sustainable practices to capture evolving market demands and mitigate operational risks.
