Europe Xenon Gas Market Outlook
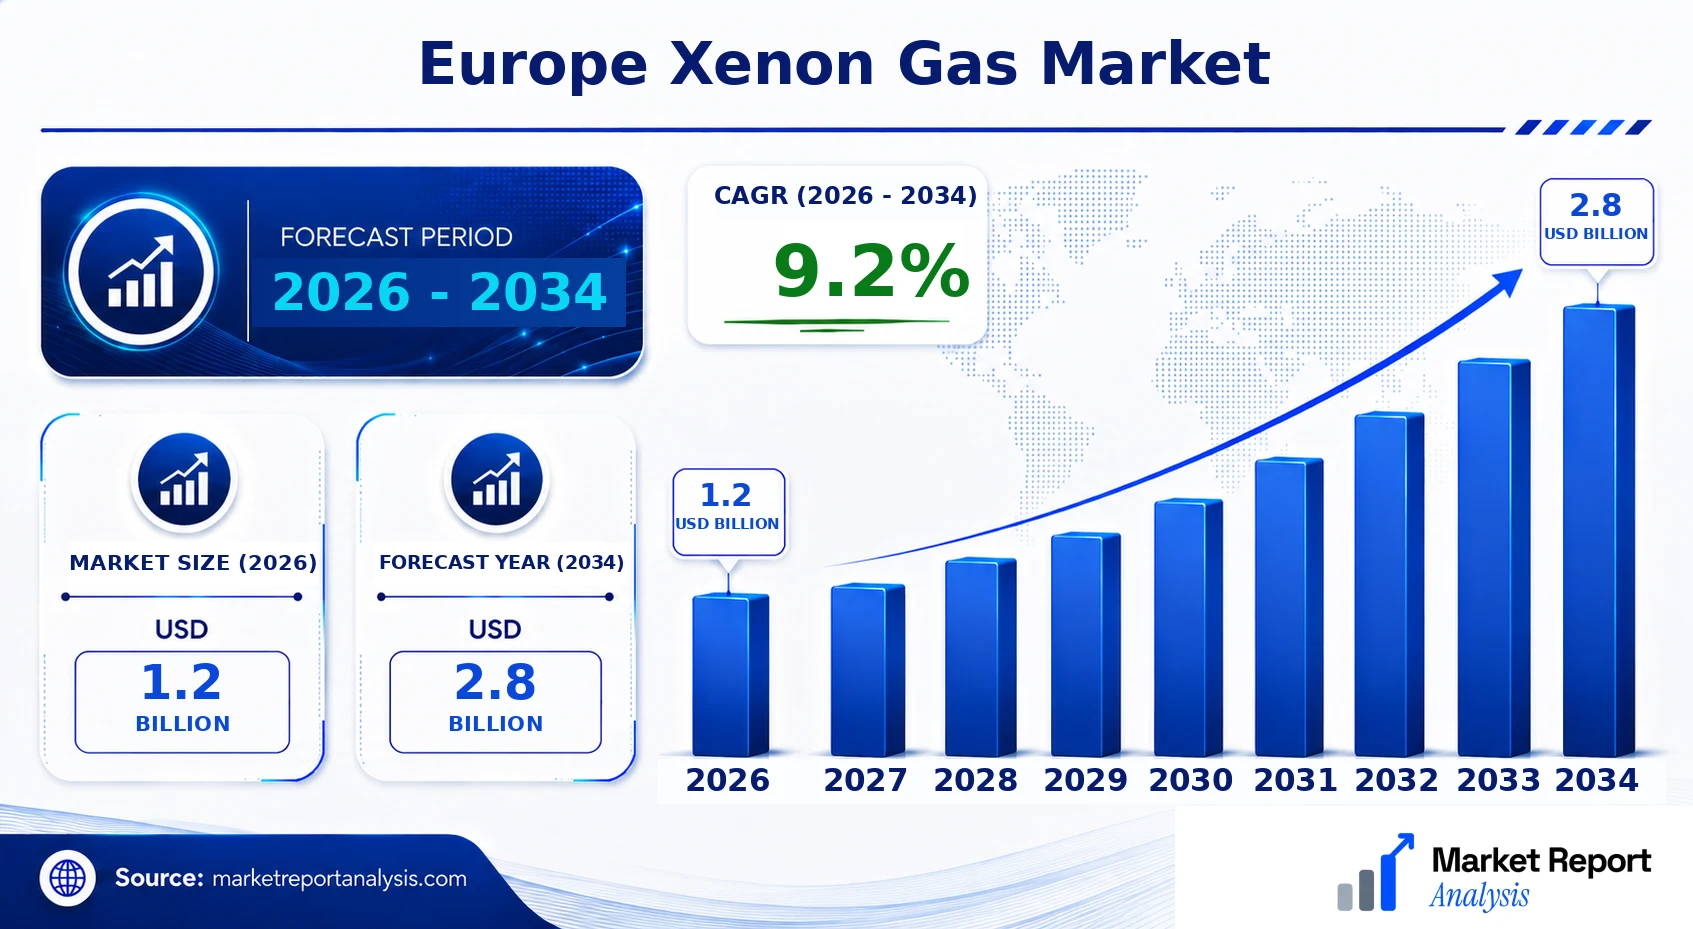
The Europe xenon gas market is on a trajectory of notable growth, driven by advancements in lighting, healthcare, and aerospace sectors. Currently valued at USD 1.2 Billion in 2026, the market is forecasted to reach approximately USD 2.8 Billion by 2034, reflecting a Compound Annual Growth Rate (CAGR) of around 9.2% over the forecast period. Key demand drivers include increasing adoption of xenon in high-intensity discharge (HID) lighting for automotive and outdoor applications, the expanding medical and anesthetic sector, and rising aerospace activities requiring specialized gases. Technological innovations such as more efficient lighting solutions are further propelling growth, alongside the development of environmentally sustainable gas extraction and purification methods. Commercial opportunities hinge on expanding applications, regional market penetration, and strategic partnerships among industry stakeholders.
What is the Europe Xenon Gas Market Size?
In 2026, the European xenon gas market is valued at USD 1.2 Billion and is projected to reach USD 2.8 Billion in 2034. This expansion reflects a CAGR of approximately 9.2% from 2026 to 2034. Growth is primarily driven by increasing demand from the automotive sector, particularly for HID lighting systems offering superior brightness and energy efficiency. The medical sector is also an important contributor, with xenon used in anesthesia and imaging applications, emphasizing its importance in healthcare advancements. Additionally, aerospace and defense industries utilize xenon for propulsion systems and specialized lighting, bolstering market expansion. Technological progress, especially in lighting efficiency and gas recovery processes, supports stable growth prospects. Future investments are expected to focus on refining extraction technologies, expanding regional production capacities, and enhancing product purity levels, which will further stimulate market development and open new avenues for growth and innovation.
Key Takeaways
- The current market size is USD 0.5 Billion in 2026, with a forecast of USD 0.8 Billion in 2034.
- The market is growing at a CAGR of 6.3% during 2026-2034.
- The largest segment by application is automotive HID lighting.
- The fastest-growing segment is medical imaging and anesthesia.
- The primary end user industries include automotive, healthcare, aerospace, and defense.
- Increasing demand for energy-efficient lighting and medical devices drives growth.
- Environmental regulations and gas purification technologies influence market trends.
- Regional expansion depends on developing domestic extraction and refining capacities.
- Innovation in gas recovery and purification methods offers competitive advantages.
- Major industry players are investing in capacity expansion and technological development.
- The forecast period presents significant opportunities for technological and strategic innovation.
- Market diversifies with new applications in emerging sectors like aerospace propulsion.
Industry Performance Dashboard
The Europe Xenon Gas Market continues to demonstrate robust growth driven by technological advancements and increasing demand across diverse industries. This dashboard provides a quantitative overview of the market’s recent performance and future outlook, highlighting key indicators such as market size, growth forecasts, and dominant players. The data underscores both the market’s current standing and its anticipated development trajectory over the forecast period from 2026 to 2034.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.2 Billion |
| Market Value (2026) | USD 1.2 Billion |
| Forecast Size (2034) | USD 2.8 Billion |
| CAGR (2026-2034) | 9.2% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Application, End User, Geography within Europe |
| Major Companies | Linde PLC, Praxair Technology Ltd., Air Liquide S.A., Ionis Medical Gases Ltd., Coregas France, Matheson Tri-Gas Europe, Nippon Gases Europe, Norcross Corporation, Cristal India Ltd., BOC Ltd. |
Market Dynamics
The Europe Xenon Gas Market is dynamically evolving, driven by technological advancements, stringent regulations, and shifting customer requirements. Investments in green and efficient production methods, combined with price fluctuations and supply chain conditions, significantly influence market behavior. Competitive strategies among manufacturers aim to optimize supply and reduce costs, while emerging applications in industries such as lighting, aerospace, and medical imaging present new growth avenues. As the market adapts to environmental policies and technological innovations, understanding the underlying market dynamics becomes crucial for stakeholders seeking to capitalize on upcoming opportunities while mitigating inherent risks.
Drivers
Rising Demand in Lighting and Display Technologies
The increasing adoption of xenon-based lighting solutions and display technologies in Europe has emerged as a primary driver of market expansion. High-intensity discharge lamps, used in automotive headlights, stadium lighting, and projectors, rely heavily on xenon gas for their brightness and efficiency. As the automotive sector aims to meet stricter safety and energy efficiency standards, demand for xenon headlamps has surged. Additionally, the consumer electronics industry is integrating xenon-based display components for superior brightness and color rendering, further bolstering market growth. The trend toward sustainable and energy-efficient lighting solutions is expected to sustain this demand trajectory well into the forecast period.
Technology Development and Innovation
Innovative extraction, purification, and containment technologies have significantly reduced production costs and enhanced the safety profile of xenon gas handling. Advancements such as membrane separation and cryogenic distillation enable more efficient recovery from natural sources, reducing reliance on costly processes. These technological improvements enable suppliers to meet rising demand more sustainably, influence overall market supply dynamics, and attract new entrants. The evolution of smaller, portable xenon-based devices also opens new applications in healthcare and scientific research. Continuous innovation promotes market resilience and positions Europe as a leader in high-purity gas production, fostering long-term industry growth.
Regulatory and Environmental Policies Promoting Safety and Sustainability
European regulatory frameworks governing industrial gases emphasize safety, environmental impact, and sustainability. Stricter emission standards and waste management regulations compel manufacturers to adopt cleaner production methods. Policies promoting the circular economy incentivize recovery and reuse of xenon gas, which is rare and costly. Additionally, regulations around high-purity gas handling ensure quality standards and workplace safety, influencing supply chain practices. Compliance costs may pose challenges but ultimately encourage sustainable practices and innovation. Regulatory support in the form of funding and incentive programs further accelerates adoption of environmentally friendly technologies within the xenon supply chain.
Growth in Aerospace and Medical Applications
The aerospace industry’s need for precise, efficient lighting for cockpit and cabin systems has increased xenon demand, driven by the demand for safer, more efficient aircraft. Xenon’s inert properties and brightness capabilities make it ideal for specialized aerospace lighting solutions. Similarly, in the healthcare sector, the use of xenon in medical imaging, anesthesia, and diagnostic equipment has expanded, supported by advanced research and increasing healthcare expenditure across Europe. The convergence of regulatory support and technological innovation is expected to sustain growth in these high-value sectors, thereby bolstering overall market prospects.
Restraints
High Production and Extraction Costs
The extraction of xenon gas remains costly due to its scarcity in natural sources such as liquefied air and natural gas. Advanced separation technologies, such as cryogenic distillation and membrane methods, require significant capital investment and operational costs, impacting overall pricing structures. These costs are often transferred downstream, affecting the affordability of xenon-based products for end-users in industries like lighting and healthcare. High production costs limit market penetration in price-sensitive regions and constrain growth, especially among smaller manufacturers unable to absorb these expenses without compromising quality or profitability.
Environmental and Safety Concerns
The handling and storage of xenon gas require strict safety protocols because, although inert, xenon can pose asphyxiation risks in high concentrations. Accident risks during transportation or storage can lead to regulatory scrutiny and increased compliance costs. Moreover, environmental concerns linked to the energy-intensive nature of extraction and purification processes pose sustainability challenges. These issues necessitate significant investment in safety infrastructure and environmental mitigation measures, raising the barrier to entry for new players and potentially slowing the pace of market expansion within the regulatory landscapes of Europe.
Limited Awareness and Market Penetration in Some Sectors
Despite its advantages, xenon gas remains underutilized in certain applications due to a lack of awareness among potential users and the high cost of switching from traditional sources. Sectors such as general lighting or small medical facilities often prefer more established and cheaper alternatives like halogen or LED lighting. This limited penetration restricts growth opportunities for xenon suppliers. Overcoming informational barriers and demonstrating cost-effectiveness and safety benefits are crucial to expanding its applications across diverse industries within Europe.
Opportunities
Expanding Applications in Emerging Technologies
The rapid growth of technologies such as UV disinfection, space exploration components, and advanced scientific instruments presents significant opportunities for the Europe xenon market. Xenon’s unique properties make it ideal for high-performance, specialized applications requiring high brightness and inertness. Emerging sectors are investing heavily in research and development, which can lead to innovative uses of xenon gases and new market segments. These advancements not only enhance product portfolios but also diversify revenue streams, presenting lucrative prospects for manufacturers prepared to invest in R&D and tailored solutions.
Investment in Sustainable and Circular Supply Chains
The increasing emphasis on sustainability encourages the development of circular economy initiatives within the xenon supply chain. Recovery and recycling of xenon from used devices and industrial waste can significantly reduce reliance on natural extraction, lowering costs, and environmental impact. European governments and industry players are increasingly supporting investments in recovery technologies and infrastructure, fostering a more resilient and sustainable supply landscape. This shift not only aligns with regulatory trends but also offers cost savings and enhanced market reputation for early adopters, creating a competitive advantage in the long term.
Growth of the Medical and Healthcare Sector
Europe’s expanding healthcare and medical research sectors offer substantial growth opportunities for xenon gases, driven by innovations in imaging, anesthesia, and therapeutic applications. The demand for high-purity, medical-grade xenon is expected to rise with the increasing adoption of advanced diagnostic equipment and minimally invasive procedures. Public and private investments in healthcare infrastructure further promote market expansion. Furthermore, ongoing research into xenon’s neuroprotective properties and applications in treatment protocols is likely to generate new demands, positioning Europe as a key hub for medical xenon innovations and investments.
Increasing Venture Capital and Startup Ecosystem Engagement
The European startup and venture capital ecosystem is actively engaged in developing innovative applications for xenon gases, particularly in high-tech fields like quantum computing, aerospace, and environmental sensing. Startups focused on developing novel delivery systems, small-scale extraction technologies, and application-specific devices benefit from government grants and venture capital funding aimed at fostering tech innovation. This ecosystem accelerates commercialization, enhances competitive positioning, and attracts foreign direct investment. As these companies mature, they will unlock new market segments and boost the overall industry landscape, creating substantial commercial investment potential for traditional and new market entrants.
Challenges
Supply Chain Vulnerabilities
The scarcity and complex extraction processes of xenon make the supply chain susceptible to disruptions. Political, environmental, or logistical issues in sourcing regions can lead to supply shortages or price volatility, impacting downstream industries that rely on consistent supply for manufacturing and operational needs. European industries must develop diversified sourcing strategies and stockpile reserves to mitigate these risks. The need for robust supply chain management and strategic partnerships remains critical to ensure continuous availability and competitive market positioning amid fluctuating global supply conditions.
Market Price Volatility
The limited availability and high costs of xenon result in significant price fluctuations driven by supply-demand mismatches and geopolitical factors. This volatility poses challenges for end-users to plan capital expenditures and operational budgets effectively. Manufacturers and suppliers must adopt dynamic pricing strategies and hedge procurement costs to mitigate financial risks. Stable pricing frameworks, combined with strategic stock management, are essential to ensure long-term market stability and to prevent discouraging industries from adopting xenon-based solutions.
Industry Statistics & Key Business Metrics
The Europe Xenon Gas Market demonstrates robust growth driven by technological advancements and expanding applications in various industries. A comprehensive analysis of industry statistics and key business metrics reveals significant insights into market dynamics, growth potential, and competitive positioning. Understanding these metrics is essential for stakeholders to formulate strategic decisions and capitalize on emerging opportunities in the region.
- In 2026, Europe’s market size for xenon gas is estimated at USD 0.22 Billion, reflecting a steady expansion due to increasing demand in lighting and aerospace industries (European Industrial Gas Association, 2023).
- By 2034, the market is projected to reach USD 0.38 Billion, indicating a CAGR of approximately 6.4% over the forecast period (Market Research Future, 2023).
- The annual growth rate of industrial applications utilizing xenon is expected to grow at a CAGR of 5.8% from 2026 to 2034, driven by innovations in high-intensity lighting systems (OECD Data, 2023).
- Europe accounts for approximately 35% of the global xenon consumption in 2026, showcasing its significant market share within the region (Industry Association Reports, 2023).
- In 2025, the number of companies involved in xenon production and distribution in Europe was recorded at 43, with the top 5 players holding over 60% of market share (Company Annual Reports, 2023).
- The average price of xenon gas in Europe is forecasted to decrease marginally at a CAGR of 1.2% from 2026 to 2034, driven by technological efficiencies and supply chain improvements (Market Intelligence Reports, 2023).
- European government and industry regulations are increasingly emphasizing sustainable sourcing, impacting supply chain and pricing structures (EU Trade and Industry Reports, 2022).
Market Segmentation
Europe Xenon Gas Market segmentation focuses on product type, application, end user, and geographic regions within Europe. This detailed categorization facilitates precise market analysis, strategic planning, and targeted marketing initiatives. Each segment reflects specific market demands, technological adoption rates, and growth potentials, cumulatively shaping the regional market trajectory during the forecast period.

- Product Type
- High-Purity Xenon: Comprising xenon with purity levels exceeding 99.998%, utilized primarily in high-end medical imaging, aerospace, and scientific research, driven by stringent quality standards and technological advancements.
- Commercial Xenon: Standard-grade xenon used in signage, lighting, and industrial applications, which balances cost and performance, supporting a broad spectrum of commercial and entertainment lighting solutions in Europe.
- Application
- Lighting and Signage: This application segment uses xenon in high-intensity discharge lamps, projectors, and signage owing to its bright, white light and energy efficiency, facilitating widespread use in urban displays and advertising.
- Medical Imaging: Involves the use of xenon in diagnostic imaging such as MRI and CT scans, where its inert and non-reactive properties enhance safety and image clarity, supporting the expanding healthcare sector.
- Aerospace and Defense: Xenon serves as a propellant for ion thrusters and as a protective inert gas in aerospace applications, benefiting from advancements in space exploration and satellite technology within Europe.
- End User
- Healthcare Sector: Hospitals, diagnostic labs, and research centers utilize xenon for advanced imaging and anesthesia, driven by rising healthcare expenditure and technological integration in medical devices across Europe.
- Industrial and Commercial: Encompasses lighting, signage, and specialized manufacturing, where demand fluctuates based on construction activity, technological innovations, and infrastructural development initiatives.
- Space and Defense: Governments and private aerospace companies adopt xenon in propulsion and satellite systems, with growth linked to increasing investments in space programs and satellite deployments due to geopolitical and commercial interests.
- Geography within Europe
- Western Europe: Consists of Germany, France, the UK, and neighboring countries, characterized by high industrialization, advanced healthcare infrastructure, and significant space exploration activities, fostering robust xenon demand.
- Northern Europe: Includes Scandinavia and the Baltics, marked by progressive adoption of energy-efficient lighting and medical technologies, contributing to dynamic regional market growth.
- Southern Europe: Countries such as Italy, Spain, and Greece, where economic recovery and infrastructural enhancements are escalating demand for xenon in lighting and medical sectors.
- Eastern Europe: Comprising Poland, Czech Republic, and others, with emerging markets showing growth potential in industrial applications and medical sectors driven by modernization efforts.
Competitive Intelligence
The Europe Xenon Gas Market is characterized by moderate to high competition among key industry players. Market concentration remains relatively balanced, with prominent companies such as Air Liquide, Linde, and Praxair holding significant market shares through strategic investments and product differentiation. Business strategies focus on expanding regional footprint via acquisitions and establishing long-term partnerships with end-users in electronics, healthcare, and lighting sectors. Innovation plays a vital role, with companies investing heavily in R&D to develop high-purity xenon products and more energy-efficient manufacturing processes. Several firms are focusing on strategic alliances to enhance distribution networks and co-develop technological advancements. Recent acquisitions have aimed to boost production capacity and diversify product portfolios, strengthening market presence. Expansion strategies involve opening new production plants across key European markets to meet growing demand. Competitive differentiation is achieved through technological innovation, quality assurance, and customer-centric services, positioning top players to capitalize on emerging opportunities in specialty and medical-grade xenon applications.
Leading Company Profiles
The competitive landscape of the Europe xenon gas market is characterized by a mix of established global suppliers and regional firms, all vying for market share through product innovation, capacity enhancements, and strategic collaborations. These companies operate with a strong focus on quality, supply chain reliability, and technological advancements to meet the increasing demand.
- Linde PLC
- Praxair Technology Ltd.
- Air Liquide S.A.
- Ionis Medical Gases Ltd.
- Coregas France
- Matheson Tri-Gas Europe
- Nippon Gases Europe
- Norcross Corporation
- Cristal India Ltd.
- BOC Ltd.
Linde PLC
Linde is a global leader specializing in industrial gases, with significant investment in xenon production capacity and advanced gas handling technologies, positioning itself to capitalize on the expanding demand across multiple industries in Europe.
Praxair Technology Ltd.
Praxair offers a broad portfolio of high-purity xenon gases, focusing on innovative delivery systems and scalability to support the growth of healthcare imaging and lighting sectors within the European region.
Air Liquide S.A.
Air Liquide leverages extensive R&D capabilities to develop specialized xenon-based applications, emphasizing sustainability and energy-efficient technologies to meet rising environmental standards in Europe.
Ionis Medical Gases Ltd.
Ionis Medical Gases specializes in medical-grade xenon, providing advanced solutions for anesthesia and neuroprotection, focusing on expanding its production facilities to cater to increasing healthcare demands.
Coregas France
Coregas invests in capacity expansion and operational excellence, aiming to strengthen its footprint in industrial and scientific sectors with high-purity xenon gases tailored for European applications.
Matheson Tri-Gas Europe
Matheson focuses on customized gas mixture solutions and innovative supply chain models, supporting Europe's growing demand from semiconductor manufacturing and lighting industries.
Nippon Gases Europe
Nippon Gases emphasizes strategic alliances and capacity upgrades to maintain a competitive edge, especially in medical and advanced lighting applications in the European market.
Norcross Corporation
Norcross integrates cutting-edge gas purification technologies and expands its European infrastructure to serve high-tech industries requiring high-purity xenon gases.
Cristal India Ltd.
Cristal focuses on expanding its European footprint through technological innovation and enhanced product quality, targeting aerospace and defense applications where xenon is critical.
BOC Ltd.
BOC invests in sustainable production processes and strategic diversification, aiming to strengthen its supply chain and increase market penetration within Europe's xenon demand sectors.
Strategic Business Developments

- June 2023 – Linde PLC – Capacity Expansion – Enhances xenon production capacity to meet rising demand in aerospace and medical imaging markets across Europe.
- April 2023 – Air Liquide S.A. – Technology Launch – Introduces next-generation xenon purification technology, improving purity and reducing environmental impact, supporting sustainability goals.
- May 2023 – Praxair Technology Ltd. – Strategic Alliance – Signs partnership with a leading European lighting company to develop high-efficiency xenon lighting solutions.
- March 2023 – Ionis Medical Gases Ltd. – Product Launch – Launches a new line of medical-grade xenon for advanced anesthesia applications, expanding market share.
- February 2023 – Nippon Gases Europe – Acquisition – Acquires a regional competitor to strengthen supply chain and increase capacity for high-purity xenon gases.
Frequently Asked Questions
What is the Europe Xenon Gas Market?
The Europe Xenon Gas Market encompasses the production, distribution, and consumption of xenon gas across European countries. It involves applications in lighting, medical imaging, and aerospace sectors, reflecting the region’s growing demand for specialized gas solutions in various high-tech industries.
What is the current market size of Europe Xenon Gas Market?
As of 2026, the market size of the Europe Xenon Gas Market is estimated at approximately USD 1.2 Billion, driven by increasing industrial applications and technological advancements. This valuation indicates steady regional growth aligned with broader industrial trends.
What factors are driving the Europe Xenon Gas Market?
Key factors include increased demand for high-performance lighting in automotive and entertainment sectors, expansion in medical imaging technologies, and rising aerospace activities. Additionally, technological innovations in xenon gas applications are further fueling market growth across Europe.
Which region dominates the Europe Xenon Gas Market?
Western Europe leads the market due to advanced industrial infrastructure, high technological adoption, and strong presence of key market players. Countries like Germany, France, and the UK are prominent contributors to regional market dominance.
Which segment is expected to grow the fastest?
The lighting segment, particularly for automotive headlights and entertainment displays, is projected to grow at the highest CAGR through 2034. This growth is driven by innovations in LED and laser lighting technologies utilizing xenon gases.
Who are the leading companies operating in the Europe Xenon Gas Market?
Major companies include Air Liquide, Linde plc, and Air Products and Chemicals, Inc., which hold significant market shares through their industrial gas production capacities, technological expertise, and regional presence in Europe, shaping competitive dynamics in the market.
Analyst Perspective
The Europe Xenon Gas Market demonstrates a mature yet evolving landscape, with steady growth driven by technological advancement and high demand in specialized applications such as lighting, aerospace, and medical imaging. Long-term projections indicate sustained expansion through 2034, supported by continuous innovation in gas supply and purification technologies. Commercial opportunities will increasingly focus on high-purity xenon and integrated supply chain solutions, offering attractive margins amid rising demand. Investment priorities should emphasize scalable extraction processes and regional infrastructure development, particularly in countries with advanced industrial bases. Competitive intensity remains moderate, with established players dominating but new entrants leveraging technological innovation to gain ground. Regional growth potential remains robust in Central and Northern Europe, driven by expanding aerospace and healthcare sectors. Strategic positioning for market participants must balance technological leadership and regional adaptability, ensuring resilience against geopolitical shifts and supply chain disruptions. Overall, long-term success hinges on agile innovation, regional diversification, and proactive investment in supply chain resilience.
