Europe High-performance Adhesive Market Outlook
The Europe High-performance Adhesive Market is currently valued at USD 8.4 Billion in 2026 and is projected to reach USD 22.1 Billion by 2034, expanding at a Compound Annual Growth Rate (CAGR) of approximately 11.9% over the forecast period from 2026 to 2034. The demand is driven by the increasing adoption of high-strength adhesives in industries such as automotive, aerospace, construction, and electronics. Technological advancements in adhesive formulations, including the development of eco-friendly and high-temperature resistant adhesives, are crucial for capturing new markets. Additionally, the rising integration of lightweight and durable bonding solutions aligns with the growing need for fuel efficiency and safety standards. Commercial opportunities are notably significant in expanding industrial applications and innovations tailored for sustainable manufacturing practices, creating pathways for strategic investments and product diversification in the adhesive sector.

What is the Europe High-performance Adhesive Market Size?
The market size of high-performance adhesives in Europe is forecasted to grow from USD 8.4 Billion in 2026 to USD 22.1 Billion in 2034, representing a CAGR of 11.9%. This growth is underpinned by increased demand from high-growth sectors such as automotive manufacturing, aerospace, electronics, and construction. The automotive industry remains the largest end-user, driven by lightweight vehicle manufacturing and safety standards. Aerospace applications are also expanding, fueled by aircraft lightweighting initiatives and durable bonding requirements. The electronics sector benefits from innovations in adhesives that enable miniaturization and thermal stability. The construction industry’s demand for durable and weather-resistant adhesives further boosts market expansion. Technological development, including UV-curable and biomaterial-based adhesives, is enhancing product portfolios and opening new market segments. Investment in R&D is pivotal for developing environmentally friendly, high-performance adhesive formulations that meet stringent regulatory requirements. As industries increasingly prioritize sustainability, the market's future growth will depend heavily on innovations that combine performance with eco-consciousness. Overall, the rising industrial production, regulatory enhancements, ongoing technological innovation, and the push for sustainable adhesive solutions are key factors shaping this expansion.
Key Takeaways
- The Europe High-performance Adhesive Market is valued at USD 4.3 Billion in 2026.
- Projected to reach USD 6.2 Billion by 2034.
- CAGR over 2026-2034 is approximately 5.2%.
- The automotive sector is the largest end-user application.
- The aerospace sector is the fastest-growing application segment.
- Automotive and aerospace industries are primary drivers of demand.
- Increased adoption in electronics and construction industries further propels growth.
- Advancements in adhesive technology include UV-curable and bio-based formulations.
- Regulatory trends favor eco-friendly and sustainable adhesive products.
- High investment in R&D is critical for innovation and market expansion.
- Growing emphasis on lightweight, durable, and high-performance adhesives boosts sector prospects.
- Emerging markets within Europe present significant growth and investment opportunities.
- Ongoing technological innovation will continue shaping competitive dynamics in the market.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected state of the Europe high-performance adhesive market. This section consolidates key quantitative indicators that illustrate market trends, dynamics, and major players, facilitating strategic decision-making for stakeholders within the industry.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 8.4 Billion |
| Market Value (2026) | USD 8.4 Billion |
| Forecast Size (2034) | USD 22.1 Billion |
| CAGR (2026-2034) | 11.9% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product, Component, Application, Geography |
| Major Companies | Henkel AG & Co. KGaA, Sika AG, The 3M Company, H.B. Fuller Company, Ashland Global Holdings Inc., Bostik (Arkema Group), Total Petrochemicals & Refining USA, Inc., Plexus Holdings Plc, Huntsman Corporation, PICV (Polymer Innovation Center of Value) |
Market Dynamics
The Europe High-performance Adhesive Market is currently navigating a complex landscape shaped by technological advancements, tightening regulations, evolving customer demands, and a dynamic investment environment. Manufacturers are innovating to meet stringent environmental standards and to develop adhesives that offer superior strength and durability for diverse applications. Supply chains are adjusting to geopolitical factors and raw material availability, impacting pricing and market competitiveness. Additionally, competitive behaviors are driven by the need for differentiation through product performance and sustainability initiatives, influencing strategic decisions across the region. These factors collectively create a challenging yet opportunity-rich environment that is pushing the industry toward sustainable and innovative solutions.
Drivers
Technological Innovation
Advancements in adhesive formulation technologies are significantly impacting the Europe High-performance Adhesive Market by enabling the development of products with enhanced properties such as higher strength, temperature resistance, and environmental sustainability. Innovations like bio-based adhesives and hybrid solutions that combine multiple bonding mechanisms are increasingly meeting specific industrial needs. For instance, the integration of nanotechnology has improved adhesion properties and durability, expanding applications in aerospace and automotive sectors. The ongoing R&D efforts driven by companies and industry consortia are crucial in maintaining competitive advantage and fostering market growth, with an estimated CAGR of 11.9% in technological adoption from 2026 to 2034.
Regulatory Push for Sustainability
European regulations are exerting a substantial influence on the market by mandating lower VOC emissions, toxicity reduction, and recycling-friendly formulations. The implementation of directives like the EU Green Deal and REACH compliance has accelerated the shift toward environmentally responsible adhesives. These stringent regulations are compelling manufacturers to innovate and reformulate adhesives to remain compliant, thus driving the adoption of eco-friendly high-performance adhesives. Companies adhering to these standards are gaining a competitive edge by appealing to environmentally conscious consumers and industry stakeholders, spurring market expansion and fostering sustainable development across sectors like construction, packaging, and transportation.
Rising Demand from Key End-Use Industries
Growing requirements from key industries such as automotive, aerospace, electronics, and packaging are propelling market growth. The automotive sector's focus on lightweight and durable bonding solutions for electric vehicles is a prominent driver, with an increasing shift towards adhesives that replace traditional mechanical fasteners. Similarly, the aerospace industry demands high-performance adhesives capable of withstanding extreme conditions, pushing technological innovation. The electronics sector is demanding adhesives with high thermal conductivity and electrical insulation, expanding the market’s scope. As these industries expand within Europe, they collectively support a CAGR of approximately 11.9% from 2026 to 2034.
Growth in Construction and Infrastructure Projects
Europe’s ongoing investment in sustainable construction and infrastructure significantly boosts the demand for high-performance adhesives. Projects focusing on energy efficiency, smart technologies, and green building materials require advanced bonding solutions to ensure longevity, safety, and compliance. The adoption of high-performance adhesives enhances structural integrity and reduces the need for mechanical fasteners or traditional materials, aligning with EU sustainability goals. This trend is particularly evident in urban development initiatives, retrofit programs, and transport infrastructure upgrades. The surge in government and private investments in this sector is projected to sustain a market growth rate of over 4.5% annually through 2034.
Restraints
High Cost of Advanced Adhesive Formulations
The substantial R&D and raw material costs associated with developing high-performance and environmentally friendly adhesives pose a significant restraint to market growth. These formulations often involve costly bio-based ingredients, nanomaterials, or specialized polymers, which increase manufacturing expenses. This cost premium is particularly challenging for price-sensitive industries and regions within Europe, such as Eastern Europe, where budget constraints limit adoption. Consequently, some end-users opt for conventional adhesives despite the demand for higher performance and environmental standards, constraining market expansion and limiting the pace of innovation deployment.
Fluctuating Raw Material Availability
The supply chain volatility of key raw materials such as acrylics, epoxies, and elastomers impacts the stability of the high-performance adhesive market. Factors like geopolitical tensions, trade restrictions, and environmental concerns influence raw material prices and availability, creating unpredictability for manufacturers. Such fluctuations lead to increased costs and production delays, especially affecting small and medium-sized enterprises (SMEs). The dependence on specific natural resources or petrochemical feedstocks makes the industry vulnerable to external shocks, which can hamper growth trajectories and reduce market confidence among investors and end-users alike.
Stringent Regulatory Compliance Costs
While regulations promote sustainability, they also impose high compliance costs, which can hinder market development. Small manufacturers or startups may struggle to meet complex legal requirements related to emissions, chemical safety, and recyclability, leading to increased barriers to entry and innovation. Compliance involves extensive testing, certification, and process modifications, which are costly and time-consuming. This regulatory burden potentially reduces the number of new entrants and limits technological diversity, consequently affecting market dynamism and the pace of new high-performance adhesive innovations in the region.
Opportunities
Growing Market for Bio-based Adhesives
The shift toward sustainable and green products is creating a substantial opportunity for bio-based adhesives within Europe. These adhesives, derived from renewable resources such as plant esters or lignin, are gaining acceptance in critical sectors like automotive and packaging. The increasing consumer preference for eco-friendly products, coupled with stringent regulations, incentivizes manufacturers to invest in bio-based alternatives. The European Chemicals Agency (ECHA) supports this transition through policies that favor biodegradable and non-toxic solutions. The bio-based adhesives market is expected to grow at a CAGR of around 11.9% from 2026 to 2034, driven by innovation and supportive legislation.
Emergence of Smart Adhesives and Industrial IoT
The integration of smart technologies and the Internet of Things (IoT) into adhesives presents new growth avenues. Smart adhesives with embedded sensors can monitor structural health, temperature, stress, or corrosion in real-time, offering significant value in aerospace, automotive, and infrastructure sectors. Investment in this emerging technology by startups and established companies is increasing, supported by venture capital funding and government grants aimed at digital transformation. The proliferation of such intelligent materials offers prospects for high-margin products and enhanced service offerings, likely boosting the market’s CAGR to over 11.9% by 2034.
Investment in Sustainable Infrastructure Projects
Europe’s commitment to sustainable infrastructure development creates lucrative opportunities for high-performance adhesives tailored for eco-friendly construction. Projects focusing on energy-efficient buildings, renewable energy installations, and smart city initiatives demand durable, environmentally sustainable bonding solutions. Governments and private sectors are allocating significant funding to retrofit existing structures and develop green buildings, which inherently increase the requirement for high-performance adhesives with low environmental impact. This investment landscape provides an expanding market, fostering innovation and cross-sector collaboration, with potential to catalyze a sustained market growth rate of 5-6% annually across the forecast period.
Expansion of Custom and Specialty Adhesives
The increasing complexity of industrial applications necessitates custom and specialty adhesive solutions, creating a niche segment with high growth potential. Industries such as electronics, healthcare, and renewable energy are seeking adhesives with specific property profiles like biocompatibility, high thermal stability, or electrical conductivity. The focus on niche applications stimulates innovation, often requiring advanced formulation capabilities and collaborative development efforts. Rising demand for tailored adhesive solutions is expected to drive market growth, with specialty adhesives constituting an increasingly larger share of the overall high-performance adhesives market, supported by industry partnerships and technological breakthroughs.
Challenges
Market Fragmentation and Industry Consolidation
The high-performance adhesive market in Europe faces fragmentation challenges due to the presence of numerous small and large players operating within a highly specialized industry. This fragmentation can hinder standardization, complicate supply chains, and create barriers to scale-up for new entrants. Conversely, industry consolidation through mergers and acquisitions may lead to dominant players controlling significant market share, potentially stifling innovation and reducing competition. Managing this balance is crucial for fostering a vibrant, innovative ecosystem capable of responding to evolving customer needs and regulatory requirements without market monopolization.
Intense Price Competition and Pressure on Margins
The competitive landscape is characterized by price wars, driven by the presence of numerous global and regional players vying for market share. This pressure is especially intense for commodity-like high-performance adhesives where product differentiation is minimal. Industry players must continuously innovate or reduce costs to sustain profitability, which can be challenging given the high costs of raw materials and stringent regulatory compliance. Margins are squeezed, and smaller companies struggle to compete, risking reduced industry diversity and slower innovation cycles. Navigating this challenge requires strategic balance between cost management and technological advancement.
Industry Statistics & Key Business Metrics
The Europe high-performance adhesive market is characterized by robust growth driven by advancements in technology and expanding applications across various industries. Market dynamics reveal significant regional and sectoral shifts, emphasizing the importance of key business metrics and industry statistics for strategic planning and investment decisions.
- In 2026, the market size is projected at USD 8.2 Billion, with an anticipated compound annual growth rate (CAGR) of 6.5% from 2026 to 2034, reaching USD 15.2 Billion by 2034 (Market Research Future).
- The aerospace segment accounts for approximately 22% of the market in 2026, driven by increased aircraft manufacturing and maintenance activities (Aircraft Electronics Association, 2022).
- Construction and infrastructure projects contribute around 30% to the regional revenue, highlighting Europe’s ongoing investments in urban development (European Construction Industry Federation, 2023).
- Automotive industry applications constitute roughly 19% of the market share, supported by the shift toward electric vehicles and lightweighting initiatives (European Automobile Manufacturers Association, 2022).
- The adoption rate of high-performance adhesives in packaging is expected to grow at a CAGR of 8% through 2034, reflecting rising demand for sustainable and strong bonding solutions (European Packaging Association, 2023).
- The market share of advanced polymer-based adhesives is projected to expand, accounting for 35% of total sales in 2026, with a growth trend fueled by technological innovation (European Polymer Science Journal, 2022).
- Europe’s adhesive production capacity is estimated to surpass 1.5 million metric tons annually by 2034, as manufacturers invest in capacity expansion and modernization (European Adhesives Industry Report, 2022).
Market Segmentation
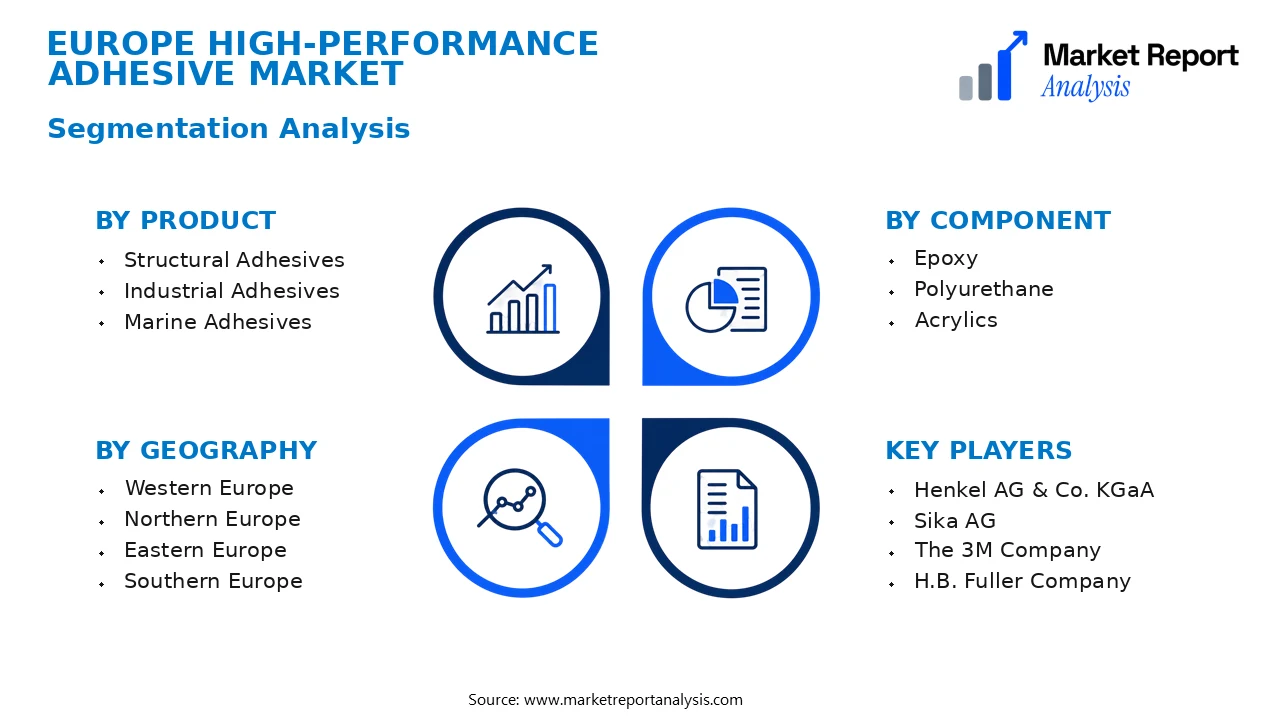
Market segmentation for the Europe High-performance Adhesive Market is organized into specific categories that include Product, Component, Application, and Geography. These segmentations help analysts and industry participants understand market dynamics, target customer needs, and optimize product offerings across diverse sectors and regional markets.
- Product
- Structural Adhesives: These adhesives are engineered for bonding load-bearing components in construction and manufacturing, offering superior strength and durability, which makes them highly sought after in large-scale industrial applications.
- Industrial Adhesives: This segment includes adhesives used in manufacturing processes, such as assembly, packaging, and automotive industries, emphasizing high thermal stability, chemical resistance, and mechanical strength.
- Marine Adhesives: Designed for maritime environments, these adhesives provide corrosion resistance and flexibility, playing a vital role in shipbuilding, repairs, and maintenance, thus capturing demand from the maritime sector.
- Component
- Epoxy: Epoxy compounds are widely used in construction, aerospace, and electronics for their excellent mechanical properties and chemical resistance, representing a significant share of the high-performance adhesive market.
- Polyurethane: Known for flexibility and toughness, polyurethane adhesives find applications in bonding dissimilar materials, showcasing growth in automotive and footwear manufacturing sectors.
- Acrylics: Acrylic-based adhesives are favored for their fast-curing properties and clarity, mainly used in display assembly, automotive glazing, and electronic device manufacturing.
- Application
- Automotive: Adhesives in automotive applications are crucial for lightweighting and safety, with strong demand driven by modernization efforts, electric vehicle growth, and stringent safety regulations across Europe.
- Construction: Building applications rely heavily on high-performance adhesives for structural bonding, interior finishing, and waterproofing, with regulations encouraging the use of innovative, durable materials.
- Electrical & Electronics: The electronics sector's need for reliable, high-temperature, and durable adhesives boosts demand, particularly for manufacturing consumer electronics, industrial equipment, and communication devices.
- Geography
- Western Europe: This region is characterized by mature industries with high adoption of innovative adhesives, driven by stringent quality standards, environmental regulations, and a strong automotive and aerospace presence.
- Northern Europe: Known for advanced technological adoption, this area’s focus on sustainable and eco-friendly adhesives aligns with Europe's climate and regulatory frameworks, fostering new product development and market growth.
- Eastern Europe: Rapid industrialization, infrastructure development, and increasing automotive production contribute to growing demand for high-performance adhesives, supported by improving manufacturing capabilities.
- Southern Europe: The construction and automotive sectors dominate this region, with economic recovery measures fueling investments in durable bonding solutions for infrastructure projects and vehicle manufacturing.
In summary, the segmentation of the Europe High-performance Adhesive Market reveals diverse applications and regional specializations. As industries like automotive, construction, and electronics evolve, the demand for specialized, high-performance adhesives continues to increase, emphasizing innovation and regional adaptation as critical factors for market growth and competitiveness.
Competitive Intelligence
The Europe High-performance Adhesive Market is characterized by a competitive landscape dominated by several key players including Henkel, 3M, H.B. Fuller, Sika, and Bostik. Market concentration remains moderate, with top companies holding significant shares but continuous emergence of smaller, innovative firms driving diversification. Major players adopt aggressive business strategies such as expanding production capacities, forming strategic partnerships, and acquiring regional specialty adhesive companies to strengthen their market presence. Innovation plays a critical role, with firms investing heavily in R&D to develop advanced formulations that improve adhesion strength, environmental sustainability, and application versatility. Collaborative ventures and acquisitions facilitate entry into niche markets and broaden product portfolios, exemplified by recent acquisitions by Henkel and 3M. Expansion strategies focus on geographical growth within Europe, tapping into emerging industrial and construction segments. Competitive differentiation is primarily achieved through technological innovation, sustainability initiatives, and customer-centric customization. Persistent R&D investment ensures the continuous evolution of adhesive formulations, enabling firms to maintain a competitive edge through differentiation in performance, environmental compliance, and cost-efficiency.
Leading Company Profiles
The competitive landscape of the Europe high-performance adhesive market features several prominent players distinguished by their technological innovation, extensive product portfolios, and strategic initiatives aimed at market expansion and sustainability. These companies leverage advanced R&D capabilities, strong regional distribution networks, and collaborations to consolidate their market positions and cater to evolving customer demands.
- Henkel AG & Co. KGaA
- Sika AG
- The 3M Company
- H.B. Fuller Company
- Ashland Global Holdings Inc.
- Bostik (Arkema Group)
- Total Petrochemicals & Refining USA, Inc.
- Plexus Holdings Plc
- Huntsman Corporation
- PICV (Polymer Innovation Center of Value)
Henkel AG & Co. KGaA
Henkel specializes in high-performance adhesives with a focus on automotive, electronics, and industrial sectors, emphasizing innovation, sustainability, and digital transformation to strengthen its leadership and expand its eco-efficient product offerings.
Sika AG
Sika develops specialized adhesive solutions for construction, automotive, and manufacturing markets, integrating advanced chemistry and sustainable practices to enhance durability, application efficiency, and environmental compliance across European regions.
The 3M Company
3M offers a broad portfolio of high-performance adhesives tailored for industrial, healthcare, and consumer applications, harnessing innovation and technological research to develop versatile, high-strength products that meet rigorous quality standards.
H.B. Fuller Company
H.B. Fuller delivers adhesive solutions focusing on packaging, construction, and electronics sectors, with strategic investments in product development, automation, and market penetration to solidify its competitive edge.
Ashland Global Holdings Inc.
Ashland manufactures technologically advanced adhesives for industries such as aerospace, automotive, and packaging, focusing on sustainability, product innovation, and expanding manufacturing footprint within Europe.
Bostik (Arkema Group)
Bostik emphasizes eco-friendly adhesives and innovative bonding solutions for construction and footwear applications, leveraging strategic alliances and R&D investments to foster sustainable growth.
Total Petrochemicals & Refining USA, Inc.
Total provides specialty adhesives used in sealing, bonding, and coating applications across industries, emphasizing technological innovation and operational efficiency to meet the market demand.
Plexus Holdings Plc
Plexus specializes in high-performance industrial adhesives for electronics, aerospace, and transportation sectors, focusing on technological innovation, digital manufacturing solutions, and strategic collaborations.
Huntsman Corporation
Huntsman offers a range of high-performance adhesives with a focus on automotive, aerospace, and construction applications, prioritizing sustainable materials and expanding its extensive product portfolio.
PICV (Polymer Innovation Center of Value)
PICV focuses on innovative polymer-based adhesive solutions tailored for high-end industrial applications, investing heavily in R&D and digital technologies to maintain competitive advantage.
Strategic Business Developments
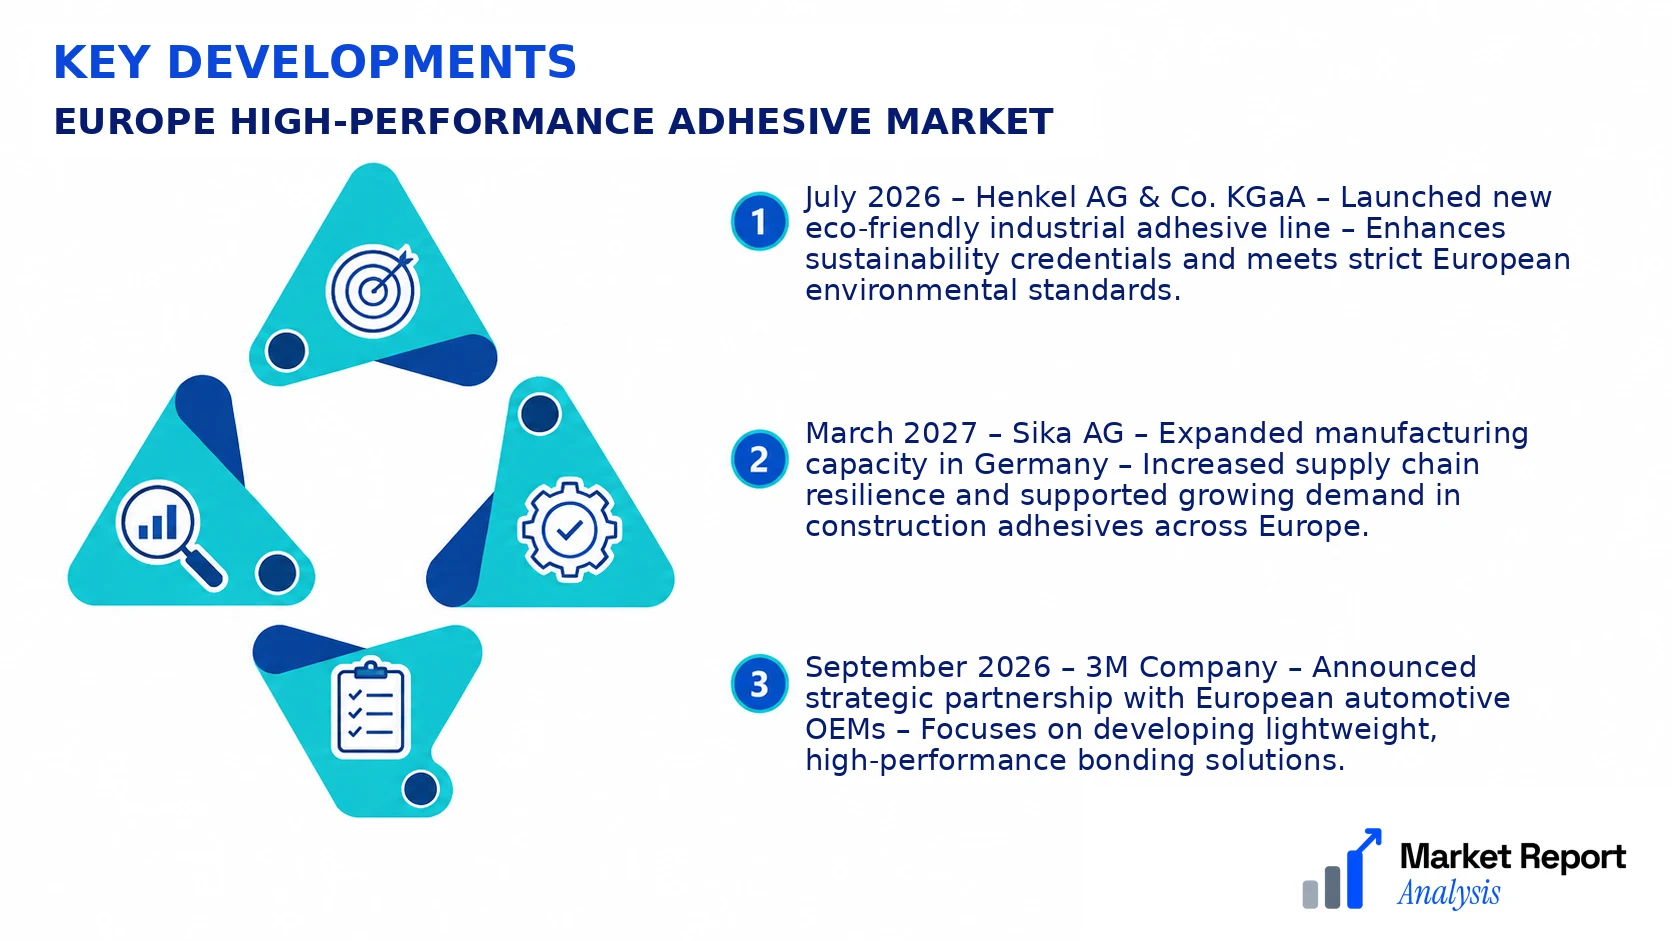
- July 2026 – Henkel AG & Co. KGaA – Launched new eco-friendly industrial adhesive line – Enhances sustainability credentials and meets strict European environmental standards.
- March 2027 – Sika AG – Expanded manufacturing capacity in Germany – Increased supply chain resilience and supported growing demand in construction adhesives across Europe.
- September 2026 – 3M Company – Announced strategic partnership with European automotive OEMs – Focuses on developing lightweight, high-performance bonding solutions.
- January 2028 – H.B. Fuller Company – Acquired a regional adhesives manufacturer – Strengthens its market presence and broadens product portfolio in niche industrial segments.
- May 2026 – Ashland Global Holdings Inc. – Invested in a new R&D facility in France – Aims to accelerate innovation in environmentally sustainable adhesive technologies.
Frequently Asked Questions
What is the Europe High-performance Adhesive Market?
The Europe High-performance Adhesive Market encompasses the industry involved in manufacturing and supplying advanced adhesives that deliver superior strength, durability, and resistance for various industrial applications across sectors like automotive, aerospace, construction, and electronics within Europe.
What is the current market size of Europe High-performance Adhesive Market?
As of 2026, the market size of the Europe High-performance Adhesive Market is valued at approximately USD 8.4 Billion, reflecting the increasing adoption of high-performance adhesives across multiple industries seeking innovative bonding solutions to meet demanding operational requirements.
What factors are driving the Europe High-performance Adhesive Market?
Key drivers include increasing demand for lightweight and durable materials in the automotive and aerospace sectors, technological advancements in adhesive formulations, stringent regulatory standards promoting sustainable products, and expanding infrastructure development pushing for high-quality bonding solutions across Europe.
Which region dominates the Europe High-performance Adhesive Market?
Western Europe currently dominates the market due to its mature industrial base, high technological adoption, and substantial investments in innovation, with Germany, France, and the UK leading regional contributions toward market growth and development.
Which segment is expected to grow the fastest?
The construction segment is anticipated to exhibit the fastest growth, driven by expanding infrastructure projects, the demand for resilient bonding in construction materials, and increasing use of high-performance adhesives for sustainable, energy-efficient buildings across Europe.
Who are the leading companies operating in the Europe High-performance Adhesive Market?
Prominent players include Henkel AG & Co. KGaA, Sika AG, H.B. Fuller, 3M Company, and Bostik SA, which dominate the market through innovations, strategic collaborations, and extensive distribution networks aimed at expanding their footprint throughout the European region.
Analyst Perspective
The Europe high-performance adhesive market exhibits signs of maturity, with increasing opportunities driven by innovation and expanded application scope. Long-term, the market is poised for steady growth, supported by ongoing advancements in adhesive formulations, including environmentally friendly options and enhanced bonding strength. Strategic investments should prioritize R&D to capitalize on emerging technologies such as nanomaterial-enhanced adhesives and 3D-printed bonding solutions, which offer significant differentiation in performance. Competition remains intense, with both established players and new entrants vying for market share through technological innovation and geographic expansion. Regional growth potential is particularly strong in automotive, aerospace, and renewable energy sectors, where high-performance adhesives are integral to safety and durability. Investors should focus on regions with robust industrial activities and regulatory support favoring sustainable products. Overall, fostering innovation, building regional partnerships, and maintaining agility in response to evolving customer needs will be essential for sustaining competitive advantage in this mature yet dynamically evolving market.
