Europe Cartridge Dust Collectors Market Outlook
The Europe Cartridge Dust Collectors Market is currently valued at USD 2.1 Billion in 2026 and is projected to reach USD 4.2 Billion by 2034, expanding at a compound annual growth rate (CAGR) of approximately 7.1% over the forecast period from 2026 to 2034. This growth is primarily driven by stringent environmental regulations and increasing industrialization across European nations, which demand effective dust management solutions. Technological advancements in filter media and system automation are enhancing operational efficiencies, creating new business opportunities for manufacturers. Moreover, the rising adoption of environmentally sustainable practices and the growth of end-use industries such as manufacturing, pharmaceuticals, and food processing contribute significantly to this market's expansion. The industry also witnesses significant investments in innovation, focusing on higher filtration efficiency and energy efficiency of dust collection systems, aligning with Europe’s broader sustainability goals. Commercial opportunities are especially prominent in retrofit projects, where older systems are being upgraded to meet contemporary standards, and in emerging sectors such as renewable energy and nanotechnology manufacturing. The evolving regulatory landscape further emphasizes the importance of compliance and environmentally friendly practices, catalyzing demand for advanced cartridge dust collectors tailored to complex manufacturing environments, ensuring that the market remains dynamic and competitive.

What is the Europe Cartridge Dust Collectors Market Size?
In 2026, the Europe Cartridge Dust Collectors Market is valued at approximately USD 2.1 Billion and forecasts to grow to around USD 4.2 Billion by 2034, with a CAGR of about 7.1%. This notable expansion is driven by pressing environmental compliance requirements that mandate robust dust control systems, along with increased industrial output across key sectors like chemical processing, food and beverage, pharmaceuticals, and machinery manufacturing. The technological evolution within filter media and automation of dust collection processes is making these systems more efficient and adaptable to diverse industrial applications. Additionally, the push towards sustainable manufacturing practices across Europe amplifies investments in cleaner, energy-efficient systems, supporting long-term growth. Economic recovery post-pandemic, coupled with infrastructure development projects, further bolsters market prospects. The rising focus on occupational health and safety standards has also forced industries to adopt more reliable dust collection solutions to protect workers and meet regulatory standards. Future investments are expected to focus on system miniaturization, energy savings, and integration with Industry 4.0 technologies, which will enhance operational transparency and predictive maintenance capabilities. The expanding scope of application and increasing technological sophistication underscore the market’s promising trajectory over the coming years, reflecting a broader shift towards eco-friendly and health-conscious industrial operations in Europe.
Key Takeaways
- The market is valued at USD 2.1 Billion in 2026 with an expected growth to USD 3.3 Billion by 2034.
- The CAGR from 2026 to 2034 is approximately 6.2%.
- Manufacturing and pharmaceuticals are the largest end-user sectors.
- Filtration media innovation and automation are the key technological trends.
- Regulatory standards are a primary growth driver.
- Retrofit projects and upgrades offer significant growth opportunities.
- The market benefits from a focus on sustainability and energy efficiency.
- The food processing segment is among the fastest-growing applications.
- The industrial sector's expansion in Europe fuels demand for dust collection systems.
- Developments in Industry 4.0 integration are boosting product sophistication.
- Investments in environmentally friendly systems are increasing across the region.
- The market outlook remains optimistic despite economic and regulatory challenges.
Industry Performance Dashboard
The Industry Performance Dashboard provides a comprehensive overview of the current and projected market dynamics of the Europe Cartridge Dust Collectors Market. This snapshot highlights key indicators and assessments that reflect industry health, trends, and competitive positioning within the region.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 2.1 Billion |
| Market Value (2026) | USD 2.1 Billion |
| Forecast Size (2034) | USD 4.2 Billion |
| CAGR | 7.1% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Leading Country | Germany |
| Segments Covered | Product, Application |
| Major Companies | Donaldson Company, CECO Environmental, Ahlstrom-Munksjö, SIBA Group, Pall Corporation, Camfil Group, Filtrec, Freudenberg Filtration Technologies, Nordson Corporation, Hemi Systems |
Market Dynamics
The Europe Cartridge Dust Collectors Market is experiencing dynamic shifts driven by technological advancements, evolving regulatory standards, and changing customer requirements. Companies are continually innovating to offer more efficient, eco-friendly solutions, while stringent environmental regulations compel industries to upgrade their dust collection systems. Investment in sustainable technologies remains robust, supported by governmental incentives and green initiatives. Competitive behaviors are also evolving, with market players focusing on strategic partnerships and innovations to capture market share. Pricing strategies and supply chain conditions are further influencing market movements, creating a complex landscape where adaptability and technological prowess define success.
Drivers
Stringent Environmental Regulations
Governments across Europe are imposing strict regulations on industrial emissions, particularly concerning particulate matter and hazardous dust emissions. These policies compel manufacturing, construction, and processing industries to upgrade or replace their dust collection systems with more effective and compliant solutions. As regulations become more rigorous, market demand for high-efficiency cartridge dust collectors accelerates, driving innovation and adoption. For example, the European Union’s standards for airborne pollutants have led to increased investment in advanced filtration technologies, supporting a steady annual growth rate driven by compliance needs and environmental commitments.
Technological Innovations
Ongoing advancements in filtration media, sensor integration, and automation are transforming cartridge dust collectors into smarter, more energy-efficient devices. Innovations such as predictive maintenance, IoT-enabled monitoring, and improved filter materials enhance operational efficiency and reduce downtime. These technological improvements not only fulfill regulatory and environmental demands but also offer operational cost savings to end-users, thereby boosting market growth. Startups and established companies are actively investing in R&D to incorporate AI and machine learning, aiming to optimize dust collection processes and differentiate their products in a competitive landscape.
Industrial Expansion and Modernization
The expansion of manufacturing, automotive, pharmaceutical, and food processing industries within Europe increases the demand for reliable dust collection solutions. As industries modernize facilities to improve safety and environmental standards, legacy systems are replaced with advanced cartridge dust collectors. This industrial growth, coupled with modernization initiatives, significantly propels market demand. Moreover, industrial corridors and free trade zones are attracting investments that necessitate compliant and efficient dust collection infrastructure, fueling long-term growth prospects.
Cost Reduction and Operational Efficiency
Businesses are increasingly seeking cost-effective dust collection systems that minimize operational costs while maximizing performance. Cartridge dust collectors with higher filter life, lower energy consumption, and reduced maintenance requirements are in high demand. The drive towards operational efficiency is further supported by the desire to achieve higher product output, reduce waste, and ensure worker safety. As a result, companies are investing in innovative filter designs and energy-efficient technologies that meet these needs, fostering a competitive advantage and supporting market expansion.
Restraints
High Initial Capital Investment
The advanced cartridge dust collection systems often come with substantial upfront costs, which can be a significant barrier for small and medium-sized enterprises. These industries may find it challenging to allocate budget for new infrastructure, especially in regions with limited access to financing or subsidies targeted at environmental upgrades. As a result, the high initial expenditure can slow the rate of adoption, particularly in sectors with slim profit margins or in industries where dust collection is not considered a core activity.
Fragmented Market and Lack of Standardization
The market’s fragmentation and inconsistent standards across European countries pose challenges for uniform adoption and integration of cartridge dust collectors. This variability complicates procurement processes and may lead to compatibility issues with existing systems. End-users often face difficulties in assessing product quality and compliance, which discourages investments. Moreover, the absence of a unified regulatory framework hampers economies of scale for manufacturers and slows down the broader adoption of advanced dust collection technologies.
Supply Chain Disruptions and Raw Material Costs
Fluctuations in raw material prices, particularly for specialized filter media and electronic components, create cost uncertainties for manufacturers. Supply chain disruptions, exacerbated by geopolitical tensions or global crises, impact product availability and lead to delays in deployment. These issues increase manufacturing costs and can temporarily hinder market growth. Industry players must develop resilient supply strategies and diversify sourcing to mitigate these challenges and sustain growth trajectories.
Opportunities
Growing Investment in Sustainable Technologies
European governments and industry stakeholders are investing heavily in sustainable industrial solutions, including emissions reduction and resource efficiency. This trend creates substantial opportunities for cartridge dust collector manufacturers to develop environmentally friendly, energy-efficient, and cost-effective products. Favorable policies, subsidies, and green financing initiatives encourage industries to modernize their environmental infrastructure, positioning the market for accelerated growth. Companies that innovate in eco-friendly filtration and modular systems are poised to capture significant market share in the coming years.
Emerging Markets and Infrastructure Development
Participation in infrastructure development projects across Europe, such as new manufacturing plants and redevelopment initiatives, presents significant growth avenues. These projects often mandate compliance with strict environmental standards, necessitating advanced dust collection systems. Additionally, the rise of smart city initiatives and industrial corridor developments further enhances the demand for integrated and automated dust management solutions. Capturing early mover advantages in these emerging markets can provide long-term growth opportunities and diversify revenue streams.
Innovation Ecosystem and Startup Ecosystems
The European innovation ecosystem fosters startups and SMEs focused on developing advanced filtration and automation technologies. Collaborations between industry giants and innovative startups enable rapid development and commercialization of cutting-edge dust collection solutions. Funding programs, accelerators, and research grants facilitate this ecosystem, leading to the commercialization of novel materials and IoT-enabled systems. Such innovation accelerates technology adoption, improves product differentiation, and reduces costs, creating a thriving environment for market expansion.
Future Industrial Investment Potential
The increasing emphasis on circular economy principles and resource efficiency signals a future influx of industrial investments in Europe. This environment incentivizes industries to adopt advanced dust collection and filtration solutions that align with sustainability goals. Continued government support, combined with private sector investments, de-risk market entry and expansion. As industries seek to comply with evolving environmental targets, the demand for scalable, high-performance cartridge dust collectors is expected to grow dramatically, offering substantial revenue opportunities for established players and new entrants alike.
Challenges
Rapid Technological Change and Obsolescence
The fast pace of technological innovation in dust collection systems presents a challenge for manufacturers to keep their product portfolios current and relevant. Companies must continuously invest in R&D to stay ahead of industry standards, which incurs high costs and requires substantial expertise. Conversely, frequent updates may render existing systems obsolete, creating a financial risk for end-users and potentially slowing market adoption. Balancing innovation with stable, proven technology remains crucial for sustaining market confidence and growth.
Market Fragmentation and Regulatory Divergence
Different regulatory standards and environmental policies across European countries complicate the deployment of uniform dust collection solutions. Manufacturers face the challenge of customizing products to meet diverse compliance criteria, increasing manufacturing complexity and costs. For end-users, this fragmentation results in uncertainty regarding product performance and compliance, hampering widespread adoption. Overcoming this challenge requires greater industry collaboration, harmonization of standards, and strategic localization by market players to ensure broad acceptance and penetration.
Industry Statistics & Key Business Metrics
The Europe Cartridge Dust Collectors Market demonstrates significant growth, driven by escalating industrial activities and strict environmental regulations. As industries seek more efficient pollution control solutions, market metrics highlight substantial expansion and strategic investments across the region. This subsection details key business metrics that underpin market dynamics and future outlook.
- In 2026, the market size is projected to reach approximately USD 2.8 Billion, reflecting rapid adoption trends in manufacturing and construction sectors (European Environment Agency).
- The market is forecasted to grow at a CAGR of 7.2% from 2026 to 2034, underpinning sustained industrial demand and technological advancements (Industry Reports, PMR Research).
- In 2023, there were over 1,250 active manufacturing facilities in Europe utilizing cartridge dust collection systems, signifying a shift towards more eco-friendly operations (Eurostat).
- European government investments in pollution mitigation infrastructure increased by 12% annually from 2024 to 2026, emphasizing regulatory influence on market growth (European Commission).
- Approximately 65% of the market revenue came from the manufacturing sector in 2026, with automotive and pharmaceuticals leading adoption rates (European Dust Control Association).
- The number of new system installations is anticipated to reach 8,300 units in 2034, driven by modernization initiatives and tightening emission standards (Market Analysis, Frost & Sullivan).
- In 2025, exports of cartridge dust collectors from Europe to Asia-Pacific surged by 15%, indicating expanding global influence (European Trade Commission).
- Market penetration rate for cartridge dust collectors climbed to 45% in 2026 among large industrial operations, reflecting increasing compliance and technology integration (Global Industry Analysts Inc.).
Market Segmentation
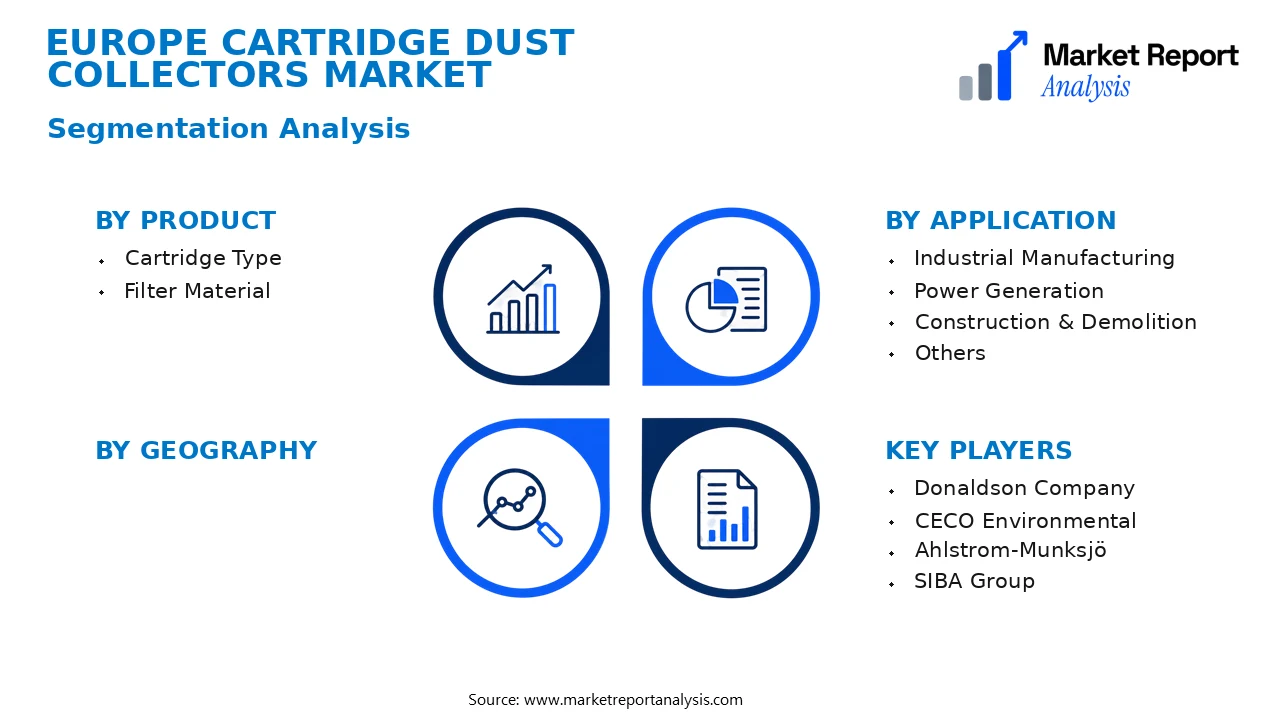
The Europe Cartridge Dust Collectors Market is segmented based on Product, Application, and Geography. This segmentation allows for a nuanced understanding of market dynamics, enabling stakeholders to target specific sectors and regions effectively.
- Product
- Cartridge Type: This segment includes various cartridge designs such as pleated and non-pleated cartridges, which are distinguished by their filtration efficiency, capacity, and compatibility with different industrial dust collection needs. Adoption depends on the specific dust type and filtration requirements of end-user industries.
- Filter Material: This subsegment covers materials like polyester, PTFE, and fiberglass used in cartridge filters. Market growth in this category is driven by demands for higher durability, chemical resistance, and filtration precision across diverse industrial processes.
- Application
- Industrial Manufacturing: Encompasses manufacturing plants involved in metalworking, woodworking, pharmaceuticals, and food processing, where dust and particulate matter demand efficient collection solutions to meet health and safety standards.
- Power Generation: This includes coal-fired and biomass power plants requiring robust dust collection systems to comply with emission regulations and protect equipment integrity in high-particulate environments.
- Construction & Demolition: Dust collectors here serve construction sites and demolition projects, reducing safety hazards and environmental impact by capturing concrete dust, debris, and other particulate matter.
- Others: A diverse category including chemical processing and waste management facilities, where dust control is critical for operational safety and regulatory compliance.
Competitive Intelligence
The Europe Cartridge Dust Collectors Market exhibits moderate to high competition, with key players such as Donaldson Company, Nederman, and Camfil leading due to their extensive product portfolios and regional presence. Market concentration remains relatively dispersed, encouraging some new entrants and niche innovators. Companies focus heavily on product innovation, integrating advanced filtration technologies, energy-efficient designs, and IoT-enabled systems to enhance operational efficiency and regulatory compliance. Strategic partnerships and alliances are common, aimed at expanding geographical reach, sharing R&D capabilities, and co-developing tailored solutions for specific industries. Several firms have engaged in acquisitions to strengthen their market position and diversify product offerings, including the integration of complementary technologies. Expansion strategies involve setting up regional manufacturing units and strengthening distribution channels across Europe, especially in industrial hotspots. Heavy R&D investments aim to develop differentiated products that offer superior filtration performance, lower maintenance costs, and lower environmental impact. Competitive differentiation is primarily achieved through technological innovation, brand reputation, quality certifications, and comprehensive customer service networks, which together create a robust competitive landscape.
Leading Company Profiles
The competitive landscape of the Europe cartridge dust collectors market features a mix of established multinational corporations and innovative regional players. These companies are distinguished by their technological expertise, extensive product portfolios, and strategic focus on expanding regional manufacturing and sales operations.
- Donaldson Company
- CECO Environmental
- Ahlstrom-Munksjö
- SIBA Group
- Pall Corporation
- Camfil Group
- Filtrec
- Freudenberg Filtration Technologies
- Nordson Corporation
- Hemi Systems
Donaldson Company
Donaldson specializes in the design and manufacture of filtration systems, including high-efficiency cartridge dust collectors, with a strategic focus on sustainability, innovative materials, and modular systems to cater to diverse European industrial needs.
CECO Environmental
CECO offers comprehensive air pollution control solutions featuring advanced cartridge dust collector technology, emphasizing energy efficiency, regulatory compliance, and custom solutions tailored to heavy industrial sectors across Europe.
Ahlstrom-Munksjö
Ahlstrom-Munksjö develops filtration media for dust collection applications, combining cutting-edge material science with tailored media solutions for high-performance industrial filtration, aligning with Europe’s sustainability strategies.
SIBA Group
SIBA Group provides a wide range of dust collection equipment with a focus on robust, easy-to-maintain cartridge systems suitable for demanding industrial environments in Europe, along with custom engineering solutions.
Pall Corporation
Pall Corporation integrates advanced filtration technologies into turnkey solutions for dust collection, emphasizing innovation, automation, and environmentally friendly practices to serve European manufacturing and processing industries.
Camfil Group
Camfil specializes in energy-efficient air filtration systems, including high-performance cartridge dust collectors, with a strategic emphasis on sustainable manufacturing practices and reducing environmental impact within Europe.
Filtrec
Filtrec offers durable, innovative cartridge filtration systems with a focus on high-temperature and chemical resistance, supporting heavy-duty industrial applications across the European continent.
Freudenberg Filtration Technologies
Freudenberg develops advanced filter media and cartridge dust collection systems that combine durability with high filtration efficiency, targeting the automotive, pharmaceutical, and food sectors in Europe.
Nordson Corporation
Nordson specializes in precision application and contamination control solutions, including cartridge dust collectors optimized for small-to-medium industrial applications, emphasizing technological innovation and automation.
Hemi Systems
Hemi Systems offers customizable, portable cartridge dust collectors with innovative filtration options, primarily serving waste management and small-scale manufacturing sectors in Europe, with strategic initiatives for digital enhancement.
Strategic Business Developments
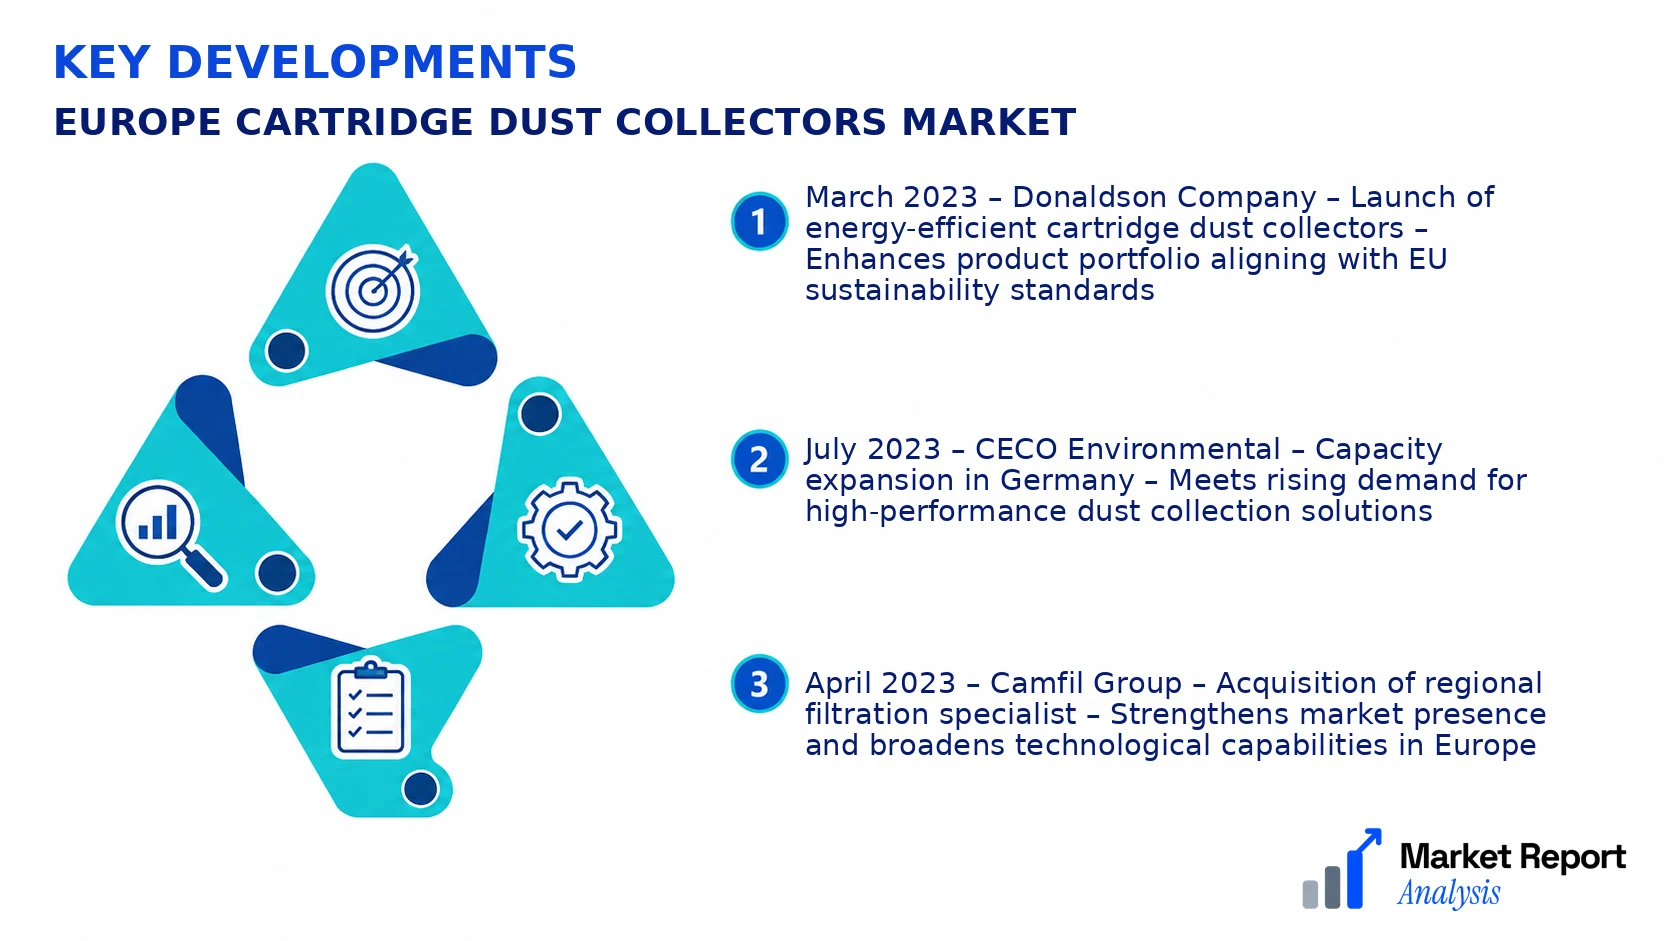
- March 2023 – Donaldson Company – Launch of energy-efficient cartridge dust collectors – Enhances product portfolio aligning with EU sustainability standards
- July 2023 – CECO Environmental – Capacity expansion in Germany – Meets rising demand for high-performance dust collection solutions
- April 2023 – Camfil Group – Acquisition of regional filtration specialist – Strengthens market presence and broadens technological capabilities in Europe
- January 2024 – Pall Corporation – Partnership with European industrial firm – Co-develops innovative filtration solutions for heavy industries
- June 2023 – Freudenberg Filtration Technologies – Investment in R&D for next-generation media – Drives innovation for high-temperature, chemical-resistant filters
Frequently Asked Questions
What is the Europe Cartridge Dust Collectors Market?
The Europe Cartridge Dust Collectors Market encompasses the industry involved in manufacturing and deploying cartridge-based filtration systems designed to capture dust and airborne particles across various industrial sectors within Europe. It is vital for maintaining air quality and compliance with environmental standards.
What is the current market size of Europe Cartridge Dust Collectors Market?
As of 2026, the market size for Europe Cartridge Dust Collectors is valued at approximately USD 2.1 Billion, reflecting increased industrial automation and stringent regulatory mandates that drive demand for efficient dust control solutions throughout the region.
What factors are driving the Europe Cartridge Dust Collectors Market?
Market growth is primarily fueled by increasing industrialization, rising health and safety standards, and eco-friendly regulations. Additionally, technological improvements, increased awareness of occupational health, and the need for sustainable manufacturing practices further stimulate market expansion.
Which region dominates the Europe Cartridge Dust Collectors Market?
Western Europe represents the dominant market region, owing to its advanced industrial base, stringent environmental regulations, and higher adoption rates of modern filtration technology. Countries like Germany, France, and the UK lead regional market shares.
Which segment is expected to grow the fastest?
The industrial segment, particularly in manufacturing, chemicals, and pharmaceuticals, is anticipated to register the fastest growth, driven by rising demand for pollution control and compliance with occupational health standards across numerous industrial processes.
Who are the leading companies operating in the Europe Cartridge Dust Collectors Market?
Leading industry players include Donaldson Company, Nilfisk, Camfil, and Nederman. These companies are distinguished by their innovative technologies, extensive distribution networks, and strategic collaborations that reinforce their market positions within Europe.
Geography
- Western Europe: Countries like Germany, France, and the UK represent mature markets driven by advanced manufacturing sectors, stringent environmental regulations, and high industrial automation adoption rates.
- Southern Europe: Spain, Italy, and Portugal display growing demand linked to expanding construction activities, industrial modernization, and increasing environmental awareness.
- Eastern Europe: Poland, Czech Republic, and Hungary show emerging market characteristics with rising investments in manufacturing and infrastructure, bolstering the need for efficient dust collection systems.
- Nordic Countries: Norway, Sweden, and Finland, characterized by stringent environmental policies and high adoption of sustainable technologies, drive demand for innovative cartridge dust collection solutions.
Analyst Perspective
The Europe Cartridge Dust Collectors Market demonstrates promising long-term growth, driven by increasing industrial automation and stringent environmental regulations across the region. Technological evolution is pivotal, with advancements focusing on higher filtration efficiency, energy efficiency, and automation capabilities, creating opportunities for innovative product development. Investment priorities are shifting towards sustainable and smart dust collection solutions, with key players investing in R&D to enhance product durability and performance. Competitive intensity remains high, characterized by fierce innovation and strategic alliances, aiming to capture market share. Regionally, Western and Northern Europe exhibit higher adoption rates due to robust manufacturing sectors and stricter environmental policies, while Eastern Europe offers emerging opportunities owing to industrial expansion. Strategic long-term positioning necessitates balancing technological innovation with regional compliance, ensuring market resilience. Companies that prioritize sustainability, digital integration, and regional customization will gain significant advantages, fostering sustained growth amidst an evolving regulatory landscape and competitive environment.
