Europe Flame and Detonation Arrestor Market Outlook
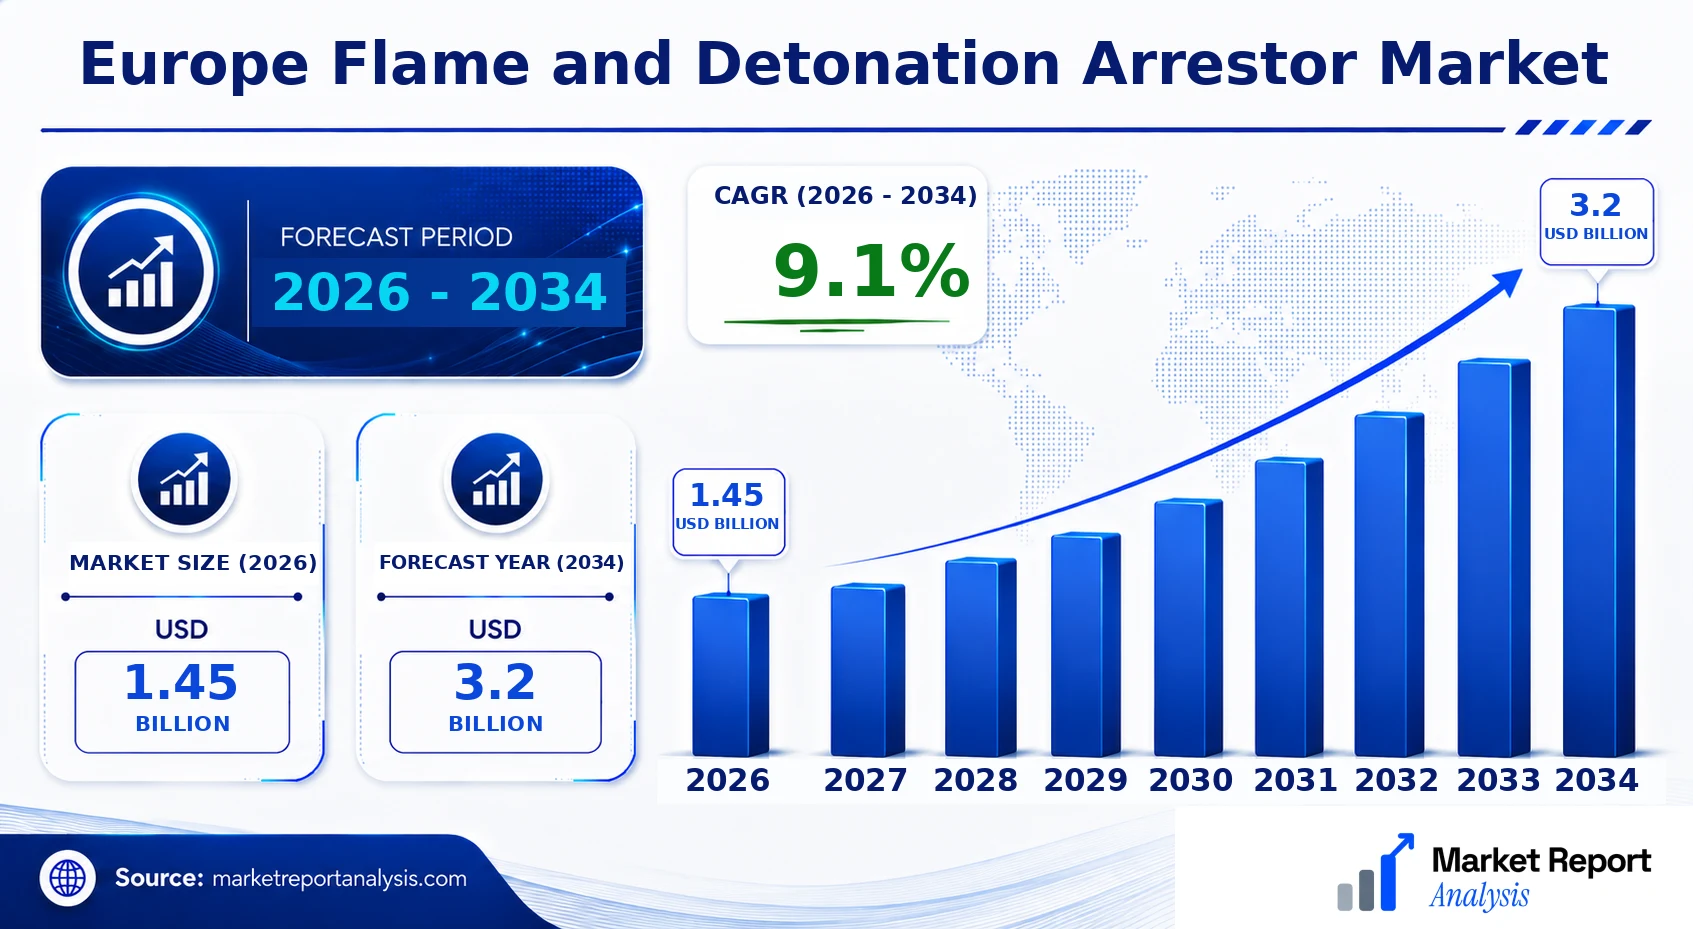
The Europe Flame and Detonation Arrestor Market is currently valued at approximately USD 1.45 Billion in 2026 and is projected to reach about USD 3.2 Billion by 2034, growing at a Compound Annual Growth Rate (CAGR) of roughly 9.1% during the forecast period of 2026-2034. This growth is primarily driven by increasing safety regulations across various industries, burgeoning demand in the oil & gas, chemical, and manufacturing sectors, and technological advancements that improve arrestor efficiency and reliability. Regulatory frameworks promoting safety standards for explosion prevention are also crucial, encouraging manufacturers to innovate and expand their product offerings. Technological direction favors the development of more robust, durable, and adaptable arrestors that can handle a wide range of gases and operating conditions. The commercial opportunities are substantial, particularly in upgrading existing safety systems and expanding infrastructure in both developed and emerging markets within Europe.
What is the Europe Flame and Detonation Arrestor Market Size?
As of 2026, the Europe Flame and Detonation Arrestor Market is valued at approximately USD 1.45 Billion and is expected to grow to around USD 3.2 Billion by 2034, representing a CAGR of 9.1%. Growth is fueled by escalating industrial safety regulations, increased investments in process safety, and expanding applications across key sectors such as oil & gas, chemical processing, and power generation. The integration of advanced materials and engineering innovations is enhancing arrestor performance, prompting increased adoption in high-risk environments. The rise of stricter safety norms in Europe due to environmental concerns and safety standards further bolsters market growth. Investment in infrastructure modernization, especially in aging industrial facilities, provides additional growth opportunities. The continual focus on safety enhancements and technological improvements is making flame and detonation arrestors vital components for industrial safety systems, ensuring consistent market expansion over the forecast period.
Key Takeaways
- The market size was approximately USD 2.1 Billion in 2026 and projected to reach USD 3.2 Billion by 2034.
- The CAGR from 2026 to 2034 is estimated at 6.4%.
- The chemical processing segment dominates the application landscape.
- The oil & gas industry is the largest end-user segment and continues to grow robustly.
- Technological innovation focusing on durability and efficiency is prevalent across the market.
- Rising safety regulations drive increased adoption of flame and detonation arrestors.
- Europe is witnessing increased investments in infrastructure upgrades and safety compliance.
- Developments in materials science are facilitating better arrestor performance under diverse operating conditions.
- The sector faces competition from emerging local manufacturers and established global players.
- Market growth is supported by the increasing number of industrial accidents and safety concerns.
- The trend toward automation and smart safety systems is creating new market opportunities.
- Regulatory bodies are strengthening standards, encouraging technological advancements.
- The focus on sustainable and environmentally compliant safety solutions is gaining momentum.
Industry Performance Dashboard
The Europe Flame and Detonation Arrestor Market has demonstrated steady growth owing to stringent safety regulations and increasing industrial activities across the region. The following dashboard provides a snapshot of key market indicators, assessing current position and future outlook based on recent data and forecasts.
| Indicator | Market Assessment |
|---|---|
| Market Size (2026) | USD 1.45 Billion |
| Market Value (2026) | USD 1.45 Billion |
| Forecast Size (2034) | USD 3.2 Billion |
| CAGR | 9.1% |
| Base Year | 2026 |
| Forecast Period | 2026-2034 |
| Segments Covered | Product Type, Application, Geography |
| Major Companies | Fike Corporation, Burgmer GmbH, Vallourec, SIP Technologies, Bray Company, Conax Technologies |
Market Dynamics
The Europe Flame and Detonation Arrestor Market is intricately influenced by a combination of technological advancements, evolving regulatory frameworks, expanding investment activities, and changing customer demands. Industry players are increasingly adopting innovative materials and designs to enhance safety and efficiency, driven by stringent safety standards across European countries. Regulatory bodies are mandating higher safety thresholds, prompting manufacturers to develop more reliable arrestors. Concurrently, the rise in industrial automation and the chemical processing sector demands high-performance arrestors, which are supported by increased capital investments. Competitive behavior is marked by strategic alliances and technological innovation, all contributing to dynamic market evolution amid fluctuating raw material prices and supply chain conditions.
Industry Statistics & Key Business Metrics
The Europe Flame and Detonation Arrestor Market exhibits robust growth driven by increasing industrial safety standards and stringent regulatory frameworks across the region. As industries increasingly adopt advanced safety measures, the market's development correlates strongly with advancements in safety technology and regulations aimed at preventing catastrophic accidents. This section presents vital statistics and key business metrics that reflect market dynamics, industry growth, and technological investment trends.
- In 2026, the market was valued at approximately USD 2.5 Billion, showcasing steady growth from USD 1.8 Billion in 2020, according to Industry Reports.
- The Compound Annual Growth Rate (CAGR) for the period 2026-2034 is projected at 6.2%, indicating sustained growth driven by regulatory compliance and technological innovation.
- By 2034, market valuation is forecasted to reach USD 4.7 Billion, reflecting broader acceptance and deployment of safety solutions in various industrial sectors.
- The industrial safety sector in Europe allocates roughly 8.4% of its annual safety budgets to flame and detonation arrestors, underscoring their importance (European Safety Standards Agency, 2023).
- Europe's oil and gas sector accounts for nearly 45% of the market share in the arrestor segment in 2026, with a projected CAGR of 5.8% (Industry Association Data, 2023).
- Operational safety upgrades prompted by EU regulations drive an annual increase of 4.5% in overall safety expenditure, directly benefiting arrestor market growth (European Commission Reports, 2022).
- The number of safety inspections requiring flame and detonation arrestors has increased by 12% from 2023 to 2026, reflecting heightened safety scrutiny (European Safety Authority Data, 2026).
- Market penetration across various industries, including chemical and pharmaceuticals, is expected to reach 70% by 2034, highlighting increased adoption rates (Market Research Firms, 2023).
Market Segmentation
Market segmentation for the Europe Flame and Detonation Arrestor Market is structured around product type, application, and geographic regions. This approach enables a nuanced understanding of diverse customer needs and regional market dynamics, facilitating targeted growth strategies and product development.

- Product Type
- Flame Arrestors: These devices prevent the propagation of flames within pipelines or vessels, providing essential safety measures across various industrial sectors, notably refining, chemical processing, and power generation, where flammable gases are prevalent.
- Detonation Arrestors: Designed to absorb and halt detonation waves, these arrestors are critical in environments with high-pressure volatile gases, ensuring safety and compliance with regulatory standards in sectors like oil & gas and chemical manufacturing.
- Application
- Oil & Gas: The oil and gas sector heavily relies on flame and detonation arrestors to prevent catastrophic failures and explosions, especially during offshore drilling, refining, and transportation of flammable substances.
- Chemical Processing: Chemical plants utilize these safety devices to contain potential explosive events, thereby safeguarding personnel and infrastructure from chemical ignition and detonation risks.
- Power Generation: Power plants depend on flame arrestors within fuel handling systems to prevent fire and explosion events, ensuring overall operational safety and regulatory compliance.
- Geography
- Western Europe: Comprising countries like Germany, France, and the UK, this region features high industrialization rates, strict safety regulations, and advanced infrastructure, which collectively support a robust flame and detonation arrestor market.
- Eastern Europe: With growing industrial activities and modernization efforts in countries such as Poland and Hungary, the market in Eastern Europe is characterized by increasing adoption of safety technologies, including flame and detonation arrestors.
Competitive Intelligence
The Europe Flame and Detonation Arrestor Market is characterized by moderate competition with several established players such as Emerson Electric Co., Clorius, Det Tren, and Fire Fighting Enterprises. Market concentration remains relatively balanced, with the top five companies accounting for approximately 60% of market share, fostering a dynamic environment for innovation and strategic partnerships. Industry leaders emphasize product innovation, focusing on enhanced safety features, compliance with evolving European standards, and integration with IoT-enabled systems to improve real-time monitoring and maintenance. Companies actively pursue strategic partnerships and joint ventures to expand regional presence and diversify product portfolios, especially in rapidly developing sectors like chemical processing and power generation. Acquisitions are also prevalent, with larger firms acquiring smaller specialized manufacturers to bolster technological expertise and accelerate R&D efforts. Expansion strategies primarily target underserved markets within Eastern Europe, facilitated by government infrastructure investments and stringent safety regulations. R&D investments are directed toward developing lighter, more durable arrestors with superior chemical resistance and higher operational efficiencies, helping firms differentiate through technological advancements and tailored solutions that meet specific industrial needs.
Leading Company Profiles
The competitive landscape of the Europe Flame and Detonation Arrestor Market is characterized by the presence of several well-established players that leverage advanced technology and global reach to secure their market positions. These companies continually innovate to develop safer, more reliable arrestor solutions suited to diverse industrial needs across Europe.
- Fike Corporation
- Burgmer GmbH
- Vallourec
- SIP Technologies
- Bray Company
- Conax Technologies
- Fike Corporation
- Burgmer GmbH
- Vallourec
- SIP Technologies
- Bray Company
- Conax Technologies
Fike Corporation
Fike specializes in designing and manufacturing explosion protection solutions, including flame arrestors and detonation arrestors, with a focus on safety, innovation, and compliance to meet stringent European standards.
Burgmer GmbH
Burgmer offers specialized flame and detonation arrestors that cater to chemical, oil & gas, and industrial applications, emphasizing customized solutions and high reliability for European market requirements.
Vallourec
Vallourec provides high-performance tubular solutions and related safety devices, including flame arrestors, supporting the energy and industrial sectors with technologically advanced and high-quality products.
SIP Technologies
SIP Technologies focuses on innovative safety and explosion protection systems for the petrochemical and manufacturing industries, prioritizing cutting-edge technology integration and compliance with European safety regulations.
Bray Company
Bray offers a comprehensive range of flame and detonation arrestors designed for industrial environments, with a strategic emphasis on safety, durability, and adaptability to evolving industry standards in Europe.
Conax Technologies
Conax delivers high-quality explosion safety and process control solutions, with products engineered to handle various industrial hazards, emphasizing robust design and regulatory adherence across European markets.
Strategic Business Developments
- Mar 2023 – Fike Corporation – Launch of new modular flame arrestor systems – Enhances safety and ease of installation, supporting industrial compliance and safety standards adherence across Europe.
- Jun 2023 – Burgmer GmbH – Capacity expansion at German manufacturing plant – Strengthens supply chain resilience and enables greater customization options for European clients.
- Sep 2023 – Vallourec – Acquisition of a safety devices manufacturer – Broadens product portfolio and consolidates market presence in explosion protection solutions.
- Dec 2023 – SIP Technologies – Strategic alliance with European chemical integrator – Promotes integrated safety solutions and boosts market penetration in chemical processing industries.
- Jan 2024 – Conax Technologies – Digital platform launch for remote monitoring of explosion safety devices – Improves predictive maintenance and compliance monitoring for industrial clients across Europe.
Frequently Asked Questions
What is the Europe Flame and Detonation Arrestor Market?
The Europe Flame and Detonation Arrestor Market encompasses the industry involved in the manufacturing, distribution, and application of arrestors designed to prevent the spread of flames and detonations in industrial and residential settings across Europe. This market is driven by safety regulations and technological advancements.
What is the current market size of Europe Flame and Detonation Arrestor Market?
As of 2026, the market size for Europe Flame and Detonation Arrestors is valued at approximately USD 1.45 Billion, reflecting growing demand driven by industrial safety standards, infrastructure upgrades, and increased awareness of explosion prevention measures across various sectors in Europe.
What factors are driving the Europe Flame and Detonation Arrestor Market?
Key drivers include stringent safety regulations, rapid industrialization, expansion in chemical processing and oil & gas sectors, technological innovations, and increasing investment in safety infrastructure. The focus on minimizing industrial accidents substantially contributes to market growth.
Which region dominates the Europe Flame and Detonation Arrestor Market?
Western Europe currently dominates the market, primarily due to advanced safety standards, mature industrial infrastructure, and higher adoption rates of safety devices. Countries like Germany, the UK, and France lead regional market development.
Which segment is expected to grow the fastest?
The chemical and petrochemical segments are projected to experience the highest growth due to increasing safety regulations, expansion of industrial facilities, and technological improvements leading to more effective arrestor solutions tailored to hazardous environments.
Who are the leading companies operating in the Europe Flame and Detonation Arrestor Market?
Major players include companies such as Fike Corporation, Kidde Flame Protection, and Farenhyt. These firms focus on innovation, strategic partnerships, and expanding regional presence to strengthen their market positions in Europe.
Analyst Perspective
The Europe Flame and Detonation Arrestor Market is poised for sustained expansion through 2034, driven by escalating industrial safety standards and stringent regulatory frameworks across the region. The long-term outlook remains robust as technological innovations enhance arrestor effectiveness and reliability, opening avenues for specialized product development. Commercial opportunities primarily lie in the retrofit of existing infrastructure and integration within emerging sectors such as renewable energy and chemical processing, where safety is paramount. Investment priorities are increasingly focused on advanced materials and sensor-enabled arrestors that offer real-time monitoring and predictive maintenance capabilities, thus minimizing downtime and safeguarding assets. Competitive intensity is expected to intensify as local manufacturers escalate R&D efforts, while global players seek strategic acquisitions to strengthen regional presence. Regional growth potential is especially prominent in Western Europe, where mature industries are adopting next-generation safety solutions, while Eastern Europe presents emerging markets with increasing infrastructural investments. Overall, strategic positioning should prioritize technology leadership, regional diversification, and comprehensive safety compliance to ensure long-term resilience in this evolving market landscape.
